
 Thermo Hygrometer Market | 2026-2036
Thermo Hygrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermo Hygrometer Market Analysis
The capital-intensity divergence between precision sensor foundries and assembly-only competitors is redrawing competitive boundaries in thermo hygrometer supply. Honeywell International Inc. leverages captive semiconductor fabrication to control capacitive sensing element costs across HVAC and pharmaceutical verticals. Vaisala Corporation anchors its position through meteorological-grade calibration protocols that sustain premium pricing in research institutions. Testo SE & Co. KGaA competes via handheld portability dominance, occupying the European industrial maintenance channel with localized service networks.
A thermo hygrometer measures simultaneous temperature and relative humidity through integrated thermal and moisture-responsive transducers, typically achieving accuracy thresholds of ±0.1°C and ±0.8% RH in laboratory-grade configurations. The device serves critical environmental validation roles where thermal-humidity coupling affects process yield, material stability, or occupant health outcomes. Digital product types lead volume shipments while wireless variants represent the fastest-expanding margin pool, driven by IoT-enabled predictive maintenance architectures in commercial buildings. Capacitive technology dominates current manufacturing throughput, though infrared thermopile hybrids are gaining traction in non-contact agricultural canopy monitoring where physical probe insertion risks crop damage.
EMA calibration traceability requirements and FDA 21 CFR Part 11 electronic record mandates shape product development priorities for pharmaceutical and food safety end users. EPA indoor air quality guidelines and OSHA thermal stress thresholds further expand addressable demand in commercial and industrial workplace compliance. Stakeholders must monitor evolving CE marking harmonization under the EU Measuring Instruments Directive and assess sensor miniaturization trajectories that could displace standalone instruments with embedded subsystem modules.
Market Dynamics
Wireless IoT sensor architectures are compressing replacement cycles for wired thermo hygrometer installations across pharmaceutical and food cold chain infrastructure, forcing incumbents to reconfigure service revenue models around predictive analytics rather than hardware replacement.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Electronic record-keeping requirements in US pharmaceutical manufacturing drive validated wireless sensor deployments for continuous environmental monitoring.
- EMA Good Manufacturing Practice updates:German and French laboratories expand calibrated instrument fleets to meet traceability protocols for temperature-sensitive biologics storage.
- Capacitive MEMS miniaturization:Semiconductor foundry advances reduce sensing element costs, enabling price-competitive penetration into agricultural canopy monitoring applications.
Market Restraints
- Premium calibration service concentration:Meteorological-grade calibration capacity clusters in Finland and Switzerland, creating bottlenecks for research institution procurement timelines.
- Raw material input volatility:Rare earth elements in thermopile infrared detectors face supply uncertainty from concentrated mining operations.
- Technical accuracy ceiling:±0.1°C precision thresholds in laboratory-grade configurations approach theoretical limits of capacitive sensing physics, constraining further differentiation.
Strategic Opportunities
- Underpenetrated Indian cold chain:FSSAI food safety modernization and CDSCO pharmaceutical storage rules create first-mover advantage for calibrated wireless sensor networks.
- EU F-Gas Regulation phase-down:Refrigeration system monitoring requirements expand addressable demand for leak-detection-integrated thermo hygrometer modules.
- Edge AI convergence:On-device anomaly detection algorithms embedded in sensor firmware enable predictive maintenance contracts displacing traditional break-fix service models.
Industry Challenges
- Metrology technician scarcity:Certified calibration engineer pipelines fail to match EMA and FDA audit frequency requirements, extending instrument downtime.
- Multi-protocol integration friction:Legacy BACnet and Modbus building management systems resist seamless wireless sensor onboarding, complicating retrofit sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermo Hygrometer Market |
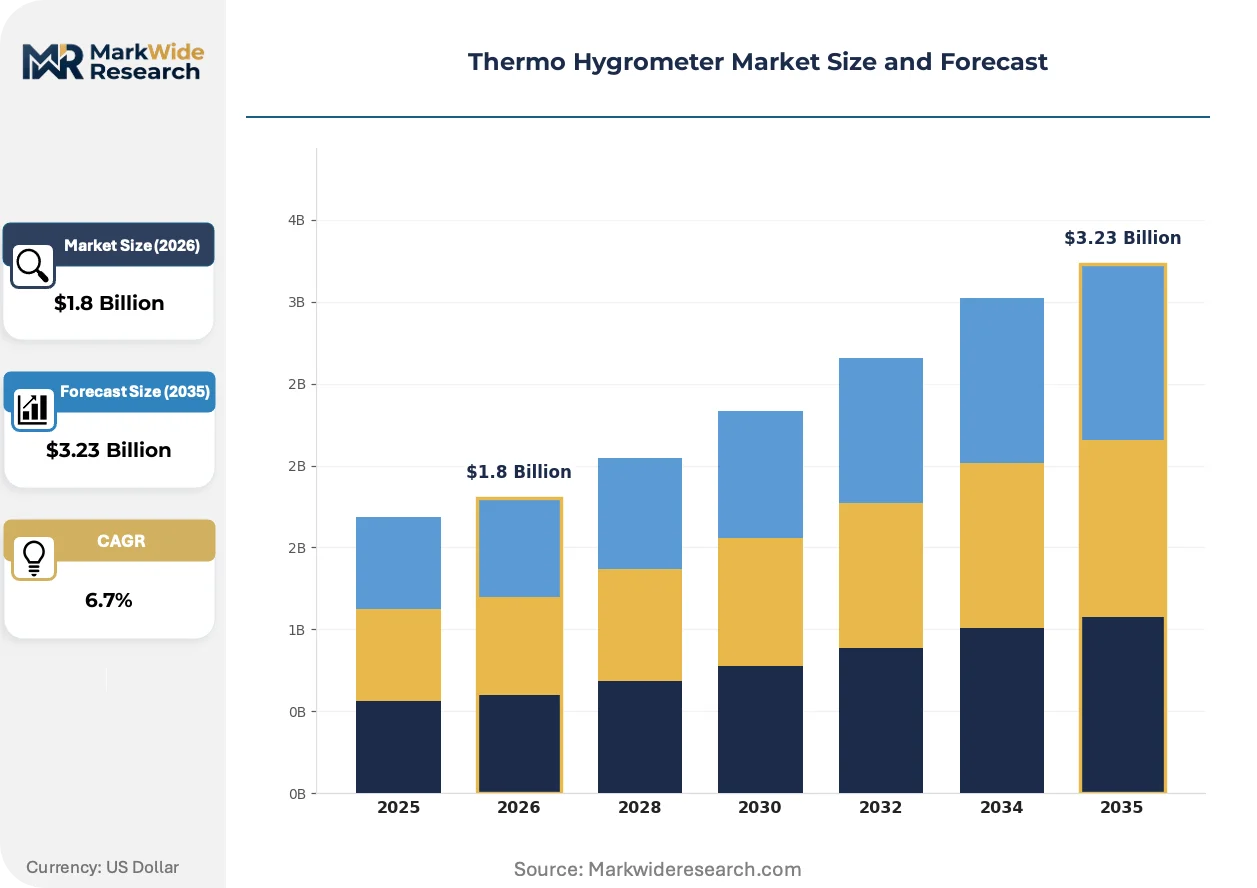
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Wireless, Portable Technology: Capacitive, Resistive, Thermoelectric, Infrared Application: HVAC, Agriculture, Laboratories, Greenhouses End User: Residential, Commercial, Industrial, Research Institutions |
| Companies Covered | Honeywell International Inc., Extech Instruments, Testo SE & Co. KGaA, Dwyer Instruments, Inc., PCE Instruments, Fluke Corporation, Omega Engineering Inc., Rotronic AG, Vaisala Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermo Hygrometer Market Emerging Trajectories
Sensor fusion architectures and predictive maintenance business models are redrawing value capture boundaries in environmental monitoring equipment, compressing hardware margins while expanding recurring software revenue pools.
Infrared thermopile hybrids are bifurcating the agricultural monitoring segment from contact-based probe systems. Grape and orchard operators in California and Bordeaux adopt non-contact canopy temperature mapping to optimize irrigation scheduling. This technology is bifurcating procurement patterns: precision agriculture buyers now prioritize spatial coverage over point-accuracy specifications.
REACH substance restrictions and RoHS compliance deadlines are accelerating material substitutions in sensing element manufacturing. European manufacturers reformulate capacitive polymer formulations to eliminate restricted phthalates without degrading humidity response curves. Laboratory-grade instrument suppliers face compressed certification timelines as notified bodies process updated technical documentation.
Subscription-based calibration-as-a-service contracts displace traditional instrument ownership models in multi-site pharmaceutical operations. Pfizer and Sanofi procurement teams in New Jersey and Frankfurt now prioritize vendors offering cloud-managed calibration scheduling over capital purchase agreements. This shift concentrates vendor selection criteria on software integration depth rather than standalone hardware specifications.
Thermo Hygrometer Market Segmentation
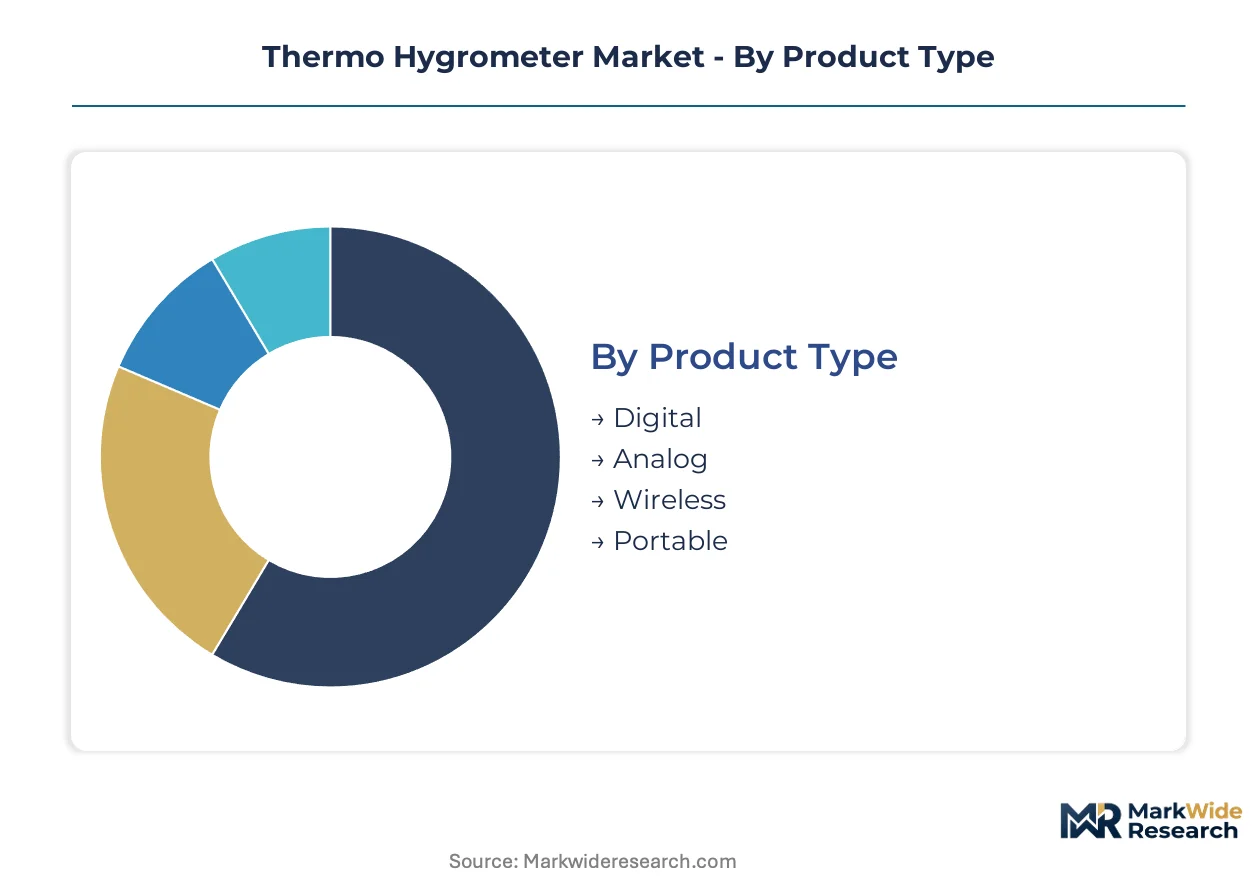
Thermo hygrometer segmentation reveals divergent compliance burdens and margin structures across precision tiers. Product type and technology choices determine whether vendors serve regulated pharmaceutical workflows or price-sensitive agricultural monitoring.
Product Type:
FDA 21 CFR Part 11 electronic record mandates and EMA Good Manufacturing Practice traceability requirements create sharp performance thresholds between validated and non-validated instrument categories.
- Digital:Solid-state sensors with integrated microprocessors deliver ±0.1°C and ±0.8% RH accuracy thresholds required for laboratory-grade configurations. Pharmaceutical laboratories in Germany and France expand calibrated digital fleets under EMA biologics storage protocols.
- Wireless:Battery-powered IoT architectures with cloud telemetry enable continuous cold chain monitoring without wired infrastructure. FDA-regulated facilities in the United States concentrate demand for predictive maintenance-enabled sensor networks.
- Analog:Dial-display instruments with bimetallic temperature elements and hair hygrometer humidity sensors serve basic HVAC commissioning. Residential and light commercial installers in India prioritize analog units for first-cost sensitivity.
- Portable:Handheld battery-operated units with rapid-response probes dominate European industrial maintenance channels. Localized service networks in Germany support calibration turnaround requirements for field technicians.
Digital instruments handle the majority of throughput; Wireless is gaining share fastest on IoT predictive maintenance architectures.
Technology:
Cost tiers separate precision sensor foundries from assembly-only competitors, with semiconductor fabrication scale determining capacitive element economics.
- Capacitive:Polymer dielectric sensors measure humidity through capacitance changes, achieving fastest response times in HVAC and laboratory applications. MEMS miniaturization at semiconductor foundries reduces per-element costs for agricultural canopy monitoring penetration.
- Infrared:Thermopile detectors enable non-contact temperature measurement without physical probe insertion. California and Bordeaux grape operators adopt infrared thermopile hybrids for irrigation scheduling optimization.
- Resistive:Conductive polymer films change electrical resistance with humidity absorption, offering lower cost alternatives for greenhouse monitoring. Southeast Asian horticulture operations specify resistive units for humidity trend tracking without calibration-intensive precision.
- Thermoelectric:Peltier-cooled dewpoint sensors achieve highest accuracy for meteorological and research-grade applications. Finnish and Swiss calibration laboratories concentrate thermoelectric instrument certification capacity.
Capacitive technology commands the dominant manufacturing volume; Infrared hybrids are expanding most quickly in precision agriculture.
Application:
End-use concentration patterns reflect regulatory enforcement intensity and climate control infrastructure maturity across geographies.
- Laboratories:Validated environmental monitoring for pharmaceutical stability testing and analytical method compliance. EMA and FDA audit frequencies drive replacement cycles for calibrated instrument fleets.
- HVAC:Building automation integration for indoor air quality management and thermal comfort optimization. EPA guidelines and OSHA thermal stress thresholds expand commercial workplace compliance demand.
- Agriculture:Canopy microclimate monitoring for irrigation timing and frost protection decisions. Non-contact infrared adoption accelerates in California orchards and Bordeaux vineyards.
- Greenhouses:Continuous humidity control for hydroponic crop yield optimization. Controlled environment agriculture operations in the Netherlands and Spain specify integrated sensor arrays.
HVAC absorbs the largest installed base; Laboratories show the steepest expansion trajectory on regulatory compliance mandates.
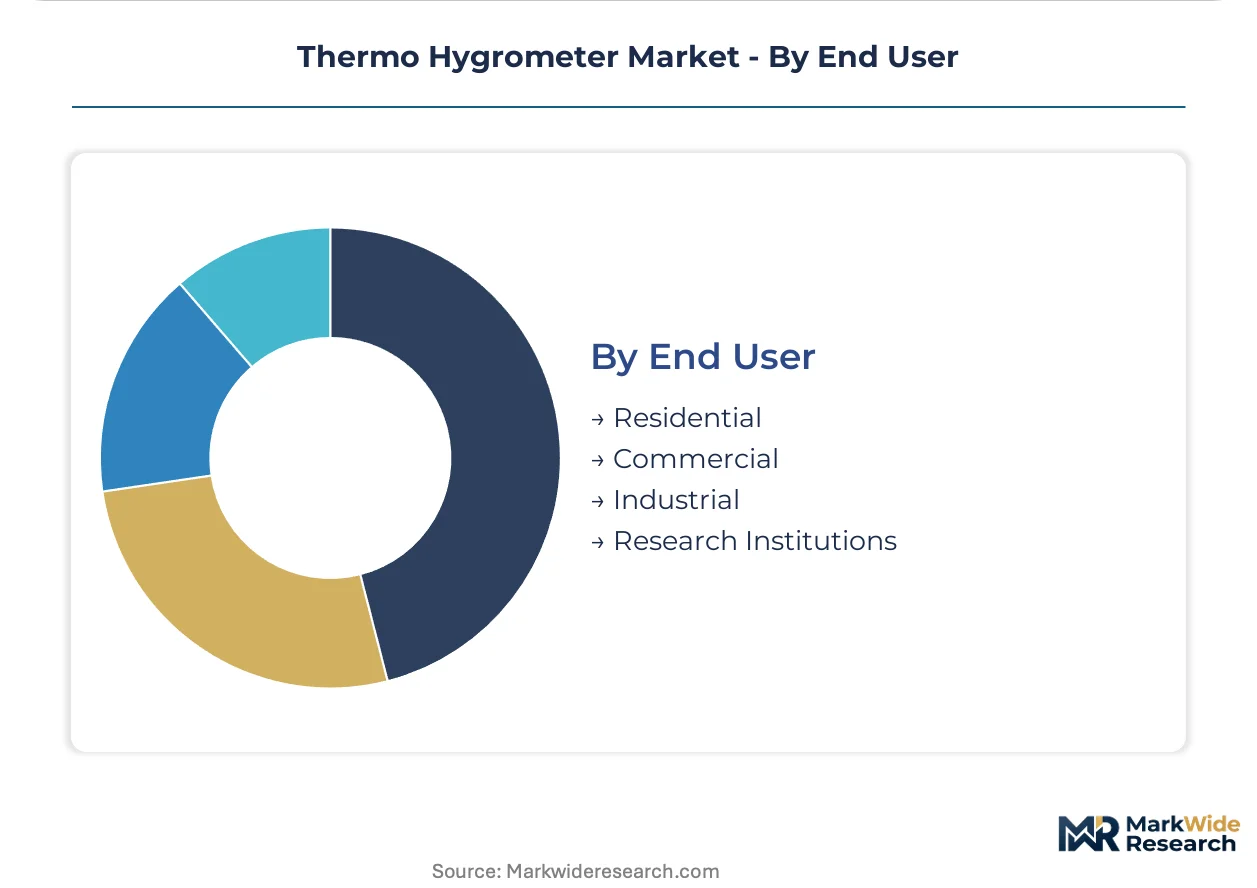
End User:
Customer type determines procurement authority structure, with multi-site pharmaceutical operations shifting from capital purchase to subscription calibration models.
- Research Institutions:Meteorological-grade calibration requirements with documented traceability chains. Premium pricing sustains on Finnish and Swiss calibration protocol adherence.
- Industrial:Process control integration for manufacturing yield protection and material stability. Food safety modernization in India creates first-mover opportunity for calibrated wireless networks.
- Commercial:Building management system integration for tenant comfort and energy efficiency. Legacy BACnet and Modbus protocol friction complicates wireless retrofit sales cycles.
- Residential:Consumer-grade accuracy for home comfort monitoring and mold prevention. Smart home ecosystem compatibility drives product selection criteria.
Industrial end users represent the dominant revenue pool; Research Institutions command the highest per-unit margins on calibration service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical laboratories deploy calibrated instrument fleets at precision thresholds exceeding Indian food safety infrastructure by an order of magnitude. This consumption-mix differential separates regulatory-mandated replacement cycles from first-time equipment procurement across geographies.
United States
FDA-regulated cold chain facilities drive wireless sensor demand for continuous environmental monitoring under 21 CFR Part 11 electronic record mandates. New Jersey pharmaceutical procurement teams now prioritize cloud-managed calibration scheduling over capital purchase agreements. Pfizer and Sanofi operations in New Jersey concentrate validated instrument deployments.
Germany
EMA Good Manufacturing Practice updates force laboratory expansion of traceable instrument fleets for temperature-sensitive biologics storage. German and French research institutions sustain premium pricing through meteorological-grade calibration protocol adherence. Frankfurt pharmaceutical clusters anchor calibrated fleet procurement timelines.
India
FSSAI food safety modernization and CDSCO pharmaceutical storage rules create first-mover opportunity for calibrated wireless sensor networks. The country's national food safety regulator mandates environmental tracking infrastructure previously absent across cold chain logistics. Maharashtra pharmaceutical manufacturing zones drive initial calibrated instrument adoption.
China
Dual carbon goals and building energy efficiency standards expand HVAC-integrated thermo hygrometer demand for indoor air quality management. The national standards administration enforces measurement instrument certification aligned with EU Measuring Instruments Directive harmonization. Yangtze River Delta manufacturing clusters adopt capacitive MEMS sensors for process yield protection.
Japan
Meteorological-grade research applications concentrate demand for thermoelectric dewpoint sensors achieving highest accuracy thresholds. The Ministry of Economy, Trade and Industry supports precision instrument calibration infrastructure for semiconductor fabrication environmental control. Kanto region research institutions anchor premium-tier procurement.
Thermo Hygrometer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication separating precision sensor foundries from assembly-only competitors. The market structures around three archetypes: vertically integrated multi-nationals controlling capacitive element costs, calibration-protocol specialists commanding research institution premiums, and handheld portability leaders occupying industrial maintenance channels. Competitive moves concentrate on predictive analytics service revenue models and sensor miniaturization trajectories displacing standalone instruments.
Within the integrated tier, Honeywell International Inc. exemplifies captive semiconductor fabrication advantages, while Vaisala Corporation anchors meteorological-grade calibration positioning. Testo SE & Co. KGaA occupies the handheld portability vector with localized European service networks. These three represent distinct competitive archetypes rather than direct segment overlap.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Extech Instruments |
| Testo SE & Co. KGaA |
| Dwyer Instruments, Inc. |
| PCE Instruments |
| Fluke Corporation |
| Omega Engineering Inc. |
| Rotronic AG |
| Vaisala Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day calibration turnaround windows at Finnish and Swiss meteorological laboratories concentrate premium-tier pricing power with protocol-certified vendors while compressing margins for assembly-only competitors lacking captive foundry capacity. This lead-time bottleneck shapes procurement patterns across EMA-audited pharmaceutical facilities, where validated instrument fleets command three-tier pricing stratification across certified-premium, traceable-standard, and uncertified-economy performance levels.
Pricing Analysis
Long-term calibration-as-a-service contracts displace spot-market instrument purchases in multi-site pharmaceutical operations, with subscription structures anchoring vendor selection criteria on software integration depth rather than standalone hardware specifications. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and geographic proximity to meteorological-grade calibration capacity, with German and French laboratories least price-sensitive due to EMA audit frequency requirements. Pricing pressure intensifies in the Indian cold chain segment as FSSAI modernization mandates attract low-cost capacitive MEMS entrants. Residential HVAC installers exhibit highest price sensitivity, prioritizing first-cost analog units over digital accuracy thresholds.
Supply Chain Analysis
Finland and Switzerland anchor meteorological-grade calibration certification capacity, while Taiwan and South Korea supply semiconductor foundry services for capacitive sensing element miniaturization. The thermo hygrometer supply chain draws from rare earth element deposits for thermopile infrared detectors and polymer dielectric formulations for humidity-responsive capacitive layers. Single-source vulnerability concentrates in meteorological-grade calibration engineer pipelines, where certified technician scarcity extends instrument downtime beyond audit tolerance windows. Distribution runs through authorized service networks for validated pharmaceutical tiers and direct e-commerce channels for residential HVAC segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-as-a-service recurring revenue layers expand faster than hardware shipments across FDA-regulated pharmaceutical operations, transforming vendor economics from capital equipment margins toward predictive analytics subscription attach rates.
For Market Incumbents: Shield premium positioning through captive semiconductor fabrication control over capacitive element costs, insulating HVAC and pharmaceutical verticals from MEMS miniaturization-driven price erosion. Deepen backward integration into polymer dielectric formulation to preempt REACH substance restriction compliance failures. Lock calibration protocol exclusivity through Swiss and Finnish laboratory partnerships, raising switching costs for EMA-audited research institutions. For New Entrants and Emerging Players: CE marking fast-track under EU Measuring Instruments Directive harmonization enables rapid market access for wireless IoT architectures targeting underpenetrated Indian cold chain infrastructure. FSSAI food safety modernization and CDSCO pharmaceutical storage rules create first-mover white space for calibrated sensor networks in Maharashtra pharmaceutical zones. Pursue partnership-based distribution with local HVAC contractors rather than direct enterprise sales to bypass entrenched service network advantages. For Investors and Strategic Acquirers: Long-term, this sits as a predictive maintenance software play because edge AI convergence in sensor firmware displaces traditional break-fix service models with recurring anomaly detection contracts. Target acquisition candidates with embedded algorithm development capabilities and existing pharmaceutical calibration service relationships. Monitor FDA 21 CFR Part 11 enforcement intensity as the inflection signal for validated wireless sensor deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-as-a-Service Platform Launch | Cloud-managed scheduling displaces capital purchase agreements at Pfizer and Sanofi procurement teams. |
| Capacitive MEMS Foundry Partnership | Semiconductor fabrication scale reduces per-element costs for agricultural canopy monitoring penetration. |
| Edge AI Firmware Integration | On-device anomaly detection enables predictive maintenance contracts replacing break-fix service models. |
| Indian Cold Chain Distribution Alliance | FSSAI modernization mandates create first-mover advantage for calibrated wireless sensor networks. |
| REACH-Compliant Polymer Reformulation | ECHA substance restrictions accelerate material substitutions without degrading humidity response curves. |
Methodological Framework
Desk research of regulatory filing databases, customs trade records, and notified body certification directories preceded structured interviews with pharmaceutical quality assurance directors, HVAC system integration engineers, meteorological calibration laboratory technicians, and agricultural precision technology procurement managers. Primary fieldwork with instrument manufacturers and end-user facilities combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA Good Manufacturing Practice updates, and EU Measuring Instruments Directive technical standards. Bottom-up shipment estimates triangulated against top-down addressable market sizing across product type, technology, and application segmentation.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with analytical frameworks modeling digital, wireless, analog, and portable product categories alongside capacitive, infrared, resistive, and thermoelectric technology tiers. Segmentation dimensions include laboratory validation grade, HVAC integration complexity, and agricultural monitoring spatial coverage requirements. CAGRs derive from regression-based trend extrapolation calibrated to regulatory mandate implementation timelines and semiconductor foundry capacity expansion trajectories. Forecast inputs incorporate cold chain infrastructure investment pipelines and EPA indoor air quality guideline enforcement patterns.
Underlying assumptions cover EMA and FDA audit frequency stability, rare earth element supply continuity, and CE marking harmonization progression, with deviation risk concentrated in meteorological-grade calibration capacity constraints and multi-protocol building management system integration friction. Forecasts reflect these assumption layers with explicit sensitivity ranges for regulatory enforcement intensity and MEMS miniaturization cost curves. Recalibration cycles align with material shifts in FDA 21 CFR Part 11 guidance updates and EU F-Gas Regulation phase-down implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Micropump Market