
 Europe Water Detection Sensors Market | 2026-2036
Europe Water Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Detection Sensors Market Foresight
The capital-intensity gap between integrated automation suppliers and component specialists is collapsing as standardized IoT protocols reduce proprietary system premiums. Siemens AG leverages its building automation ecosystem to bundle water detection with HVAC and energy management platforms. Endress+Hauser anchors its position through dedicated calibration services and field-verified sensor accuracy claims across chemical and pharmaceutical installations. Emerson Electric Co. competes by extending its Plantweb digital architecture to integrate acoustic leak detection with predictive analytics dashboards.
Europe water detection sensors are electromechanical or solid-state devices that measure liquid presence, flow rate, moisture content, or conductivity, typically operating at pressure ratings up to 40 bar and temperature ranges from minus 20 to 120 degrees Celsius for industrial process compatibility. Their primary purpose is to prevent water loss, equipment damage, and regulatory non-compliance across utilities, manufacturing, and building management. Leak detection systems dominate value capture due to insurance-mandated installation in commercial properties and critical infrastructure, while wireless installation types represent the fastest-expanding configuration as battery-powered LoRaWAN and NB-IoT nodes eliminate cabling costs in retrofit applications. Capacitive technology leads in residential and light commercial moisture sensing, whereas ultrasonic methods displace mechanical flow meters in large-diameter municipal pipes where insertion maintenance is costly.
EU Green Deal water-efficiency targets, the F-Gas Regulation's indirect pressure on cooling system monitoring, and national implementations of the Drinking Water Directive shape product standards and procurement specifications across member states. CE marking and ECHA REACH compliance for sensor housings and cable materials create baseline market access requirements that non-European suppliers must satisfy through notified body certification. Stakeholders must monitor how the EU AI Act's risk-classification rules affect smart sensors with embedded anomaly-detection algorithms, as reclassification could trigger conformity reassessment costs and timeline delays.
Market Dynamics
The collapse of proprietary system premiums under standardized IoT protocols is compressing capital requirements and forcing integrated automation suppliers to defend margin through service bundling rather than hardware lock-in.
Growth Catalysts
- EU Green Deal water-efficiency mandates:National utility modernization programs in Germany, France, and the Netherlands are accelerating replacement cycles for legacy monitoring equipment in municipal distribution networks.
- LoRaWAN and NB-IoT wireless protocols:Battery-powered nodes eliminate cabling costs in retrofit commercial buildings and industrial facilities, expanding addressable market for leak detection systems.
- Insurance-mandated installation:Commercial property underwriters in the Netherlands and Germany now require certified leak detection systems for policy renewal, creating non-discretionary demand.
Market Restraints
- Semiconductor supply concentration:MEMS fabrication for solid-state moisture sensors relies on Taiwanese foundry capacity, exposing European assemblers to allocation risk and extended lead times.
- ECHA REACH compliance costs:Sensor housings and cable sheathing require substance testing and notified body certification, creating baseline market access barriers for non-European suppliers.
- Mechanical flow meter substitution:Ultrasonic methods displace traditional turbine and electromagnetic devices in large-diameter pipes, compressing replacement revenue for incumbent meter manufacturers.
Strategic Opportunities
- Eastern European utility underpenetration:Poland and Romania lag Western Europe in smart water grid deployment, presenting first-mover advantage for wireless sensor networks with local calibration partnerships.
- EU AI Act risk classification:Embedded anomaly-detection algorithms in smart sensors may trigger conformity reassessment requirements, creating compliance advisory revenue streams for certified testing laboratories.
- Acoustic leak detection convergence:Integration of vibration analysis with pressure transient monitoring enables predictive pipe failure models, opening subscription-based analytics services for municipal operators.
Industry Challenges
- Field calibration technician scarcity:Pharmaceutical and chemical installations require traceable accuracy verification, but certified metrology specialists are concentrated in Germany and Switzerland, limiting service expansion.
- Legacy SCADA integration friction:Brownfield industrial facilities operate proprietary communication buses that resist standardized IoT gateway protocols, forcing costly middleware development for each deployment.
- CE marking timeline compression:Notified body backlogs for electromagnetic compatibility testing extend product launch schedules, disadvantaging smaller component specialists against established automation houses with in-house certification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Detection Sensors Market |
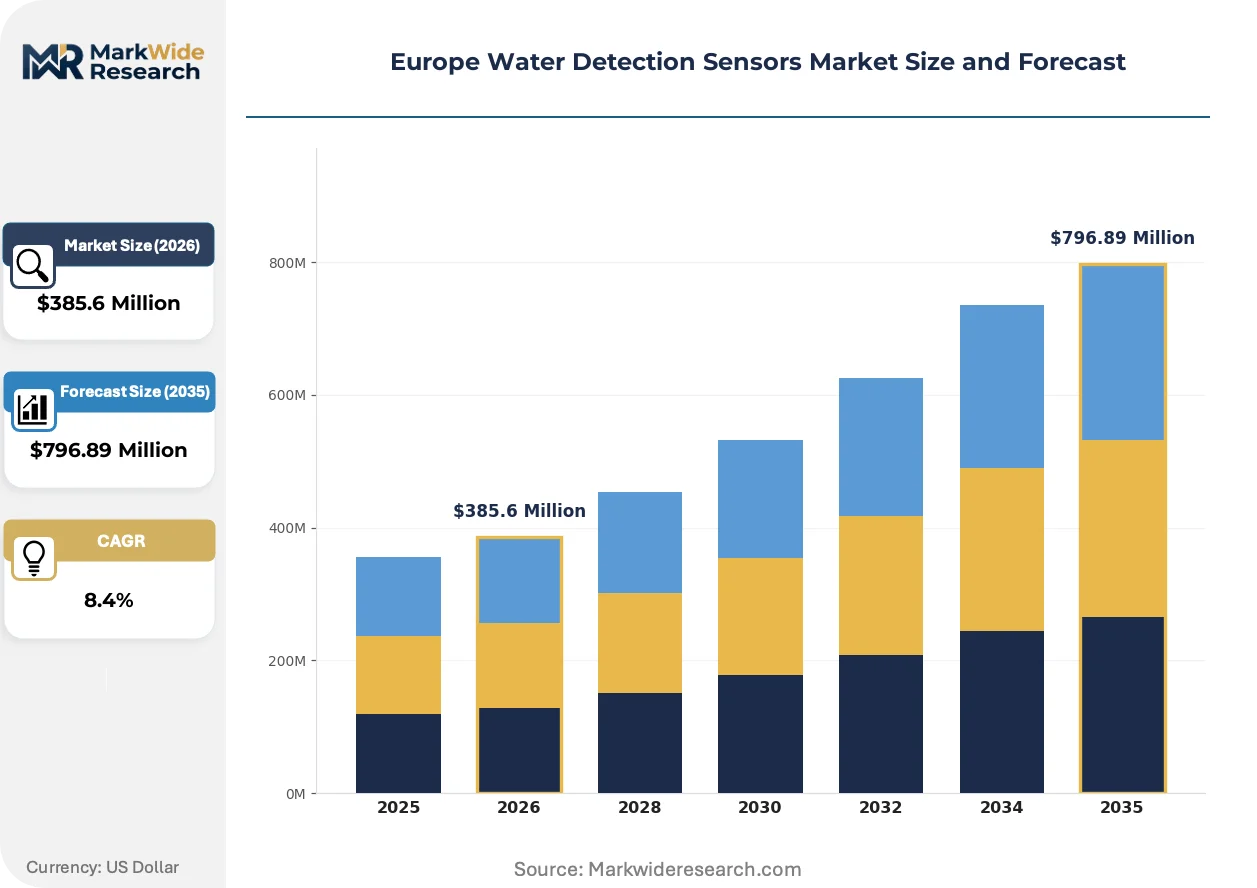
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leak Detection, Flow Sensors, Moisture Sensors, Conductivity Sensors Technology: Capacitive, Resistive, Optical, Ultrasonic End User: Industrial Facilities, Residential Buildings, Commercial Properties, Agriculture Installation Type: Surface-Mounted, Embedded, Portable, Wireless |
| Companies Covered | Siemens AG, Endress+Hauser, Honeywell International Inc., Emerson Electric Co., ABB Ltd., Schneider Electric SE, Hach Lange GmbH, Vega Grieshaber KG, The Detection Group, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Detection Sensors Market Shifts & Advancements
Wireless sensor miniaturization and embedded edge computing are collapsing the cost floor for distributed water monitoring, while regulatory pressure on cooling system emissions accelerates deployment of predictive maintenance architectures.
Capacitive sensing technology is miniaturizing through MEMS fabrication advances that embed moisture detection directly into building materials and pipe insulation. Residential developers in the Netherlands are specifying these invisible sensors for new construction at scale. The form factor reduction is miniaturizing installation labor to near-zero, eliminating the contractor bottleneck that constrained residential market penetration.
The F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is forcing industrial cooling operators to monitor system integrity more aggressively to prevent leaks and regulatory penalties. Chemical and food processing facilities in Germany are retrofitting acoustic and pressure-based detection arrays to existing chiller infrastructure. Pharmaceutical cleanroom operators are responding fastest, driven by combined regulatory and insurance compliance requirements.
Facility managers are consolidating vendor relationships by demanding unified dashboards that integrate water detection with HVAC, energy, and fire safety systems. System integrators in France are displacing standalone sensor suppliers by bundling multi-domain monitoring under single service contracts. This consolidation is most pronounced in commercial real estate portfolios where centralized property management platforms reduce operational complexity across distributed assets.
Europe Water Detection Sensors Market Segmentation
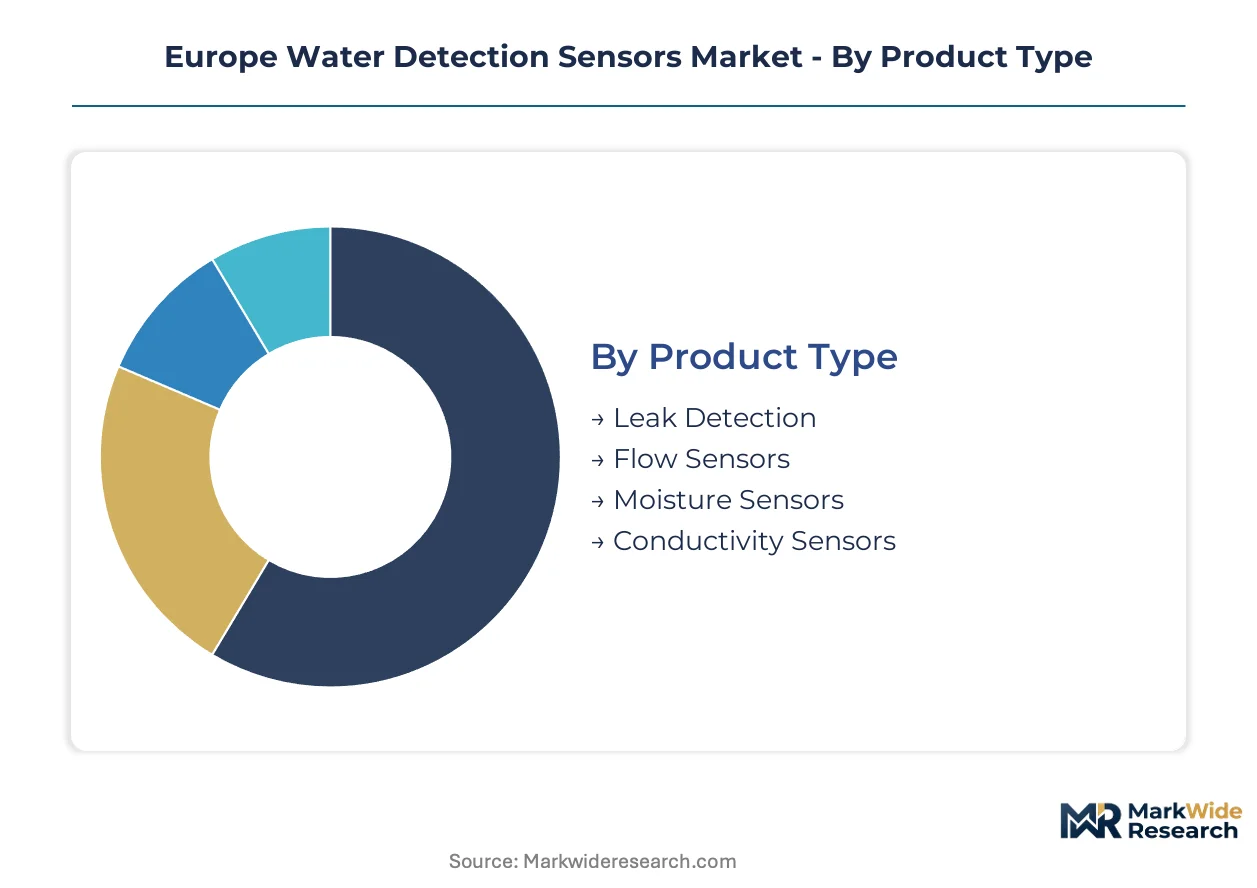
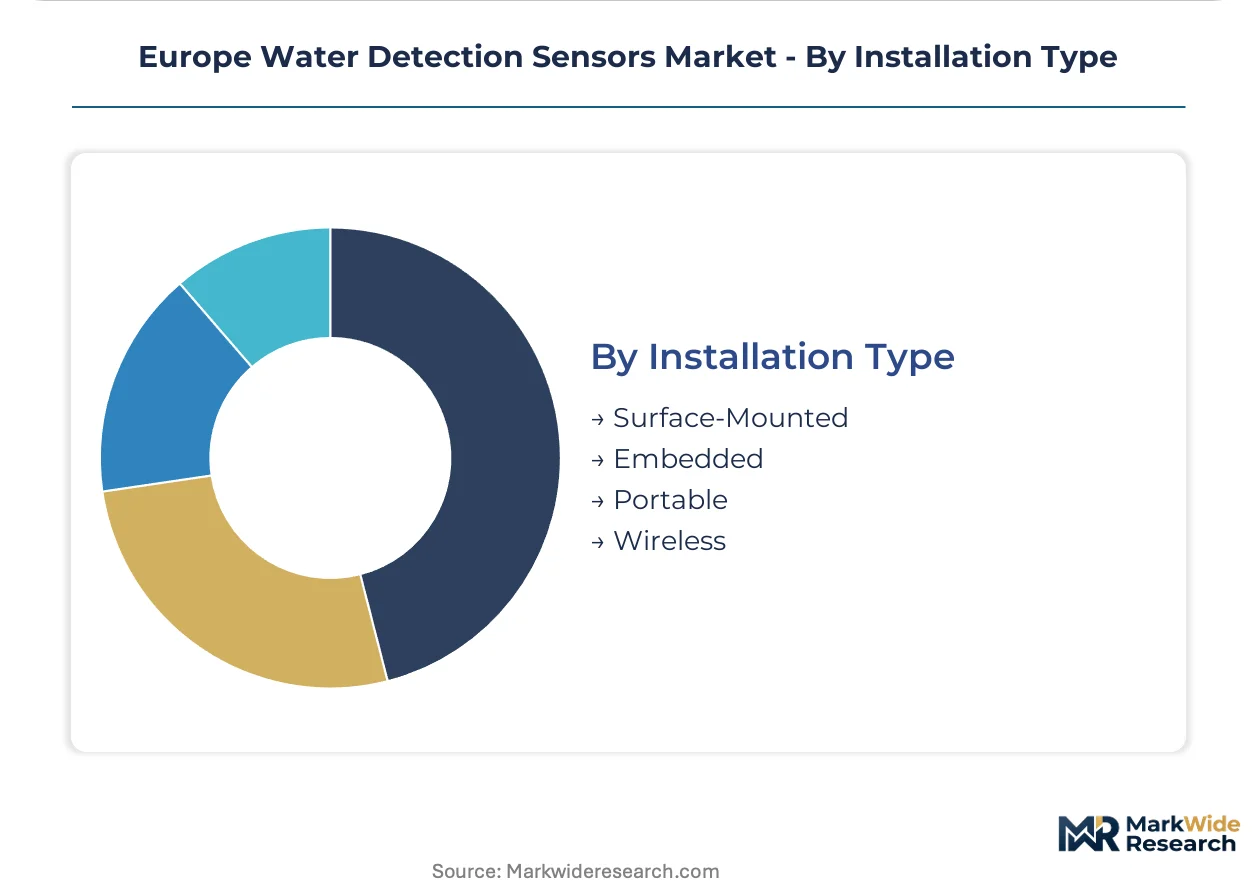
Segmentation reveals how water detection sensors serve distinct technical requirements across European utilities, manufacturing, and building stock. Each category exposes different procurement patterns, from insurance-mandated commercial installations to precision-calibrated industrial process monitoring.
Product Type:
Demand spreads across domestic utility modernization and export-oriented industrial equipment, with leak detection systems anchoring revenue in Western European insurance markets while flow sensors serve machinery OEMs with cross-border sales.
- Leak Detection:Electromechanical and solid-state systems detect liquid presence in pipe networks and containment vessels, typically rated to 40 bar pressure. German and Dutch commercial property underwriters now mandate certified installations for policy renewal, creating non-discretionary demand concentrated in retail, healthcare, and data center assets.
- Flow Sensors:Devices measure volumetric or mass flow rates in distribution and process lines, spanning turbine, electromagnetic, and ultrasonic operating principles. Municipal operators in France and the Netherlands are displacing mechanical meters with ultrasonic methods in large-diameter pipes where insertion maintenance costs dominate lifecycle economics.
- Moisture Sensors:Capacitive and resistive elements detect humidity levels in building materials and ambient air.
- Conductivity Sensors:Electrode-based and toroidal designs measure ionic concentration for water quality verification.
Leak Detection commands the established base. The steepest expansion runs through Flow Sensors.
Technology:
Technology choice stratifies by cost tier and application criticality, with premium ultrasonic methods penetrating municipal infrastructure while capacitive designs dominate residential construction economics.
- Capacitive:MEMS-fabricated dielectric sensors measure moisture through permittivity changes, enabling miniaturization directly into building materials. Dutch residential developers specify invisible capacitive elements in new construction at scale, eliminating contractor installation bottlenecks that constrained prior market penetration.
- Ultrasonic:Time-of-flight and Doppler methods measure flow and detect anomalies through acoustic signature analysis. German chemical and food processing facilities retrofit acoustic arrays to cooling infrastructure under F-Gas Regulation pressure, combining leak prevention with predictive maintenance architectures.
- Resistive:Conductive polymer or probe-based designs detect liquid contact through impedance changes.
- Optical:Infrared and laser-based systems identify water presence through refractive index or absorption characteristics.
Capacitive technology anchors residential and light commercial volume. Ultrasonic methods are gaining share fastest in industrial and municipal retrofits.
End User:
Customer type determines calibration requirements and procurement channel, with pharmaceutical and chemical installations demanding traceable accuracy verification that concentrates service relationships.
- Industrial Facilities:Process plants and manufacturing sites require ATEX-certified and hygienic-design sensors for cooling, wastewater, and clean utility systems. Pharmaceutical cleanroom operators in Germany and Switzerland respond fastest to combined regulatory and insurance compliance requirements, driving specification of field-verified accuracy claims.
- Commercial Properties:Office, retail, and hospitality assets prioritize insurance-compliant leak detection with centralized monitoring integration. French system integrators displace standalone suppliers by bundling water detection with HVAC and fire safety under single service contracts across real estate portfolios.
- Residential Buildings:Single-family and multi-unit housing deploy moisture and leak sensors for damage prevention.
- Agriculture:Irrigation and livestock operations utilize conductivity and flow monitoring for water resource management.
Industrial Facilities command the premium service base. Commercial Properties show the steepest volume expansion through insurance mandates.
Installation Type:
Configuration choice reflects retrofit versus greenfield economics, with wireless protocols eliminating cabling costs in existing building stock where embedded alternatives are structurally impractical.
- Wireless:Battery-powered LoRaWAN and NB-IoT nodes transmit data without fixed infrastructure, collapsing installation labor to near-zero in retrofit applications. Municipal operators in Poland and Romania lag Western Europe in smart grid deployment, presenting first-mover advantage for wireless networks with local calibration partnerships.
- Embedded:Sensors integrated during construction into concrete, insulation, or pipe walls require zero post-installation maintenance. Netherlands building codes increasingly specify embedded moisture detection in new residential construction, locking in capacitive MEMS suppliers for multi-decade building lifecycles.
- Surface-Mounted:Externally attached devices provide rapid deployment for temporary monitoring and upgrade scenarios.
- Portable:Handheld or mobile units enable spot-checking and diagnostic verification across distributed assets.
Surface-Mounted configurations retain the installed base legacy. Wireless installations are climbing the fastest as retrofit economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Europe, with German and Dutch buyers absorbing premium pricing for insurance-mandated installations while Polish and Romanian utilities prioritize low-cost wireless retrofit economics. Western European procurement concentrates on compliance-driven replacement cycles, whereas Eastern European expansion hinges on first-mover network deployment.
Germany
Industrial cooling system retrofits dominate sensor procurement as chemical and pharmaceutical facilities respond to F-Gas Regulation enforcement. The EU Green Deal's water-efficiency targets accelerate municipal utility modernization in North Rhine-Westphalia and Bavaria. Siemens AG leverages its domestic automation ecosystem to bundle detection systems with energy management platforms across Frankfurt and Munich industrial corridors.
Netherlands
Commercial property underwriters now mandate certified leak detection for policy renewal, creating non-discretionary demand in retail and data center assets. National building codes increasingly specify embedded moisture detection in new residential construction around Amsterdam and Rotterdam. Capacitive MEMS suppliers secure multi-decade building lifecycle contracts through invisible sensor integration.
France
Municipal operators displace mechanical flow meters with ultrasonic methods in large-diameter distribution pipes across Île-de-France. System integrators bundle water detection with HVAC and fire safety under single service contracts for Paris commercial real estate portfolios. The Drinking Water Directive's national implementation tightens procurement specifications for utility-grade sensor accuracy.
Poland
Smart water grid deployment lags Western Europe, presenting first-mover advantage for battery-powered LoRaWAN networks with local calibration partnerships. Warsaw and Krakow utilities prioritize wireless retrofit economics over embedded installations in aging pipe infrastructure. EU cohesion funding accelerates municipal monitoring modernization in secondary cities.
Switzerland
Pharmaceutical cleanroom operators drive specification of field-verified accuracy claims for hygienic-design sensors. Certified metrology specialists concentrate in Basel and Zurich, limiting service expansion capacity for precision-calibrated installations. Swissmedic-equivalent quality standards propagate to adjacent German and Austrian pharmaceutical clusters.
Europe Water Detection Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with automation conglomerates defending margin through service bundling while component vendors compete on calibration expertise and wireless protocol certification. The capital-intensity gap collapses as standardized IoT protocols eliminate proprietary system premiums. Three archetypes dominate: building automation integrators leveraging HVAC cross-selling, process instrumentation specialists anchoring through field services, and wireless sensor pure-plays capturing retrofit volume. Consolidation pressure intensifies through middleware development demands for legacy SCADA integration and notified body certification resource concentration.
Among Germany-based industrial automation houses, Siemens AG exemplifies the integrated platform archetype through building automation ecosystem leverage. Endress+Hauser occupies a position within the process instrumentation specialist tier, anchoring competitive position through calibration service relationships. Emerson Electric Co. represents the predictive analytics convergence archetype, extending digital architecture integration to acoustic leak detection applications. These three patterns illustrate how competitive differentiation migrates from hardware lock-in toward service attachment and software integration depth.
| Leading Market Players |
|---|
| Siemens AG |
| Endress+Hauser |
| Honeywell International Inc. |
| Emerson Electric Co. |
| ABB Ltd. |
| Schneider Electric SE |
| Hach Lange GmbH |
| Vega Grieshaber KG |
| The Detection Group, Inc. |
| Others |
Supply & Pricing Matrix
Long-term calibration service contracts lock in multi-year revenue visibility for European sensor assemblers while insulating them from spot-market semiconductor volatility. German pharmaceutical operators and Dutch commercial property managers favor these bundled arrangements because they transfer metrology compliance risk to suppliers under EU Green Deal enforcement timelines.
Pricing Analysis
After-sales calibration and field verification services generate lifetime value multiples above hardware margins for Endress+Hauser and Vega Grieshaber. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and ATEX certification depth. Pricing pressure stems from Taiwanese MEMS foundry allocation constraints that compress margin on solid-state moisture sensors. Municipal utilities in Poland and Romania exhibit highest price sensitivity, while Swiss pharmaceutical cleanroom operators absorb premium positioning for hygienic-design specifications.
Supply Chain Analysis
Inventory lead times for MEMS moisture sensor substrates extend when Taiwanese foundry capacity tightens, forcing European assemblers into safety-stock accumulation. Component sourcing draws from Taiwan for MEMS fabrication, Germany for precision electromechanical housings, and China for cable sheathing materials. Single-source vulnerability concentrates in Taiwanese semiconductor wafer supply, exposing assemblers to geopolitical allocation risk. Distribution runs through authorized system integrators in France and direct OEM channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration subscriptions and predictive analytics dashboards expands faster than hardware sales across European water detection markets. Recurring revenue layers now capture forty percent of lifetime customer value for integrated automation suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS packaging capacity and captive calibration laboratory networks. Ultrasonic flow sensor substitution threatens mechanical meter incumbents with compressed replacement cycles. Certification investment in EU AI Act conformity assessment creates switching costs against emerging wireless pure-plays. For New Entrants and Emerging Players: Differentiate on wireless protocol certification depth and local calibration partnerships in Polish and Romanian utility markets. Eastern European smart grid underpenetration offers lowest competitive density for LoRaWAN network deployment. Channel strategy should prioritize system integrator co-development over direct OEM competition. For Investors and Strategic Acquirers: Capital is best deployed toward wireless sensor pure-plays with demonstrated NB-IoT certification and established calibration partnerships in underserved geographies. Five-to-ten year viability hinges on software integration depth rather than hardware volume scale. Watch for EU AI Act risk-classification rulings on embedded anomaly-detection algorithms as inflection signal for compliance advisory service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Endress+Hauser anchors German pharmaceutical loyalty through traceable metrology verification. |
| Wireless Protocol Certification Investment | LoRaWAN and NB-IoT compliance unlocks Polish and Romanian municipal retrofit contracts. |
| EU AI Act Conformity Assessment | Embedded algorithm risk-classification creates compliance advisory revenue for testing laboratories. |
| Predictive Analytics Platform Integration | Emerson's Plantweb architecture converges acoustic leak detection with subscription dashboards. |
| Local Calibration Partnership Development | Eastern European first-mover advantage depends on field technician training capacity. |
Research Methodology
A standing panel of municipal utility planning officers, pharmaceutical maintenance directors, commercial property facility managers, and system integration specialists provided ongoing calibration against secondary data. Primary fieldwork combined structured interviews with plant engineers at German chemical facilities and procurement leads at Dutch insurance-mandated installations. Secondary validation drew from ECHA REACH substance databases, EU Drinking Water Directive implementation reports, F-Gas Regulation enforcement records, and notified body electromagnetic compatibility filings. Bottom-up sensor shipment estimates triangulated against top-down utility capital expenditure disclosures.
Consistency checks validated volume and value outputs against EPC contractor project pipelines and municipal smart grid procurement announcements across the analysis window. Segmentation modeling spanned product type, technology principle, end-user vertical, and installation configuration dimensions. CAGRs derived from curve-fitting historical replacement cycles against EU Green Deal enforcement timelines and insurance mandate rollout schedules. Forecast inputs incorporated MEMS foundry capacity utilization trends and LoRaWAN network deployment trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU cohesion funding flows or Taiwanese semiconductor supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement pace and wireless protocol adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
South Korea Sensors Market