
 Differential Pressure Sensor Market | 2026-2036
Differential Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
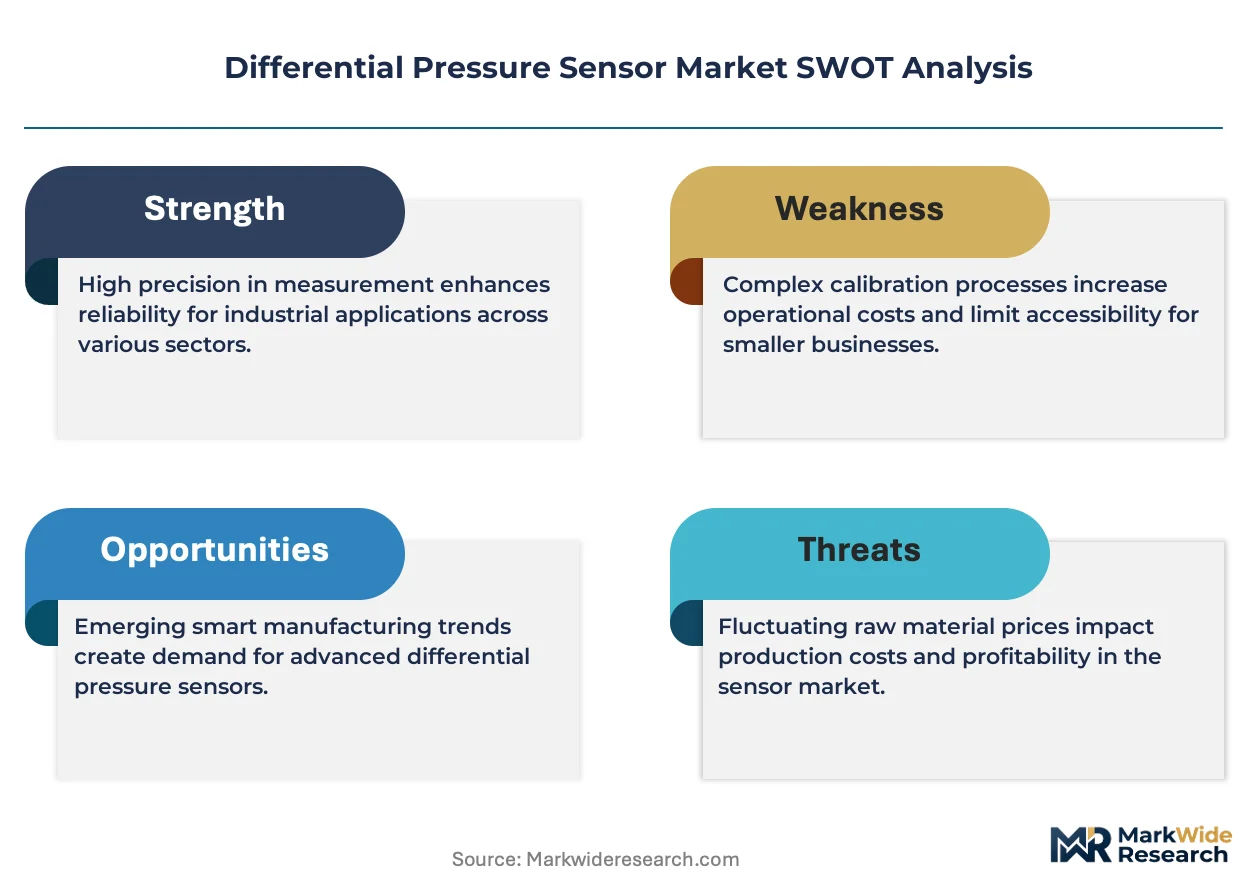
Differential Pressure Sensor Market Analysis
Silicon MEMS is hardening its position over traditional ceramic capacitive elements in mid-range industrial applications, compressing bill-of-materials costs while preserving measurement stability. Honeywell leverages captive MEMS foundry capacity to anchor its position in aerospace and building management channels. Emerson competes through vertical integration into transmitter assembly, sustaining margin pools that pure component vendors cannot match. Siemens dominates European HVAC retrofit programs, where regulatory pressure for energy efficiency drives sensor refresh cycles.
A differential pressure sensor measures the pressure difference between two distinct points in a fluid system, typically employing capacitive, piezoelectric, or strain gauge transduction mechanisms with full-scale ranges from fractions of a pascal to several megapascals. Its primary purpose is to infer flow rate, filter clogging, or containment integrity across industrial process lines, medical ventilators, and building air handling units. Capacitive technology occupies the largest revenue share due to its stability in harsh media and compatibility with standard industrial communication protocols. Piezoelectric variants represent the fastest-expanding technology segment, propelled by demand for dynamic pressure measurement in combustion monitoring and turbine diagnostics. The end-user concentration in HVAC and industrial automation channels creates divergent margin structures, with building management applications favoring cost-optimized units and process industries prioritizing calibration longevity.
The EPA enforces emissions monitoring standards that mandate differential pressure measurement across stack gas and filtration systems, directly shaping product certification requirements for vendors serving US industrial accounts. REACH and the EU Green Deal impose material disclosure and energy efficiency obligations on sensors deployed in European environmental monitoring and building automation networks. FDA quality system regulations govern differential pressure sensors integrated into medical device airflow control, creating a separate compliance pathway from industrial applications. Stakeholders must monitor how evolving semiconductor export controls affect MEMS die supply security and whether regional clean air enforcement diverges enough to require localized product variants.
Market Dynamics
Silicon MEMS transduction is compressing unit economics across mid-range industrial applications while EPA stack-monitoring mandates and Taiwan's semiconductor fab expansion reshape demand geography and certification requirements simultaneously.
Growth Catalysts
- EPA Clean Air Act Enforcement:Updated emissions monitoring standards mandate differential pressure measurement across filtration and stack gas systems, forcing sensor refresh cycles in US manufacturing facilities and expanding certified vendor pools.
- Taiwan Semiconductor Fab Expansion:Cleanroom monitoring system upgrades in Hsinchu and Tainan Science Parks embed differential pressure sensors for particle containment, creating concentrated demand from high-specification buyers.
- EU Green Deal Building Retrofits:Energy efficiency mandates accelerate HVAC sensor replacement across Germany's industrial automation corridor, compressing replacement cycles from ten-year to seven-year intervals.
Market Restraints
- MEMS Die Supply Concentration:Foundry capacity for piezoelectric MEMS wafers concentrates in Taiwan and South Korea, exposing buyers to geopolitical disruption risk and extended lead times during capacity crunches.
- Ceramic Capacitive Cost Structure:Alumina substrate and precious metal electrode costs resist scale economies, trapping traditional technology in premium niches as silicon alternatives capture volume segments.
- REACH Material Disclosure Burden:ECHA substance-of-very-high-concern listings complicate supply chain documentation for sensors deployed in European environmental monitoring networks, extending compliance timelines.
Strategic Opportunities
- India Industrial Automation Corridor:PLI scheme incentives for semiconductor and pharmaceutical manufacturing create first-mover advantage for sensor vendors establishing local calibration and service infrastructure.
- Combustion Monitoring Convergence:Integration of piezoelectric differential pressure sensing with optical flame detection enables real-time turbine diagnostics, opening premium pricing in power generation aftermarket.
- Digital Twin Integration:Sensor-to-cloud architectures that embed differential pressure data directly into building management system digital twins command 15-25% price premiums in smart facility retrofits.
Industry Challenges
- Multi-Protocol Certification Complexity:Simultaneous compliance with HART, Foundation Fieldbus, and IO-Link industrial communication standards extends product development timelines and fragments engineering resources.
- Cleanroom Integration Engineering:Semiconductor fab customers demand sub-0.5% full-scale accuracy with 10-year calibration stability, requiring specialized temperature compensation algorithms that strain R&D bandwidth.
- Legacy System Interoperability:4-20mA analog infrastructure in installed industrial bases resists digital migration, forcing dual-output product variants that inflate bill-of-materials complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Differential Pressure Sensor Market |
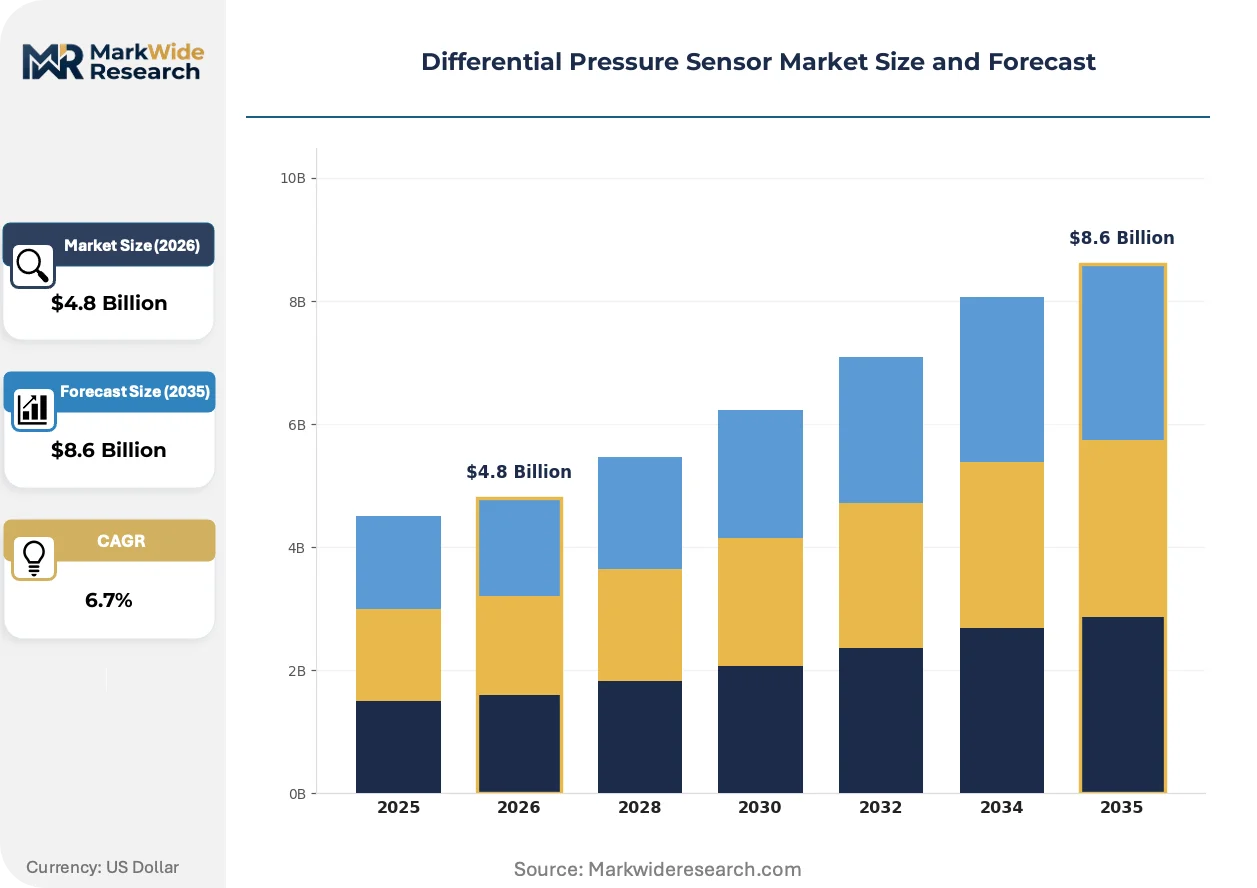
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Pressure Sensors, Gauge Pressure Sensors, Differential Pressure Sensors, Altitude Sensors Technology: Capacitive, Piezoelectric, Strain Gauge, Optical End User: Aerospace, Automotive, Environmental Monitoring, HVAC Application: Fluid Dynamics, Industrial Automation, Medical Devices, Building Management |
| Companies Covered | ABB, Yokogawa Electric, Honeywell, Keller, Endress+Hauser, Emerson, Siemens, Amphenol, WIKA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Differential Pressure Sensor Market Emerging Trajectories
Technology substitution, regulatory stringency, and buyer procurement model evolution are restructuring competitive position and margin architecture across sensor categories and geographic markets.
Silicon MEMS capacitive structures is absorbing the functional territory once held by ceramic capacitive elements in process industries requiring 0.1% accuracy. HVAC and building automation buyers in North America and Europe are adopting MEMS-based units at replacement rates exceeding legacy ceramic by three-to-one in new construction specifications. This technology is absorbing margin compression pressure while preserving measurement stability through on-chip temperature compensation, enabling vendors to defend position in mid-range industrial tiers.
REACH authorization requirements and the EU F-Gas Regulation are tightening material traceability and energy efficiency standards for sensors deployed in European environmental monitoring networks. Industrial buyers must now document substance compliance across full supply chains, favoring vendors with captive MEMS foundry control over fabless competitors. Process industries in Germany and the Netherlands are responding by consolidating supplier relationships and demanding extended calibration warranties as risk transfer mechanisms.
Consolidated procurement through integrated facility management contractors is displacing direct OEM relationships in commercial building sensor purchasing. HVAC service aggregators in the United Kingdom and Australia are unbundling sensor supply from installation and maintenance contracts, compressing unit prices while expanding volume commitments. This concentration is most visible in healthcare and education verticals where estate rationalization programs favor single-source sensor specifications across multi-site portfolios.
Differential Pressure Sensor Market Segmentation
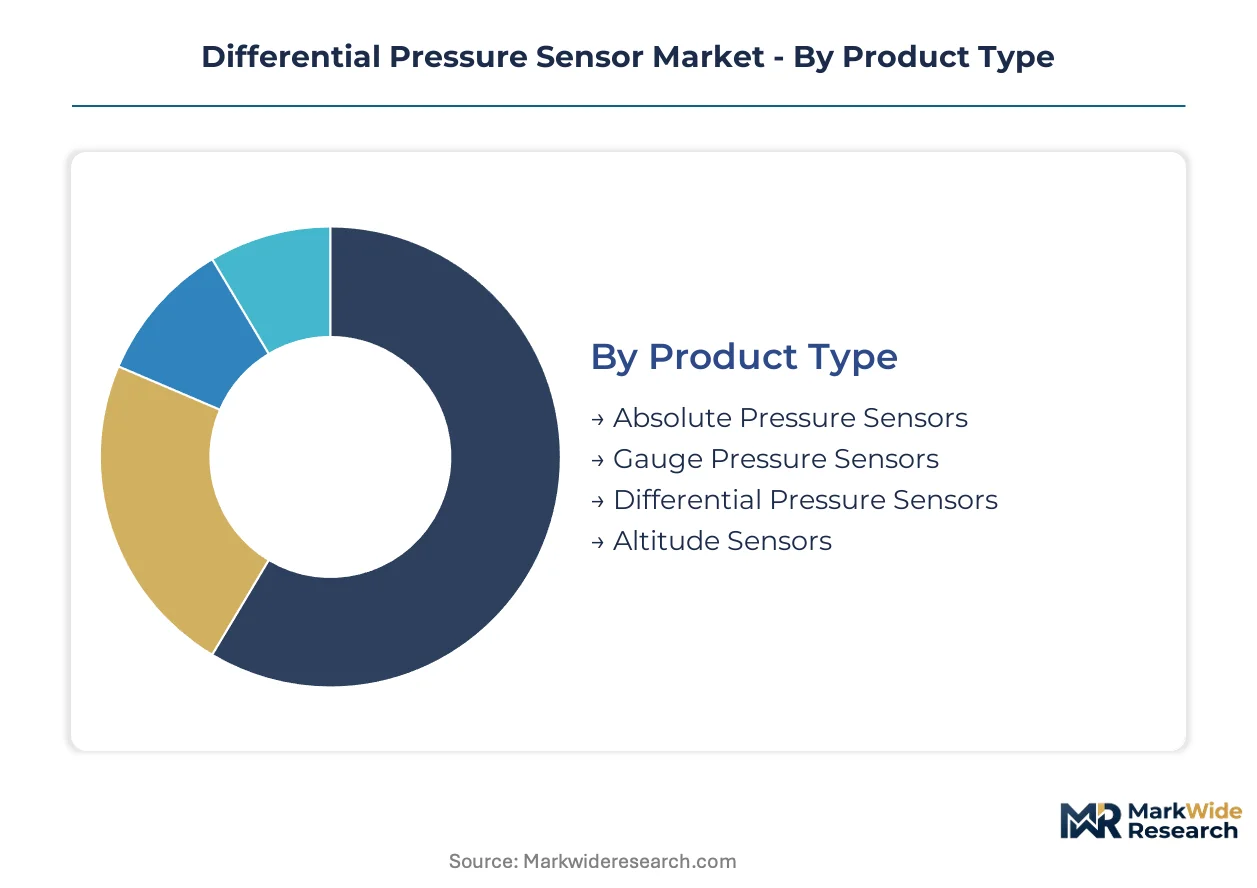
Differential pressure sensor procurement patterns diverge sharply across certification regimes, with medical and aerospace channels demanding FDA and FAA traceability while industrial buyers prioritize EPA emissions compliance. Understanding these segmentation boundaries clarifies why vendor positioning and margin structures vary dramatically despite underlying technical similarities.
Product Type:
Certification burden intensity varies substantially across product categories, with absolute pressure sensors facing the most stringent FAA airworthiness documentation and altitude sensors requiring dual EPA-FDA clearance for environmental-medical crossover applications.
- Absolute Pressure Sensors:These devices measure pressure relative to a perfect vacuum, employing sealed reference cavities that demand hermetic packaging integrity. Demand concentrates in aerospace altimetry and meteorological stations, where FAA certification timelines and MIL-STD-810G environmental testing create 18-24 month qualification cycles that lock out unproven vendors.
- Gauge Pressure Sensors:Atmospheric-referenced designs dominate automotive tire pressure monitoring and industrial pneumatics, with Tier 1 automotive suppliers in Germany and Japan driving specifications that mandate ISO 26262 functional safety compliance for electric vehicle integration.
- Differential Pressure Sensors:Twin-port configurations serve HVAC airflow measurement and filter monitoring, with EPA Clean Air Act enforcement mandating calibrated accuracy documentation across US manufacturing installations.
- Altitude Sensors:Barometric pressure-derived elevation measurement serves drone navigation and wearable fitness devices, with consumer-grade variants facing less regulatory burden than aviation-certified counterparts.
Absolute pressure sensors sit at the top of the volume ranking, with altitude sensors climbing the fastest on drone and wearable demand.
Technology:
Cost tier stratification separates mature capacitive platforms from emerging optical architectures, with piezoelectric variants capturing mid-range industrial automation spend and strain gauge designs defending legacy installed bases.
- Capacitive:Parallel-plate or interdigitated electrode structures measure pressure-induced capacitance change, offering exceptional stability in harsh media. Demand concentrates in semiconductor fab cleanroom monitoring across Taiwan and South Korea, where sub-0.5% full-scale accuracy requirements and 10-year calibration warranties favor established suppliers with captive MEMS foundry capacity.
- Piezoelectric:Crystalline materials generate charge proportional to dynamic pressure, enabling high-frequency response for combustion diagnostics. Automotive and power generation sectors in Germany and the United States are adopting these for real-time turbine monitoring, with integration into optical flame detection systems opening premium aftermarket pricing.
- Strain Gauge:Metal foil or semiconductor piezoresistive elements bonded to diaphragms provide robust measurement for hydraulic and pneumatic systems, with 4-20mA analog output compatibility preserving relevance in legacy industrial infrastructure.
- Optical:Fiber Bragg grating and interferometric techniques enable intrinsic safety in explosive atmospheres and electromagnetic immunity for MRI-adjacent medical applications, though unit costs currently restrict deployment to specialized niches.
Capacitive technology commands the largest revenue share, with optical methods gaining share fastest on intrinsic safety requirements.
End User:
Application maturity and replacement cycle timing create divergent customer profiles, with environmental monitoring networks accelerating refresh rates and aerospace procurement extending vendor relationships across multi-decade platforms.
- Aerospace:Flight-critical pitot-static and cabin pressure systems demand DO-178C software certification and AS9100 quality management, with Boeing and Airbus platform commonality enabling decade-long production contracts that amortize qualification investment.
- Automotive:Electrification is expanding sensor count per vehicle for battery thermal management and fuel cell pressure regulation, with South Korean and German OEMs specifying AEC-Q100 automotive-grade reliability.
- Environmental Monitoring:EPA stack gas and ambient air quality networks require NIST-traceable calibration with annual recertification, creating recurring service revenue streams that alter vendor economics toward lifecycle contracting.
- HVAC:Building automation retrofits across Germany's industrial corridor are compressing replacement cycles from ten to seven years under EU Green Deal efficiency mandates, with integrated facility management contractors consolidating purchasing power.
HVAC generates the highest unit volume, with environmental monitoring expanding most quickly on regulatory enforcement tightening.
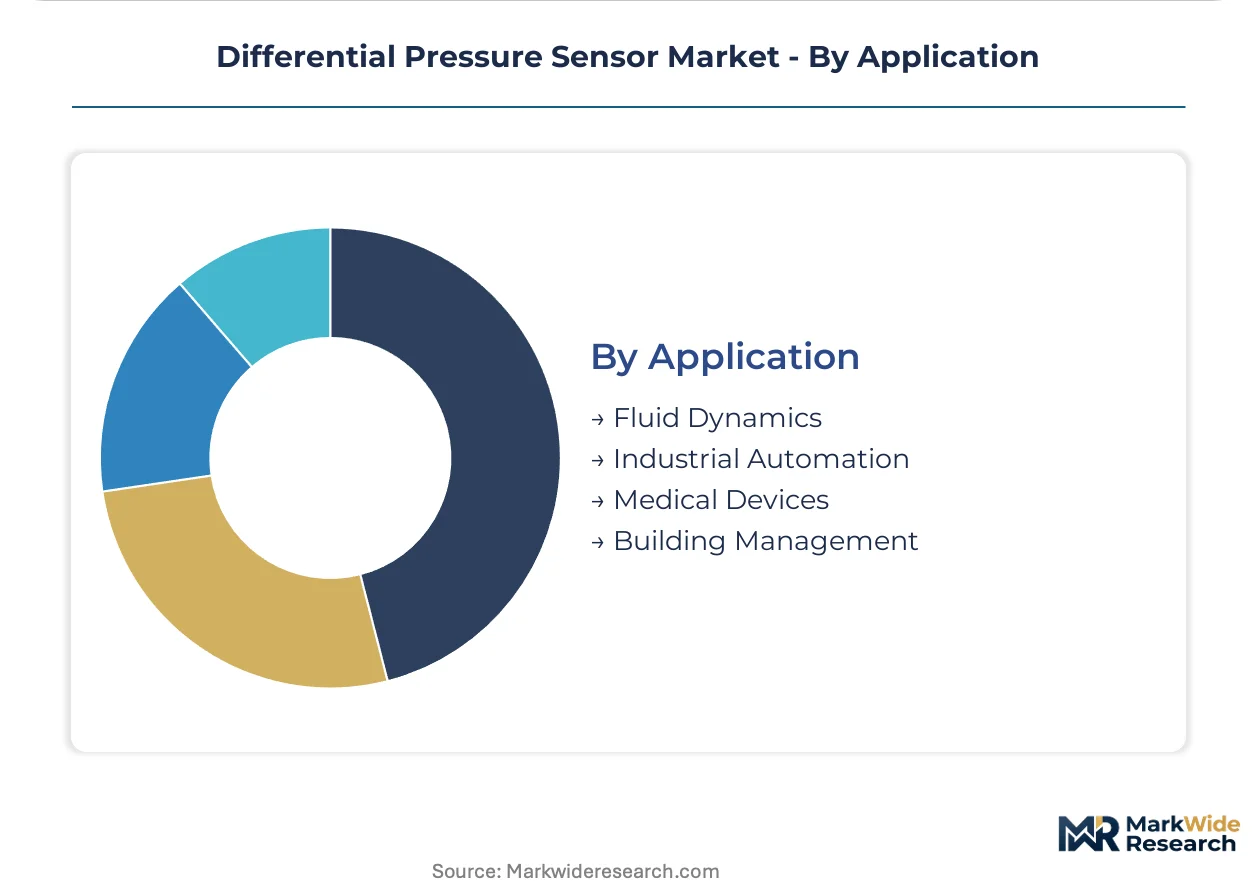
Application:
Customer type fragmentation separates specification-driven OEM relationships from price-sensitive aftermarket procurement, with medical device channels demanding FDA quality system compliance and building management favoring cost-optimized volume supply.
- Fluid Dynamics:Flow measurement via differential pressure across orifice plates and venturi tubes serves oil and gas pipeline monitoring and water utility distribution networks, with custody transfer applications requiring metrology-grade accuracy certification that limits qualified vendor pools.
- Industrial Automation:Process control loops for chemical and pharmaceutical manufacturing integrate sensors with HART and Foundation Fieldbus communication, with multi-protocol certification complexity extending development timelines for smaller competitors.
- Medical Devices:Ventilator airflow control and anesthesia machine pressure monitoring fall under FDA 21 CFR Part 820 quality system regulation, with design history file documentation and biocompatibility testing creating compliance moats around established suppliers.
- Building Management:Smart facility digital twins are commanding 15-25% price premiums for sensor-to-cloud architectures, with United Kingdom and Australian HVAC service aggregators unbundling supply from installation contracts.
Industrial automation leads in revenue contribution, with building management gaining share fastest on digital twin integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors global demand concentration for high-specification differential pressure sensors, with semiconductor cleanroom expansions driving procurement volumes. EPA enforcement in the United States and EU Green Deal retrofits in Germany are reshaping replacement cycles across manufacturing and building automation channels.
United States
Stack gas monitoring networks and pharmaceutical manufacturing drive sensor deployment across the Gulf Coast and Midwest industrial corridors. EPA Clean Air Act enforcement mandates differential pressure measurement for emissions compliance, accelerating refresh cycles in Texas and Louisiana petrochemical clusters. Houston's process automation vendors are consolidating supplier relationships to manage multi-protocol certification complexity.
Germany
HVAC retrofit programs and industrial automation upgrades concentrate demand in the North Rhine-Westphalia and Bavaria manufacturing belts. EU F-Gas Regulation and REACH material disclosure requirements favor vendors with captive MEMS foundry control over fabless competitors. Stuttgart's automotive suppliers are specifying ISO 26262-compliant sensors for electric vehicle thermal management systems.
Taiwan
Semiconductor fab expansions in Hsinchu and Tainan Science Parks embed differential pressure sensors for particle containment integrity. The country's central environmental regulator enforces cleanroom standards that demand sub-0.5% full-scale accuracy with decade-long calibration stability. Kaohsiung's facility management contractors are unbundling sensor supply from installation contracts to compress unit economics.
South Korea
Memory and logic foundry construction in Pyeongtaek and Yongin drives cleanroom monitoring system procurement at scale. The national semiconductor support framework incentivizes local sensor calibration infrastructure development. Seoul Capital Area HVAC service aggregators are consolidating purchasing power across healthcare and education vertical estates.
India
Pharmaceutical manufacturing and semiconductor assembly growth in Maharashtra and Gujarat create first-mover opportunities for sensor vendors. PLI scheme incentives for electronics manufacturing support local calibration and service infrastructure establishment. Pune's industrial automation corridor is compressing replacement cycles as process control upgrades accelerate.
Differential Pressure Sensor Market Vendor Landscape
Global majors compete with regional champions across certification depth and foundry control dimensions, producing a tiered structure where aerospace-grade documentation separates premium suppliers from cost-optimized volume players. Market concentration is moderate, with technology substitution favoring silicon MEMS vendors over traditional ceramic capacitive specialists. Three archetypes dominate: captive foundry integrators, transmitter assembly specialists, and fabless component vendors. Competitive moves center on backward integration into MEMS wafer supply and geographic expansion into India's industrial automation corridor.
Among Swiss-German precision engineering groups, Endress+Hauser and Keller occupy positions exemplifying the premium-tier archetype anchored by vertical manufacturing depth. Yokogawa Electric represents the Asia-Pacific specialist model with regional service infrastructure density. These three names illustrate how geographic origin and organizational structure correlate with competitive positioning across certification-intensive segments.
| Leading Market Players |
|---|
| ABB |
| Yokogawa Electric |
| Honeywell |
| Keller |
| Endress+Hauser |
| Emerson |
| Siemens |
| Amphenol |
| WIKA |
| Others |
Supply Flow & Price Mechanics
MEMS process engineering talent concentrated in Hsinchu and Yongin feeds directly into pricing-tier spreads, with labor-cost differentials between Taiwan and mainland China enabling three-tier pricing structures that separate aerospace-grade units from building-automation commodities.
Pricing Analysis
Alumina substrate and precious metal electrode costs pass through to ceramic capacitive sensor pricing, creating premium-mid-economy pricing differentiation where aerospace and semiconductor fab buyers absorb ISO 26262 and EPA certification premiums while HVAC contractors in Germany and Australia drive cost compression through consolidated procurement. Silicon MEMS alternatives capture volume segments by compressing bill-of-materials while preserving 0.1% accuracy, forcing ceramic specialists into filter-monitoring and combustion-diagnostic niches where calibration longevity commands price premiums. Price erosion runs through standard industrial tiers as Chinese MEMS foundries expand capacity, though medical device channels with FDA 21 CFR Part 820 requirements remain least price-sensitive due to compliance moats.
Supply Chain Analysis
Cleanroom-qualified technicians and MEMS wafer fabrication specialists concentrate in Taiwan, South Korea, and select German industrial zones, with foundry capacity for piezoelectric MEMS drawing from 300mm silicon wafer supply anchored in Hsinchu and Pyeongtaek. Alumina ceramic substrates and platinum electrode materials feed from Japanese and German specialty ceramics suppliers, creating single-source vulnerability for high-temperature applications. Distribution runs through integrated facility management contractors in European building automation and direct OEM relationships in aerospace and medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where vendors can exploit calibration-labor cost differentials between Taiwan's high-specification fab corridors and India's emerging pharmaceutical manufacturing clusters under PLI scheme incentives.
For Market Incumbents: Cement captive MEMS foundry control against fabless competitors by securing wafer supply agreements in Taiwan and South Korea before export-control tightening strains die availability. Lock in decade-long calibration service contracts with German automotive and Dutch process industry accounts as REACH documentation burdens extend compliance timelines and favor established supplier relationships.
For New Entrants and Emerging Players: Optical flame-detection integration for turbine diagnostics offers a technology-first wedge into power generation aftermarket channels where real-time combustion monitoring commands premium pricing. Target India's Maharashtra and Gujarat pharmaceutical corridors with localized calibration infrastructure, unbundling sensor supply from installation contracts to bypass entrenched European vendor relationships.
For Investors and Strategic Acquirers: Industrial automation conglomerates with building management system portfolios are the most active acquirer in this space, seeking MEMS sensor capabilities to complete digital twin architectures. Five-to-ten year viability hinges on semiconductor fab expansion sustainability; monitor Taiwan Science Park construction permits and EPA enforcement budget allocations for demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Acquisition | Secures wafer supply against Taiwan geopolitical disruption and REACH material disclosure requirements. |
| Digital Twin Platform Integration | Commands 15-25% price premiums in UK and Australian smart facility retrofits. |
| India Calibration Infrastructure Buildout | Captures PLI scheme pharmaceutical manufacturing growth in Maharashtra and Gujarat corridors. |
| Combustion Monitoring Convergence | Opens premium aftermarket pricing in German and US power generation turbine diagnostics. |
| Multi-Protocol Certification Investment | Reduces HART, Foundation Fieldbus, and IO-Link fragmentation risk for process industry accounts. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with MEMS process engineers, HVAC procurement directors at integrated facility management contractors, pharmaceutical manufacturing plant managers, and semiconductor fab facilities heads with secondary validation through EPA enforcement databases, ECHA REACH substance listings, FDA 510(k) filings, and Taiwan Science Park investment disclosures. Bottom-up sensor shipment estimates triangulate against top-down industrial automation capital expenditure tracking.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with segmentation modeling across technology type, certification tier, end-use industry, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and new construction specification trends, incorporating semiconductor fab cleanroom standards and EU F-Gas Regulation efficiency mandates as demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEMS die supply disruptions and divergent regional clean air enforcement intensity. Practitioners should monitor Taiwan foundry utilization rates and EPA inspection staffing levels for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market