
 Proximity Sensors Market | 2026-2036
Proximity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Proximity Sensors Market Intelligence
Software-defined calibration and predictive maintenance subscriptions is rebalancing how proximity sensor vendors capture lifetime value. OMRON Corporation leverages its factory automation ecosystem to bundle sensor hardware with remote diagnostics platforms. KEYENCE Corporation sustains premium positioning through direct sales teams that control technical consultation channels. SICK AG anchors European industrial accounts with safety-certified photoelectric lines.
Proximity sensors detect object presence or distance through electromagnetic, capacitive, or optical fields without physical contact, typically operating at response times under one millisecond and sensing ranges from fractions of a millimeter to several meters depending on the sensing principle. Their primary purpose spans automated machinery safeguarding, position verification, and process control in continuous manufacturing environments. Inductive sensors dominate metal-detection applications in automotive welding cells where ferrous targets prevail. Photoelectric variants capture the fastest expansion in consumer electronics assembly as miniaturized diffuse-reflective units replace mechanical limit switches. Capacitive sensors retain niche margin pools in liquid-level monitoring and non-metallic material detection where other principles fail.
FDA device regulations and IEC 60947-5-2 proximity switch standards constrain design architectures for healthcare and industrial entrants respectively, while EU machinery directives mandate functional safety ratings that filter out uncertified suppliers. EPA energy efficiency guidelines and OSHA machine guarding rules indirectly stimulate replacement demand as older non-compliant equipment cycles out. Stakeholders must monitor how EU AI Act risk classifications and evolving NHTSA autonomous vehicle sensor requirements reshape certification burdens before committing to next-generation product platforms.
Market Dynamics
The transition from discrete hardware sales to integrated sensing platforms is restructuring how proximity sensor vendors capture value, with software-defined calibration and predictive maintenance subscriptions displacing one-time component transactions across industrial automation accounts.
Growth Catalysts
- EU machinery directives:Functional safety mandates under the Machinery Regulation 2023/1230 are forcing replacement cycles in German automotive assembly lines, creating certified sensor demand that filters out uncertified suppliers.
- Chinese EV battery plants:Gigafactory expansion in Ningbo and Changzhou is absorbing photoelectric proximity sensors for electrode positioning at volumes exceeding traditional automotive demand.
- IEC 60947-5-2 harmonization:Standardized proximity switch testing protocols are reducing certification friction for South Korean semiconductor fabs sourcing from multiple vendor geographies.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing dominance by Chinese state-controlled refineries exposes inductive sensor manufacturers to input cost volatility and export quota disruptions.
- Photoelectric sensing range limitations:Diffuse-reflective variants fail in high-ambient-light conditions, constraining deployment in unshaded outdoor logistics automation without costly protective housing.
- REACH substance restrictions:Candidate list additions for nickel compounds in sensing coils are forcing reformulation of inductive sensor windings with alternative conductive materials.
Strategic Opportunities
- Indian PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly are attracting proximity sensor module investments in Gujarat and Tamil Nadu industrial corridors.
- Edge-AI sensor fusion:Convergence of proximity detection with on-chip neural processing enables predictive collision avoidance in collaborative robot cells without external controller dependency.
- Direct-to-factory digital sales channels:Configurator platforms with parametric search are bypassing traditional distributor markups in Japanese precision equipment procurement, compressing channel economics.
Industry Challenges
- Functional safety engineer scarcity:SIL 2 and SIL 3 certification expertise concentrates in German TÜV-accredited consultants, creating bottlenecks for vendors pursuing machinery directive compliance.
- Legacy PLC integration complexity:Proprietary fieldbus protocols in decade-old automotive welding cells require protocol gateway hardware that degrades proximity sensor response times below specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proximity Sensors Market |
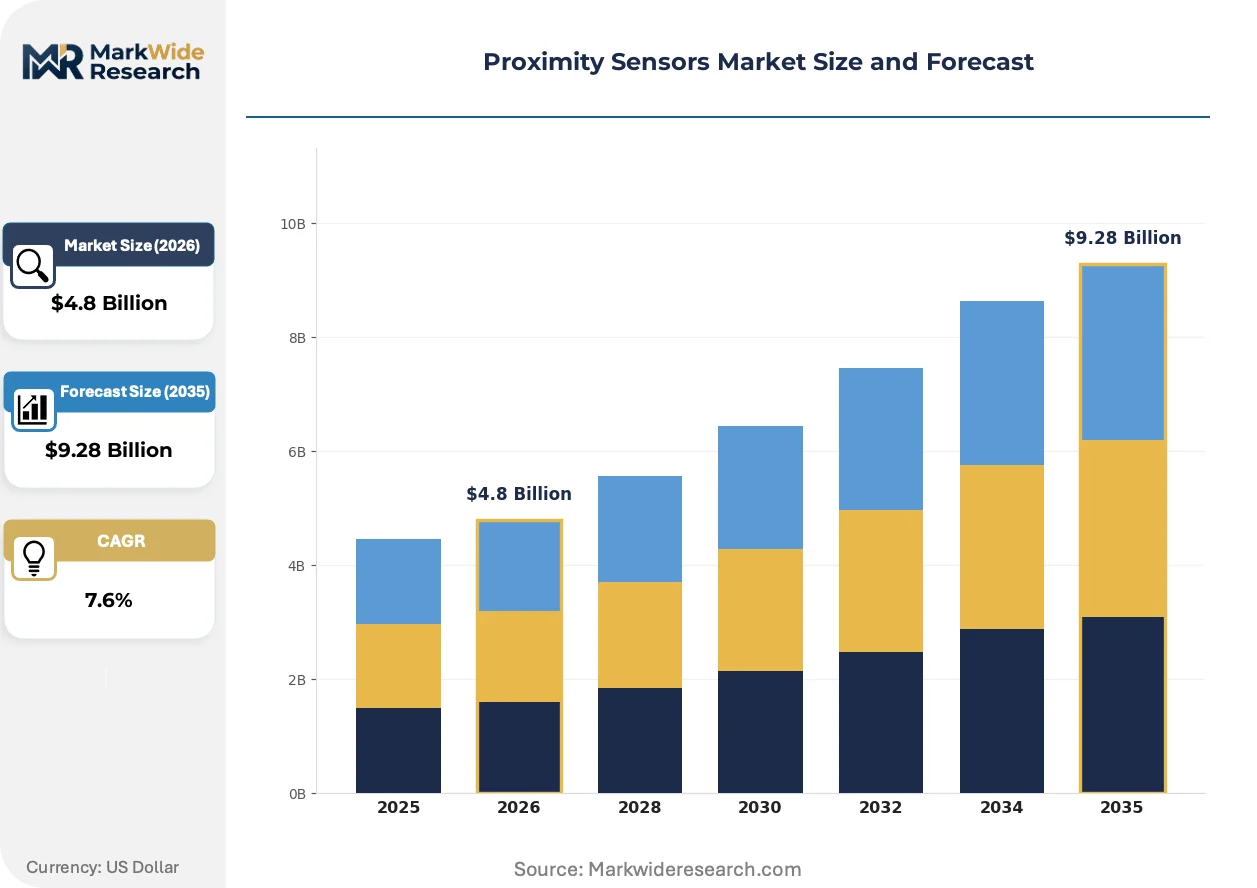
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Ultrasonic Sensors, Inductive Sensors, Photoelectric Sensors Technology: Laser, Infrared, Microwave, Magnetic End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Installation: Surface Mount, Through-Hole, Embedded, Wall-Mounted |
| Companies Covered | OMRON Corporation, KEYENCE Corporation, Panasonic Corporation, SICK AG, STMicroelectronics, Honeywell International Inc., Schneider Electric SE, Rockwell Automation, Pepperl+Fuchs GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proximity Sensors Market Strategic Shifts & Innovations
Time-of-flight photoelectric sensing is displacing traditional diffuse-reflective architectures in precision positioning applications, while regulatory pressure on functional safety certification is compressing vendor qualification timelines across automotive and medical device supply chains.
Time-of-flight proximity sensing is consolidating market share in consumer electronics assembly where sub-millimeter z-height detection determines component placement accuracy. Foxconn and Luxshare production lines in Zhengzhou and Kunshan are standardizing on VCSEL-based modules that eliminate reflectivity-dependent calibration drift. The technology is consolidating what previously required separate laser displacement sensors and photoelectric switches into single-package solutions, compressing bill-of-materials complexity.
The EU AI Act risk classification framework is reshaping proximity sensor deployment in collaborative robotics by mandating documented failure-mode analysis for AI-enabled safety systems. Machinery builders in Stuttgart and Turin must now maintain technical files demonstrating sensor redundancy for high-risk applications. German automotive OEMs are responding by dual-sourcing inductive and capacitive variants for critical axis homing to satisfy conformity assessment body scrutiny.
Subscription-based calibration services are displacing perpetual hardware ownership in Japanese factory automation procurement, with METI's Society 5.0 productivity targets encouraging operational expenditure models. Keyence and Omron direct sales teams are bundling annual sensor health monitoring with replacement guarantees, unbundling the traditional capital equipment purchase. This pattern is most visible in Toyota and Honda tier-one supplier networks where total cost of ownership calculations dominate vendor selection criteria.
Proximity Sensors Market Segmentation
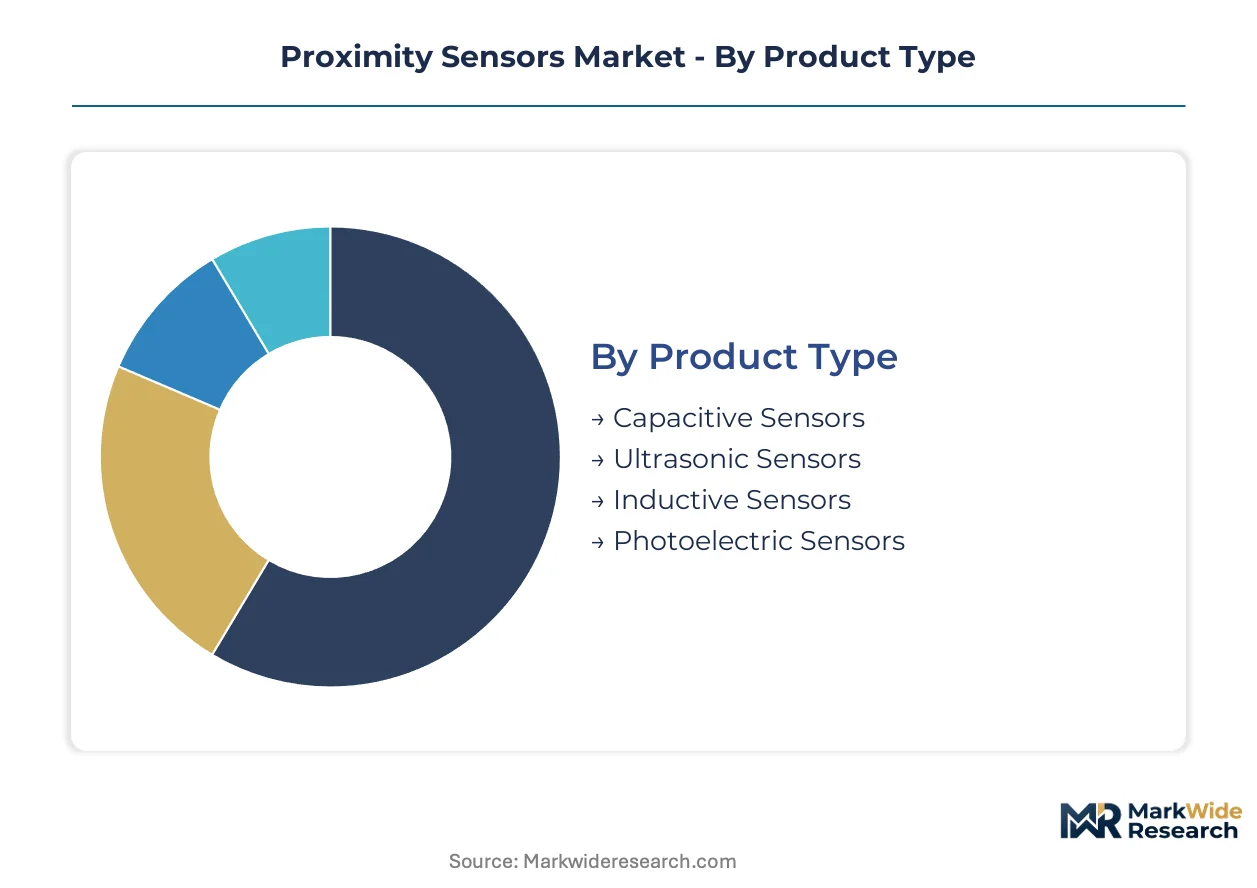
Proximity sensor procurement decisions pivot on detection range, target material compatibility, and integration complexity with existing automation infrastructure. Vendors structure product portfolios across four intersecting dimensions that determine pricing power and replacement cycle frequency.
Product Type:
Application environment dictates sensing principle selection, with target material properties and ambient interference tolerance driving specification choices.
- Inductive Sensors:Electromagnetic field detection of ferrous and non-ferrous metals operates without physical contact at ranges up to 40mm. German automotive welding cells in Wolfsburg and Stuttgart deploy these for tool position verification where metallic debris and weld spatter destroy mechanical alternatives.
- Photoelectric Sensors:Light-beam interruption or reflection architectures span diffuse-reflective, through-beam, and retro-reflective configurations. Chinese EV battery plants in Ningbo absorb these for electrode alignment at volumes exceeding traditional automotive demand, though high-ambient-light conditions constrain unshaded outdoor deployment.
- Capacitive Sensors:Electric field variation detects metallic and non-metallic targets including liquids and powders. These retain margin pools in semiconductor wet-process equipment where liquid-level monitoring requirements exclude inductive alternatives.
- Ultrasonic Sensors:Time-of-flight acoustic pulse measurement enables distance detection regardless of target color or transparency. Japanese precision equipment manufacturers specify these for transparent object detection where photoelectric principles fail.
Inductive variants lead on scale across metalworking automation; photoelectric variants lead on momentum in electronics assembly miniaturization.
Technology:
Emitter-detector pairing determines sensing accuracy, environmental immunity, and cost structure across industrial and consumer applications.
- Laser:Coherent light sources achieve sub-millimeter precision with narrow beam divergence. South Korean semiconductor fabs in Pyeongtaek standardize on VCSEL-based time-of-flight modules for wafer handling positioning that eliminates reflectivity-dependent calibration drift.
- Infrared:Near-infrared LED emitters balance range and cost in diffuse-reflective architectures. These dominate Japanese factory automation procurement where METI productivity targets encourage operational expenditure models bundling sensor health monitoring.
- Microwave:Radar-based detection penetrates dust, steam, and non-metallic materials. These serve niche applications in cement and mining operations where environmental contamination disables optical principles.
- Magnetic:Hall-effect and magnetoresistive detection of magnetic field distortion. These secure safety-critical homing functions in collaborative robot cells subject to EU AI Act risk classification scrutiny.
Infrared deployments retain volume concentration; laser architectures are climbing the fastest on precision electronics assembly demand.
End User:
Industry-specific certification requirements and failure-mode tolerance shape vendor qualification timelines and pricing architecture.
- Industrial Automation:IEC 60947-5-2 compliant proximity switches in continuous manufacturing environments. Functional safety mandates under EU machinery directives force replacement cycles that filter out uncertified suppliers.
- Automotive:Assembly line precision positioning and welding cell safeguarding. German OEMs dual-source inductive and capacitive variants for critical axis homing to satisfy conformity assessment body scrutiny.
- Consumer Electronics:Miniaturized surface-mount units for assembly equipment and device integration. Foxconn production lines in Zhengzhou consolidate previously separate laser displacement and photoelectric functions into single-package VCSEL solutions.
- Healthcare:FDA device regulations constrain design architectures for patient monitoring and diagnostic equipment proximity detection. These applications demand documented failure-mode analysis exceeding industrial certification burden.
Industrial automation commands revenue concentration; consumer electronics shows the steepest expansion trajectory on assembly miniaturization.
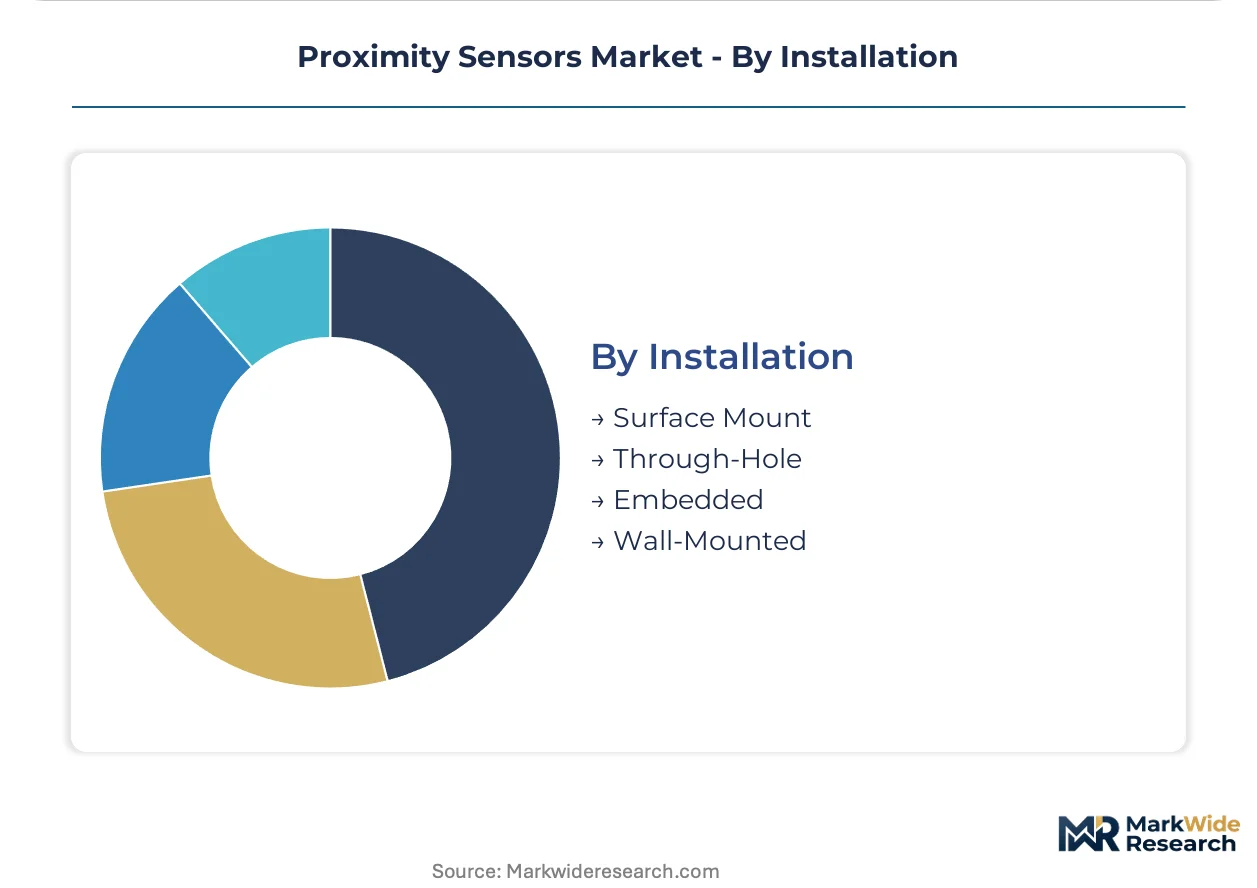
Installation:
Mechanical integration method determines environmental sealing, thermal management, and maintenance accessibility trade-offs.
- Surface Mount:PCB-level integration for compact electronics assembly equipment. These enable dense sensor arrays in semiconductor test handlers where space constraints preclude bulkier alternatives.
- Through-Hole:Pin-through-board mounting for mechanical stability in vibration-prone environments. Automotive powertrain assembly lines specify these for camshaft and crankshaft position sensing.
- Embedded:Sub-surface integration within machinery structures for protected operation. These appear in food processing equipment where washdown requirements mandate sealed housing integration.
- Wall-Mounted:External bracket mounting for field retrofit and accessibility. Logistics automation in European distribution centers favors these for rapid deployment without machinery disassembly.
Surface mount dominates electronics manufacturing procurement; embedded configurations are gaining share fastest on hygienic design requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting proximity sensor production toward jurisdictions with streamlined certification pathways, as EU machinery directives and FDA device regulations impose divergent compliance burdens that reshape manufacturing location decisions.
Germany
Automotive welding cells in Wolfsburg and Stuttgart drive inductive sensor procurement for tool position verification. Machinery Regulation 2023/1230 functional safety mandates force replacement cycles that filter uncertified suppliers from industrial accounts. Bavaria's factory automation corridor concentrates TÜV-accredited certification expertise, creating bottlenecks for vendors pursuing SIL 2 and SIL 3 compliance.
China
EV battery plants in Ningbo and Changzhou absorb photoelectric sensors for electrode positioning at volumes exceeding traditional automotive demand. GB standards and MIIT industrial automation directives shape product certification requirements for domestic and export markets. The Yangtze River Delta electronics manufacturing cluster anchors semiconductor fab equipment procurement, particularly for VCSEL-based time-of-flight modules.
United States
FDA device regulations constrain design architectures for healthcare proximity detection applications exceeding industrial certification burdens. NHTSA autonomous vehicle sensor requirements reshape procurement specifications for automotive tier-one suppliers. The Midwest automotive belt spanning Michigan and Ohio sustains demand for safety-certified photoelectric lines in powertrain assembly.
Japan
METI's Society 5.0 productivity targets encourage operational expenditure models bundling sensor health monitoring with replacement guarantees. Kanto region factory automation procurement favors subscription-based calibration services over perpetual hardware ownership. Toyota and Honda tier-one supplier networks in Aichi Prefecture dominate vendor selection criteria through total cost of ownership calculations.
South Korea
Semiconductor fabs in Pyeongtaek standardize on VCSEL-based time-of-flight modules for wafer handling positioning. MFDS medical device regulations and IEC 60947-5-2 harmonization reduce certification friction for multi-vendor sourcing strategies. The Seoul Capital Area electronics manufacturing cluster concentrates demand for miniaturized surface-mount units in test handler equipment.
Proximity Sensors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in safety-certified industrial automation contrasting fragmented supply in consumer electronics assembly. Japanese and German conglomerates anchor premium tiers through direct sales control, while Chinese module assemblers capture volume in battery plant procurement. Three archetypes dominate: integrated factory automation ecosystem vendors, precision measurement specialists, and component-scale contract manufacturers. Competitive moves concentrate on backward integration into sensing element production and geographic expansion through local certification partnerships.
Within the integrated ecosystem tier, OMRON Corporation exemplifies vendors bundling hardware with remote diagnostics platforms. KEYENCE Corporation occupies a position among direct-sales-controlled technical consultation channels. SICK AG anchors European industrial accounts through safety-certified positioning. These three represent divergent geographic origin strategies—Japanese conglomerate, Japanese precision specialist, and German industrial automation incumbent—each sitting within distinct certification and channel economics.
| Leading Market Players |
|---|
| OMRON Corporation |
| KEYENCE Corporation |
| Panasonic Corporation |
| SICK AG |
| STMicroelectronics |
| Honeywell International Inc. |
| Schneider Electric SE |
| Rockwell Automation |
| Pepperl+Fuchs GmbH |
| Others |
Cost & Logistics Intelligence
German automotive OEM procurement concentration anchors the proximity sensor pricing model around functional safety certification tiers, with Machinery Regulation 2023/1230 compliance requirements stratifying contract values across SIL 2 and SIL 3 qualified suppliers versus uncertified alternatives.
Pricing Analysis
Capacity additions in Chinese EV battery manufacturing are reshaping price floors for photoelectric variants, compressing margins on standard-grade units while premium-tier laser-based time-of-flight modules retain pricing power through South Korean semiconductor fab qualification requirements. Pricing stratifies across premium, standard, and economy tiers based on IEC 60947-5-2 certification level and bundled predictive maintenance subscriptions. Cost compression in infrared diffuse-reflective architectures is intensifying because of module commoditization in Chinese electronics assembly. Japanese factory automation accounts show the lowest price sensitivity due to METI Society 5.0 operational expenditure models, while Indian PLI scheme beneficiaries drive the hardest unit-cost negotiations.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and South Korean semiconductor fabs are fragmenting supplier concentration across China, Japan, and Germany for finished sensor modules. Sensing element production draws from Japanese VCSEL foundries, German inductive coil specialists, and Chinese PCB substrate manufacturers. Rare earth magnet processing in Chinese state-controlled refineries creates single-source vulnerability for inductive sensor magnetic cores. Distribution runs through direct sales teams for premium industrial accounts and electronics component distributors for volume consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
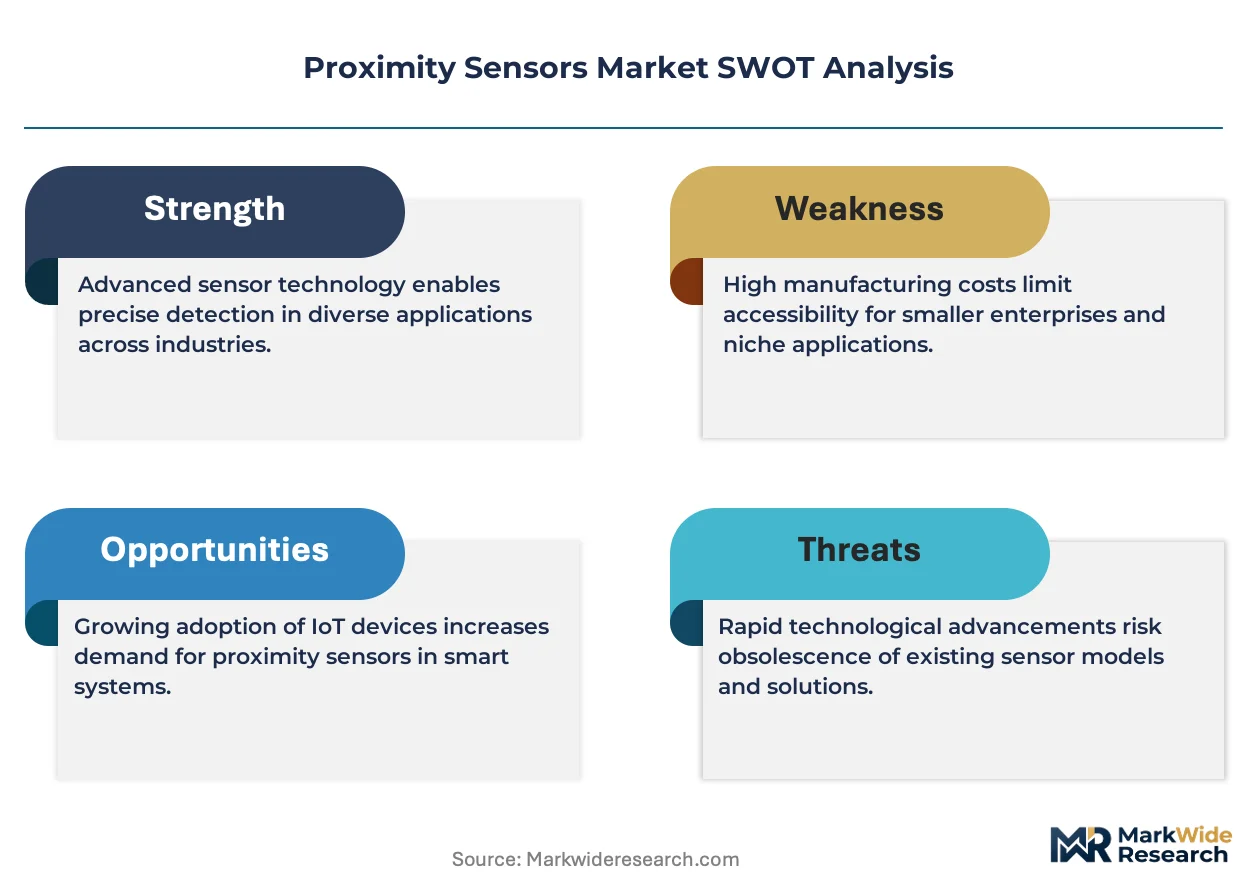
The proximity sensor market functions as a regulatory compounder where EU machinery directives and FDA device regulations continuously refresh replacement demand through compliance-driven obsolescence cycles.
For Market Incumbents: Acquire TÜV-accredited functional safety certification capabilities to defend against emerging Chinese module assemblers with cost advantages but lacking SIL 2 expertise. Deepen backward integration into VCSEL and magnetic sensing element production to reduce exposure to rare earth supply volatility. Channel control through factory automation ecosystem bundling remains the critical lever against pure-play component vendors. For New Entrants and Emerging Players: Capture Indian PLI scheme electronics manufacturing corridors before incumbent certification investments solidify. The most penetrable white space sits in subscription-based calibration services for Japanese precision equipment procurement, where METI Society 5.0 targets encourage operational expenditure shifts. A direct-to-factory digital configurator platform bypassing traditional distributor markups offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Factory automation ecosystem vendors are the most active acquirer in this space, seeking sensing element production capabilities to complete vertical integration. The five-to-ten year viability window favors targets with dual automotive and medical device certification pathways. Watch EU AI Act risk classification implementation timelines as the critical inflection signal for AI-enabled sensor fusion valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | TÜV SIL 2 and SIL 3 accreditation filters uncertified suppliers from German automotive accounts. |
| Backward Integration into Sensing Elements | Captive VCSEL and magnetic core production reduces Chinese rare earth supply exposure. |
| Subscription Service Launch | METI Society 5.0 productivity targets encourage Japanese factory automation operational expenditure models. |
| Direct-to-Factory Digital Channel | Parametric configurator platforms bypass distributor markups in precision equipment procurement. |
| Edge-AI Sensor Fusion Development | EU AI Act risk classifications mandate documented failure-mode analysis for collaborative robotics. |
Research Approach
Multiple input streams — primary interviews with factory automation procurement directors, semiconductor fab equipment engineers, and automotive tier-one supplier quality managers, alongside secondary validation through IEC standards documentation, EU machinery directive filings, and METI industrial automation policy releases — were reconciled through bottom-up and top-down triangulation.
Historical shipment data was cross-referenced against expert panel inputs covering sensing principle, technology emitter type, end-user industry vertical, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with named demand drivers including EU machinery directive replacement cycles and Chinese EV battery plant expansion. Industry-specific forecast inputs incorporated functional safety certification pipeline visibility and rare earth magnet supply quota announcements.
Regulatory implementation delays, rare earth export quota disruptions, and semiconductor capital expenditure cycle turns are the dominant revision risks to modeled outputs. Deviation in EU AI Act enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Thermometer Market