
 Middle East and Africa Temperature Sensors Market | 2026-2036
Middle East and Africa Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Temperature Sensors Market Foresight
REACH compliance is decoupling European-export eligibility from basic component sourcing across Middle East and Africa manufacturing hubs. Texas Instruments leverages its analog portfolio depth to sustain design-win traction in Saudi process automation. Siemens anchors large-scale integrated sensor networks across UAE desalination and district cooling infrastructure. Emerson Electric differentiates through fiber-optic temperature monitoring systems deployed in high-electromagnetic environments across Qatar's liquefied natural gas trains.
Temperature sensors are transducer devices that convert thermal energy into electrical signals through thermoelectric, resistive, or radiative principles, typically operating across ranges from -200°C to 1,700°C depending on sensing element composition. Their primary industrial purpose centers on process control, equipment protection, and regulatory compliance in continuous manufacturing and energy extraction operations. Thermocouples dominate hydrocarbon processing installations where extreme temperatures and vibration tolerance outweigh precision requirements. Smart Sensors represent the fastest-expanding technology category as IIoT architectures proliferate across Middle East industrial zones. RTDs capture premium positioning in pharmaceutical and food-safety applications where ±0.1°C accuracy justifies higher unit costs.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and South African Bureau of Standards (SABS) certification requirements shape product entry protocols across the region's two largest industrial economies. The UAE's Emirates Authority for Standardization and Metrology (ESMA) mandates IEC-compliant electrical safety markings for sensor imports into Dubai and Abu Dhabi free zones. Stakeholders must monitor evolving Gulf Cooperation Council harmonization timelines and local content thresholds that could reroute supply chain configurations without warning.
Market Dynamics
IIoT architecture proliferation across Saudi and UAE industrial zones is compressing replacement cycles for legacy analog sensors, forcing vendors to bundle connectivity modules with thermocouple and RTD hardware to retain specification wins.
Growth Catalysts
- SASO Energy Efficiency Mandates:Saudi Arabia's industrial efficiency regulations compel petrochemical operators to retrofit continuous process monitoring systems, accelerating digital sensor deployment across Jubail and Yanbu corridors.
- Desalination Infrastructure Buildout:UAE district cooling and desalination megaprojects specify fiber-optic temperature monitoring for electromagnetic immunity in high-salinity environments.
- Smart City Specifications:Dubai and Abu Dhabi building automation codes mandate networked temperature sensors for HVAC optimization, creating recurring replacement demand across commercial real estate portfolios.
Market Restraints
- Platinum Price Volatility:RTD sensing elements depend on platinum wire supplies, exposing manufacturers to London Metal Exchange price swings that compress gross margins on precision-grade units.
- Calibration Infrastructure Gaps:South Africa and Nigeria lack ISO 17025-accredited temperature calibration laboratories, forcing end-users to ship sensors to European facilities and extending lead times.
- Optical Pyrometer Substitution:Non-contact infrared thermometers displace contact sensors in steel and cement kiln applications where surface temperature measurement suffices.
Strategic Opportunities
- Qatar LNG Train Expansion:North Field East and West projects require explosion-proof temperature transmitters for cryogenic liquefaction processes, opening specification windows for certified vendors.
- Edge Computing Convergence:On-sensor data processing reduces bandwidth requirements for remote pipeline monitoring, enabling new deployments across Saudi Arabia's Empty Quarter transmission corridors.
- ESMA Cybersecurity Markings:UAE's emerging IoT device certification framework creates first-mover advantage for suppliers pre-integrating secure firmware update capabilities.
Industry Challenges
- Embedded Systems Engineering Scarcity:Firmware development for wireless sensor networks requires specialized talent scarce across Dubai, Riyadh, and Johannesburg technology labor markets.
- IECEx Certification Timelines:Hazardous area equipment approvals for Zone 0 and Zone 1 installations average 14-18 months, delaying revenue recognition for explosion-proof product lines.
- Legacy 4-20mA Integration:Brownfield facilities across Kuwait and Bahrain maintain decades-old control systems incompatible with digital HART or WirelessHART protocols without costly gateway infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Temperature Sensors Market |
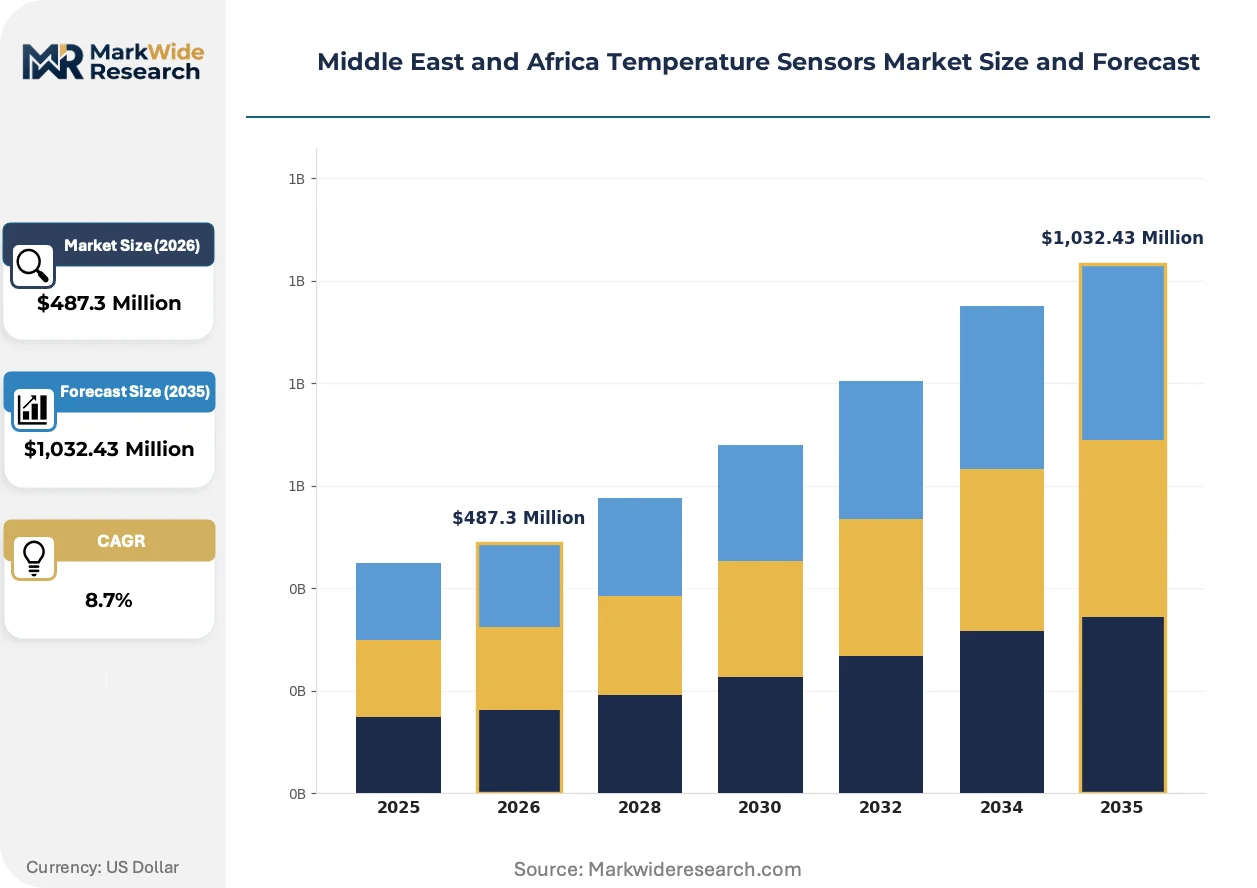
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Thermistors, Infrared Sensors Installation Type: Fixed, Portable, Wireless, Integrated End User: Oil & Gas, Manufacturing, Healthcare, Automotive Technology: Analog, Digital, Fiber Optic, Smart Sensors |
| Companies Covered | Texas Instruments Inc., Siemens AG, TE Connectivity Ltd., Analog Devices Inc., Panasonic Corporation, Emerson Electric Co., Microchip Technology, Inc., Honeywell International, Inc., NXP Semiconductors N.V., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Temperature Sensors Market Shifts & Advancements
Sensor miniaturization and edge intelligence are converging to redefine temperature monitoring architectures across Middle East process industries, compressing the traditional separation between sensing hardware and control systems.
MEMS-based temperature sensors are expanding into wearable industrial safety equipment and drone-mounted pipeline inspection systems. Oilfield services contractors in Saudi Arabia and the UAE are integrating these devices for worker heat-stress monitoring and flare-stack thermal profiling. The technology is expanding into applications previously served by bulkier thermocouple assemblies, reducing payload weight and enabling continuous mobile monitoring.
ESMA's phased implementation of IEC 62443 cybersecurity standards for industrial automation components is reshaping procurement specifications across UAE free zones. Sensor vendors must now submit SBOM documentation and demonstrate secure boot capabilities to qualify for critical infrastructure projects. Process automation buyers in Abu Dhabi's oil concessions are prioritizing pre-certified devices to avoid project delays.
After-sales service unbundling is disrupting traditional channel relationships across the region. End-users in Saudi petrochemical complexes now procure calibration and recertification services separately from hardware, favoring specialized metrology providers over distributor-integrated support. This pattern concentrates most visibly in Jubail Industrial City, where maintenance contractors maintain captive calibration capabilities to reduce downtime.
Middle East and Africa Temperature Sensors Market Segmentation
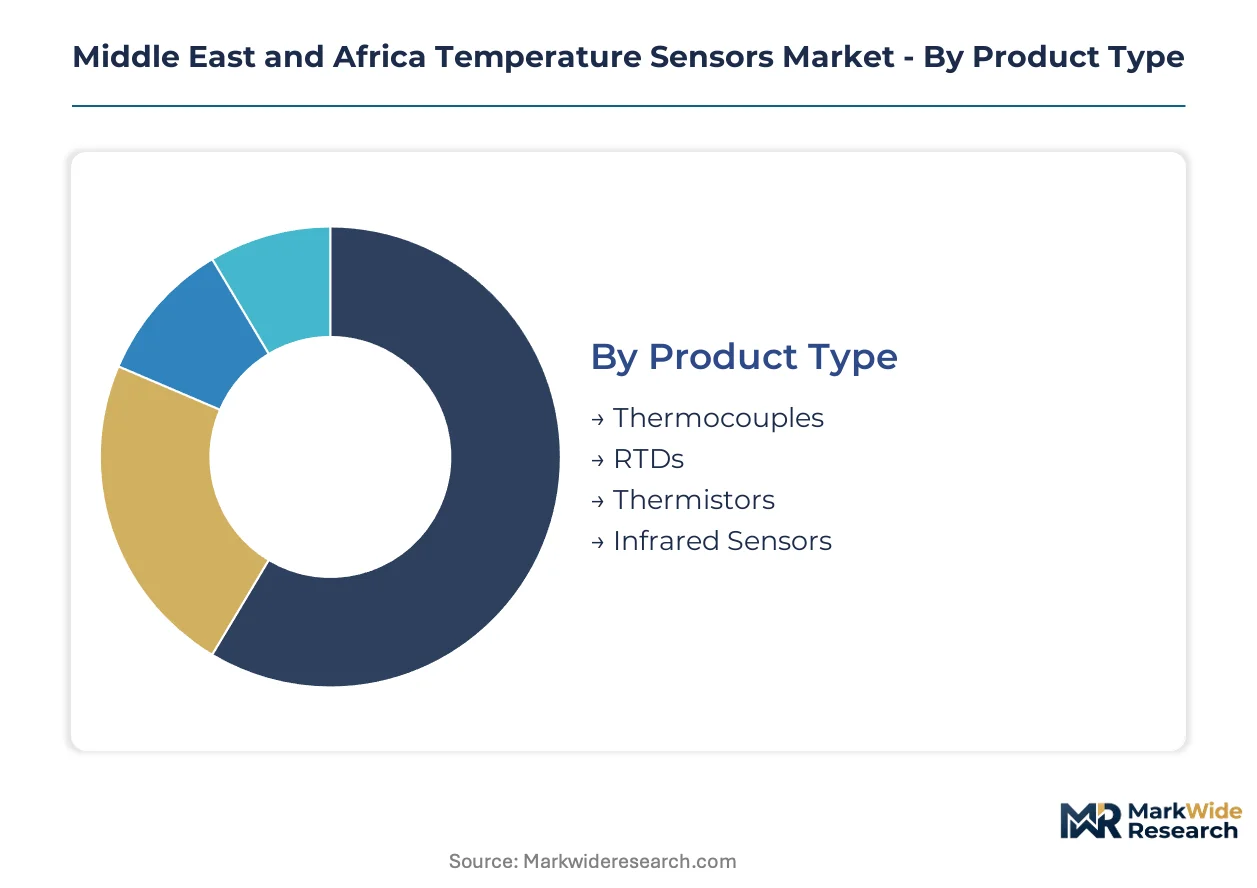
Temperature sensor procurement across Middle East and Africa industrial zones diverges sharply by capital commitment and operational criticality. Segment selection determines total cost of ownership through calibration frequency, replacement cycles, and integration complexity with legacy control architectures.
Product Type:
Capital intensity varies most dramatically in this category, with platinum-dependent RTDs demanding substantially higher upfront material investment than base-metal alternatives.
- Thermocouples:These junction-based sensors pair dissimilar metals to generate millivolt signals proportional to temperature differentials. Demand concentrates in Saudi Aramco's upstream processing facilities and Qatar's LNG liquefaction trains, where vibration tolerance and 1,700°C range capability override precision requirements.
- RTDs:Platinum wire wound or thin-film elements deliver ±0.1°C accuracy through resistance-temperature correlation. UAE pharmaceutical manufacturing and South African food processing facilities specify these for regulatory compliance despite platinum price volatility compressing procurement budgets.
- Thermistors:Ceramic semiconductor elements provide exponential resistance change for narrow-span applications. HVAC contractors in Dubai's commercial real estate sector deploy these for cost-sensitive zone control.
- Infrared Sensors:Non-contact pyrometers measure surface radiation without thermal mass. Steel producers in Egypt and cement kiln operators across North Africa favor these for moving-target measurement.
Most installed capacity flows through thermocouples. Expansion is steepest in infrared sensors.
Installation Type:
Deployment architecture selection tracks the tension between permanent infrastructure investment and operational flexibility requirements across brownfield and greenfield sites.
- Fixed:Hardwired thermowell or surface-mounted installations dominate continuous process applications. Jubail petrochemical corridors and Abu Dhabi oil concessions standardize these for 20-year asset life cycles.
- Portable:Handheld probe configurations serve spot-checking and maintenance verification. Calibration service providers across Johannesburg and Lagos maintain fleets for field audit support.
- Wireless:Battery-powered nodes with mesh networking eliminate cable trenching costs. Saudi Aramco's Empty Quarter pipeline monitoring and UAE smart building retrofits are expanding these deployments.
- Integrated:Sensor-transmitter-control system packages reduce engineering procurement complexity. District cooling authorities in Dubai specify these for turnkey accountability.
Fixed installations retain the largest footprint. Wireless configurations are climbing the fastest.
End User:
Customer-type segmentation reveals diverging specification authority between owner-operators with captive engineering and contractor-driven project procurement.
- Oil & Gas:Upstream, midstream, and downstream operators specify explosion-proof and fiber-optic variants for hazardous area compliance. QatarEnergy's North Field expansions and ADNOC's offshore developments anchor regional demand.
- Manufacturing:Petrochemical, steel, and cement producers balance precision against environmental ruggedness. Saudi SABIC affiliates and Egypt's El Nasr Company drive replacement cycles.
- Healthcare:Cold chain validation and sterilization monitoring require ISO 17025-traceable accuracy. South African hospital networks and UAE pharmaceutical free zones mandate calibrated RTD networks.
- Automotive:Engine monitoring and battery thermal management specifications are emerging. Morocco's vehicle assembly plants and South African OEM tier suppliers represent nascent demand.
Oil and gas commands the dominant share. Healthcare applications are gaining share fastest.
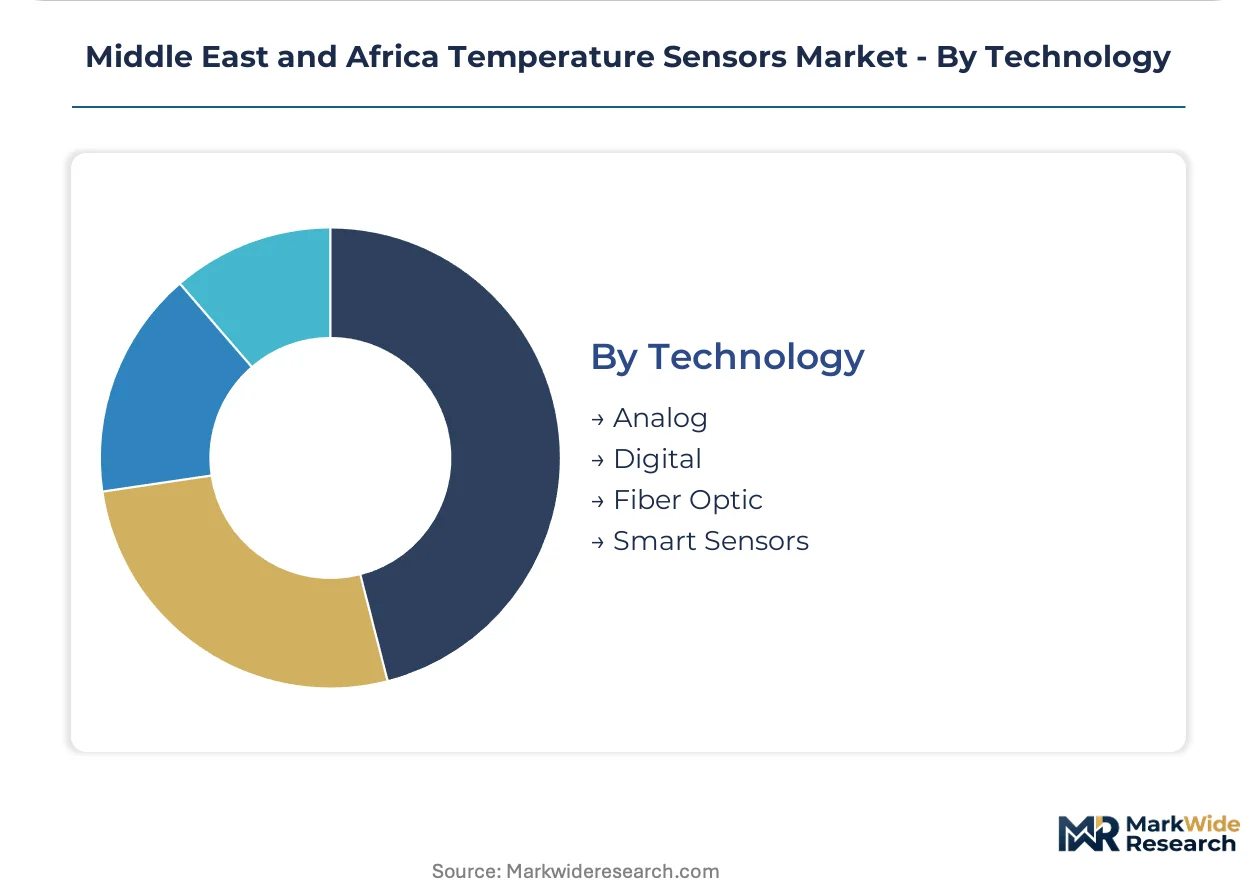
Technology:
Technology tier selection increasingly determines connectivity architecture and cybersecurity posture rather than raw measurement performance.
- Analog:4-20mA and millivolt output signals persist in Kuwaiti and Bahraini brownfield facilities where control system replacement remains capital-constrained.
- Digital:HART and Modbus protocols enable remote configuration and diagnostics. UAE process automation buyers prioritize these for reduced field service costs.
- Fiber Optic:Gallium arsenide or silicon crystal sensing elements immune to electromagnetic interference. Desalination plants across the UAE and high-voltage switchgear applications specify these.
- Smart Sensors:Edge-processing devices with embedded algorithms and wireless stacks. ESMA's emerging cybersecurity mandates are accelerating qualification for UAE critical infrastructure.
Analog technology retains the largest installed base. Smart sensors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process automation engineers and embedded systems specialists cluster in Dubai, Riyadh, and Johannesburg, anchoring technical specification authority for temperature sensor procurement across the region's industrial corridors.
Saudi Arabia
Jubail and Yanbu petrochemical complexes drive thermocouple demand for continuous process monitoring. SASO energy efficiency mandates compel retrofitting of legacy analog systems with digital sensor networks. Aramco's upstream facilities in the Eastern Province specify explosion-proof variants for hazardous area compliance.
United Arab Emirates
Dubai's district cooling megaprojects and Abu Dhabi's desalination infrastructure anchor fiber-optic temperature monitoring deployments. ESMA mandates IEC-compliant electrical safety markings for sensor imports into free zones. Masdar City's smart building codes require networked HVAC sensors with embedded wireless stacks.
Qatar
North Field East and West LNG expansion projects demand cryogenic-rated temperature transmitters for liquefaction trains. QatarEnergy's procurement specifications prioritize IECEx-certified devices for Zone 0 installations. Ras Laffan Industrial City concentrates specification activity for offshore and onshore gas processing.
South Africa
Johannesburg-based mining houses and Cape Town pharmaceutical manufacturers specify RTD networks for regulatory compliance. SABS certification requirements shape product entry protocols for industrial automation components. The country's ISO 17025 calibration infrastructure gaps force sensor shipments to European facilities.
Egypt
El Nasr Company steel operations and Suez Canal industrial zones favor infrared pyrometers for non-contact kiln monitoring. The country's national standards body mandates conformity assessment for imported electrical equipment. Alexandria's cement producers are displacing contact sensors with radiative measurement in high-dust environments.
Middle East and Africa Temperature Sensors Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive semiconductor fabrication. Vendor positioning stratifies across three tiers: integrated automation houses bundling sensors with control systems, component specialists supplying discrete sensing elements, and regional distributors providing calibration and recertification services. Dominant competitive moves include strategic partnerships with national oil companies for specification lock-in and portfolio diversification into edge-computing sensor modules.
Within the integrated automation tier, Siemens AG and Emerson Electric Co. exemplify the control-system-anchored approach. Texas Instruments Inc. represents the semiconductor-origin archetype with analog portfolio depth. TE Connectivity Ltd. occupies a position bridging component supply and system integration. These three patterns—automation integration, chip-level sourcing, and connectivity infrastructure—capture the bulk of specification wins across Saudi and UAE project procurement.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Siemens AG |
| TE Connectivity Ltd. |
| Analog Devices Inc. |
| Panasonic Corporation |
| Emerson Electric Co. |
| Microchip Technology, Inc. |
| Honeywell International, Inc. |
| NXP Semiconductors N.V. |
| Others |
Supply & Pricing Matrix
Sovereign-backed industrial conglomerates across Saudi Arabia and the UAE anchor procurement volumes for temperature sensors, compressing pricing power among component specialists while elevating specification authority for national oil companies and district cooling authorities. Their consolidated buying positions force vendors to unbundle hardware from calibration services, reshaping margin structures across Jubail petrochemical corridors and Dubai smart building projects.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across Middle East and Africa temperature sensor markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service inclusion, with IECEx-certified explosion-proof units commanding substantial premiums over basic thermocouple assemblies. Cost compression in economy-grade analog sensors is intensifying because South African and Nigerian buyers face extended calibration lead times that erode total cost of ownership advantages. Healthcare and pharmaceutical end-users in the UAE exhibit the least price sensitivity, prioritizing ISO 17025-traceable accuracy over procurement savings.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Dubai's Jebel Ali Free Zone and Johannesburg industrial parks, creating hub-and-spoke patterns that feed project sites across the Gulf and sub-Saharan Africa. Manufacturing draws from Germany, the United States, and Japan for precision sensing elements, with platinum wire supplies resting on London Metal Exchange price discovery. Single-source vulnerability in platinum-dependent RTD production exposes margins to commodity volatility. Distribution runs through authorized distributor networks that maintain captive calibration capabilities to satisfy SASO and SABS recertification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification authority is migrating toward buyers demanding embedded cybersecurity and edge-computing capabilities. Premium sensor procurement is displacing basic analog replacements across UAE critical infrastructure.
For Market Incumbents: Deepen backward integration into platinum wire supply arrangements to defend margin positions against London Metal Exchange volatility. Fortify firmware development capabilities in Dubai and Riyadh technology clusters to counter embedded systems engineering scarcity that delays smart sensor deployments. Lock in IECEx certification pre-approvals for Zone 0 installations to accelerate revenue recognition on Qatar LNG expansion specifications. For New Entrants and Emerging Players: The price-point gap between fiber-optic premium tiers and basic thermocouple economy tiers opens specification windows for mid-market digital transmitters with HART protocol compatibility. Wireless sensor networks for Saudi Aramco's Empty Quarter pipeline monitoring represent the most penetrable application segment given brownfield integration challenges facing established vendors. Pursue direct engagement with UAE district cooling authorities seeking turnkey integrated sensor-transmitter packages. For Investors and Strategic Acquirers: Valuations sit cheapest among regional calibration service providers that have unbundled from hardware distribution, capturing recurring revenue streams without platinum price exposure. The five-to-ten year viability framing favors specialists with captive metrology capabilities in Jubail and Ras Laffan industrial zones. Watch ESMA cybersecurity mandate implementation timelines as the inflection indicator for smart sensor qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IECEx Certification Pre-Approval | Compresses 14-18 month hazardous area approval timelines for Qatar LNG specifications. |
| Edge Computing Module Integration | Enables on-sensor data processing for Saudi Aramco's remote pipeline monitoring corridors. |
| Platinum Supply Hedging | Defends gross margins on precision RTD units against London Metal Exchange volatility. |
| Cybersecurity Firmware Pre-Certification | Captures first-mover advantage under ESMA's emerging IoT device certification framework. |
| Calibration Service Captivity | Locks in recurring revenue from Saudi petrochemical operators unbundling hardware from support. |
Research Methodology
Multiple input streams — structured interviews with process automation engineers, primary fieldwork with calibration service providers, and secondary validation through customs and trade databases — were reconciled to construct market estimates. Conversations captured specification authority patterns among Saudi Aramco procurement teams, UAE district cooling authority technical directors, QatarEnergy project engineers, and South African SABS certification officers. Secondary sources included SASO technical regulation filings, ESMA standardization notices, IECEx equipment certification databases, and SEC filings from disclosed market participants. Bottom-up project pipeline enumeration and top-down industrial automation spend allocation were cross-referenced to anchor volume estimates.
Data-stream reconciliation applied across the analysis window employed product-type, installation architecture, end-user industry, and technology tier segmentation to model demand trajectories. CAGRs were derived from fitted growth curves applied to disclosed project timelines and regulatory mandate implementation schedules. Forecast inputs incorporated platinum price trajectory assumptions, Gulf Cooperation Council harmonization timelines, and IIoT architecture deployment velocities across Saudi and UAE industrial zones.
Caveats apply where platinum price spikes, IECEx certification delays, or ESMA cybersecurity mandate acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
China Industrial Sensors Market