
 Roll to Roll Flexible Electronics Market | 2026-2036
Roll to Roll Flexible Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Roll to Roll Flexible Electronics Market Analytics
Automotive OEMs is unwinding legacy rigid PCB procurement patterns as cabin electronics and battery monitoring systems migrate to conformal flexible substrates. DuPont de Nemours Inc. leverages its polymer substrate portfolio to anchor supply relationships with tier-one automotive suppliers. E Ink Holdings Inc. specializes in reflective display modules that compete for dashboard and e-mirror applications. LG Electronics Inc. dominates flexible OLED panel production, sustaining R&D intensity through captive pilot lines in Gumi.
Roll to roll flexible electronics denotes continuous manufacturing of electronic devices on bendable substrates—typically polyethylene naphthalate or polyimide films ranging from 12 to 125 micrometers—via sequential deposition, patterning, and coating processes on web-handling equipment. This architecture enables high-throughput production of circuits that conform to curved surfaces for displays, sensors, and energy harvesting. Flexible Displays captures the largest value pool as smartphone foldable panels and automotive curved screens command premium pricing. Printed Electronics is expanding fastest among technology categories as silver nanoparticle and graphene ink formulations reduce thermal budget constraints. Polymer Substrates retains margin concentration due to limited qualified suppliers capable of dimensional stability at processing temperatures above 150°C.
EPA oversees volatile organic compound emissions from solvent-based conductive ink coating operations, pushing manufacturers toward waterborne and UV-curable formulations. REACH restricts phthalate plasticizers and certain halogenated flame retardants in polymer substrates sold into European consumer electronics and automotive channels. FDA biocompatibility requirements for wearable healthcare patches create a parallel compliance pathway for materials qualification. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking, as these frameworks will soon differentiate market access for substrate and ink suppliers.
Market Dynamics
Automotive OEM procurement of conformal sensor arrays is compressing qualification timelines for polymer substrate suppliers, forcing simultaneous compliance with REACH material disclosure and NHTSA reliability standards.
Growth Catalysts
- Foldable Display Penetration:Smartphone manufacturers in South Korea are expanding captive pilot line capacity for flexible OLED panels, pulling upstream demand for polyethylene naphthalate films.
- REACH Compliance Deadlines:ECHA disclosure requirements for halogenated flame retardants are accelerating qualified supplier consolidation among European automotive tier-ones.
- Solvent-to-Waterborne Ink Transition:EPA volatile organic compound rules are redirecting conductive ink formulation R&D toward UV-curable silver nanoparticle systems.
Market Restraints
- Dimensional Stability Thresholds:Polyimide suppliers capable of maintaining flatness above 150°C processing temperatures number fewer than six globally, concentrating margin capture.
- Silver Price Volatility:Conductive ink formulations remain exposed to precious metal commodity swings, compressing gross margins for printed electronics specialists.
- Rigid PCB Substitution Inertia:Industrial automation and legacy automotive modules retain entrenched supply contracts with fiberglass-epoxy substrate providers.
Strategic Opportunities
- Healthcare Wearable Biocompatibility:FDA Class II pathway for epidermal patches creates parallel materials qualification demand distinct from consumer electronics specifications.
- EU Green Deal Embodied Carbon Tracking:Substrate suppliers with verified lifecycle data will secure preferential access to European automotive and consumer electronics channels.
- Graphene Ink Convergence:Hybrid formulations combining carbon allotropes with metallic conductors are opening thermal budget relief for temperature-sensitive polymer webs.
Industry Challenges
- Process Engineer Scarcity:Web-handling expertise spanning roll-to-roll coating, tension control, and in-line metrology remains concentrated among veterans of display panel manufacturing.
- Dual Certification Timelines:Simultaneous automotive AEC-Q200 and medical ISO 13485 qualification cycles extend product launch windows by 18-24 months.
- Legacy Equipment Retrofit Costs:Converting rigid PCB fabrication lines to flexible substrate handling requires capital outlays for tension-controlled unwind/rewind systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll to Roll Flexible Electronics Market |
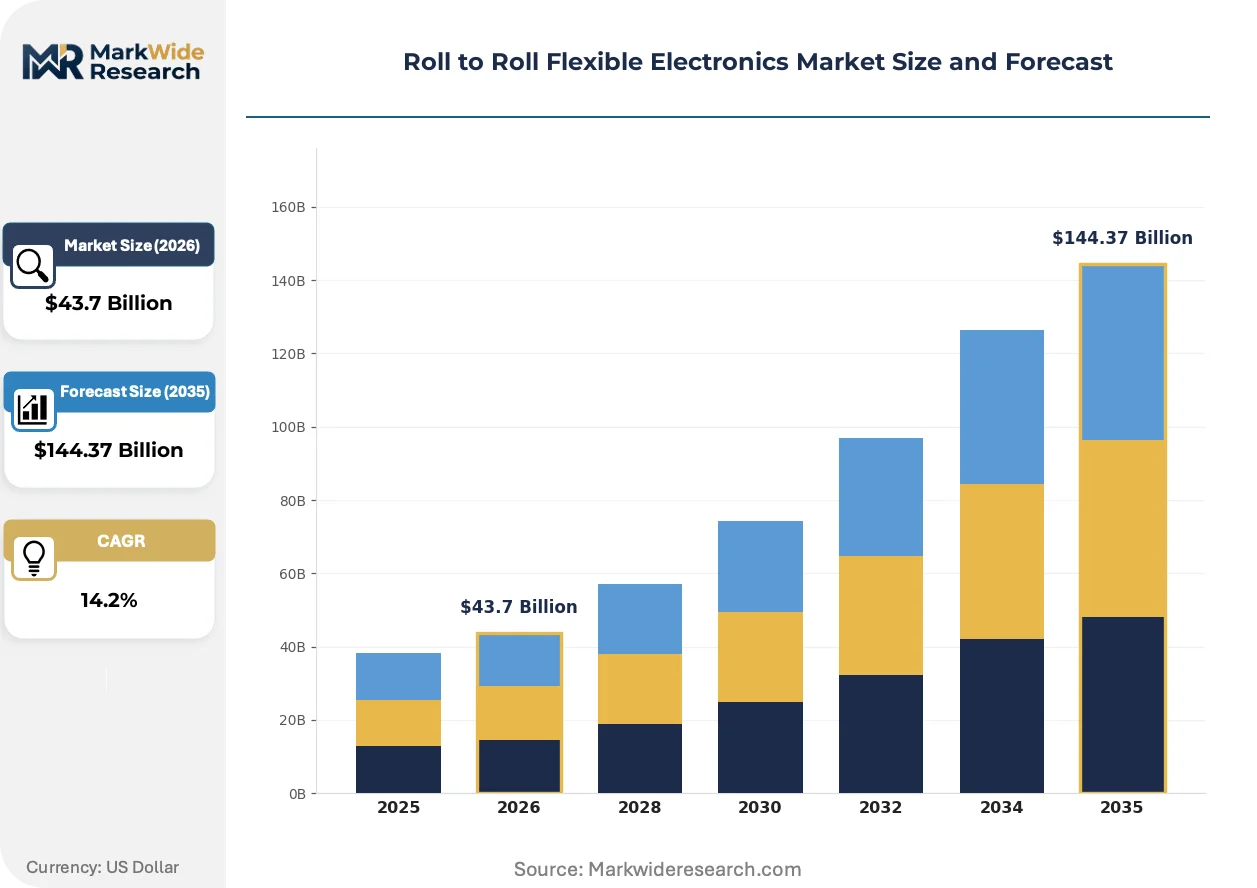
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $144.37 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Wearable Devices, Smart Packaging, Solar Cells, Flexible Displays Material Type: Polymer Substrates, Metal Films, Conductive Inks, Adhesives End User: Consumer Electronics, Automotive, Healthcare, Military Technology: Printed Electronics, Organic Electronics, Nanoelectronics, Thin-Film Processing |
| Companies Covered | LG Electronics Inc., E Ink Holdings Inc., 3M Co., Nissha Co. Ltd., Fujikura Co. Ltd., DuPont de Nemours Inc., Sumitomo Electric Industries, Applied Materials Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll to Roll Flexible Electronics Market Evolving Landscape
Silver nanoparticle ink deposition is fragmenting into divergent technical approaches as end-use thermal budgets tighten and regulatory solvent restrictions harden across manufacturing geographies.
Photonic curing systems for metallic inks are bifurcating the printed electronics equipment market. Display panel makers in Gumi and Shenzhen are installing pulsed-light systems capable of sintering conductive traces in milliseconds without substrate thermal damage. This flash-anneal capability is compressing the addressable market for conventional thermal oven lines while expanding design freedom for heat-sensitive polymer films below 50 micrometers.
REACH restrictions on phthalate plasticizers and halogenated flame retardants are forcing substrate compounders to reformulate dimensional stabilizers. European automotive electronics suppliers now face mandatory material disclosure thresholds for substances of very high concern. Korean display material providers are responding by accelerating bio-based polyimide development to preempt EU market access barriers.
Automotive procurement teams are consolidating flexible sensor array suppliers under long-term capacity reservation contracts. Tier-one cabin electronics integrators in Germany and Japan are shifting from spot purchasing to multi-year substrate volume commitments with penalty clauses for qualification delays. This contract restructuring is most visible in battery monitoring system applications where conformal flexible circuits displace wire harnesses.
Roll to Roll Flexible Electronics Market Segmentation
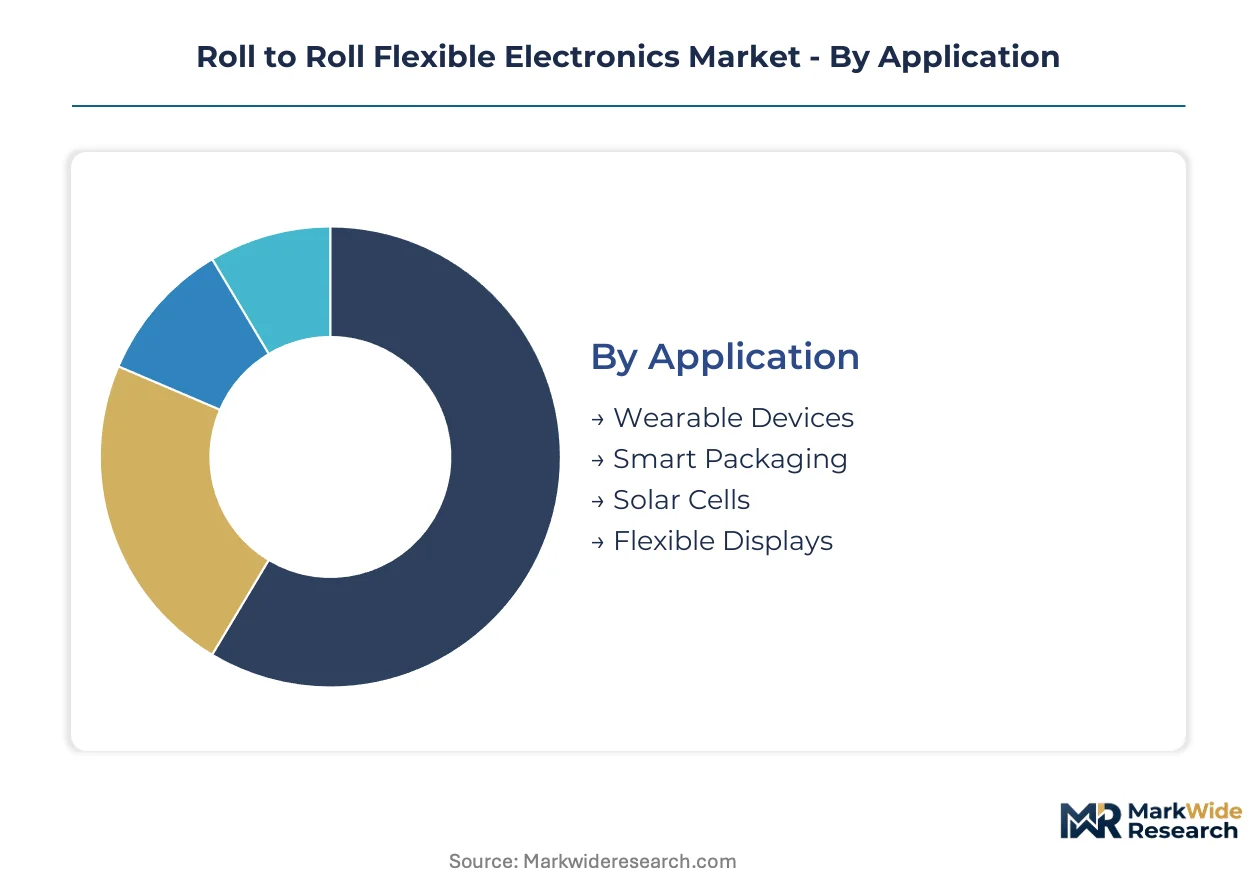
Segmentation in roll-to-roll flexible electronics reveals how substrate specifications, deposition techniques, and end-use reliability requirements create distinct procurement channels. Material thermal budgets and regulatory compliance thresholds fragment supplier relationships across automotive, healthcare, and consumer verticals.
Application:
Wearable Devices and Smart Packaging face intensifying substitution pressure from rigid PCB alternatives as cost-sensitive consumer OEMs weigh flexibility premiums against assembly yields.
- Flexible Displays:Polyethylene naphthalate and polyimide films ranging 12-125 micrometers enable curved automotive screens and foldable smartphone panels. South Korean display makers anchor regional capacity expansion, pulling demand for ultra-thin substrates with dimensional stability above 150°C processing temperatures.
- Wearable Devices:Epidermal patches and fitness monitors require FDA biocompatibility pathways for polymer substrates, creating qualification barriers distinct from consumer electronics specifications. Healthcare OEMs in the United States prioritize ISO 13485-certified suppliers for long-term adhesive interfaces.
- Smart Packaging:RFID-enabled labels and temperature-logging logistics tags deploy printed antenna structures on low-cost polyethylene terephthalate webs.
- Solar Cells:Copper indium gallium selenide and perovskite photovoltaic layers on flexible foils target building-integrated and portable power applications.
Flexible Displays retains volume leadership; Smart Packaging holds the steepest expansion curve.
Material Type:
Cost tier stratification separates qualified automotive-grade substrates from commodity packaging films, with thermal stability thresholds determining margin capture.
- Polymer Substrates:Polyimide suppliers capable of maintaining flatness above 150°C number fewer than six globally, concentrating margin capture among Japanese and Korean compounders. REACH restrictions on phthalate plasticizers and halogenated flame retardants force reformulation of dimensional stabilizers for European automotive market access.
- Conductive Inks:Silver nanoparticle and graphene formulations are displacing solvent-based systems as EPA volatile organic compound rules redirect R&D toward UV-curable deposition. Waterborne ink transitions compress gross margins for printed electronics specialists exposed to precious metal commodity swings.
- Metal Films:Sputtered copper and aluminum layers provide electromagnetic shielding and busbar conductivity for display driver circuits.
- Adhesives:Pressure-sensitive and thermally conductive bonding layers enable multilayer lamination of sensor arrays and barrier films.
Polymer Substrates commands the premium pricing tier; Conductive Inks is gaining share fastest through formulation substitution.
End User:
Customer type divergence separates long-term automotive capacity reservation contracts from spot purchasing patterns in consumer electronics procurement.
- Automotive:Tier-one cabin electronics integrators in Germany and Japan are consolidating flexible sensor array suppliers under multi-year volume commitments with penalty clauses for qualification delays. Battery monitoring systems and conformal interior surfaces displace wire harnesses and rigid PCB assemblies.
- Consumer Electronics:Smartphone and tablet OEMs drive foldable display penetration, with procurement concentrated among South Korean panel makers sustaining R&D intensity through captive pilot lines in Gumi.
- Healthcare:FDA Class II pathway requirements for wearable patches create parallel materials qualification demand, extending product launch windows by 18-24 months for dual-certified suppliers.
- Military:Ruggedized flexible circuits for avionics and soldier-worn systems emphasize shock tolerance and extended temperature operation.
Automotive anchors the highest contract values; Healthcare is climbing the fastest as biocompatibility specifications proliferate.
Technology:
Process maturity separates high-volume printed electronics from emerging nanoelectronics approaches still scaling deposition uniformity across web widths.
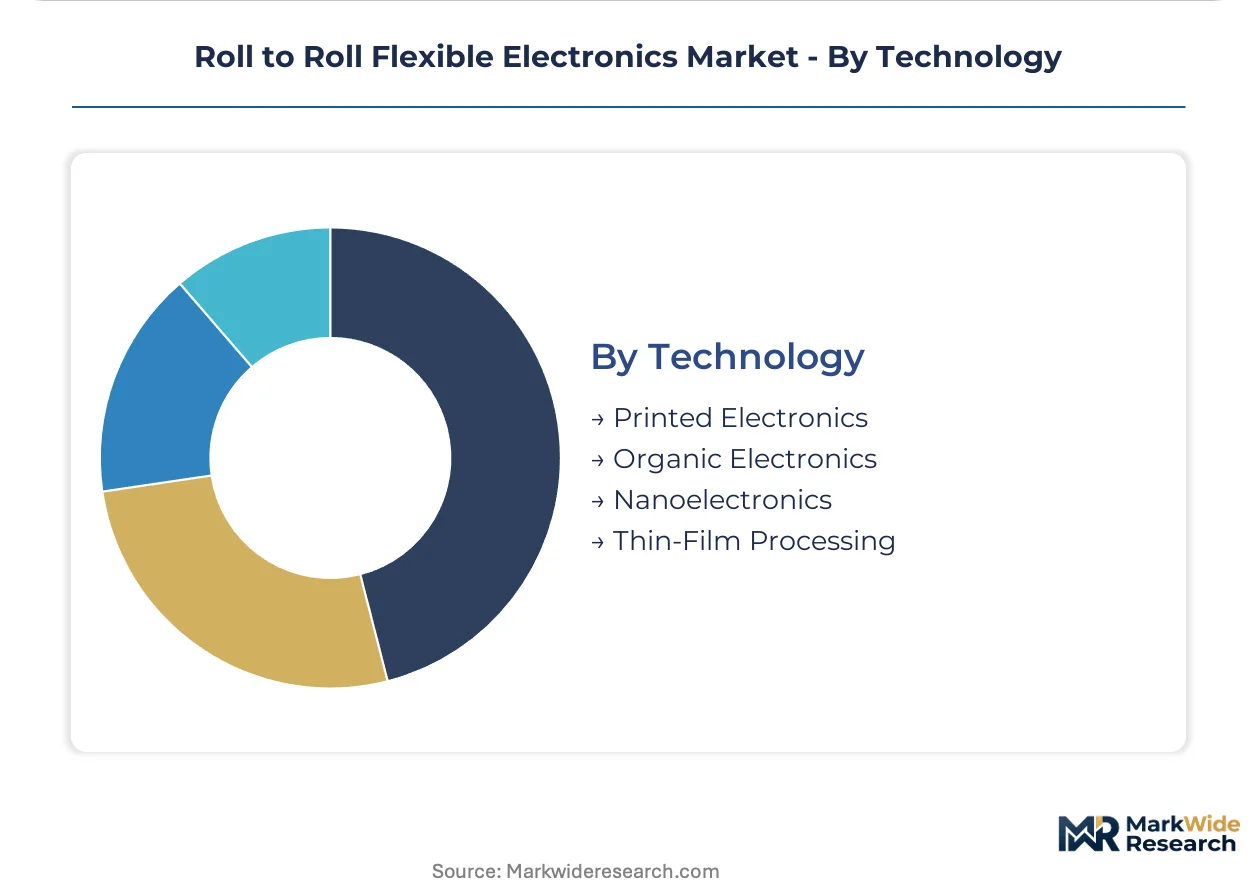
- Printed Electronics:Roll-to-roll gravure and inkjet deposition of metallic and carbon-based conductors enable high-throughput antenna, sensor, and interconnect production. Photonic curing systems in Gumi and Shenzhen sinter traces in milliseconds without thermal damage to polymer webs below 50 micrometers.
- Thin-Film Processing:Chemical vapor deposition and atomic layer deposition create hermetic barrier layers for organic light-emitting diode encapsulation, with equipment concentrated among display panel manufacturing veterans.
- Organic Electronics:Solution-processed semiconductors target low-cost logic and memory for disposable sensor applications.
- Nanoelectronics:Carbon nanotube and graphene channel transistors remain in pilot-scale demonstration for flexible radio-frequency identification and sensing.
Printed Electronics dominates current installed capacity; Thin-Film Processing is expanding most quickly through display maker capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams in Germany and South Korea are consolidating flexible sensor array suppliers under multi-year capacity reservation contracts. Tier-one cabin electronics integrators in Japan and tier-one display panel makers in Gumi anchor regional demand concentration. Chinese waterborne ink specialists and American polymer compounders compete for qualification slots in divergent regulatory environments.
South Korea
Display panel makers in Gumi sustain captive pilot line capacity for flexible OLED substrates, pulling polyethylene naphthalate demand from Japanese compounders. MFDS biocompatibility pathways for wearable healthcare patches run parallel to consumer electronics specifications. Seoul Capital Area concentration of roll-to-roll coating equipment vendors supplies tension-controlled web handling systems across Asia-Pacific.
Germany
Tier-one automotive electronics integrators in Bavaria and Baden-Württemberg are shifting from spot purchasing to multi-year substrate volume commitments with penalty clauses. REACH disclosure requirements for halogenated flame retardants accelerate qualified supplier consolidation among cabin electronics suppliers. Stuttgart industrial cluster hosts precision coating equipment manufacturers serving European automotive qualification timelines.
United States
FDA Class II pathway requirements for epidermal healthcare patches extend materials qualification windows by 18-24 months for dual-certified suppliers. EPA volatile organic compound rules redirect conductive ink R&D toward UV-curable silver nanoparticle systems. California and Texas concentration of printed electronics specialists supplies antenna and sensor arrays for logistics and defense applications.
Japan
Polyimide compounders capable of maintaining dimensional stability above 150°C processing temperatures concentrate margin capture among fewer than six qualified suppliers. METI industrial standards for flexible electronics manufacturing equipment shape regional equipment vendor specifications. Nagoya industrial corridor hosts thin-film deposition equipment makers serving display panel manufacturing veterans.
China
Dual carbon goals and embodied carbon tracking frameworks differentiate market access for substrate and ink suppliers into European automotive channels. Shenzhen and Suzhou industrial clusters install photonic curing systems capable of sintering conductive traces without thermal damage to polymer webs below 50 micrometers. MIIT standards for flexible display manufacturing equipment accelerate domestic equipment vendor qualification.
Roll to Roll Flexible Electronics Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates and specialized display material providers. Market structure concentrates margin capture among qualified polymer substrate suppliers with automotive and medical dual-certification capabilities. Three archetypes dominate: Korean-Japanese display panel integrators with captive substrate supply, American-European chemical conglomerates with polymer formulation depth, and specialized printed electronics equipment vendors with photonic curing expertise. Competitive moves center on multi-year capacity reservation contracts with automotive tier-ones and simultaneous REACH-FDA qualification cycles for healthcare wearable applications.
Within the diversified chemical conglomerate tier, DuPont de Nemours Inc. and BASF SE occupy positions anchored by polymer substrate formulation portfolios and REACH-compliant material disclosure systems. Among specialized display material providers, LG Electronics Inc. and E Ink Holdings Inc. exemplify the Korean-Taiwanese concentration of flexible panel and reflective display module production. Japanese industrial conglomerates including Fujikura Co. Ltd. and Sumitomo Electric Industries represent the precision coating and interconnect cable expertise that supplies automotive conformal circuit applications. These named entities serve as archetype anchors for understanding how geographic origin and corporate structure shape competitive positioning in qualification-intensive procurement channels.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| E Ink Holdings Inc. |
| 3M Co. |
| Nissha Co. Ltd. |
| Fujikura Co. Ltd. |
| DuPont de Nemours Inc. |
| Sumitomo Electric Industries |
| Applied Materials Inc. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Ninety-day qualification timelines for automotive-grade polyimide substrates compress inventory turns and amplify pricing power for the fewer than six qualified suppliers capable of dimensional stability above 150°C. This lead-time compression concentrates margin capture among Japanese and Korean compounders while forcing tier-one automotive integrators into multi-year capacity reservation contracts with penalty clauses for delivery failures.
Pricing Analysis
Second-generation photonic curing equipment commands a 40-50% premium over conventional thermal oven lines, while legacy solvent-based conductive ink formulations trade at discount to waterborne and UV-curable silver nanoparticle systems. Three-tier pricing structure across automotive-qualified, medical-certified, and consumer-grade substrate tiers reflects divergent compliance burdens, with REACH disclosure requirements and FDA biocompatibility pathways adding qualification cost layers. Pricing pressure stems from silver commodity volatility compressing gross margins for printed electronics specialists. Consumer electronics OEMs exhibit highest price sensitivity, prioritizing cost-per-unit over thermal performance, while automotive procurement teams absorb premiums for AEC-Q200 reliability certification.
Supply Chain Analysis
Strategic stockpiling of polyethylene naphthalate films prevails among South Korean display panel makers, contrasting with just-in-time inventory discipline at European automotive tier-ones constrained by REACH material disclosure deadlines. Supply concentrates in Japan, South Korea, and Germany for qualified polymer substrates, with Chinese waterborne ink specialists and American polymer compounders competing for secondary qualification slots. Silver nanoparticle inks, polyimide films, and photonic curing equipment constitute critical input dependencies. Single-source vulnerability pervades the sub-50 micrometer substrate tier where qualified web-handling equipment vendors number fewer than ten globally. Distribution runs through direct long-term contracts with automotive OEMs and spot purchasing channels for consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roll-to-roll flexible electronics represents a high-growth disruption as photonic curing technology collapses thermal budgets and REACH compliance deadlines force supplier consolidation across European automotive channels.
For Market Incumbents: Fortify supply relationships through captive pilot line investments in Gumi and multi-year capacity reservation contracts with German and Japanese automotive tier-ones. Deepen backward integration into bio-based polyimide development to preempt EU market access barriers from ECHA restrictions on halogenated flame retardants. Prioritize simultaneous AEC-Q200 and ISO 13485 qualification cycles to capture healthcare wearable demand without surrendering automotive positioning. For New Entrants and Emerging Players: Differentiate on waterborne ink formulation expertise to exploit EPA volatile organic compound rule enforcement redirecting procurement from solvent-based systems. Target FDA Class II epidermal patch applications where 18-24 month qualification windows deter incumbent resource allocation. Pursue graphene-silver hybrid ink development for thermal budget relief in temperature-sensitive polymer web applications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core flexible electronics material portfolios amid restructuring pressures. Five-to-ten year viability hinges on dual-certification capabilities spanning automotive reliability and medical biocompatibility. Monitor photonic curing equipment installation announcements in Shenzhen and Gumi as inflection indicators for substrate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Curing Equipment Deployment | Pulsed-light systems in Gumi and Shenzhen sinter traces without thermal damage to sub-50 micrometer polymer webs. |
| Dual Certification Investment | Simultaneous AEC-Q200 and ISO 13485 qualification opens automotive and healthcare procurement channels for substrate suppliers. |
| Waterborne Ink Formulation Pivot | EPA volatile organic compound rules redirect R&D toward UV-curable silver nanoparticle systems displacing solvent-based alternatives. |
| Bio-Based Polyimide Development | Korean compounders accelerate development to preempt EU market access barriers from REACH restrictions on halogenated flame retardants. |
| Long-Term Capacity Reservation Contracts | German and Japanese tier-ones shift from spot purchasing to multi-year volume commitments with penalty clauses for qualification delays. |
Research Methodology
A standing panel of roll-to-roll coating equipment vendors, automotive tier-one procurement directors, display panel manufacturing engineers, and polymer substrate compounders provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, customs and trade data, EPA enforcement records, and ECHA substance registration databases. Bottom-up demand modeling from individual application segments triangulated against top-down industry capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across application type, material grade tier, end-user industry, and deposition technology complexity. CAGRs derived from installed capacity trajectories, equipment vendor order backlogs, and automotive platform electrification roadmaps. Industry-specific forecast inputs incorporated photonic curing adoption curves and REACH compliance deadline impacts on supplier consolidation.
Material uncertainties — silver commodity price spikes, regulatory enforcement intensity variations, and equipment vendor delivery delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding qualification timeline stability and automotive procurement pattern continuity. Revision becomes warranted when photonic curing equipment installation rates or REACH substance restriction expansions cross threshold magnitudes that alter supplier competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market