
 Europe Wireless Sensors Market | 2026-2036
Europe Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Sensors Market Foresight
Germany's industrial sensor manufacturing corridor is reshaping supply dynamics for wireless sensing hardware across Europe. Honeywell International Inc leverages its automation heritage to anchor premium positioning in process control applications. Siemens AG competes through deep vertical integration into industrial IoT platforms that bundle wireless sensor networks with edge analytics. Bosch Sensortec GmbH specializes in MEMS-based miniature sensors that dominate wearable device and automotive cabin monitoring segments.
Europe wireless sensors are self-contained measurement devices that transmit data via radio frequency protocols without physical cabling, typically operating on coin-cell batteries with power budgets below 100 milliwatts and designed for 5-10 year field lifespans in ambient conditions from minus 40 to 85 degrees Celsius. Their primary purpose is enabling distributed real-time monitoring in locations where wired infrastructure proves economically unfeasible or physically impractical. Temperature sensors and pressure sensors command the largest installed base in legacy industrial settings where retrofit economics favor wireless over conduit replacement. LoRaWAN technology represents the fastest-expanding protocol layer for agricultural and environmental monitoring applications requiring kilometer-range transmission at sub-gigahertz frequencies with minimal power draw.
CE marking under the EU Radio Equipment Directive and REACH chemical substance restrictions govern hardware composition and electromagnetic compatibility for all wireless sensors sold within the European Economic Area. The EU AI Act's risk classification framework will increasingly shape demand for sensor data governance architectures in healthcare and critical infrastructure deployments. Germany's KBA and France's ANSM are tightening type-approval requirements for automotive and medical wireless sensing applications respectively. Stakeholders must monitor evolving cybersecurity certification schemes under the EU Cyber Resilience Act as these will determine market access eligibility for connected sensor products before the decade's midpoint.
Market Dynamics
LoRaWAN protocol maturation is compressing deployment timelines for kilometer-range sensing networks, forcing legacy proprietary RF systems into obsolescence across German automotive plants and Nordic municipal infrastructure.
Growth Catalysts
- EU Green Deal digitalization mandates:Industrial facility operators must install continuous emissions and energy monitoring systems, creating hardware pull for battery-powered temperature and pressure sensors in German manufacturing corridors.
- France's ANSM medical device connectivity guidelines:Remote patient monitoring programs are expanding reimbursement eligibility for wireless vital sign sensors in hospital-at-home deployments.
- MEMS fabrication scaling:Bosch Sensortec's captive wafer capacity is driving unit cost reductions for miniature accelerometers and gyroscopes destined for automotive cabin monitoring and wearable health devices.
Market Restraints
- Coin-cell lithium supply concentration:Battery chemistry constraints and raw material sourcing bottlenecks from East Asian refiners are extending lead times for 10-year field-life power modules.
- Sub-gigahertz spectrum licensing fragmentation:National frequency allocation mismatches across EU member states complicate cross-border sensor network deployments for logistics and agricultural monitoring.
- Wired industrial instrumentation substitution:Greenfield process plants in established automation clusters still favor cabled 4-20mA loops for critical control points where wireless reliability remains unproven.
Strategic Opportunities
- Polish industrial modernization programs:EU cohesion fund infrastructure investments are creating first-mover advantages for LoRaWAN-enabled predictive maintenance networks in Silesian mining and steel operations.
- EU Cyber Resilience Act pre-certification:Early compliance with forthcoming connected device security standards will unlock preferential positioning in healthcare and critical infrastructure procurement pipelines.
- Edge-AI sensor fusion architectures:Convergence of on-device machine learning inference with ultra-low-power microcontrollers is enabling new application categories in acoustic anomaly detection and vibration signature analysis.
Industry Challenges
- RF engineering talent scarcity:Specialized antenna design and protocol stack optimization skills are concentrated among a small pool of experienced practitioners, inflating compensation costs for product development teams.
- REACH substance restriction compliance:Reformulation of solder alloys and PCB substrates to eliminate restricted chemicals is forcing supply chain requalification cycles that delay new product introductions.
- Legacy SCADA integration complexity:Brownfield industrial sites require costly protocol gateway infrastructure to bridge proprietary wireless sensor networks with decades-old distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Sensors Market |
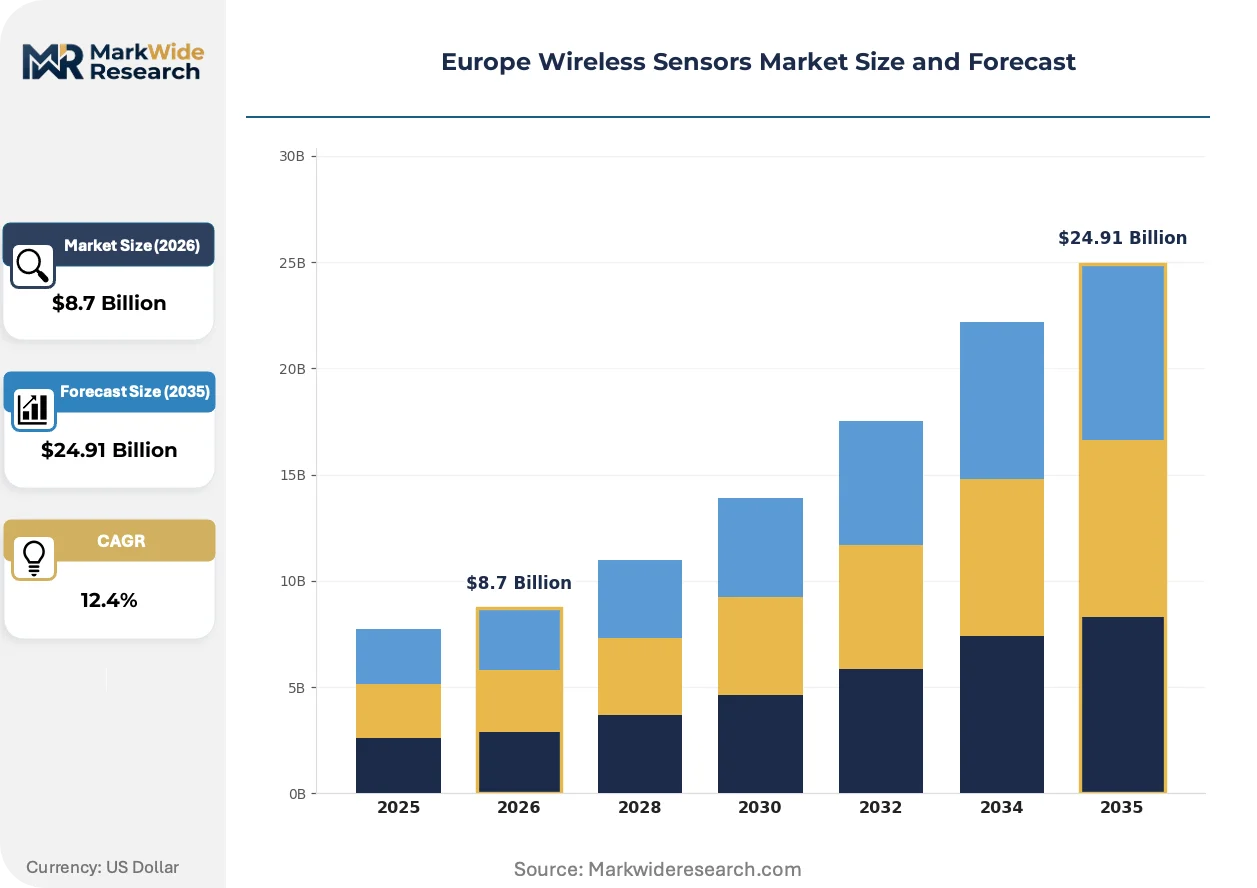
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Humidity Sensors, Pressure Sensors, Proximity Sensors Technology: Bluetooth, Zigbee, Wi-Fi, LoRaWAN End User: Healthcare, Agriculture, Industrial Automation, Smart Homes Application: Environmental Monitoring, Asset Tracking, Smart Metering, Wearable Devices |
| Companies Covered | Honeywell International Inc, Emerson Electric Co, Schneider Electric, Siemens AG, ABB Ltd, Texas Instruments Incorporated, TE Connectivity Ltd, Infineon Technologies AG, Bosch Sensortec GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Sensors Market Shifts & Advancements
Digital twin architectures are driving demand for higher-fidelity, lower-latency sensor feeds that traditional polling-based data collection cannot satisfy. This pressure is reshaping hardware design priorities and network topology choices across European industrial verticals.
Software-defined radio modules with reprogrammable protocol stacks are virtualizing hardware functions that previously required dedicated transceiver chips. German automotive suppliers are adopting these flexible RF platforms to future-proof sensor designs against evolving regional frequency regulations. The technology is virtualizing the traditional boundary between hardware and firmware, collapsing SKU proliferation and simplifying inventory management for multi-market product lines.
REACH chemical substance restrictions are tightening disclosure requirements for battery electrolytes and PCB flame retardants in all wireless devices sold within the European Economic Area. Hardware manufacturers are accelerating material substitution programs and supply chain audits to maintain CE marking eligibility. Medical and automotive sensor categories face the most intensive documentation burdens, with France's ANSM and Germany's KBA imposing additional substance verification layers beyond baseline EU requirements.
Industrial buyers are consolidating sensor procurement under single-source framework agreements that bundle hardware, connectivity management, and cloud analytics subscriptions. Traditional component distributors are losing share to verticalized IoT platform vendors offering outcome-guaranteed service contracts. This consolidation is most pronounced in German automotive manufacturing clusters, where tier-one suppliers prefer integrated partnerships over multi-vendor integration complexity.
Europe Wireless Sensors Market Segmentation
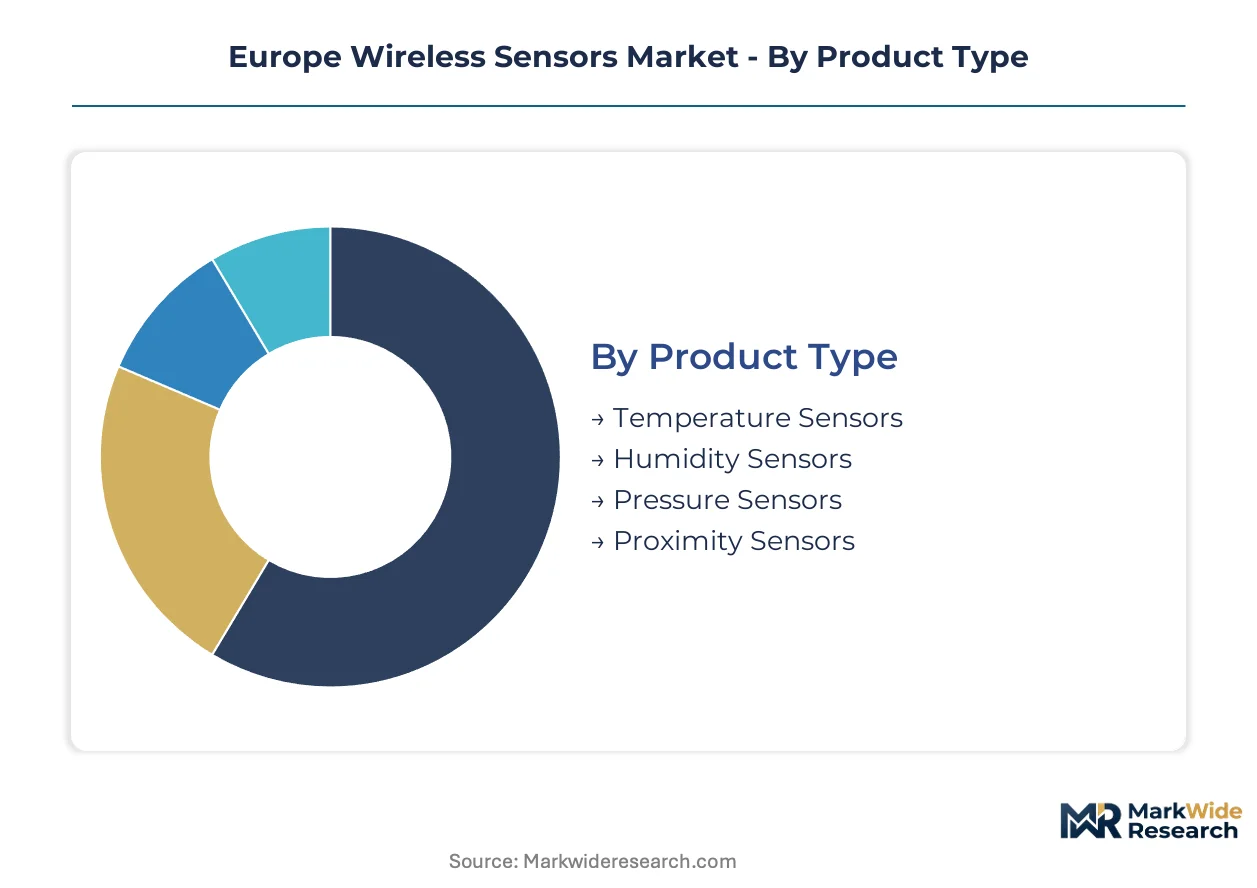
Wireless sensor procurement patterns diverge sharply across European verticals. Industrial buyers prioritize decade-long field reliability and protocol interoperability, while consumer-facing deployments emphasize miniaturization and rapid commissioning cycles.
Product Type:
Temperature and pressure sensors rotate through industrial maintenance cycles every 7-10 years, whereas proximity sensors in consumer electronics turn over within 18-24 months.
- Temperature Sensors:Thermistor and RTD-based wireless nodes transmit process values via sub-gigahertz protocols. German automotive paint shops and French food processing facilities drive replacement demand as REACH-compliant materials displace legacy solder alloys.
- Pressure Sensors:Piezoresistive MEMS capsules with ceramic diaphragms handle corrosive media in chemical plants. Nordic offshore wind operators specify these for nacelle lubrication monitoring where salt spray degrades wired alternatives.
- Humidity Sensors:Capacitive polymer films measure ambient moisture in Dutch greenhouse climate control networks.
- Proximity Sensors:Inductive and ultrasonic variants enable collision avoidance in automated guided vehicles traversing Polish warehouse floors.
Temperature sensors dominate installed base. Proximity sensors are where expansion concentrates.
Technology:
Protocol selection maps directly to power budget and range requirements, with cost tiers separating short-range personal area networks from kilometer-scale infrastructure deployments.
- LoRaWAN:Chirp spread spectrum modulation achieves 15-kilometer rural range at sub-milliwatt transmit power. French water utilities and German agricultural cooperatives are standardizing on this for soil moisture and pipeline monitoring where cellular tariffs erode project economics.
- Bluetooth:Low Energy 5.3 stacks enable 2-megabit throughput for wearable health patches and automotive cabin comfort controls. Bosch Sensortec and Nordic Semiconductor dominate module supply for these short-range applications.
- Zigbee:Mesh networking suits smart home lighting and HVAC retrofit markets in UK residential construction.
- Wi-Fi:HaLow variants penetrate industrial video surveillance and high-bandwidth vibration analysis use cases.
Bluetooth anchors consumer volume. LoRaWAN captures the steepest expansion trajectory in utility and agriculture procurement.
End User:
Customer type determines certification burden and sales cycle length, with medical and automotive verticals imposing 18-36 month qualification timelines against 6-12 months for industrial automation.
- Industrial Automation:Predictive maintenance networks in German automotive stamping plants and Silesian steel mills require SIL-rated wireless transmitters. Buyers here consolidate procurement under multi-year framework agreements bundling hardware, connectivity management, and cloud analytics.
- Healthcare:France's ANSM reimbursement expansion for hospital-at-home programs is accelerating wireless vital sign patch deployments. CE marking under MDR and cybersecurity pre-certification under the EU Cyber Resilience Act dominate vendor selection criteria.
- Agriculture:Dutch precision farming cooperatives and French viticulture estates adopt soil moisture and microclimate monitoring to optimize irrigation subsidies under CAP eco-schemes.
- Smart Homes:Nordic and Benelux utilities bundle connected thermostats and energy display units with residential tariff restructuring programs.
Industrial automation commands the largest contract values. Healthcare is where regulatory compliance investments concentrate most intensively.
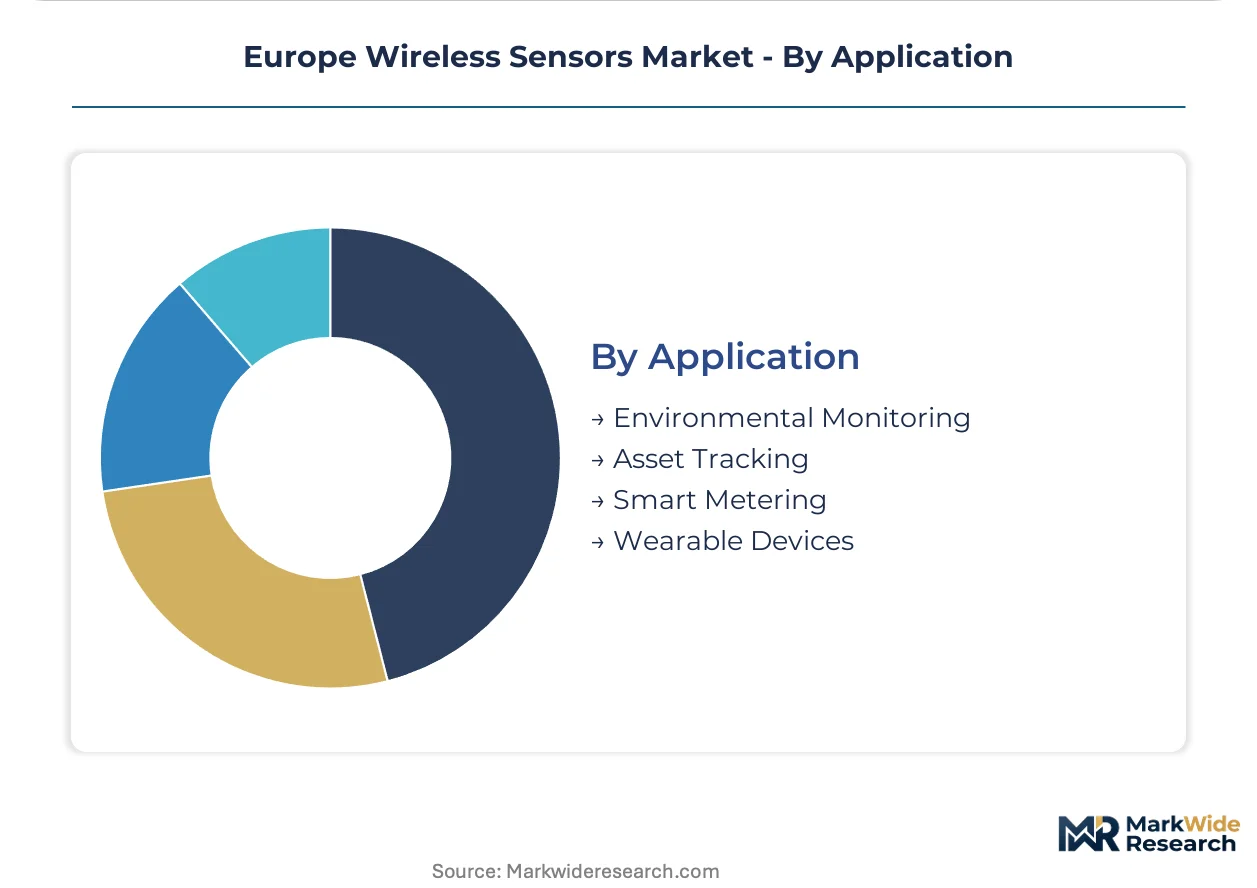
Application:
Use case maturity varies from commoditized smart metering to emerging acoustic anomaly detection, with data governance requirements scaling alongside criticality.
- Environmental Monitoring:Distributed air quality and noise level sensors feed municipal digital twin platforms in Barcelona, Amsterdam, and Copenhagen. EU Green Deal reporting mandates require continuous emissions verification at German manufacturing facilities.
- Asset Tracking:BLE and UWB tags locate high-value tooling in aerospace supply chains and pharmaceutical cold chain logistics. Battery life constraints favor LoRaWAN for multi-year container tracking across fragmented EU spectrum allocations.
- Smart Metering:Electricity and gas utilities in Italy and Spain complete nationwide rollouts, shifting vendor focus toward software-defined radio upgrades.
- Wearable Devices:Biometric sensor fusion in industrial exoskeletons and consumer fitness bands drives MEMS accelerometer and gyroscope demand.
Smart metering saturates Western European penetration. Asset tracking is where cross-border logistics and supply chain resilience investments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation corridors concentrate wireless sensor manufacturing capacity, with captive MEMS fabrication and RF module assembly anchoring supply-side output across the continent.
Germany
Automotive stamping plants in Stuttgart and Wolfsburg drive predictive maintenance sensor procurement, while chemical facilities along the Rhine corridor retrofit emissions monitoring networks. KBA type-approval requirements for vehicle-integrated sensing hardware tighten certification timelines. Bavarian industrial clusters anchor LoRaWAN gateway manufacturing for agricultural and utility deployments.
France
Hospital-at-home reimbursement expansion under ANSM guidelines accelerates wireless vital sign patch deployments in Paris and Lyon healthcare systems. Nuclear decommissioning programs in Normandy and Provence demand radiation-hardened sensor networks for remote monitoring. REACH-compliant material reformulation pressures PCB substrate suppliers in Grenoble semiconductor corridors.
Netherlands
Precision greenhouse operators in Westland and Aalsmeer deploy soil moisture and microclimate sensors to optimize CAP eco-scheme irrigation subsidies. Port of Rotterdam logistics hubs adopt BLE asset tracking for container condition monitoring. Spectrum harmonization with neighboring Belgium and Germany enables cross-border LoRaWAN coverage for Rhine-Meuse delta agricultural cooperatives.
Poland
EU cohesion fund investments modernize Silesian mining and steel operations with predictive maintenance sensor networks. Warsaw-based system integrators bundle LoRaWAN connectivity with cloud analytics for municipal smart city pilots. Lower Silesian manufacturing zones attract German automotive suppliers establishing captive sensor assembly capacity.
Sweden
Nordic smart city infrastructure programs in Stockholm and Gothenburg standardize on sub-gigahertz protocols for streetlight control and waste management optimization. Offshore wind operators in the Baltic Sea specify pressure sensors for nacelle lubrication monitoring where salt spray degrades wired alternatives. Ericsson's RF engineering heritage concentrates antenna design talent in Kista technology corridors.
Europe Wireless Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying MEMS dies and RF modules. The vendor base stratifies across three tiers: diversified automation conglomerates bundling hardware with software subscriptions, captive semiconductor divisions serving parent company verticals, and independent module vendors competing on unit economics. Dominant competitive moves include M&A to acquire edge-AI software stacks and strategic partnerships to secure sub-gigahertz spectrum licenses across fragmented national allocations.
Among diversified automation conglomerates, Honeywell International Inc and Siemens AG exemplify platform-centric positioning that bundles wireless sensor networks with predictive analytics and managed connectivity services. Bosch Sensortec GmbH occupies a distinct upstream tier as a captive semiconductor division leveraging in-house MEMS fabrication to supply miniature accelerometers and environmental sensors to external device manufacturers.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Emerson Electric Co |
| Schneider Electric |
| Siemens AG |
| ABB Ltd |
| Texas Instruments Incorporated |
| TE Connectivity Ltd |
| Infineon Technologies AG |
| Bosch Sensortec GmbH |
| Others |
Supply & Pricing Matrix
Coin-cell lithium supply concentration from East Asian refiners determines both the pricing tier spreads across premium and standard sensor modules and the geographic shape of European assembly networks seeking to decouple from single-source dependencies.
Pricing Analysis
CE marking under the EU Radio Equipment Directive dictates the pricing tier structure across the European market. Three-tier pricing separates SIL-certified industrial transmitters from standard commercial-grade nodes and economy consumer modules, with certification grade and volume scale as the primary differentiation drivers. Cost compression in the economy tier is intensifying because MEMS fabrication scaling at Bosch Sensortec drives unit cost reductions for miniature accelerometers. Industrial automation buyers demonstrate the lowest price sensitivity due to outcome-guaranteed service contracts, while smart home consumers exhibit the highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for wireless sensor manufacturers. Component sourcing draws from Taiwan for RF transceiver chips, South Korea for advanced MEMS foundry services, and China for PCB substrate materials and battery cell production. Single-source vulnerability concentrates in coin-cell lithium supply from East Asian chemical refiners. Distribution runs through German industrial automation distributors and verticalized IoT platform vendors offering bundled hardware-connectivity-analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Wireless Sensors Market sits in a cyclical recovery phase driven by EU Green Deal digitalization mandates accelerating industrial facility retrofit programs.
For Market Incumbents: Insulate premium positioning through captive MEMS fabrication investments in German industrial corridors and early EU Cyber Resilience Act pre-certification to lock in healthcare procurement pipelines. Threat substitution from software-defined radio modules virtualizing hardware functions demands accelerated edge-AI software stack acquisition to maintain platform bundling advantages.
For New Entrants and Emerging Players: Polish Silesian mining and steel operations represent the most penetrable geography for LoRaWAN-enabled predictive maintenance networks, with EU cohesion fund infrastructure investments creating first-mover advantages. Target hospital-at-home wireless vital sign patches in France as the regulatory reimbursement window expands under ANSM guidelines. Pursue system integrator partnerships as the preferred go-to-market channel.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrators with edge-AI capabilities and sub-gigahertz spectrum license portfolios. Long-term viability over a multi-year horizon hinges on vertical integration depth into MEMS fabrication and RF module assembly. Target acquisition archetypes include independent module vendors with software-defined radio competencies and captive semiconductor divisions serving parent company verticals. Monitor EU Cyber Resilience Act implementation timelines as the critical inflection signal for procurement eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Software Stack Acquisition | Enables on-device machine learning inference for acoustic anomaly detection in German automotive plants. |
| EU Cyber Resilience Act Pre-Certification | Unlocks preferential positioning in France ANSM-governed hospital-at-home procurement pipelines. |
| LoRaWAN Gateway Manufacturing Expansion | Bavarian industrial clusters anchor agricultural and utility deployment infrastructure across the continent. |
| MEMS Fabrication Capacity Addition | Bosch Sensortec's captive wafer investments drive unit cost reductions for automotive cabin monitoring sensors. |
| Sub-Gigahertz Spectrum License Partnership | Addresses national frequency allocation fragmentation complicating cross-border logistics network deployments. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Field discussions with plant engineers at German automotive stamping facilities, procurement leads at Nordic offshore wind operators, regulatory affairs specialists navigating France's ANSM guidelines, and IoT platform integration specialists informed the demand-side assessment. Secondary validation drew from EU Radio Equipment Directive implementation documents, REACH substance restriction databases, KBA type-approval records, and customs trade data for MEMS and RF module flows. Bottom-up sensor deployment estimates triangulated against top-down industrial automation spending patterns.
Calibration against historical protocol adoption curves and industrial IoT platform penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor product type, wireless protocol technology, end-user vertical, and application criticality, with additional granularity on certification tier and power budget classification. CAGRs were derived from regression analysis of deployment velocity correlated with regulatory mandate implementation phases. Industry-specific forecast inputs incorporated EU Green Deal emissions monitoring compliance deadlines and France's ANSM reimbursement expansion timelines.
Practitioners should monitor lithium raw material sourcing disruptions and sub-gigahertz spectrum harmonization negotiations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Thermistor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Sensor Bearing Market