
 Pressure Sensor Market | 2026-2036
Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Sensor Market Analysis
MEMS-to-silicon integration is reshaping pressure sensor architectures, collapsing multiple sensing functions onto single die platforms while demanding sub-micron fabrication precision. Honeywell International Inc. leverages its aerospace certification depth to dominate high-reliability segments where failure tolerance approaches zero. Bosch Sensortec anchors consumer and automotive volume tiers through captive wafer capacity and proprietary packaging. TE Connectivity specializes in harsh-environment transducers for industrial process streams, differentiating through hermetic sealing and media-isolated construction.
A pressure sensor converts applied mechanical force into quantifiable electrical signals through piezoresistive, capacitive, or optical transduction mechanisms, typically achieving accuracy within 0.1% full-scale span across calibrated temperature ranges. Its primary purpose spans process safety, fluid dynamics control, and closed-loop automation in equipment where real-time pressure state determines operational integrity. Piezoresistive technology leads unit volumes due to mature silicon micromachining and foundry accessibility, while capacitive architectures capture premium positioning in applications demanding superior stability and low power draw. Automotive end-use commands the largest revenue pool, though healthcare diagnostic and monitoring applications expand fastest as wearable and point-of-care platforms proliferate.
ISO 26262 functional safety mandates and EPA emissions verification protocols shape automotive sensor validation burdens, extending development cycles but raising barriers against unqualified suppliers. REACH substance restrictions and RoHS material limits constrain piezoresistive element compositions, redirecting R&D toward compliant metallization and lead-free die-attach processes. NHTSA brake-system regulations and FAA airworthiness directives further segment qualification requirements by end-use severity. Stakeholders must monitor how Chinese GB standards and EU CSRD disclosure rules will recalibrate supply chain transparency expectations and carbon-accounting obligations across component sourcing decisions.
Market Dynamics
MEMS-to-silicon integration is collapsing multiple sensing functions onto single die platforms, compressing bill-of-materials counts while demanding sub-micron fabrication precision from foundry partners. This structural force is redrawing competitive boundaries between component specialists and integrated system suppliers.
Growth Catalysts
- Automotive electrification mandates:Germany, Japan, and the United States are expanding sensor integration for battery thermal management and brake-by-wire systems under NHTSA and ISO 26262 functional safety protocols.
- China's local procurement tightening:Domestic EV production scaling and GB standards compliance requirements are concentrating demand for locally certified pressure sensor suppliers.
- MEMS miniaturization advances:Silicon-on-insulator fabrication improvements are lowering unit costs while expanding addressable applications into wearable healthcare diagnostics.
Market Restraints
- Raw material concentration:High-purity silicon wafer supply concentrates among a handful of East Asian foundries, creating input cost volatility and single-source vulnerability.
- Regulatory friction:REACH substance restrictions and RoHS material limits constrain piezoresistive element compositions, forcing metallization redesigns and lead-free die-attach process qualification.
- Technical limitation:Piezoresistive architectures suffer temperature drift beyond 150°C, capping deployment in aerospace engine monitoring where capacitive alternatives command premium positioning.
Strategic Opportunities
- Underpenetrated healthcare wearables:Point-of-care and continuous monitoring platforms in North America and Western Europe are creating demand for ultra-low-power pressure sensors with sub-millimeter form factors.
- EU CSRD disclosure alignment:Supply chain transparency and carbon-accounting obligations are creating first-mover advantage for suppliers with documented lifecycle emissions data.
- Optical transduction convergence:Fiber-optic pressure sensing fused with MEMS packaging is opening subsea oil exploration and nuclear containment applications previously inaccessible to silicon-based approaches.
Industry Challenges
- Certification timeline compression:FAA airworthiness directives and EPA emissions verification protocols extend development cycles, straining R&D amortization across lower-volume specialty segments.
- Integration complexity:Legacy industrial control systems with analog 4-20mA loops resist digital MEMS sensor integration, forcing dual-output product architectures and field calibration service investments.
- Skill scarcity:MEMS design expertise concentrates among aging specialists in Germany, Japan, and the United States, constraining foundry capacity expansion and process innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Sensor Market |
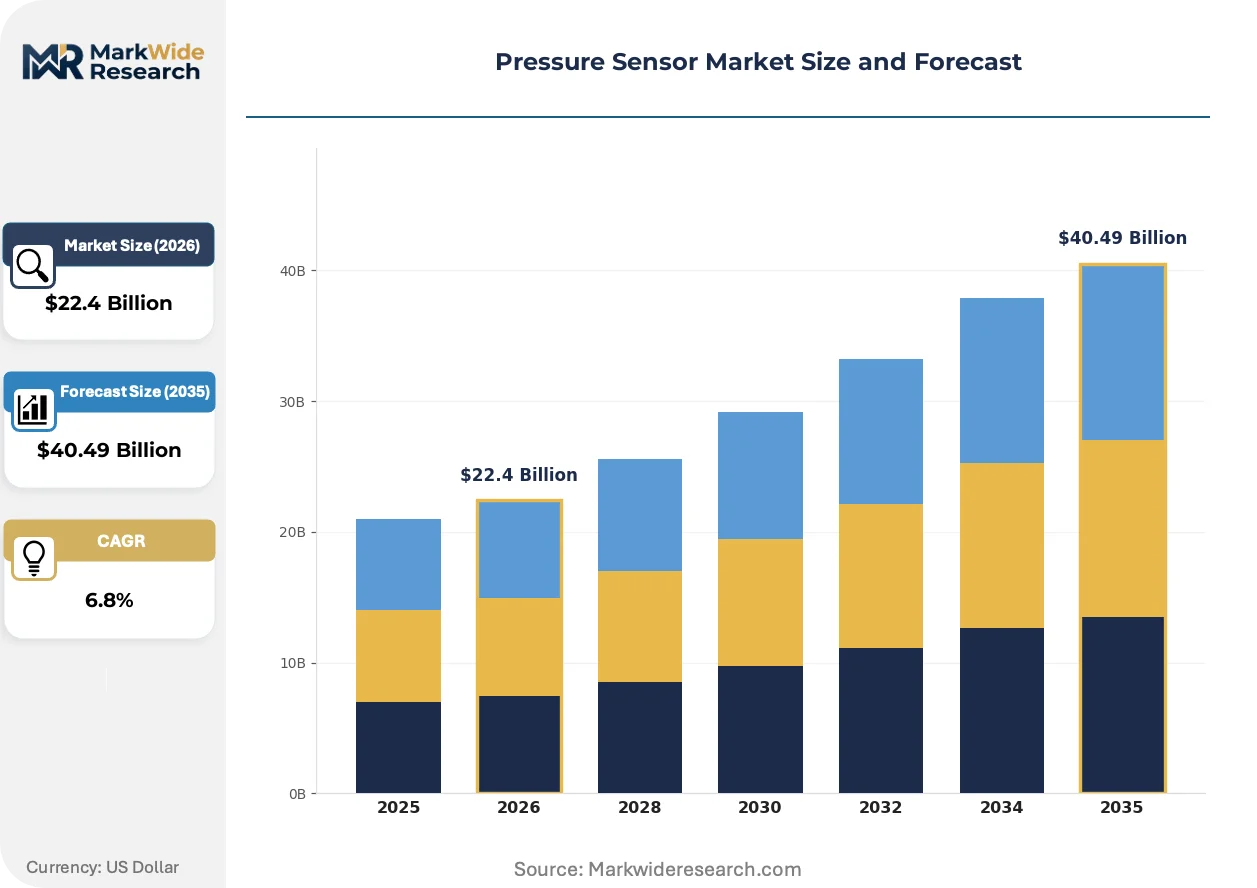
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Gauge, Differential, Sealed Technology: Electrical, Capacitive, Piezoresistive, Optical End User: Aerospace, Automotive, Healthcare, Industrial Application: Process Control, Level Measurement, Monitoring, HVAC |
| Companies Covered | ROHM Semiconductor, Honeywell International Inc., Infineon Technologies, Sensata Technologies, TE Connectivity, Murata Manufacturing Co. Ltd., STMicroelectronics, Bosch Sensortec, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Sensor Market Emerging Trajectories
Active developments across transduction physics, regulatory compliance frameworks, and procurement architectures are compressing product lifecycles and redrawing supplier-customer relationships in pressure sensing.
Multi-physics sensor fusion is collapsing discrete pressure, temperature, and humidity sensing elements into monolithic CMOS-MEMS platforms. Automotive Tier 1 suppliers in Germany and Japan are accelerating adoption for cabin climate and battery management systems. This integration is collapsing module supplier count per vehicle platform from three to one, concentrating procurement power among integrated device manufacturers.
REACH and RoHS substance restrictions are forcing metallization transitions away from lead-based die-attach and cadmium-containing thin films. European sensor manufacturers are absorbing eighteen-to-twenty-four month requalification cycles for process changes. Medical device OEMs serving the EU market are now requiring full material disclosure documentation upstream to MDR compliance deadlines.
Automotive OEMs are consolidating sensor procurement under long-term system-supplier contracts rather than discrete component purchasing. This disintermediation is compressing available channel margin for specialty pressure sensor distributors. The shift is most visible in China, where domestic EV manufacturers are awarding ten-year sole-source agreements to vertically integrated packaging houses with captive wafer capacity.
Pressure Sensor Market Segmentation
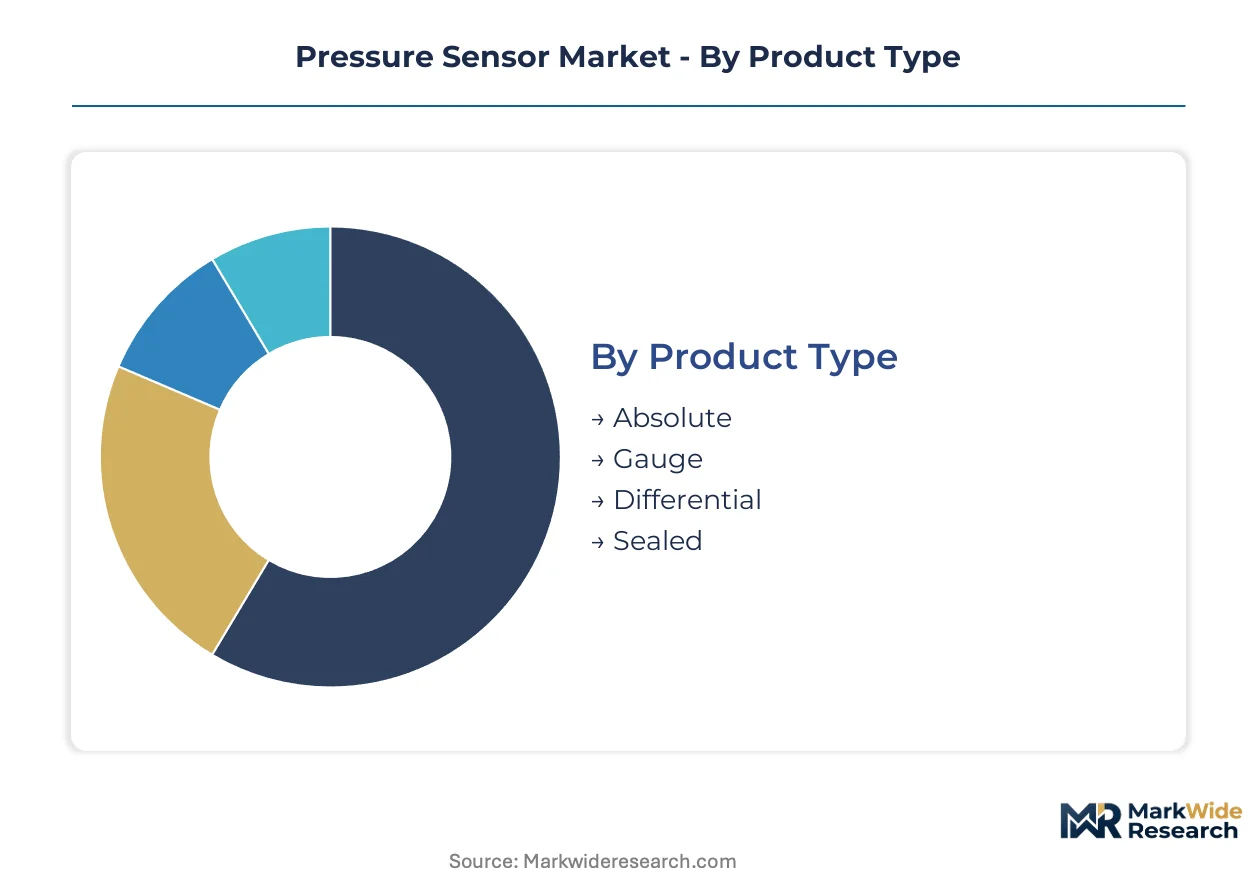
Pressure sensor architectures fragment across measurement principles, fabrication technologies, and environmental tolerances. Each segmentation axis carries distinct qualification burdens and margin profiles that reshape supplier positioning across automotive, medical, and industrial procurement channels.
Product Type:
Measurement reference frames determine calibration complexity and deployment suitability across sealed systems, atmospheric venting, and differential flow applications.
- Absolute:Vacuum-referenced designs measure pressure against sealed zero-point cavities. Demand concentrates in aerospace altitude sensing and meteorological instrumentation where barometric baselines determine flight safety protocols.
- Gauge:Atmospheric-referenced configurations dominate automotive tire pressure monitoring and industrial pneumatic systems. Bosch Sensortec and TE Connectivity compete aggressively for platform integration slots in Germany and United States vehicle programs.
- Differential:Dual-port architectures sense pressure gradients across filtration membranes and HVAC ductwork. Compact MEMS implementations are displacing legacy capacitive cells in cleanroom airflow management.
- Sealed:Hermetically isolated elements withstand corrosive process media in chemical manufacturing and subsea oil extraction. Premium positioning reflects tungsten-carbide diaphragm costs and extended calibration cycles.
Established volume favors Gauge; emerging adoption favors Differential.
Technology:
Fabrication physics dictate temperature tolerance, power consumption, and foundry accessibility.
- Piezoresistive:Silicon strain-gauge elements etched through bulk micromachining achieve sub-dollar unit costs at automotive scale. Temperature drift beyond 150°C limits turbine engine applications where capacitive alternatives command price premiums.
- Capacitive:Parallel-plate architectures deliver superior stability for implantable medical devices and aerospace fuel gauging. Honeywell International Inc. leverages proprietary glass-to-metal sealing for FAA-certified transducers in United States commercial aviation.
- Optical:Fiber-Bragg-grating and Fabry-Perot interferometric approaches eliminate electromagnetic interference in MRI suites and high-voltage switchgear. Subsea oil exploration in Norway and Brazil is adopting fused fiber-MEMS packages for wellhead monitoring.
- Electrical:Strain-gauge and potentiometric legacy designs persist in heavy industrial hydraulics where analog 4-20mA output compatibility outweighs digital precision advantages.
Cost-sensitive procurement favors Piezoresistive; performance-critical applications favor Capacitive.
End User:
Sector-specific certification requirements fragment supplier qualification pathways and amortization timelines.
- Automotive:ISO 26262 functional safety mandates and NHTSA brake-by-wire protocols extend development cycles. Battery thermal management in China EV production is accelerating demand for multi-channel pressure-temperature fusion sensors.
- Healthcare:FDA 510(k) and EU MDR compliance burdens concentrate procurement among established medical device suppliers. Wearable continuous blood pressure monitors in United States and Western Europe are creating sub-millimeter form factor requirements.
- Industrial:Hermetic sealing and media isolation differentiate suppliers for chemical process and oil refining applications. REACH substance restrictions are forcing metallization transitions in European sensor manufacturing.
- Aerospace:FAA airworthiness directives and EASA certification requirements limit qualified supplier pools. Engine monitoring above 300°C demands specialized capacitive or optical architectures beyond standard silicon MEMS tolerance.
Volume concentration favors Automotive; margin expansion favors Healthcare.
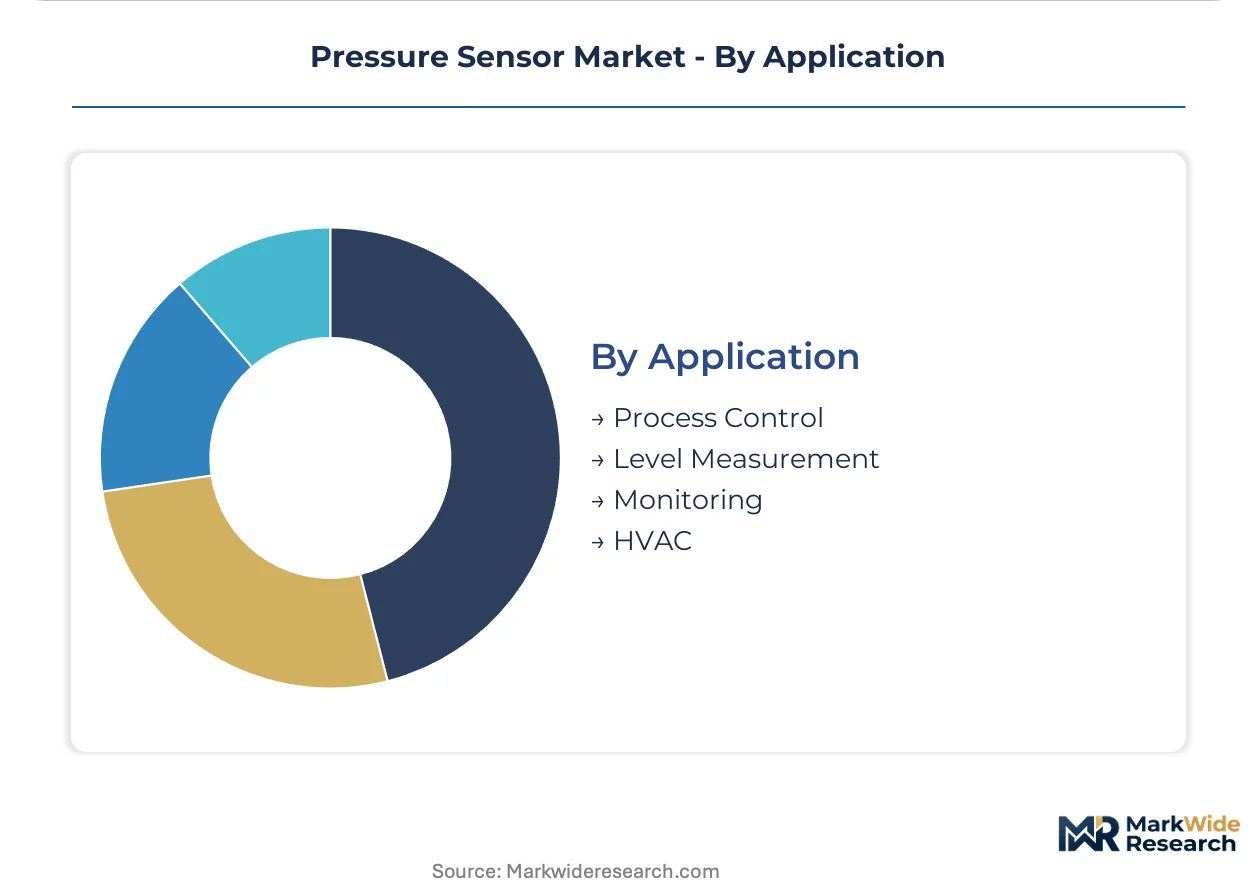
Application:
Functional deployment contexts determine accuracy requirements, environmental hardening, and replacement cycle economics.
- Process Control:Closed-loop automation in chemical and pharmaceutical manufacturing demands 0.1% full-scale accuracy with SIL-rated safety integrity. United States FDA process analytical technology initiatives are tightening calibration documentation requirements.
- Monitoring:Predictive maintenance platforms in industrial IoT architectures are shifting demand toward wireless-enabled MEMS sensors with edge computing integration. Germany Industrie 4.0 programs are accelerating smart sensor adoption.
- Level Measurement:Hydrostatic pressure inference dominates tank gauging in oil storage and water treatment. Submersible ceramic-capacitive designs resist contamination in wastewater applications.
- HVAC:Building automation systems in commercial real estate prioritize low-power differential sensing for airflow optimization. United States DOE efficiency standards are driving sensor density increases in rooftop units.
Replacement revenue favors Process Control; installed base expansion favors Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive sensor exports flow into Chinese EV battery management systems, while Japanese MEMS foundries supply North American aerospace certification channels. This trade architecture concentrates value capture among three manufacturing geographies with divergent regulatory exposure.
United States
NHTSA brake-by-wire mandates and FAA airworthiness directives drive demand for high-reliability pressure transducers in Detroit automotive platforms and Seattle-area aerospace clusters. EPA emissions verification protocols extend sensor qualification timelines. Honeywell leverages its aerospace certification depth from facilities in Arizona and Minnesota to dominate zero-failure-tolerance segments.
Germany
ISO 26262 functional safety requirements and KBA vehicle-type approval processes shape sensor integration for BMW and Volkswagen electrification programs. REACH substance restrictions force metallization redesigns in Baden-Württemberg fabrication plants. Bosch Sensortec anchors consumer and automotive volume tiers through captive wafer capacity in Reutlingen.
China
Domestic EV production scaling and GB standards compliance requirements concentrate procurement among locally certified suppliers. MIIT industrial policy and dual carbon goals accelerate battery thermal management sensor deployment. BYD and CATL procurement mandates in Shenzhen and Ningbo are tightening local content rules for pressure sensor modules.
Japan
METI technology roadmaps and JIS standard harmonization guide MEMS miniaturization investments for Toyota and Honda electrification programs. PMDA medical device regulations shape diagnostic sensor requirements. Murata Manufacturing and STMicroelectronics operations in Kyoto and Aizu-Wakamatsu supply precision capacitive elements for implantable healthcare platforms.
South Korea
MFDS medical device approval pathways and KAT vehicle safety mandates drive demand for multi-physics sensor fusion in Hyundai-Kia battery platforms. Government semiconductor subsidies under the K-Semiconductor Belt initiative expand foundry capacity. Samsung SDI and LG Energy Solution procurement in Gyeonggi-do prioritizes suppliers with documented carbon-accounting data under emerging CSRD-aligned disclosure requirements.
Pressure Sensor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base organizes around three archetypes: integrated device manufacturers with captive wafer capacity, specialized packaging houses with system-level certification depth, and component distributors bridging legacy industrial analog loops. Dominant competitive moves include strategic partnerships with automotive Tier 1 suppliers and geographic expansion into Chinese EV supply chains under local procurement mandates.
Within the aerospace-certification archetype, Honeywell International Inc. and Sensata Technologies occupy positions where failure tolerance approaches zero. Among European integrated device manufacturers, Infineon Technologies and STMicroelectronics exemplify the MEMS-to-silicon integration trajectory collapsing multiple sensing functions onto single die platforms. Bosch Sensortec anchors the high-volume automotive tier through proprietary packaging and scale-driven cost structures.
| Leading Market Players |
|---|
| ROHM Semiconductor |
| Honeywell International Inc. |
| Infineon Technologies |
| Sensata Technologies |
| TE Connectivity |
| Murata Manufacturing Co. Ltd. |
| STMicroelectronics |
| Bosch Sensortec |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Overcapacity in 200mm silicon wafer fabrication across Taiwan and South Korea is compressing foundry pricing while concentrating bargaining power among automotive Tier 1 buyers with multi-year offtake agreements. This utilization asymmetry forces MEMS specialists to absorb margin erosion in commodity piezoresistive tiers while extracting premiums through capacitive certification depth.
Pricing Analysis
Silicon-on-insulator wafer pricing gaps between mature 180nm nodes and emerging 65nm MEMS-CMOS integration are widening as automotive electrification demands precision scaling. Three-tier pricing structure across aerospace-certified capacitive, automotive-grade piezoresistive, and industrial analog legacy tiers separates Honeywell's FAA-qualified transducers from Bosch Sensortec's volume MEMS. Cost compression in gauge-pressure automotive segments is intensifying because Chinese EV manufacturers are consolidating procurement under ten-year sole-source contracts. Healthcare OEMs exhibit lowest price sensitivity due to FDA 510(k) requalification costs, while HVAC building automation buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
High-purity monocrystalline silicon feedstock draws from German Wacker Chemie, Japanese Shin-Etsu, and South Korean SK Siltron refining operations before reaching Taiwan Semiconductor and GlobalFoundries MEMS foundries. Boron-doped wafers, hermetic glass-to-metal seals, and tungsten-carbide diaphragms anchor input cost structures across aerospace and subsea tiers. Single-source vulnerability concentrates in 200mm SOI wafer supply where three foundries control automotive-qualified capacity. Distribution runs through authorized component distributors for legacy industrial analog loops, while automotive Tier 1 suppliers demand direct vendor-managed inventory at assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure sensor demand is inflecting on MEMS-to-silicon integration density as ISO 26262 functional safety mandates collapse multi-sensor modules into single-die platforms. This technological disruption rewards foundry-scale players while stranding packaging specialists without captive wafer capacity.
For Market Incumbents: Pre-empt Chinese local procurement tightening by qualifying Reutlingen or Arizona facilities under GB standards before MIIT mandates harden. Backward integration into silicon-on-insulator wafer supply insulates margin position against Shin-Etsu pricing volatility. Certification investment in FAA and EASA dual-release pathways defends aerospace revenue pools from Sensata Technologies' acquisition-led expansion.
For New Entrants and Emerging Players: Western European healthcare wearables present the most penetrable white-space as FDA 510(k) parallel submissions create regulatory moats against Chinese competitors. Sub-millimeter blood pressure monitoring form factors for United States diagnostic platforms offer technology differentiation without automotive scale requirements. Partnership with contract MEMS foundries in South Korea's K-Semiconductor Belt enables rapid prototyping without billion-dollar captive fab investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical-fiber MEMS fusion platforms as subsea oil exploration demands hermetic packaging beyond silicon limits. Five-to-ten year viability favors packaging houses with proprietary glass-to-metal sealing IP rather than commodity piezoresistive assemblers. Watch for MIIT local-content enforcement tightening as the signal indicating Chinese EV procurement preference shifts from cost to compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-CMOS Monolithic Integration | Collapses multi-sensor module costs for BMW and Volkswagen battery platforms under ISO 26262. |
| GB Standards Qualification | Unlocks BYD and CATL procurement channels before MIIT local-content mandates harden. |
| Optical-Fiber MEMS Fusion | Opens Norwegian and Brazilian subsea wellhead monitoring beyond silicon temperature limits. |
| Carbon-Accounting Documentation | Meets EU CSRD disclosure requirements for Samsung SDI and LG Energy Solution supplier selection. |
| Healthcare Wearable Miniaturization | Captures United States point-of-care diagnostic demand for sub-millimeter continuous monitors. |
Methodological Framework
Operator-level perspectives from MEMS foundry process engineers, automotive Tier 1 supplier procurement directors, FAA certification specialists, and hospital biomedical equipment committees anchored the qualitative base. These primary interviews combined with secondary validation from SEC 10-K filings, EPA emissions verification protocols, FDA 510(k) clearance databases, and MIIT industrial policy announcements. Bottom-up wafer shipment analysis and top-down automotive platform sensor content modeling provided triangulation across volume estimates.
Scenario-bracketing around automotive electrification penetration rates and Chinese local procurement enforcement timelines structured the analytical framework across the analysis window. Segmentation dimensions modeled include transduction physics, measurement reference frame, end-use certification tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and content-per-vehicle expansion in battery thermal management systems. Forecast inputs incorporated REACH substance restriction phase-out schedules and FAA airworthiness directive amendment pipelines.
Practitioners should monitor MIIT GB standards enforcement intensity, EPA brake-by-wire mandate acceleration, and SOI wafer foundry utilization rates for early signals of forecast deviation. Forecasts reflect documented assumptions on automotive platform standardization timelines and healthcare wearable regulatory pathways. Material shifts in Chinese EV export tariff structures or EASA-METI regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
North America Pressure Sensors Market