
 Semiconductor Lithography Equipment Market | 2026-2036
Semiconductor Lithography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Lithography Equipment Market Analytics
Modular service bundling around lithography light sources is shifting how foundries evaluate total cost of ownership. ASML Holding N.V. anchors the extreme ultraviolet segment through its monopoly on high-NA EUV scanner production. Carl Zeiss AG leverages its optical component supremacy to sustain critical supply relationships with scanner OEMs. Nikon Corporation competes in ArF immersion systems while specializing in mature-node equipment for memory manufacturers.
Semiconductor lithography equipment comprises precision projection systems that transfer circuit patterns onto silicon wafers using wavelengths ranging from 13.5 nanometers in EUV systems to 193 nanometers in ArF immersion tools, with overlay accuracy requirements now below two nanometers for leading-edge nodes. Its primary purpose is enabling the dimensional scaling that drives transistor density gains across logic and memory devices. EUV lithography now dominates capital allocation at leading foundries, while KrF lithography retains margin pools in mature-node analog and power semiconductor production. Maskless lithography serves research institutions and prototyping flows where photomask costs prove prohibitive for low-volume designs.
The EPA regulates fluorinated greenhouse gas emissions from EUV laser-produced plasma sources under the American Innovation and Manufacturing Act, while REACH and the F-Gas Regulation impose chemical restrictions on EUV resist chemistries and cleaning agents across European supply chains. Japan's METI coordinates export control alignment on advanced lithography components through its semiconductor equipment licensing framework. Stakeholders must monitor how bilateral technology controls reshape equipment availability across major fabrication regions and whether domestic lithography development programs in China and South Korea alter supplier concentration.
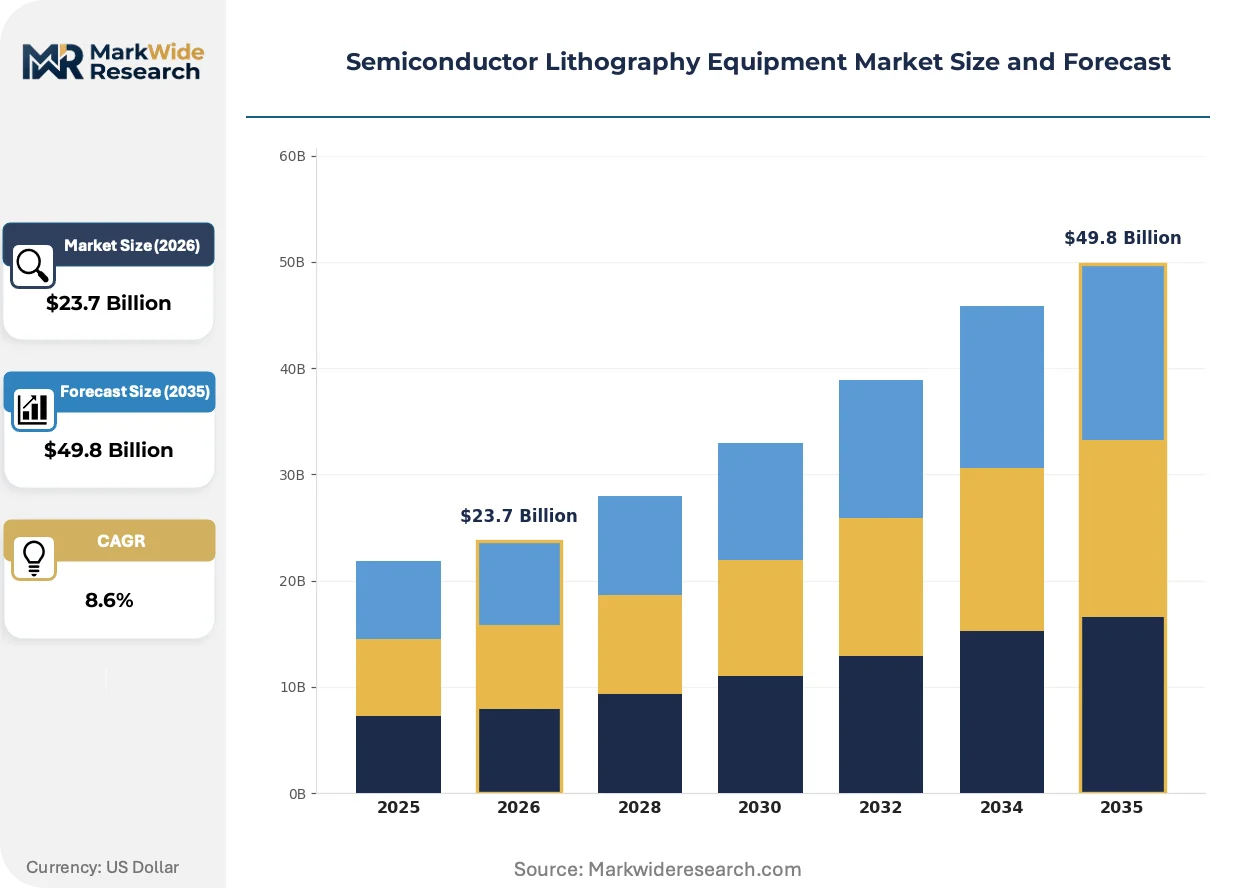
Market Dynamics
Capital allocation at leading foundries is compressing toward EUV scanner procurement, with single-tool costs exceeding prior-generation lithography suites and node migration timelines dictating equipment delivery windows.
Growth Catalysts
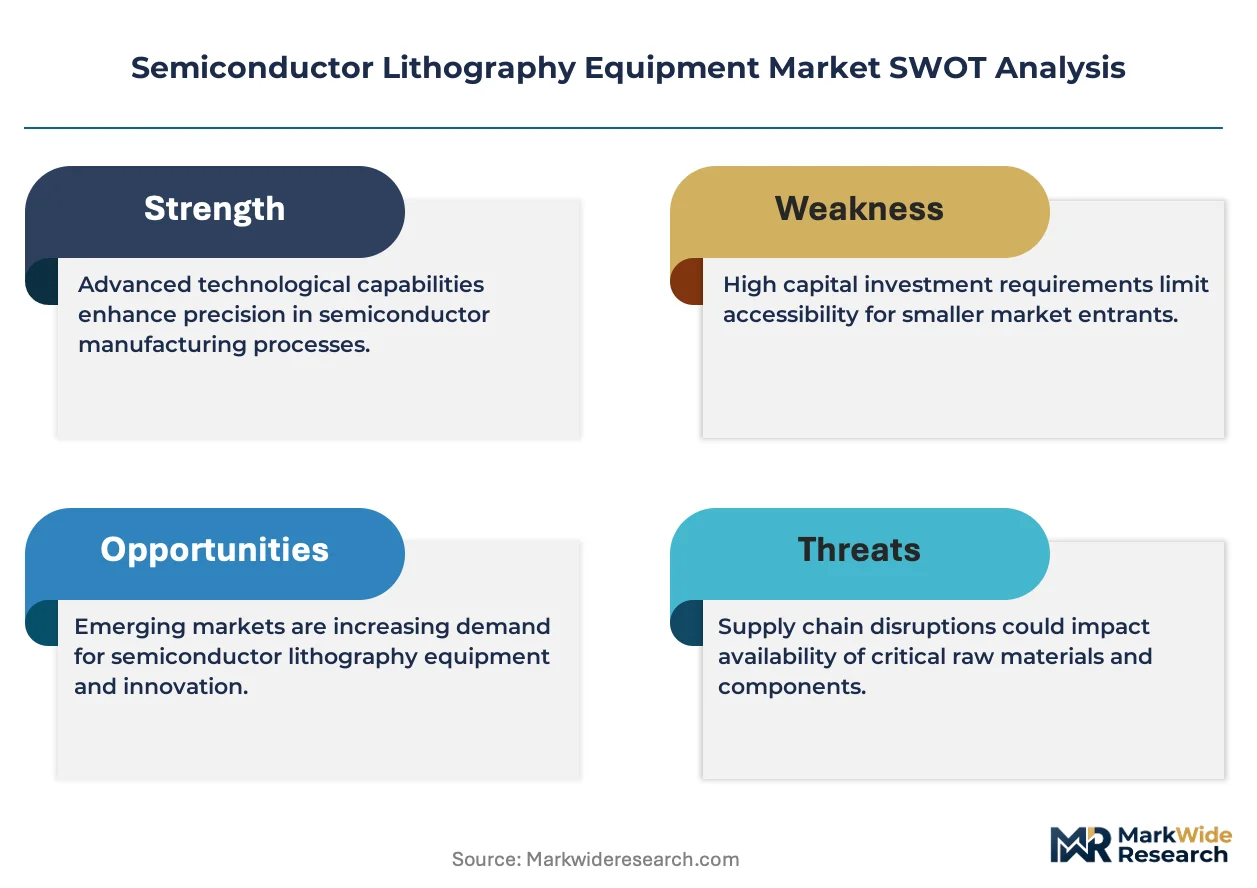
- Foundry node expansion:TSMC, Samsung Foundry, and Intel Foundry Services are commissioning high-NA EUV capacity for 2nm-class production ramps.
- EU F-Gas Regulation phase-down:The European Commission's tightening fluorinated gas quotas are accelerating closed-loop gas recovery system retrofits across EUV light source fleets.
- Memory stack scaling:3D NAND vertical layer counts beyond 300 layers are driving multi-patterning lithography demand at mature-node equipment suppliers.
Market Restraints
- Optics supply concentration:Aspheric mirror fabrication for EUV systems depends on a single German optics supplier with multi-year order backlogs.
- Fluorinated gas input volatility:SF6 and NF3 price swings under EU quota systems create operational cost uncertainty for laser-produced plasma source operators.
- Technical limitation at sub-7nm overlay:Stochastic resist effects and mask 3D topography impose fundamental patterning fidelity constraints without secondary exposure techniques.
Strategic Opportunities
- India semiconductor fabrication:The country's PLI scheme for display and semiconductor manufacturing is attracting lithography equipment tenders for emerging 28nm-class facilities.
- Regulatory tailwind from US CHIPS Act:Domestic content bonuses and facility tax credits are incentivizing scanner deployment at new Arizona and Texas fabrication sites.
- Computational lithography convergence:Machine learning-optimized optical proximity correction is compressing mask data preparation cycles for leading-edge logic designs.
Industry Challenges
- EUV source engineer scarcity:The specialized plasma physics and vacuum systems expertise required for high-power CO2 laser maintenance outstrips available training pipeline output.
- Legacy tool integration:ArF immersion fleet retrofits for multi-patterning compatibility require software stack harmonization with newer overlay metrology systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Lithography Equipment Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ArF Lithography, KrF Lithography, EUV Lithography, DUV Lithography End User: Foundries, OEMs, Integrated Device Manufacturers, Research Institutions Technology: Optical Lithography, Maskless Lithography, Nanoimprint Lithography, Extreme Ultraviolet Lithography Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Applications |
| Companies Covered | Carl Zeiss AG, NuFlare Technology Inc., ASML Holding N.V., Raith GmbH, Vistec Electron Beam GmbH, Nikon Corporation, JEOL Ltd., Mycronic AB, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Lithography Equipment Market Evolving Landscape
Patterning technology roadmaps are diverging between EUV dominance at leading-edge logic and mature-node multi-patterning evolution, with regulatory chemistry constraints forcing resist formulation redesigns.
High-numerical-aperture EUV systems are expanding into 0.55NA configurations that enable single-exposure patterning at 8nm pitch. Memory manufacturers in South Korea and logic foundries in Taiwan are qualifying these tools for 2025-2026 production ramps. The technology is expanding into applications previously requiring quadruple patterning, compressing process complexity and mask count.
The EPA's fluorinated greenhouse gas reporting mandates under the American Innovation and Manufacturing Act are tightening disclosure thresholds for EUV laser-produced plasma operations. Equipment operators must now quantify and verify SF6 and NF3 emissions across facility boundaries. Scanner OEMs are responding with integrated gas abatement system bundling to preempt regulatory compliance costs.
After-sales service unbundling is fragmenting how foundries contract for light source maintenance and optics refurbishment. Large-volume buyers in Taiwan are negotiating component-level service agreements separate from OEM comprehensive contracts. This pattern is most visible among mature-node operators seeking to decouple uptime guarantees from capital equipment financing structures.
Semiconductor Lithography Equipment Market Segmentation
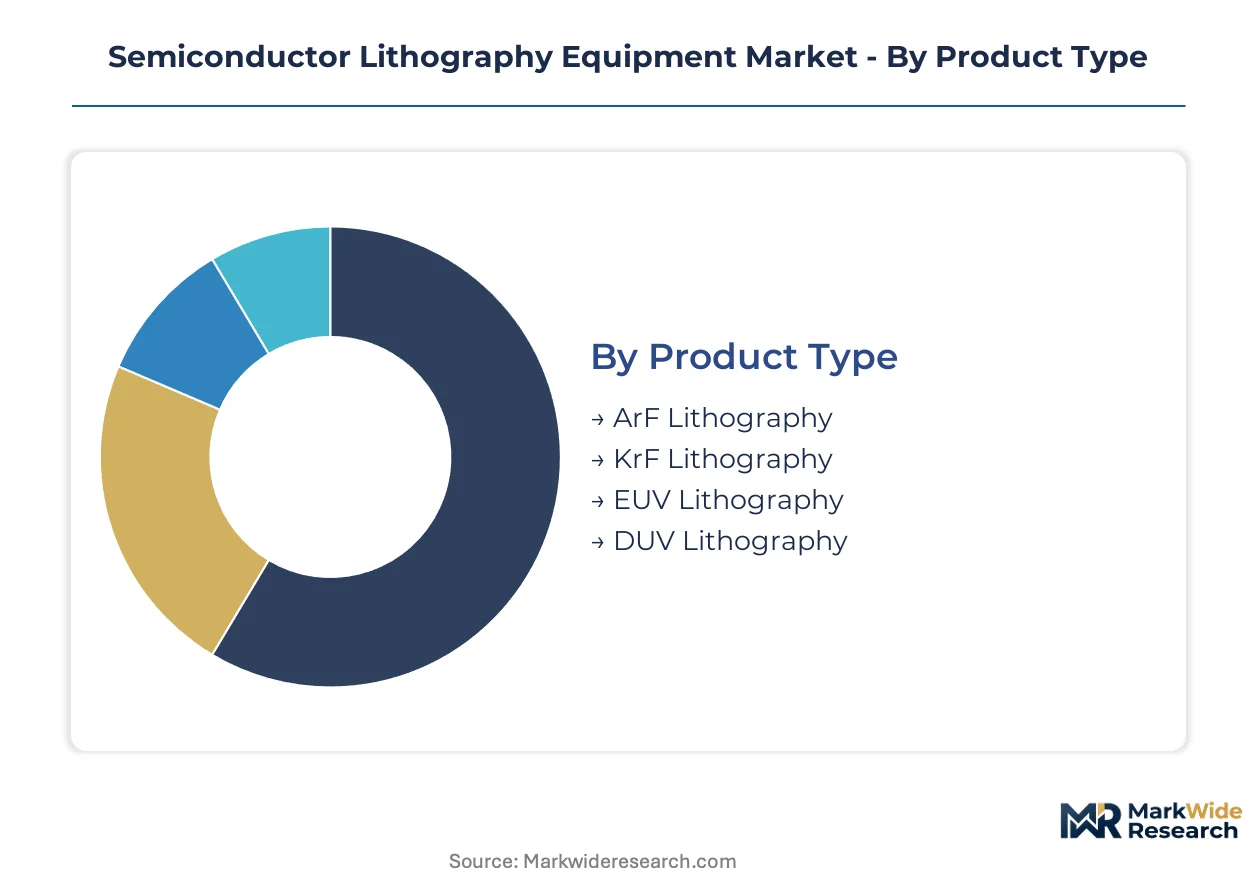
Lithography equipment segmentation reveals how capital allocation splits between leading-edge node investments and mature-node efficiency plays. Procurement patterns diverge sharply by technology generation and end-user business model.
Product Type:
Scanner selection hinges on resolution requirements and total cost of ownership across node generations.
- EUV Lithography:Systems utilizing 13.5nm wavelength with high-NA optics achieving sub-7nm resolution. TSMC's Hsinchu cluster and Samsung's Pyeongtaek complex anchor procurement volumes as both foundries commission 0.55NA tools for 2nm-class ramps. EUV dominates capital allocation despite single-tool costs exceeding legacy lithography suites.
- ArF Lithography:193nm immersion systems employing liquid immersion between final lens and wafer to extend resolution limits. Memory manufacturers in South Korea deploy multi-patterning ArF for 3D NAND layer stacking beyond 300 layers, where overlay tolerance requirements remain less stringent than logic.
- KrF Lithography:248nm wavelength systems serving mature-node analog and power semiconductor production. Foundries in India target KrF equipment for emerging 28nm-class facilities under the PLI scheme.
- DUV Lithography:Deep ultraviolet systems spanning i-line through KrF wavelengths for non-critical layers and legacy node maintenance. IDMs in Japan and Europe utilize DUV fleets for automotive-grade chip production where reliability protocols favor proven process windows.
EUV Lithography leads on scale; ArF Lithography leads on momentum across memory stack scaling applications.
End User:
Business model determines procurement scale, service contract structure, and technology adoption timing.
- Foundries:Merchant manufacturers supplying multiple fabless customers with leading-edge capacity. TSMC, Samsung Foundry, and Intel Foundry Services concentrate EUV procurement, with node migration timelines dictating equipment delivery windows and creating multi-year order backlogs.
- Integrated Device Manufacturers:Vertically integrated producers combining design and fabrication. Intel and Texas Instruments maintain captive lithography fleets optimized for internal product roadmaps rather than external customer diversity.
- OEMs:Equipment manufacturers requiring lithography for component production. Automotive tier-1 suppliers in Germany and Japan deploy mature-node systems for sensor and power module fabrication.
- Research Institutions:Universities and national laboratories operating tools for process development and academic training. imec in Belgium and Albany Nanotech in New York state host multi-vendor lithography clusters for pre-competitive research.
Foundries lead on scale; Research Institutions lead on technology evaluation speed.
Technology:
Patterning modality selection trades resolution capability against throughput and infrastructure requirements.
- Extreme Ultraviolet Lithography:Laser-produced plasma sources generating 13.5nm photons for single-exposure patterning at 8nm pitch. The EPA's fluorinated greenhouse gas reporting mandates under the American Innovation and Manufacturing Act tighten operational compliance costs for laser-produced plasma source operators.
- Optical Lithography:Mercury lamp and laser-based systems spanning g-line through ArF wavelengths. Nikon Corporation and Canon Inc. compete in this segment with specialized offerings for display panel and mature semiconductor applications.
- Maskless Lithography:Electron-beam and multi-beam systems writing patterns directly without photomasks. Prototyping flows and low-volume aerospace electronics in the United States employ maskless tools where photomask costs prove prohibitive.
- Nanoimprint Lithography:Mechanical pattern transfer using embossed templates rather than optical projection. Toshiba Memory and SK Hynix evaluate nanoimprint for 3D NAND fabrication where repetitive layer stacking favors template replication economics.
Extreme Ultraviolet Lithography leads on scale; Nanoimprint Lithography gains share fastest in memory-specific applications.
Application:
End-market performance requirements drive resolution, overlay, and contamination control specifications.
- Consumer Electronics:Smartphone and personal computing processors demanding maximum transistor density. Apple's A-series and M-series chip production at TSMC consumes the highest-resolution EUV capacity.
- Automotive Electronics:Advanced driver-assistance systems and powertrain controllers requiring extended temperature reliability. Bosch and Continental foundry partnerships specify mature-node lithography with enhanced process control protocols.
- Telecommunications:5G baseband and radio-frequency components balancing performance with power efficiency. Qualcomm and MediaTek designs split between leading-edge logic and specialty RF processes.
- Industrial Applications:Factory automation and power conversion equipment prioritizing longevity over density. Siemens and ABB supply chains source from European IDM fabrication networks.
Consumer Electronics leads on scale; Automotive Electronics leads on qualification rigor momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The semiconductor lithography equipment industry traces its commercial origins to post-war precision optics manufacturing in Germany and Japan, with subsequent scaling concentrated in Dutch lithography system engineering and East Asian foundry demand.
United States
Intel Foundry Services and Texas Instruments drive scanner procurement for domestic logic and analog fabrication. The EPA's fluorinated greenhouse gas reporting mandates under the American Innovation and Manufacturing Act tighten operational compliance for laser-produced plasma source operators. Arizona's Phoenix-Tucson corridor hosts expanding fabrication campuses where high-NA EUV tools are being commissioned for advanced node production.
Taiwan
TSMC's merchant foundry model concentrates global EUV scanner demand within a single procurement entity. The island's environmental regulator enforces industrial emissions controls aligned with international climate protocols. Hsinchu Science Park anchors the world's densest lithography equipment cluster, with tool density exceeding any comparable fabrication region.
South Korea
Samsung Foundry and SK Hynix split capital allocation between leading-edge logic and 3D NAND memory stack scaling. The Ministry of Trade, Industry and Energy coordinates domestic content requirements through its semiconductor equipment localization programs. Pyeongtaek's semiconductor complex qualifies high-NA EUV systems alongside multi-patterning ArF immersion fleets for vertical NAND fabrication.
Japan
Tokyo Electron and Nikon Corporation maintain captive demand for domestic lithography component and system production. METI coordinates export control alignment on advanced lithography components through its semiconductor equipment licensing framework. Kyushu's Kumamoto region hosts expanding fabrication capacity where mature-node equipment serves automotive and power semiconductor supply chains.
Germany
Carl Zeiss AG's optical component supremacy sustains critical supply relationships with scanner OEMs across all technology generations. The EU F-Gas Regulation imposes binding fluorinated gas phase-down quotas affecting EUV light source operations throughout European supply chains. Oberkochen and Jena anchor precision optics manufacturing clusters where aspheric mirror fabrication for EUV systems depends on specialized German supplier infrastructure.
Semiconductor Lithography Equipment Market Competitive Landscape
The competitive structure tilts toward technology-locked specialists with multi-decade barriers to entry. Scanner production concentrates around a single dominant system integrator controlling high-NA EUV architecture, while optical component supply depends on German precision manufacturing heritage. Two strategic archetypes define positioning: integrated platform vendors spanning light source through wafer stage engineering, and component specialists commanding irreplaceable optical or metrology subsystems. Dominant competitive moves include strategic partnerships securing exclusive supply relationships and capacity expansion at mirror polishing facilities to relieve multi-year order backlogs.
Within the integrated platform tier, ASML Holding N.V. and Nikon Corporation occupy positions representing distinct technology generation specializations, with the former exemplifying EUV system integration dominance and the latter representing mature-node immersion technology. Among component specialists, Carl Zeiss AG anchors optical subsystem supply, its German heritage and precision engineering capabilities creating structural positioning that scanner OEMs cannot readily replicate. NuFlare Technology Inc. represents the electron-beam and mask writing specialization archetype, serving niches where direct-write patterning displaces optical projection economics.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| NuFlare Technology Inc. |
| ASML Holding N.V. |
| Raith GmbH |
| Vistec Electron Beam GmbH |
| Nikon Corporation |
| JEOL Ltd. |
| Mycronic AB |
| Canon Inc. |
| Others |
Value Network & Pricing Analysis
Foundry procurement consolidation around 0.55NA EUV systems is forcing scanner OEMs to bundle gas abatement hardware with light source contracts, compressing margin pools for standalone component suppliers across Taiwan and Arizona fabrication clusters.
Pricing Analysis
Scanner OEMs deploy value-based pricing anchored to resolution capability and throughput metrics, with high-NA EUV tools commanding premiums over ArF immersion fleets. Price differentiation separates single-exposure systems from multi-patterning configurations, while after-sales service unbundling intensifies cost compression in mature-node segments. Pricing pressure stems from foundry capital allocation constraints as node migration timelines compress procurement windows. Memory manufacturers exhibit highest price sensitivity due to cyclical bit-demand volatility, whereas leading logic foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Germany coordinate hub-and-spoke logistics for EUV optics and laser source modules. Aspheric mirror fabrication draws from specialized German polishing infrastructure, while fluorinated gas supply rests on Japanese chemical producers and European quota allocations. Single-source vulnerability concentrates in high-NA optical component supply, where Carl Zeiss AG maintains irreplaceable metrology capabilities. Distribution runs through OEM-integrated service networks rather than independent channel partners, reflecting the complexity of vacuum system installation and plasma source maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor lithography equipment functions as a late-cycle quality market where foundry demand is shifting toward 0.55NA EUV specifications that guarantee single-exposure patterning fidelity at 8nm pitch.
For Market Incumbents: Deploy capacity addition in German mirror polishing facilities to relieve multi-year order backlogs constraining high-NA EUV scanner output. Secure exclusive supply relationships with fluorinated gas recovery system vendors before EU F-Gas Regulation phase-down tightens further. Threat of domestic lithography development programs in China and South Korea demands accelerated localization partnerships in those markets. For New Entrants and Emerging Players: Enter via computational lithography software specialization serving mask data preparation bottlenecks at mature-node foundries. White-space targets include India PLI scheme facilities requiring 28nm-class ArF immersion support, and electron-beam mask writing for low-volume aerospace prototyping. Go-to-market angle should emphasize machine learning-optimized optical proximity correction compressing design-to-tapeout cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists commanding irreplaceable optical or vacuum subsystems rather than integrated platform vendors facing capital intensity ceilings. Long-term viability favors German and Japanese precision engineering heritage with multi-decade customer lock-in. Signal to watch is high-NA EUV qualification timelines at Samsung Pyeongtaek and TSMC Hsinchu as inflection indicators for 2nm-class capacity ramps.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Capacity Expansion | ASML's 0.55NA scanner deployments at TSMC and Samsung compress multi-patterning process steps. |
| Fluorinated Gas Recovery Integration | Closed-loop abatement system bundling preempts EPA reporting mandates under the American Innovation and Manufacturing Act. |
| Computational Lithography Partnership | Machine learning OPC convergence with EDA vendors accelerates mask data preparation for leading-edge logic. |
| Mirror Polishing Facility Expansion | Carl Zeiss AG capacity addition in Oberkochen relieves aspheric substrate bottlenecks constraining scanner output. |
| India PLI Scheme Localization | ArF immersion fleet deployment at emerging 28nm-class facilities diversifies geographic demand concentration. |
Research Methodology
Coverage spans Taiwan, South Korea, the United States, Japan, and Germany, with primary inputs from each region's fabrication cluster. The analysis combines interviews with foundry procurement directors, lithography tool engineering leads, and EPA regulatory compliance officers with secondary validation from SEC filings, METI equipment export license data, and EU F-Gas Regulation quota disclosures. Bottom-up and top-down triangulation cross-checks scanner shipment tallies against foundry capital expenditure announcements.
Granularity-level modeling operates at product type, end user, technology, and application dimensions, with additional segmentation by node generation and regional regulatory cluster. Value outputs across the analysis window derive from equipment average selling price bands by technology generation, adjusted for service contract bundling trends. Forecast inputs incorporate foundry node migration timelines, memory stack scaling roadmaps, and fluorinated gas quota phase-down schedules.
Inputs from foundry capital expenditure disclosures and OEM order backlogs were available through the study window; gaps in Chinese domestic lithography development progress introduce uncertainty bands around supplier concentration scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market