
 Active Vibration Control Market | 2026-2036
Active Vibration Control Market Size, Share, and Industry Trends Forecast 2026-2036
Active Vibration Control Market Insights
China's eastern manufacturing corridor is reshaping competitive dynamics in active vibration control, with new production capacity for piezoelectric actuators and servo controllers clustering around Shanghai and Suzhou. Parker Hannifin Corporation leverages its hydraulic actuator expertise to dominate heavy industrial applications across Asia-Pacific. Honeywell International Inc. anchors aerospace-grade vibration suppression systems through integrated sensor-controller architectures. Moog Inc. specializes in high-bandwidth electromechanical actuators for defense and satellite platforms, sustaining premium positioning in mission-critical segments.
Active vibration control encompasses electromechanical systems that generate real-time counter-forces to attenuate unwanted mechanical oscillations, typically operating across frequency ranges from 0.1 Hz to 10 kHz with closed-loop feedback latencies below 1 millisecond. Piezoelectric technology leads commercial deployment due to millisecond response times and compact form factors, while electromagnetic systems capture expanding share in large-structure applications where stroke length exceeds 50 millimeters. Component-level margin pools concentrate in controllers and signal processors, where firmware integration creates switching costs, whereas sensor manufacturing faces commoditization from standardized MEMS accelerometers.
The EU Machinery Directive, ISO 10816 standards, and China's GB/T vibration measurement protocols collectively tighten performance verification requirements for rotating equipment and precision manufacturing tools. FDA 21 CFR Part 820 quality system regulations extend into diagnostic imaging equipment, where vibration isolation directly impacts image resolution compliance. Stakeholders must monitor evolving certification timelines across EMA, NMPA, and FDA jurisdictions as regulatory divergence threatens platform standardization strategies for multinational OEMs.
Market Dynamics
Precision manufacturing in China's eastern corridor and aerospace production in Germany are compressing vibration tolerance thresholds, forcing real-time adaptive damping into standard equipment specifications rather than premium add-ons.
Growth Catalysts
- EU Machinery Directive compliance mandates:Rotating equipment manufacturers across Germany and France must install active damping systems to meet revised ISO 10816 vibration thresholds, creating baseline demand for electromechanical actuators.
- Semiconductor fabrication expansion:Lithography tool OEMs in Taiwan and South Korea require sub-nanometer stability, driving specification of piezoelectric stacks with millisecond feedback loops.
- High-speed rail deployment:Track-borne vibration mitigation systems are becoming standard on China's expanding passenger rail network, with Suzhou-based actuator suppliers scaling production to match installation timelines.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity PZT materials depend on processing facilities concentrated in Japan and China, exposing actuator manufacturers to input cost volatility and export licensing friction.
- Electromagnetic actuator technical limitations:Coil-based systems face stroke-length constraints below 50 millimeters, restricting deployment in large civil engineering structures where passive tuned mass dampers remain economically dominant.
- Regulatory fragmentation across FDA, EMA, and NMPA:Diagnostic imaging equipment must satisfy divergent vibration isolation test protocols, inflating certification timelines and preventing platform standardization for multinational OEMs.
Strategic Opportunities
- India's underpenetrated precision manufacturing base:The PLI scheme for electronics and semiconductor assembly is attracting fabrication facilities that will require vibration isolation for cleanroom operations, with domestic supply chains still nascent.
- Convergence of edge computing and adaptive control:Onboard signal processing is enabling distributed vibration suppression without centralized controller hardware, reducing wiring complexity in satellite and defense platforms.
- MEA regulatory tailwinds:Saudi Arabia's SFDA and UAE's MOHAP are adopting imaging equipment standards that reference ISO vibration limits, creating compliance-driven replacement cycles for imported diagnostic systems.
Industry Challenges
- Multiphysics simulation talent scarcity:Controller firmware development requires expertise spanning structural dynamics, signal processing, and real-time embedded systems, with universities producing fewer cross-trained engineers than industry demand.
- Legacy equipment integration complexity:Retrofitting active damping into existing machine tools and production lines demands custom mechanical interfaces and control architecture adaptations that extend deployment timelines.
- Certification timeline unpredictability:EMA and NMPA review cycles for medical device vibration isolation subsystems lack published duration benchmarks, complicating revenue forecasting for component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Vibration Control Market |
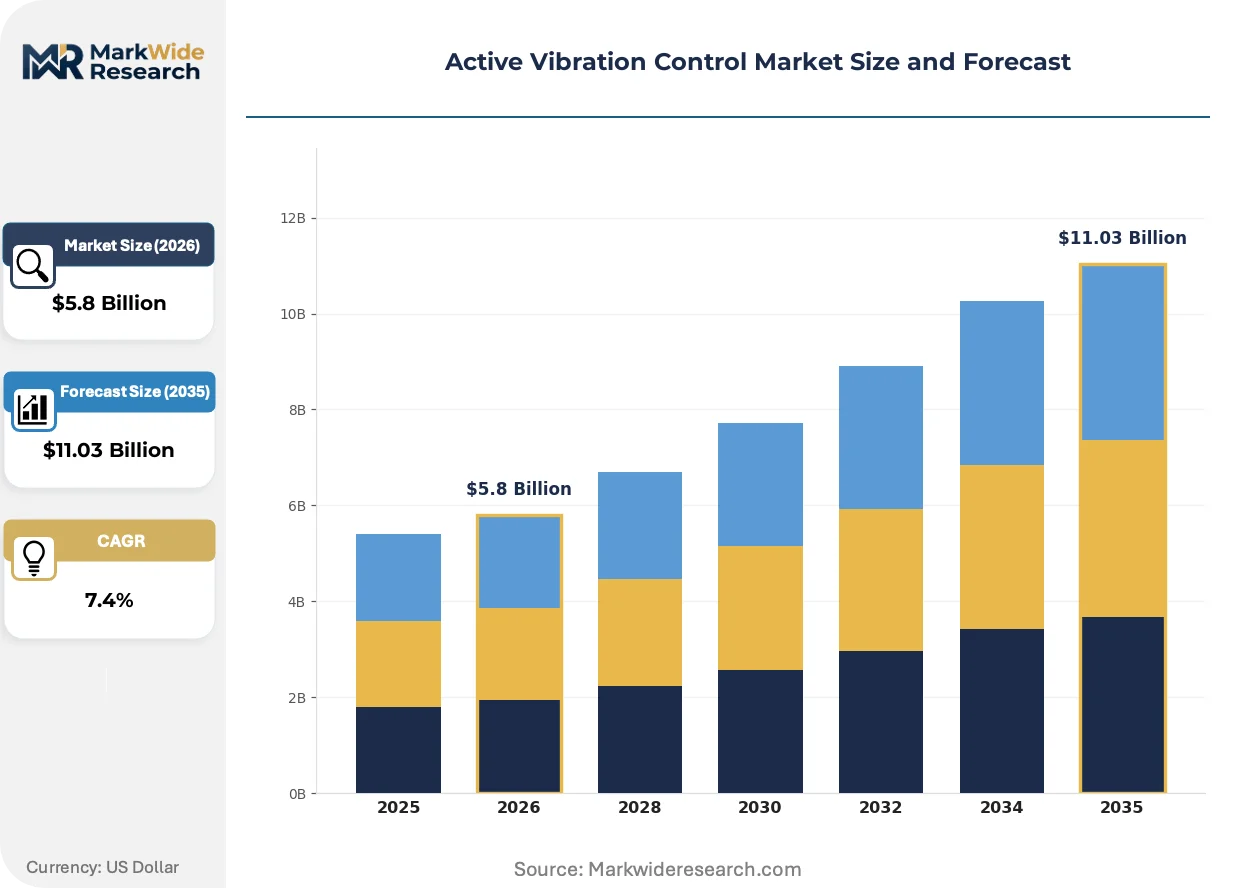
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Piezoelectric, Electromagnetic, Hydraulic, Pneumatic, Magnetostrictive, Servo Component: Sensor, Actuator, Controller, Amplifier, Signal Processor, Power Supply Application: Aerospace, Consumer Electronics, Renewable Energy, Construction Equipment, Marine Vessels, Robotics End User: OEMs, Research Laboratories, Automotive Suppliers, Military & Defense, Industrial Manufacturers, Testing Centers |
| Companies Covered | Parker Hannifin Corporation, Honeywell International Inc., Moog Inc., Hutchinson SA, Trelleborg AB, Fabreeka International Inc., Terma A/S, Faurecia Creo AB, Ultra Electronics Holdings Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Vibration Control Market Trends and Innovations
Control architectures are decentralizing as edge computing migrates into actuator housings, collapsing the traditional separation between sensing, processing, and force generation into integrated smart modules.
Adaptive feedforward algorithms are migrating from centralized DSP platforms into embedded microcontroller firmware within individual piezoelectric actuators. Semiconductor lithography OEMs in Taiwan are specifying these intelligent modules for next-generation EUV tool bases. This compression of the control loop is eliminating cabinet-mounted controller hardware and reducing installation footprint by consolidating three functional layers into one.
REACH substance restrictions on lead-containing piezoceramics are forcing European actuator manufacturers to qualify alternative compositions such as potassium sodium niobate. The industrial consequence is a two-year qualification gap during which supply chains must dual-source legacy and compliant materials. German automotive test rig builders are most affected, delaying new platform launches while awaiting ceramic reliability data.
Buying committees in precision manufacturing are unbundling vibration isolation from machine tool procurement, treating active damping as a separately sourced subsystem with independent specification and vendor selection. Japanese machine tool distributors are responding by establishing dedicated vibration control application engineering teams. This pattern is most visible in South Korea's display panel fabrication sector, where facilities engineers now issue standalone RFPs for cleanroom floor isolation.
Active Vibration Control Market Segmentation
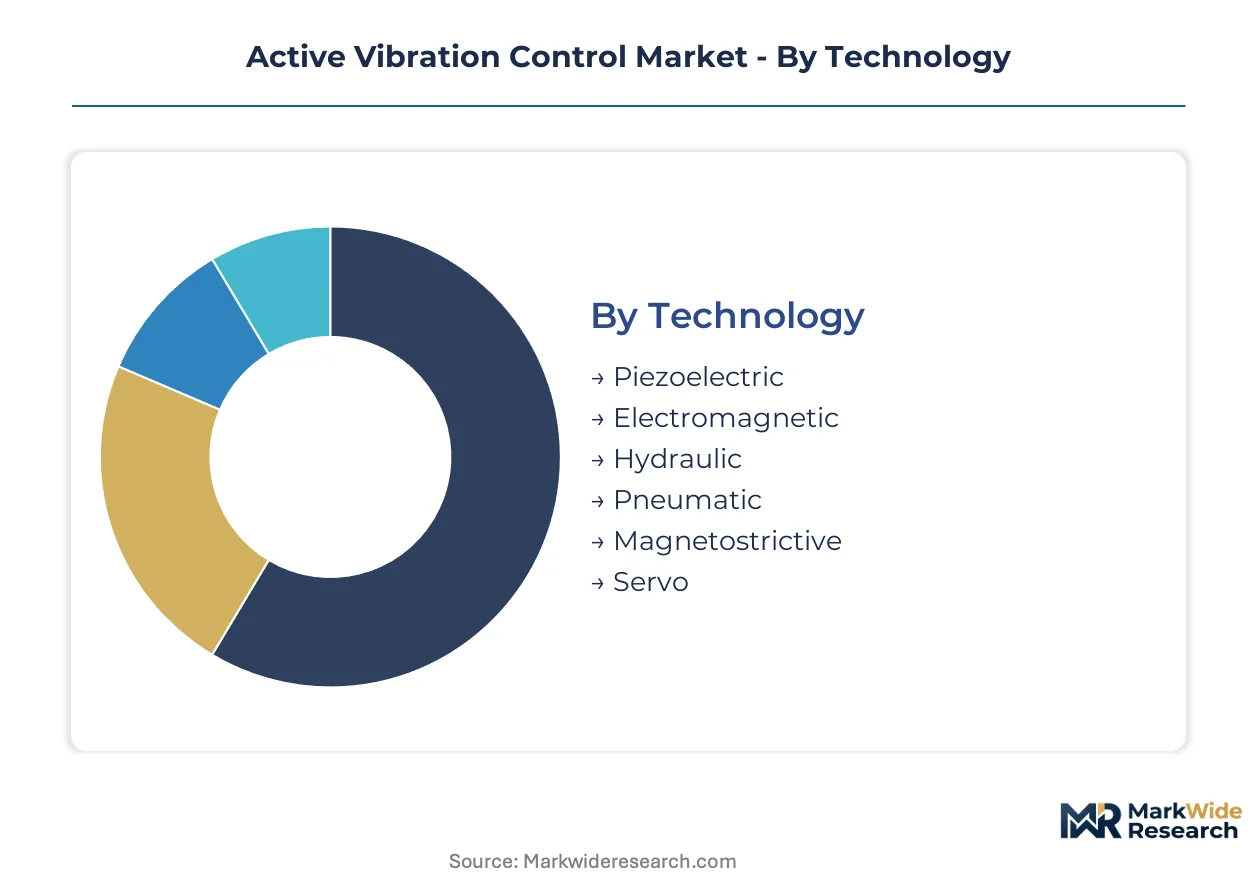
Technology choice determines response latency and force bandwidth, creating distinct procurement cycles across precision manufacturing and heavy industrial verticals. Component-level sourcing strategies diverge sharply between integrated system vendors and modular subsystem suppliers. Application requirements span sub-nanometer semiconductor stability to meter-scale civil engineering damping, fragmenting specification standards and certification pathways.
Technology:
Piezoelectric systems turn over fastest in semiconductor and aerospace procurement cycles, while hydraulic installations persist for decades in heavy infrastructure.
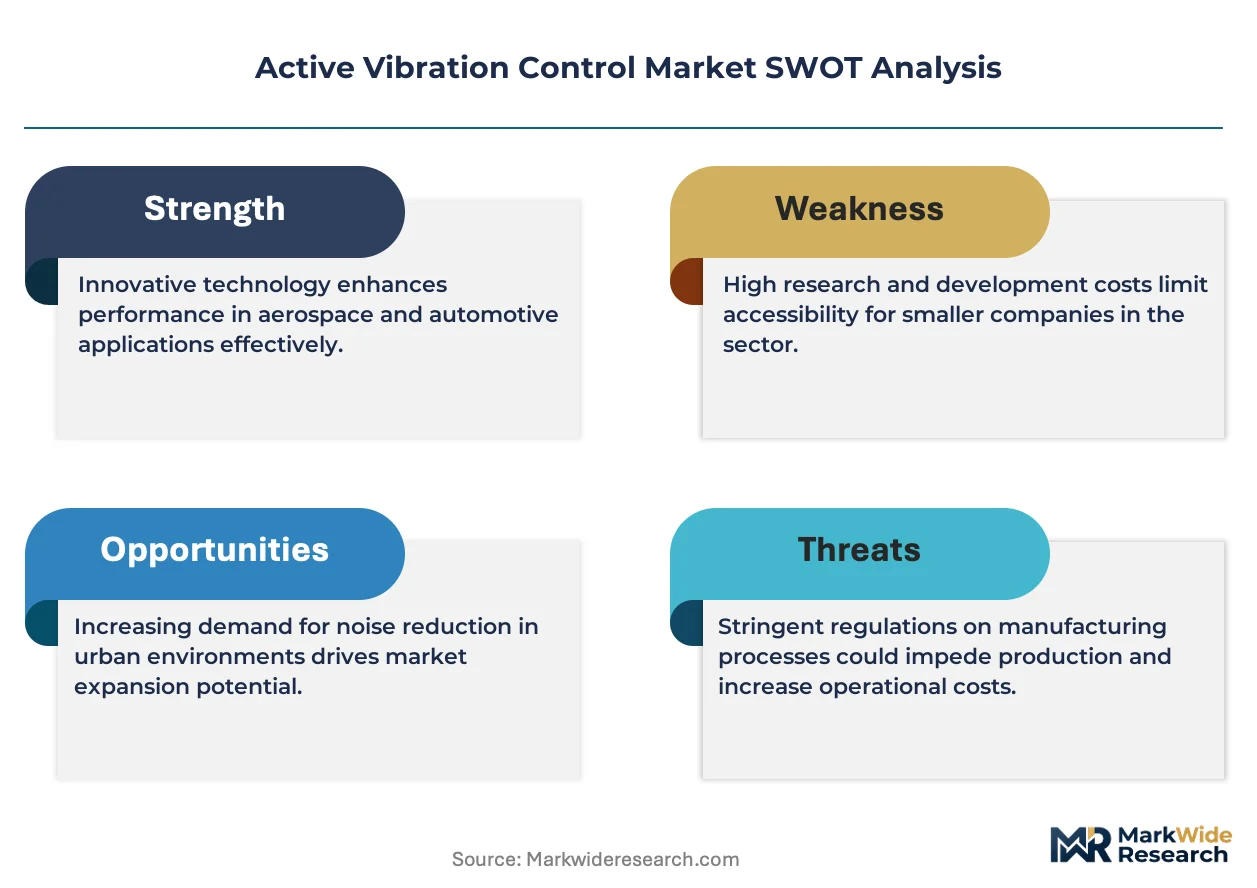
- Piezoelectric:Ceramic-stack actuators deliver sub-millisecond response times with nanometer positioning resolution. Taiwan-based lithography tool OEMs specify these for EUV wafer stage stabilization, where thermal drift tolerance now sits below 0.1 nanometers.
- Electromagnetic:Voice-coil and linear motor architectures achieve stroke lengths exceeding 50 millimeters with moderate bandwidth. China's high-speed rail expansion drives specification for track-borne electromagnetic dampers on passenger lines radiating from Shanghai.
- Hydraulic:High-force actuation for large civil structures and marine platforms, with service intervals measured in years rather than months.
- Pneumatic:Compressed-air systems for industrial automation with lower precision requirements and reduced capital cost.
- Magnetostrictive:Terfenol-D and similar alloys convert magnetic fields to mechanical strain for specialized defense and energy applications.
- Servo:Closed-loop electromechanical systems integrating motor, encoder, and drive electronics for robotics and precision manufacturing.
Piezoelectric technology anchors the volume base in precision applications while electromagnetic systems gain share at the steepest rate in transportation infrastructure.
Component:
Margin concentration follows firmware integration depth, with controllers commanding premium pricing against commoditized sensor hardware.
- Controller:Real-time DSP and FPGA platforms execute adaptive algorithms with feedback latencies below 1 millisecond. German automotive test rig builders source these from specialized motion control vendors to meet ISO 10816 compliance mandates.
- Actuator:Force-generating elements spanning piezoelectric stacks, electromagnetic coils, and hydraulic cylinders. Suzhou-based suppliers are scaling piezoelectric actuator production to match China's high-speed rail installation timelines.
- Sensor:MEMS accelerometers and proximity probes measuring vibration amplitude across 0.1 Hz to 10 kHz bandwidths.
- Amplifier:High-voltage drive electronics for piezoelectric stacks requiring hundreds of volts at millisecond switching speeds.
- Signal Processor:Analog-to-digital conversion and filtering hardware conditioning raw sensor outputs for control algorithms.
- Power Supply:Conditioned electrical infrastructure delivering stable voltage and current to distributed actuator networks.
Controllers and actuators together capture the dominant margin pool, with sensors facing persistent price pressure from standardized MEMS sourcing.
Application:
Specification authority sits with distinct buyer types across each vertical, from facilities engineers in semiconductor to procurement departments in renewable energy.
- Aerospace:Flight control surface damping and satellite payload isolation requiring mission-critical reliability certification. Honeywell and Moog dominate specification for commercial aviation and defense platforms respectively.
- Consumer Electronics:Compact vibration suppression for smartphone camera modules and hard disk drives. South Korean and Chinese handset OEMs drive volume demand for millimeter-scale piezoelectric dampers.
- Renewable Energy:Gearbox and drivetrain damping for wind turbines, with offshore installations demanding corrosion-resistant actuation systems.
- Construction Equipment:Operator cabin isolation and structural damping for excavators and cranes.
- Marine Vessels:Engine mount stabilization and hull damping systems for commercial shipping and naval applications.
- Robotics:End-effector vibration suppression for precision assembly and surgical systems.
Aerospace anchors the premium pricing tier while consumer electronics expands most quickly on volume scale.
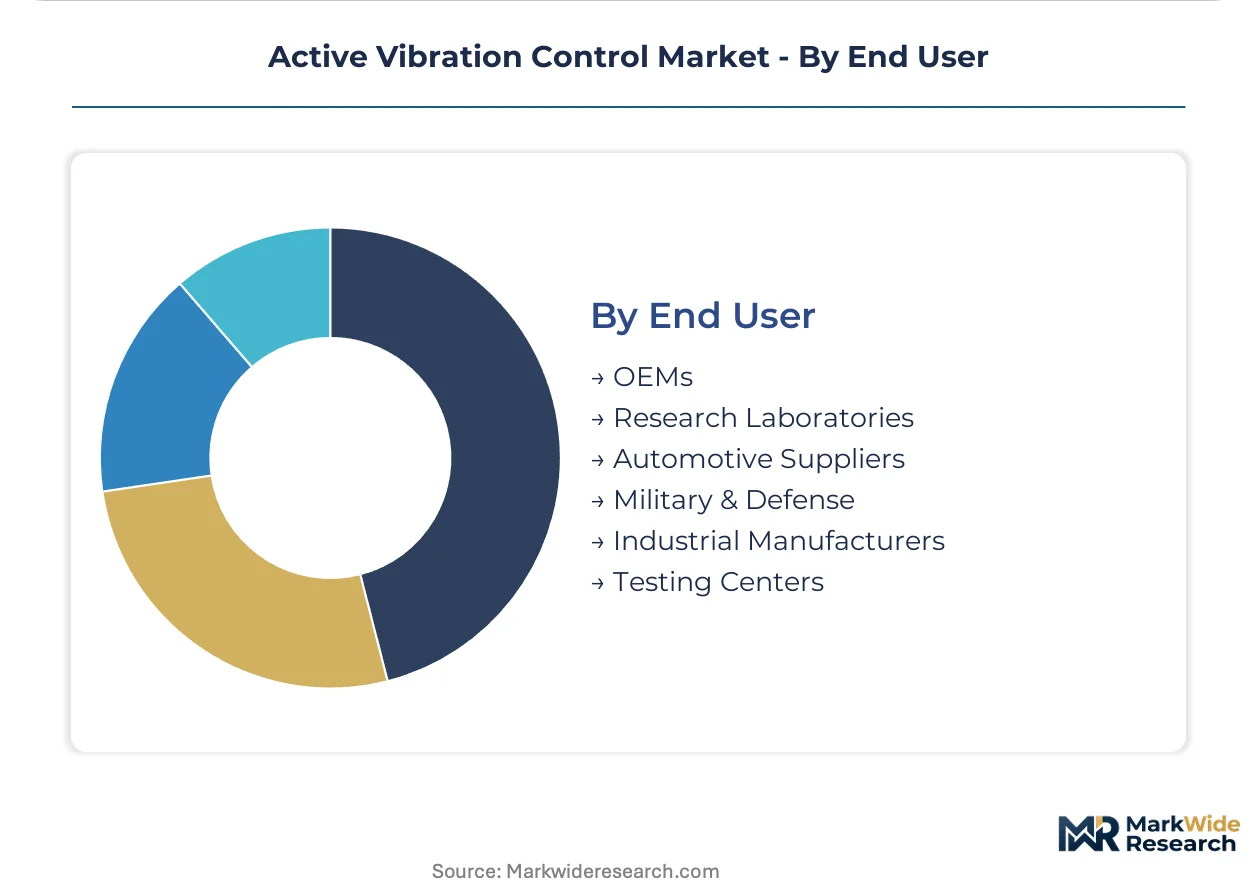
End User:
Procurement sophistication varies from integrated system sourcing by OEMs to fragmented spot purchasing by testing centers.
- OEMs:Original equipment manufacturers integrating active damping as standard specification rather than optional add-on. German machine tool builders now embed piezoelectric isolation in premium machining centers.
- Industrial Manufacturers:Retrofit installations for existing production lines, requiring custom mechanical interfaces and extended deployment timelines.
- Automotive Suppliers:Tier-1 and Tier-2 component producers specifying test rig vibration isolation for powertrain validation.
- Military & Defense:Satellite, naval, and ground vehicle platforms with mission-critical reliability requirements and extended qualification cycles.
- Research Laboratories:Academic and government facilities with bespoke specifications and limited volume scale.
- Testing Centers:Independent validation facilities sourcing modular systems for contract measurement services.
OEMs anchor the volume base with integrated procurement while industrial manufacturers represent the steepest expansion trajectory as retrofit demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail network expansion and Germany's precision manufacturing corridors are underwriting the geographic concentration of active vibration control demand. Industrial clusters in Taiwan and South Korea anchor semiconductor-grade stabilization requirements. Saudi Arabia's giga-project pipeline and India's electronics manufacturing incentives are generating new procurement baselines.
China
High-speed rail deployment along the Shanghai-Nanjing-Hangzhou triangle and semiconductor fabrication in Suzhou drive specification of electromagnetic track dampers and piezoelectric wafer-stage stabilizers. GB/T vibration measurement protocols tighten compliance thresholds for rotating equipment. The Yangtze River Delta manufacturing corridor concentrates actuator production capacity to match installation timelines for passenger rail and EUV lithography tool bases.
Germany
Aerospace production in Bavaria and automotive test rig construction across Baden-Württemberg compress vibration tolerance thresholds for flight control surfaces and powertrain validation equipment. The EU Machinery Directive mandates active damping installation for rotating machinery to meet revised ISO 10816 standards. Stuttgart's precision engineering cluster hosts qualification programs for REACH-compliant piezoceramic alternatives, delaying new platform launches pending ceramic reliability data.
South Korea
Display panel fabrication near Seoul and memory semiconductor production in Pyeongtaek require sub-nanometer stability for lithography and inspection equipment. MFDS imaging equipment standards reference ISO vibration limits, creating compliance-driven replacement cycles. The Seoul Capital Area concentrates buying committee authority for standalone vibration isolation RFPs, unbundling active damping from machine tool procurement.
India
Electronics assembly under the PLI scheme and emerging semiconductor fabrication in Gujarat and Karnataka will require cleanroom vibration isolation for wafer processing and packaging operations. BIS standards adoption for industrial equipment is tightening performance verification requirements. Domestic supply chains for piezoelectric actuators and servo controllers remain nascent, forcing reliance on imported subsystems during facility commissioning.
Saudi Arabia
NEOM giga-projects and diagnostic imaging equipment imports are generating demand for structural damping and medical device vibration isolation. SFDA adoption of imaging equipment standards referencing ISO vibration limits is accelerating compliance-driven replacement cycles. The Eastern Province industrial cities are concentrating construction equipment procurement, with operator cabin isolation becoming standard specification for excavators and cranes.
Active Vibration Control Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying force-generating elements and signal conditioning hardware. The vendor base organizes into three tiers: multinational conglomerates with cross-industry actuator portfolios, mid-cap specialists focused on single technology modalities, and regional fabricators serving retrofit installations. Strategic moves concentrate on technology licensing for piezoelectric ceramic formulations and capacity expansion for electromagnetic actuator coils serving transportation infrastructure.
Within the integrated systems tier, Parker Hannifin Corporation, Honeywell International Inc., and Moog Inc. occupy positions spanning industrial hydraulics, aerospace avionics, and defense electromechanics respectively. These entities exemplify archetype differentiation through embedded controller architectures and mission-critical reliability certification. Their geographic footprints—Cleveland-based, Charlotte-based, and East Aurora-based respectively—mirror the regional concentration of heavy industry, commercial aviation, and defense procurement.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Honeywell International Inc. |
| Moog Inc. |
| Hutchinson SA |
| Trelleborg AB |
| Fabreeka International Inc. |
| Terma A/S |
| Faurecia Creo AB |
| Ultra Electronics Holdings Plc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Japanese high-purity PZT ceramic processing is forcing actuator manufacturers toward dual-sourcing strategies while compressing margins across piezoelectric controller tiers. This supply tightness simultaneously elevates input costs for precision damping systems and accelerates qualification timelines for REACH-compliant ceramic alternatives in European manufacturing corridors.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, industrial-standard, and economy retrofit levels dominates procurement negotiations. Price differentiation centers on ISO 10816 compliance certification and firmware integration depth, with aerospace-grade controllers commanding substantial premiums over MEMS-sensor bundles. Cost compression in the economy retrofit tier is intensifying because of standardized MEMS accelerometer commoditization. Automotive test rig builders exhibit highest price sensitivity due to batch procurement volumes, while satellite platform integrators remain least sensitive given mission-critical reliability requirements.
Supply Chain Analysis
Export-control restrictions on high-purity piezoelectric ceramics and precision motion controllers limit technology flows between Japan, China, and Western defense contractors. Raw material dependencies center on lead zirconate titanate powders, Terfenol-D magnetostrictive alloys, and high-voltage amplifier semiconductors. Single-source vulnerability concentrates in Japanese PZT processing facilities, exposing actuator manufacturers to licensing friction and allocation delays. Distribution runs through specialized motion control distributors serving OEM procurement teams and direct sales forces targeting defense platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active vibration control sits in early-cycle expansion as EU Machinery Directive mandates convert adaptive damping from premium add-on to baseline specification across German and French rotating equipment fleets.
For Market Incumbents: Build firmware-integration moats by embedding adaptive algorithms directly into piezoelectric actuator housings, collapsing controller hardware layers. Deepen backward integration into high-voltage amplifier electronics to defend margin pools against sensor commoditization. Expand Suzhou-based production capacity to match China's high-speed rail installation timelines and semiconductor fabrication buildout. Certification investment in REACH-compliant ceramic alternatives protects European market access against substance restriction tightening. For New Entrants and Emerging Players: India's underpenetrated precision manufacturing base offers white-space opportunity as PLI-scheme electronics assembly and emerging semiconductor fabrication create cleanroom vibration isolation demand. Target Gujarat and Karnataka wafer processing facilities with imported-subsystem partnerships during domestic supply chain gestation. Pursue edge-computing convergence angle for satellite and defense distributed control architectures, offering smart actuator modules that eliminate centralized controller hardware. Channel strategy should emphasize application engineering partnerships with Japanese machine tool distributors unbundling vibration isolation from core equipment procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controller firmware vendors with embedded algorithm licensing and long-term service contracts. Five-to-ten year viability favors specialists spanning structural dynamics, signal processing, and real-time embedded systems expertise rather than pure hardware fabricators. Acquisition target archetype: mid-cap piezoelectric actuator manufacturers with qualified REACH-compliant ceramic pipelines and established aerospace certification. Monitor EMA and NMPA review cycle duration benchmarks as inflection signal—published certification timelines would accelerate multinational OEM platform standardization and consolidate procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ceramic Qualification | European actuator manufacturers secure market access ahead of lead-content substance restrictions. |
| Edge Computing Module Integration | Taiwan lithography OEMs specify intelligent piezoelectric actuators collapsing three-layer control architectures. |
| Dual-Source PZT Supply Arrangement | Japanese and Chinese ceramic processors reduce allocation risk for high-volume rail and semiconductor customers. |
| Application Engineering Team Expansion | Japanese distributors capture unbundled vibration isolation procurement in South Korean display fabrication. |
| SFDA Certification Pathway Investment | Diagnostic imaging suppliers accelerate Saudi Arabian compliance-driven replacement cycle participation. |
Research Methodology
Desk research of customs trade databases, ISO standards documentation, and SEC equipment manufacturer filings preceded structured interviews with aerospace platform engineers, semiconductor facilities managers, automotive test rig procurement leads, and medical device regulatory affairs specialists. Primary fieldwork combined plant-level assessments of Suzhou actuator production capacity with validation against EU Machinery Directive implementation timelines and NMPA certification process documentation. Bottom-up demand modeling across rail, semiconductor, and aerospace verticals triangulated against top-down equipment manufacturer revenue attribution.
Assumptions held fixed include continued enforcement of ISO 10816 vibration thresholds across European rotating equipment, sustained Chinese high-speed rail network expansion, and stable REACH substance restriction timelines for lead-containing piezoceramics. Variables tested include electromagnetic versus piezoelectric technology substitution rates in transportation infrastructure, edge computing adoption velocity in satellite platforms, and regulatory divergence across FDA, EMA, and NMPA medical device certification pathways. CAGRs derived from segment-level demand buildups incorporating lithography tool installation forecasts, passenger rail rolling stock procurement schedules, and wind turbine gearbox damping replacement cycles.
Practitioners should monitor ceramic export licensing decisions, REACH alternative material reliability data publication, and EMA/NMPA certification duration benchmark releases for early signals of forecast revision necessity. Material shifts in Japanese PZT processing capacity utilization, EU Machinery Directive enforcement intensity, or semiconductor fabrication capital expenditure commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market