
 Biopotential Sensor Market | 2026-2036
Biopotential Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Biopotential Sensor Market Outlook
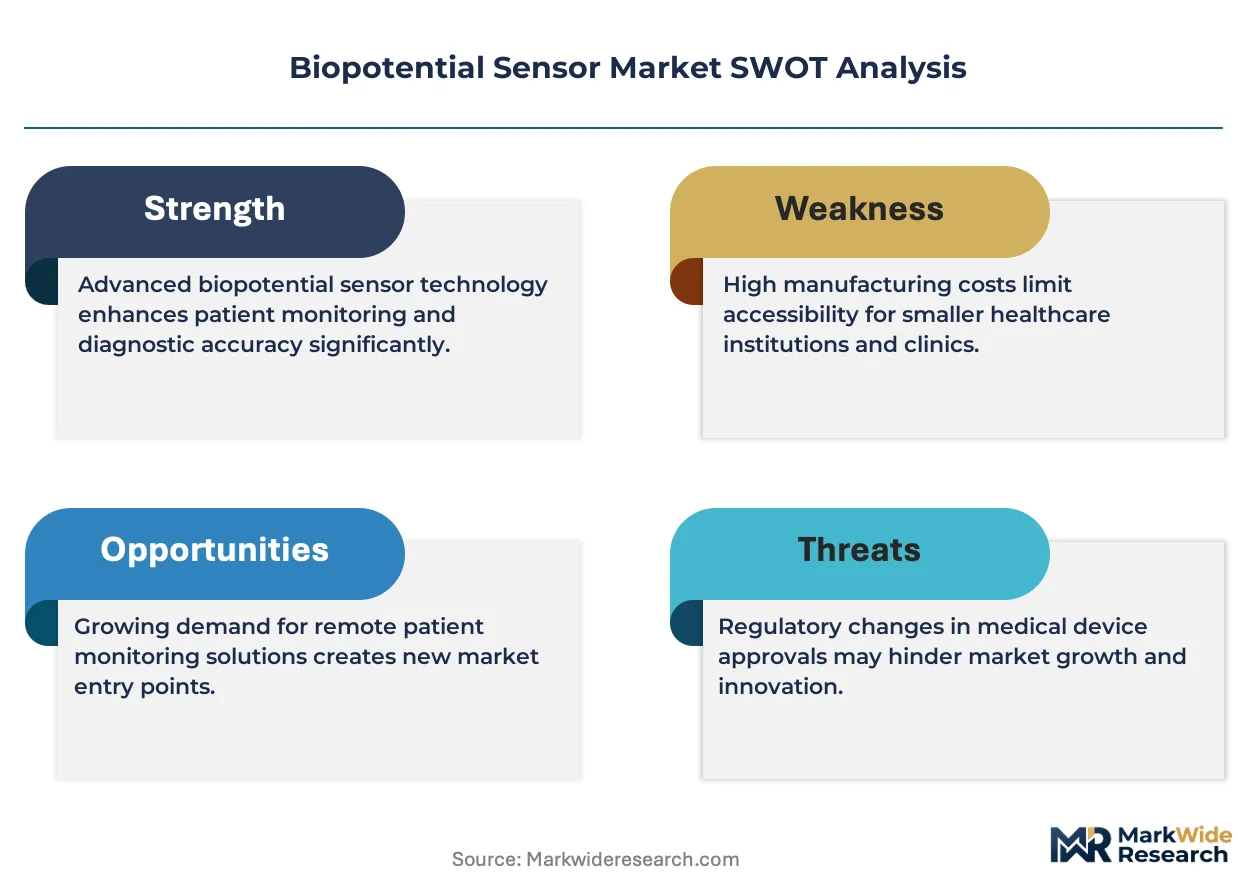
Modular electrode arrays with detachable wireless transmitters is recalibrating how hospitals evaluate total cost of ownership against single-use disposable configurations. Texas Instruments Incorporated leverages its analog front-end portfolio to anchor supply relationships with original equipment manufacturers across North America. Analog Devices, Inc. competes through precision instrumentation amplifiers optimized for microvolt-level signal fidelity in electromyography applications. Medtronic plc dominates the implantable segment with deep regulatory experience and captive access to electrophysiology catheter labs.
Biopotential sensors detect and amplify minute electrical signals generated by cellular depolarization in cardiac, neural, and muscular tissue, typically capturing microvolt-to-millivolt potentials through Ag/AgCl electrodes with input impedance exceeding 10 megaohms for clinical-grade fidelity. ECG sensors occupy the largest revenue share given established reimbursement for ambulatory arrhythmia monitoring, while EEG sensors represent the fastest-expanding category as closed-loop neurostimulation trials multiply across academic medical centers. Wireless technology commands premium positioning over wired alternatives in home care and sports medicine, though implantable configurations concentrate the highest per-unit margins due to surgical placement requirements and extended regulatory validation cycles.
FDA digital health pre-certification and EU MDR Class IIa technical documentation requirements are elevating barriers for new entrants without established quality management systems or clinical evidence libraries. ISO 13485 certification and IEC 60601-1-2 electromagnetic compatibility standards function as table-stakes credentials that channel procurement decisions toward vertically integrated manufacturers with in-house testing laboratories. Stakeholders must weigh accelerated FDA breakthrough device designations against lengthening EU notified body capacity constraints when sequencing geographic market entry.
Market Dynamics
Wireless ambulatory ECG systems are compressing hospital procurement cycles as reimbursement pathways for remote patient monitoring solidify across multiple jurisdictions, forcing incumbent wired-device manufacturers to restructure pricing architectures or cede cardiology service lines.
Growth Catalysts
- FDA breakthrough device designation:Compressed review timelines for AI-enabled arrhythmia detection algorithms are accelerating commercialization of next-generation Holter monitors in the United States.
- Ambulatory surgical centers:Expansion of same-day electrophysiology procedures is creating dedicated procurement budgets for disposable biopotential electrode arrays.
- Sports medicine clinics:Wireless EMG systems for biomechanical analysis are penetrating professional athletic training facilities and university research laboratories.
Market Restraints
- Silver chloride electrode costs:Volatility in precious metal pricing directly squeezes margins for disposable Ag/AgCl consumables used in clinical-grade ECG applications.
- EU notified body capacity:Lengthening MDR Class IIa technical documentation review queues are delaying market entry for novel wearable cardiac sensors in European markets.
- Dry electrode fidelity gaps:Capacitive coupling alternatives struggle to match wet-electrode signal-to-noise ratios in high-impedance electromyography applications.
Strategic Opportunities
- Closed-loop neurostimulation:EEG-fusion algorithms enabling real-time seizure prediction are opening premium pricing tiers in academic epilepsy centers.
- Home-based sleep diagnostics:Polysomnography-grade wireless sensors are displacing laboratory-based overnight studies in obstructive sleep apnea workflows.
- Japan's aging demographics:METI incentives for preventive cardiac monitoring are expanding reimbursable indications for ambulatory ECG in community care settings.
Industry Challenges
- Biomedical signal processing expertise:Scarcity of engineers proficient in adaptive filtering for motion artifact suppression is constraining R&D velocity at mid-tier sensor developers.
- IEC 60601-1-2 electromagnetic compatibility:Escalating test protocol complexity for wireless coexistence verification is extending certification timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopotential Sensor Market |
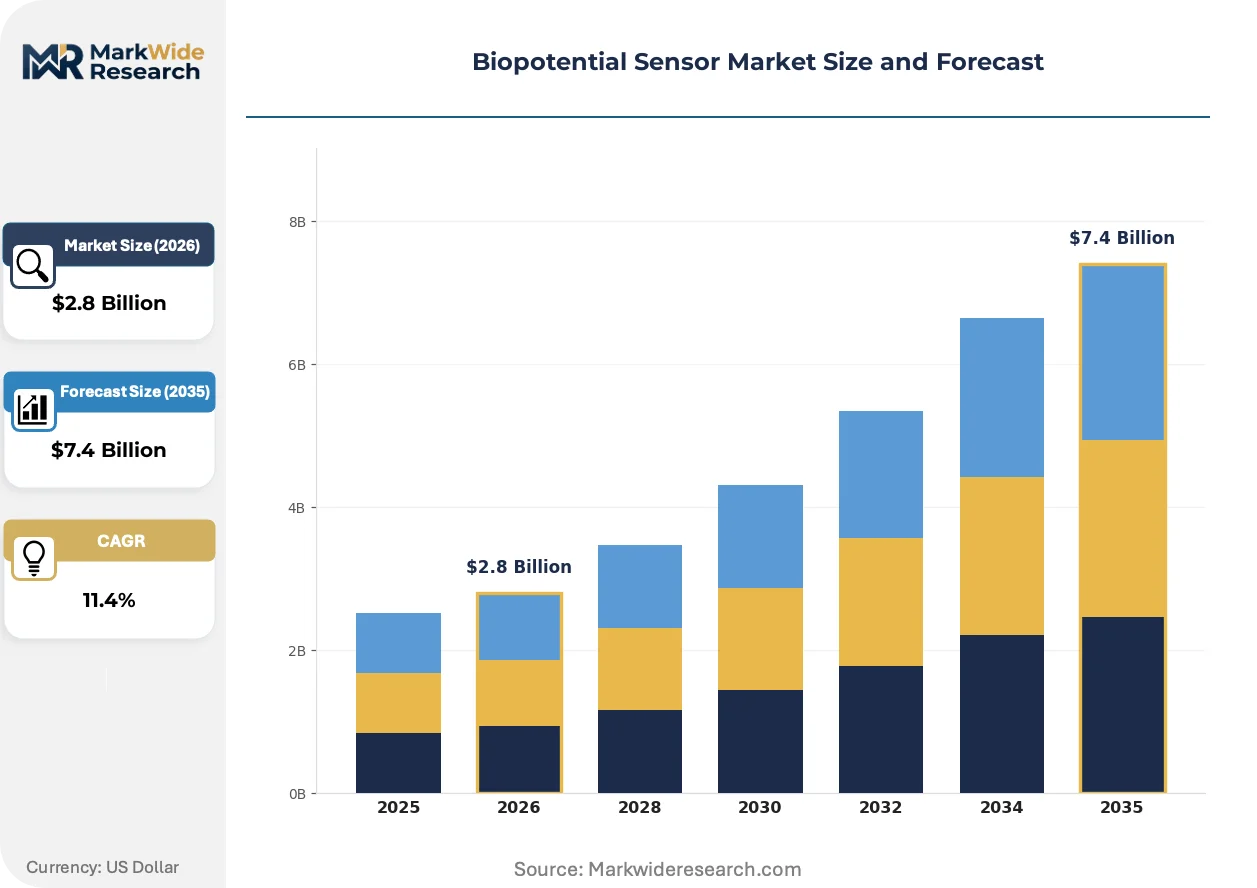
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ECG Sensors, EEG Sensors, EMG Sensors, Nerve Sensors Technology: Wireless, Wired, Flexible, Implantable End User: Hospitals, Research Laboratories, Fitness Centers, Home Care Application: Cardiology, Neurology, Rehabilitation, Sports Medicine |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., Medtronic plc, NXP Semiconductors N.V., Maxim Integrated, ams OSRAM, Siemens Healthineers AG, Philips Healthcare, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopotential Sensor Market Strategic Shifts
Artifact-rejection algorithms and substrate-level integration of analog front-end circuitry are compressing form factors while elevating signal fidelity thresholds, enabling new deployment contexts previously inaccessible to conventional biopotential acquisition hardware.
Flexible printed circuit electrodes with micro-structured dry-contact interfaces are rewriting performance benchmarks for long-term wearability. Sports medicine practitioners and occupational health clinics are adopting these configurations for multi-day continuous monitoring protocols. The technology is rewriting competitive positioning by collapsing the historical trade-off between patient comfort and clinical-grade signal integrity.
EU MDR technical documentation requirements for Class IIa active implantable devices are elevating clinical evidence burdens for novel cardiac sensors seeking CE marking. Manufacturers must now submit prospective registry data rather than retrospective case series, extending pre-market investment horizons. Wireless patch-based monitors with extended wear durations face the most acute compliance cost inflation as notified bodies scrutinize battery safety and biocompatibility matrices.
Health system procurement committees are unbundling sensor hardware from analytics software, forcing vendors to demonstrate standalone value or accept margin compression. Hospital IDNs in Germany and the United States are piloting direct-to-manufacturer contracting for electrode consumables, bypassing traditional distributor markups. This behavioral shift is most visible in cardiology service lines where ambulatory monitoring volumes have exceeded inpatient diagnostic thresholds.
Biopotential Sensor Market Segmentation
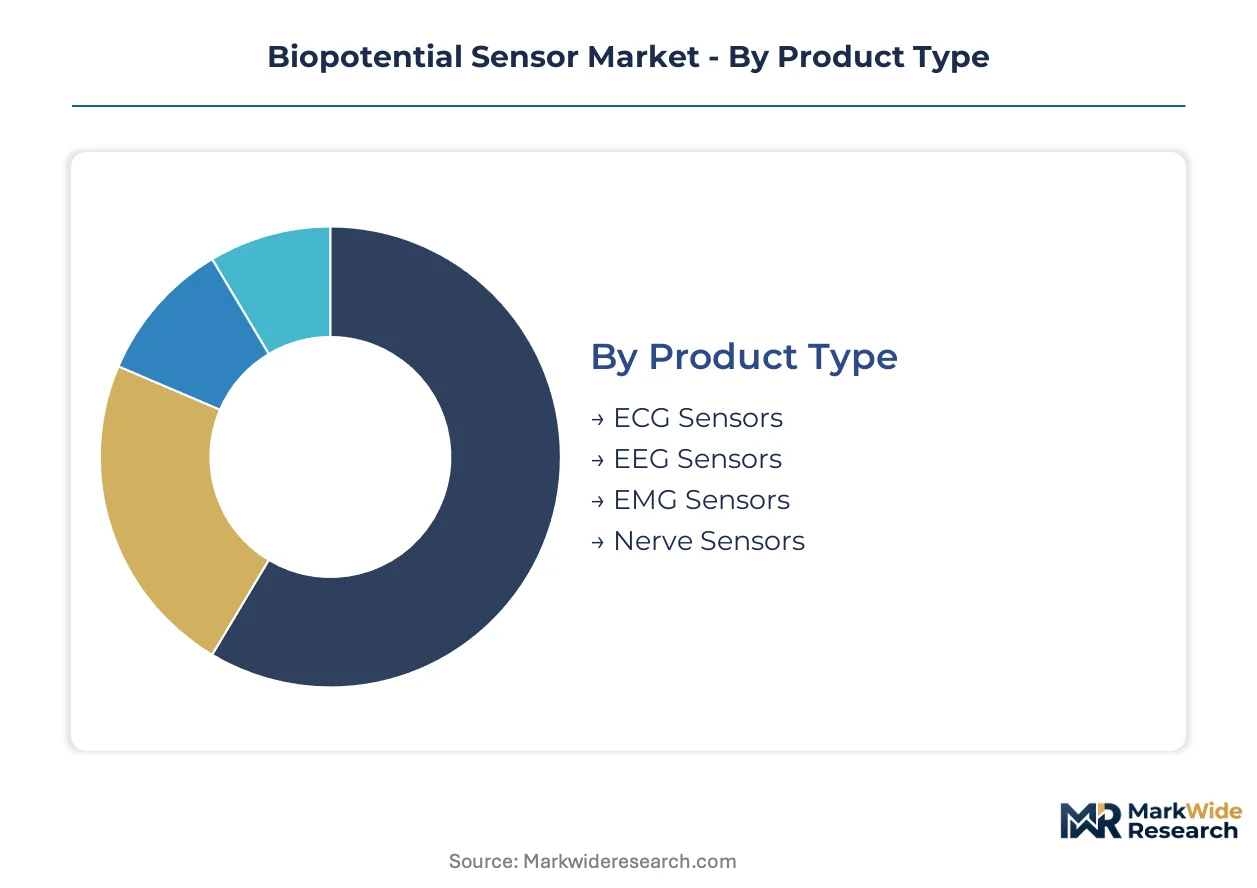
Biopotential sensor procurement patterns diverge sharply across clinical versus consumer contexts, with reimbursement pathways and signal fidelity requirements dictating hardware specifications. Understanding segment-level technology-sensitivity helps vendors calibrate R&D investment and distribution partnerships.
Product Type:
Replacement cycles vary from single-use disposables in electrophysiology labs to multi-year implantable devices, creating divergent margin profiles and customer retention mechanics.
- ECG Sensors:Ag/AgCl electrodes with gel interfaces dominate ambulatory arrhythmia monitoring where FDA-cleared algorithms command premium positioning. Demand concentrates in United States hospital cardiology departments as remote patient monitoring reimbursement solidifies.
- EEG Sensors:High-density electrode arrays with active shielding enable microvolt-level cortical signal capture for epilepsy monitoring and closed-loop neurostimulation trials. Academic medical centers in Germany and Japan are expanding procurement for sleep diagnostics and intraoperative monitoring applications.
- EMG Sensors:Surface electrodes with bipolar configurations detect motor unit action potentials for neuromuscular assessment.
- Nerve Sensors:Cuff electrodes and penetrating arrays interface with peripheral nervous system signals for prosthetic control and chronic pain management.
ECG sensors sit at the top of the volume ranking, with EEG sensors climbing the fastest.
Technology:
Cost tiers separate premium wireless configurations from economy wired alternatives, with flexible and implantable categories commanding specialized manufacturing capabilities.
- Wireless:Bluetooth Low Energy and proprietary RF protocols enable ambulatory monitoring without tethered connections. Home care settings and sports medicine clinics in the United States are displacing wired legacy systems as battery life extends beyond 14 days.
- Wired:Shielded coaxial cables deliver interference-resistant signal transmission for operating room environments where electromagnetic compatibility is non-negotiable. Research laboratories retain wired infrastructure for high-channel-count neurophysiology studies.
- Flexible:Polyimide and silicone substrates conform to skin topography for multi-day wear without adhesive irritation.
- Implantable:Hermetic titanium enclosures with platinum-iridium electrodes require Class III regulatory pathways and surgical placement protocols.
Wireless configurations capture the highest shipment volumes, while implantable systems generate the steepest per-unit margins.
End User:
Customer type determines purchasing authority structure, with hospitals consolidating procurement through IDNs while home care channels fragment across direct-to-consumer and durable medical equipment distributors.
- Hospitals:Electrophysiology catheter labs and critical care units drive demand for multi-parameter monitoring with centralized telemetry integration. German hospital networks are unbundling electrode consumables from device contracts to capture distributor margin.
- Research Laboratories:Academic neuroscience and biomechanics departments prioritize signal fidelity and open-source software compatibility over regulatory clearance speed.
- Fitness Centers:Consumer-grade heart rate variability and muscle activation tracking penetrates premium athletic training facilities.
- Home Care:Reimbursable remote patient monitoring programs are expanding prescription-grade ECG patch deployment for post-acute cardiac patients.
Hospitals dominate absolute spending, with home care channels expanding most quickly as reimbursement frameworks mature.
Application:
Application maturity correlates with regulatory precedent depth, with cardiology benefiting from decades of clinical evidence while sports medicine navigates evolving performance-claim standards.
- Cardiology:Ambulatory ECG for atrial fibrillation detection represents the most established reimbursement category, with AI-enabled arrhythmia classification accelerating FDA breakthrough designations.
- Neurology:Epilepsy monitoring and intraoperative neurophysiology require specialized electrode placement expertise and prolonged recording durations.
- Rehabilitation:Biofeedback systems for stroke recovery and prosthetic training integrate EMG signal processing with gamified therapy protocols.
- Sports Medicine:Wireless EMG for biomechanical analysis and concussion assessment protocols are penetrating professional athletic organizations and university research programs.
Cardiology commands the largest installed base, with neurology applications gaining share fastest through neurostimulation trial expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The biopotential sensor industry traces its clinical-scale origins to German electrophysiology research laboratories in the 1970s, where Ag/AgCl electrode chemistry and high-impedance amplification circuits were first standardized for cardiac monitoring. German engineering culture subsequently shaped precision instrumentation norms that persist across global regulatory frameworks.
United States
FDA breakthrough device designations for AI-enabled arrhythmia detection are compressing commercialization timelines for next-generation Holter monitors. Remote patient monitoring reimbursement pathways under CMS have solidified procurement budgets for wireless ECG patches in cardiology service lines. The Boston-Cambridge corridor anchors venture-backed neurotechnology startups developing closed-loop neurostimulation systems for epilepsy centers.
Germany
Hospital networks in Baden-Württemberg and Bavaria are unbundling electrode consumables from device contracts to capture distributor margin in ambulatory monitoring programs. EU MDR Class IIa technical documentation requirements are elevating clinical evidence burdens for wearable cardiac sensors seeking CE marking. The Munich-Stuttgart industrial corridor concentrates precision electronics manufacturers supplying analog front-end components to OEMs across Europe.
Japan
METI incentives for preventive cardiac monitoring are expanding reimbursable indications for ambulatory ECG in community care settings serving aging demographics. PMDA consultation pathways for novel neurostimulation devices are streamlining pre-market dialogue for academic medical center trials. The Kansai region around Osaka hosts specialized electrode manufacturers supplying high-density EEG arrays for sleep diagnostics and intraoperative monitoring.
China
NMPA innovation approval pathways for Class II medical devices are accelerating market entry for domestic manufacturers of wireless cardiac monitors. Provincial health commissions in Jiangsu and Guangdong are piloting remote patient monitoring reimbursement for post-acute cardiac patients. The Yangtze River Delta manufacturing ecosystem produces cost-optimized Ag/AgCl electrodes serving price-sensitive segments across Asia-Pacific.
Switzerland
Swissmedic's alignment with EU MDR standards enables streamlined parallel market access for implantable cardiac sensors targeting European and Swiss electrophysiology labs simultaneously. The Lake Geneva corridor concentrates precision sensor developers leveraging microelectromechanical systems expertise from adjacent watchmaking and medtech industries. Zurich-based research hospitals are expanding procurement for wireless EMG systems in sports medicine and rehabilitation applications.
Biopotential Sensor Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory validation depth, with implantable configurations commanding surgical-placement premiums and extended certification timelines. The vendor base stratifies into three tiers: semiconductor component suppliers anchoring analog front-end supply relationships, integrated device manufacturers with captive electrophysiology lab access, and emerging flexible-electrode specialists rewriting wearability benchmarks. Dominant competitive moves include backward integration into electrode substrate manufacturing and strategic partnerships with AI-enabled analytics platforms.
Within the semiconductor component tier, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions as North American suppliers of precision instrumentation amplifiers. Medtronic plc exemplifies the integrated device manufacturer archetype with deep regulatory experience in implantable cardiac applications. These three entities anchor distinct competitive vectors: analog signal fidelity, electrophysiology catheter lab integration, and implantable device validation expertise respectively.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Medtronic plc |
| NXP Semiconductors N.V. |
| Maxim Integrated |
| ams OSRAM |
| Siemens Healthineers AG |
| Philips Healthcare |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Biomedical signal processing engineers concentrated in the Boston-Cambridge corridor and Munich-Stuttgart industrial belt command wage premiums that propagate through three-tier pricing spreads separating FDA-cleared implantable systems from standard wireless patches and economy-grade consumables.
Pricing Analysis
Premium-mid-economy pricing differentiation separates hermetic titanium implantable configurations from flexible wireless patches and disposable Ag/AgCl electrode arrays. Price differentiation hinges on ISO 13485 certification depth and FDA breakthrough device designation status. Cost compression in the economy tier intensifies as Chinese manufacturers scale output of commodity electrodes. Home care channel buyers exhibit highest price sensitivity; electrophysiology catheter labs demonstrate lowest.
Supply Chain Analysis
Workforce availability for precision analog front-end engineering concentrates in Taiwan, Germany, and the United States, constraining capacity expansion velocity for clinical-grade instrumentation amplifiers. Raw material dependencies center on silver chloride chemistry, polyimide substrates, and platinum-iridium electrode alloys. Single-source vulnerability runs through specialized semiconductor foundries serving medical-grade ASIC production. Distribution runs through hospital IDN procurement committees unbundling hardware from software and direct-to-manufacturer electrode contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biopotential sensor market functions as a regulatory compounder where FDA digital health pre-certification and EU MDR Class IIa pathway maturation are accelerating procurement velocity for cleared devices.
For Market Incumbents: Acquire AI-enabled arrhythmia detection algorithm portfolios to neutralize software-native entrants threatening hardware margins. Secure backward integration into Ag/AgCl electrode substrate manufacturing to defend against precious metal cost volatility and Chinese commoditization pressure. For New Entrants and Emerging Players: Direct-to-clinician digital channels offer the lowest customer acquisition cost entry vector for prescription-grade ECG patch deployment. Target Japan's community care settings where METI incentives for preventive cardiac monitoring create reimbursable demand without entrenched vendor relationships. Lead with 14-day battery life wireless systems displacing wired legacy infrastructure in ambulatory surgical centers. For Investors and Strategic Acquirers: Integrated device manufacturers with captive electrophysiology lab access are the most active acquirer in this space, consolidating implantable sensor pipelines and regulatory submission expertise. Five-to-ten year viability favors targets with established ISO 13485 quality systems and FDA breakthrough device track records. Signal to watch: EU notified body capacity expansion rates as a leading indicator of European market entry velocity for novel wearables.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compressed review timelines for AI-enabled arrhythmia algorithms accelerate commercialization in United States cardiology service lines. |
| EU MDR Class IIa Technical Documentation | Prospective registry data requirements elevate clinical evidence burdens and extend pre-market investment horizons for wearable cardiac sensors. |
| Hospital IDN Direct Contracting | Unbundling electrode consumables from device contracts captures distributor margin in German and United States ambulatory monitoring programs. |
| Closed-Loop Neurostimulation Platform | EEG-fusion algorithms enabling real-time seizure prediction open premium pricing tiers in academic epilepsy centers. |
| Flexible Dry-Electrode Substrate Development | Micro-structured polyimide interfaces collapse the comfort-versus-fidelity trade-off for multi-day continuous monitoring protocols. |
Study Parameters
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS reimbursement databases, and GPO contract analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged include electrophysiology lab directors, IDN procurement executives, analog front-end semiconductor specialists, and regulatory affairs leads at wearable sensor developers. Secondary sources encompassed ISO 13485 certification registries, EU MDR notified body technical documentation queues, and hospital capital equipment expenditure records.
Historical shipment data cross-referenced against panel input from component suppliers and OEMs anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user channel, and application maturity. CAGRs derived from unit-volume trajectory analysis weighted against average selling price erosion curves in the wireless and implantable categories. Industry-specific forecast inputs incorporated FDA breakthrough device designation velocity and EU notified body capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for dry-electrode capacitive coupling achieving wet-electrode signal fidelity would alter the outlook. Forecasts reflect assumptions regarding reimbursement pathway solidification and regulatory harmonization timelines. Material deviation in FDA pre-certification expansion rates or EU MDR notified body staffing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Electronic Differential Control Module Market