
 Gyro Sensors Market | 2026-2036
Gyro Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Gyro Sensors Market Foresight
Buyer concentration in automotive and aerospace procurement is shifting as tier-one suppliers consolidate long-term gyro sensor contracts with fewer vendors. Robert Bosch GmbH leverages its integrated MEMS fabrication capabilities to control cost curves across high-volume automotive programs. STMicroelectronics N.V. sustains R&D intensity in consumer-grade motion sensing, while Honeywell International Inc. dominates precision fiber optic and ring laser systems for defense and aviation end users.
Gyro sensors detect angular velocity through Coriolis force measurement, with MEMS variants fabricated on silicon substrates using bulk or surface micromachining processes to achieve package sizes below 5 mm by 5 mm. These devices enable stabilization, navigation, and orientation tracking across platforms from drones to surgical robots. MEMS gyroscopes lead unit shipments due to consumer electronics scale, yet fiber optic gyroscopes command premium positioning in aerospace and marine applications where bias stability below 0.01 degrees per hour is mandatory. Industrial automation and robotics applications are expanding fastest as warehouse automation and collaborative robot deployments multiply.
FAA airworthiness standards and EU MDR requirements shape product certification pathways for gyro sensors deployed in commercial aviation and surgical navigation systems respectively. REACH compliance and RoHS substance restrictions constrain material selection for European-market MEMS packages, while ISO 26262 functional safety mandates govern automotive gyroscope integration. Stakeholders must monitor how emerging quantum and integrated photonic gyro technologies disrupt incumbent performance-cost tradeoffs.
Market Dynamics
Precision requirements from autonomous navigation systems are compressing performance-cost tradeoffs across MEMS and fiber optic architectures, forcing manufacturers to reconfigure fabrication strategies around solid-state designs.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gases accelerate solid-state gyro adoption as automakers abandon mechanical designs dependent on sealed gas environments.
- Autonomous vehicle navigation:L4 and L5 driving programs demand bias stability below 0.1 degrees per hour, pulling high-precision inertial measurement units into series production.
- Industrial robotics:Warehouse automation and collaborative robot deployments multiply six-axis stabilization needs across fulfillment networks in Germany and Japan.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea anchor 70%+ of advanced silicon micromachining capacity, exposing supply chains to single-point geopolitical risk.
- Precision fiber optic cost structure:Coil winding and polarization-maintaining fiber input costs limit unit economics below aerospace and marine volumes.
- ISO 26262 certification friction:Automotive functional safety mandates extend qualification timelines 18-24 months for new gyro designs.
Strategic Opportunities
- Quantum gyroscope convergence:Cold atom and integrated photonic technologies promise bias stability improvements of two orders of magnitude for defense and scientific applications.
- India manufacturing incentives:PLI scheme subsidies for electronic components attract MEMS packaging investments serving domestic automotive and consumer electronics demand.
- Surgical navigation systems:EU MDR certification requirements create premium positioning for fiber optic gyros in image-guided orthopedic and neurosurgical platforms.
Industry Challenges
- Specialized MEMS process engineering:Bulk and surface micromachining expertise concentrates among aging fabrication specialists, constraining talent pipelines for new entrants.
- Aviation certification timelines:FAA airworthiness standards for inertial reference systems impose multi-year validation cycles that compress product refresh rates.
- Legacy system integration:Defense and marine platforms running 1990s-era ring laser gyros resist architecture swaps despite maintenance cost burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gyro Sensors Market |
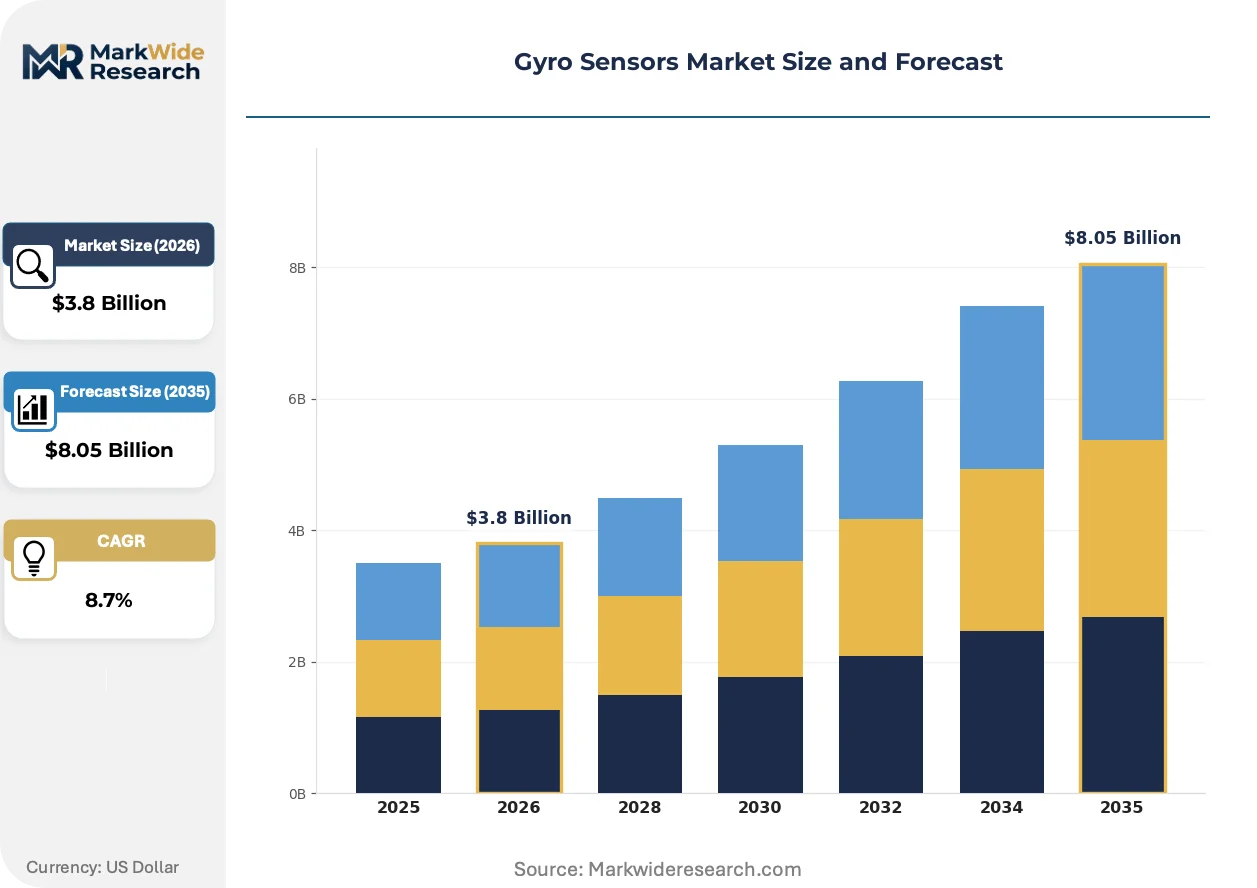
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS Gyroscopes, Fiber Optic Gyroscopes, Ring Laser Gyroscopes, Vibrating Structure Gyroscopes Application: Aerospace, Automotive, Industrial Automation, Consumer Electronics End User: Defense, Robotics, Marine, Healthcare Connectivity: Wired, Wireless, Bluetooth, IoT |
| Companies Covered | Analog Devices, Inc., STMicroelectronics N.V., Honeywell International Inc., Murata Manufacturing Co., Ltd., Robert Bosch GmbH, NXP Semiconductors N.V., InvenSense, Inc., TDK Corporation, KVH Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gyro Sensors Market Shifts & Advancements
Silicon photonics and quantum sensing architectures are redrawing performance boundaries that MEMS established over two decades, while procurement patterns consolidate around vertically integrated sensor module suppliers.
Integrated photonic gyroscopes are expanding into navigation-grade applications through silicon nitride waveguide platforms that replicate fiber optic precision without coil winding labor. Automotive tier-one suppliers in Germany and Japan are sampling chip-scale prototypes for 2027 platform integration. This technology is expanding into cost brackets previously reserved for MEMS, compressing the traditional performance-price hierarchy.
REACH substance restrictions and RoHS compliance deadlines are forcing material substitutions in MEMS package metallization and die-attach compounds. European market access now requires full supply chain substance documentation back to smelter level. Medical device and automotive OEMs are responding by pre-qualifying alternative lead-free solders and gold wire bonding processes ahead of 2026 enforcement windows.
Long-term supply agreements are displacing spot procurement as tier-one automotive and aerospace buyers consolidate vendor panels to three or fewer qualified sources per program. This concentration favors integrated device manufacturers with captive fabrication over fabless design houses. The shift is most visible in Germany, where Bosch and Continental have locked five-year MEMS supply commitments with volume guarantees and joint roadmap investments.
Gyro Sensors Market Segmentation
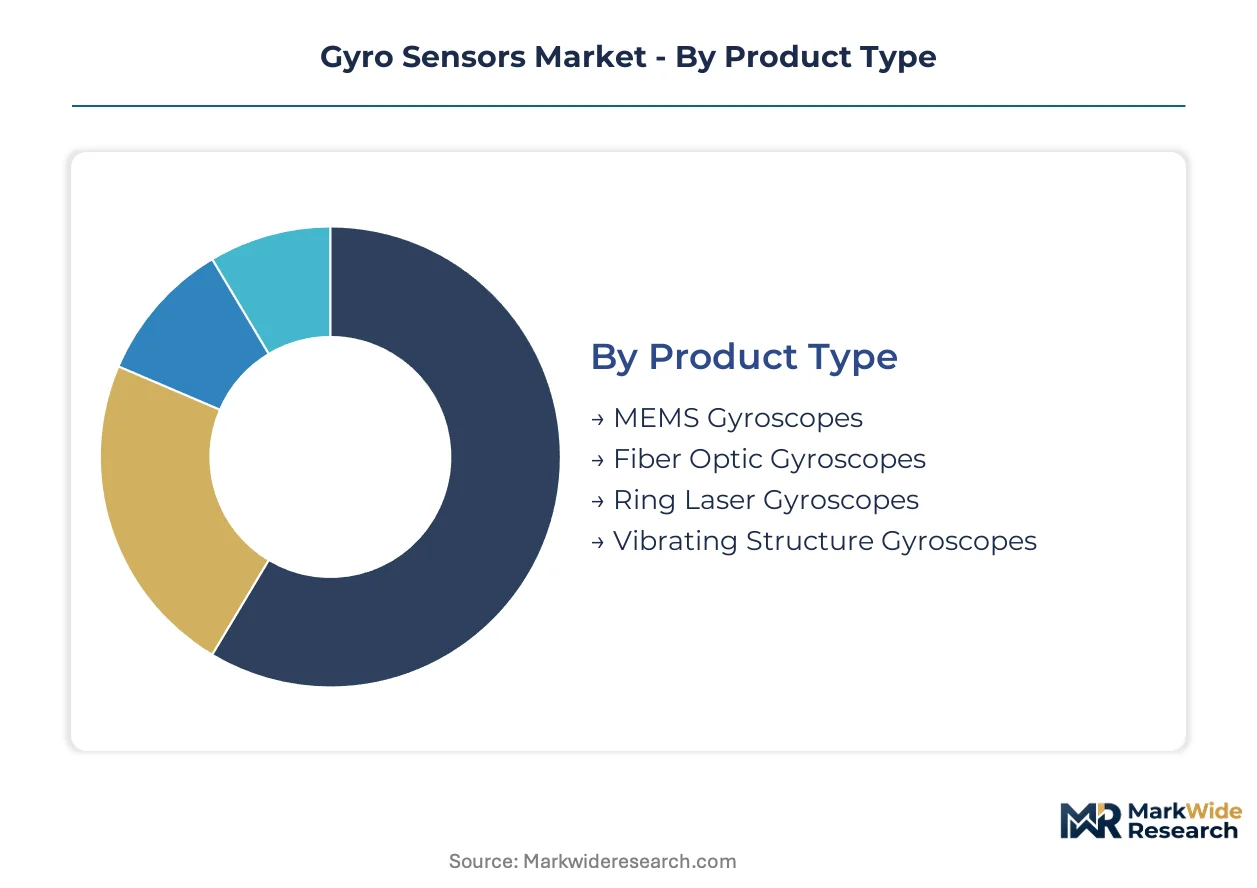
Gyro sensor procurement splits across four distinct classification schemes, each governing different certification burdens and margin structures. Buyers navigate divergent qualification pathways depending on whether sensors deploy in FAA-regulated aviation systems or consumer electronics platforms.
Product Type:
FAA airworthiness standards and ISO 26262 functional safety mandates create tiered approval burdens across gyro architectures, with aerospace-grade designs requiring multi-year validation cycles.
- MEMS Gyroscopes:Silicon-based devices fabricated through bulk or surface micromachining achieve package sizes below 5 mm by 5 mm. Consumer electronics manufacturers in Taiwan and South Korea drive unit volumes, though automotive qualification under ISO 26262 extends timelines 18-24 months for new designs.
- Fiber Optic Gyroscopes:Coil-wound polarization-maintaining fiber architectures deliver bias stability below 0.01 degrees per hour. Defense and marine applications in Germany and Japan concentrate demand, constrained by input material costs that limit expansion below premium aerospace volumes.
- Ring Laser Gyroscopes:Heirloom precision systems from the 1990s still populate defense platforms despite maintenance burdens.
- Vibrating Structure Gyroscopes:Piezoelectric resonator designs serve niche industrial stabilization needs with moderate precision requirements.
MEMS Gyroscopes sit at the top of the volume ranking, with Fiber Optic Gyroscopes climbing the fastest as autonomous navigation programs pull precision inertial measurement units into series production.
Application:
End-use concentration determines pricing tiers, with aerospace and automotive programs commanding 5-10x premiums over consumer electronics procurement.
- Aerospace:Commercial aviation and defense platforms require bias stability below 0.1 degrees per hour. FAA airworthiness certification imposes multi-year validation cycles that compress product refresh rates and favor incumbent suppliers with established qualification histories.
- Automotive:L4 and L5 autonomous driving programs anchor precision IMU demand in Germany and Japan. EU F-Gas Regulation accelerates solid-state adoption as automakers abandon mechanical designs dependent on sealed gas environments.
- Industrial Automation:Warehouse robotics and collaborative robot deployments multiply six-axis stabilization needs across fulfillment networks.
- Consumer Electronics:Smartphone and wearable integration drives MEMS unit economics through Taiwan and South Korea foundry scale.
Consumer Electronics dominates shipment volumes, though Aerospace maintains the steepest expansion trajectory as next-generation aircraft programs refresh inertial reference systems.
End User:
Defense procurement cycles and healthcare certification timelines create divergent customer profiles with distinct vendor relationship models.
- Defense:Multi-year platform contracts favor ring laser and fiber optic architectures with proven field histories. Cold atom and quantum sensing R&D programs promise two-order-of-magnitude bias stability improvements for next-generation targeting systems.
- Robotics:Collaborative robot and warehouse automation deployments concentrate in Germany and Japan, pulling six-axis IMU demand from tier-one automotive suppliers.
- Marine:Subsea navigation and autonomous vessel programs require fiber optic precision in saltwater environments.
- Healthcare:EU MDR certification creates premium positioning for fiber optic gyros in image-guided orthopedic and neurosurgical platforms.
Defense commands the highest average selling prices, with Healthcare gaining share fastest as surgical navigation systems integrate inertial tracking.
Connectivity:
Interface architecture determines integration complexity and cybersecurity exposure across deployment environments.
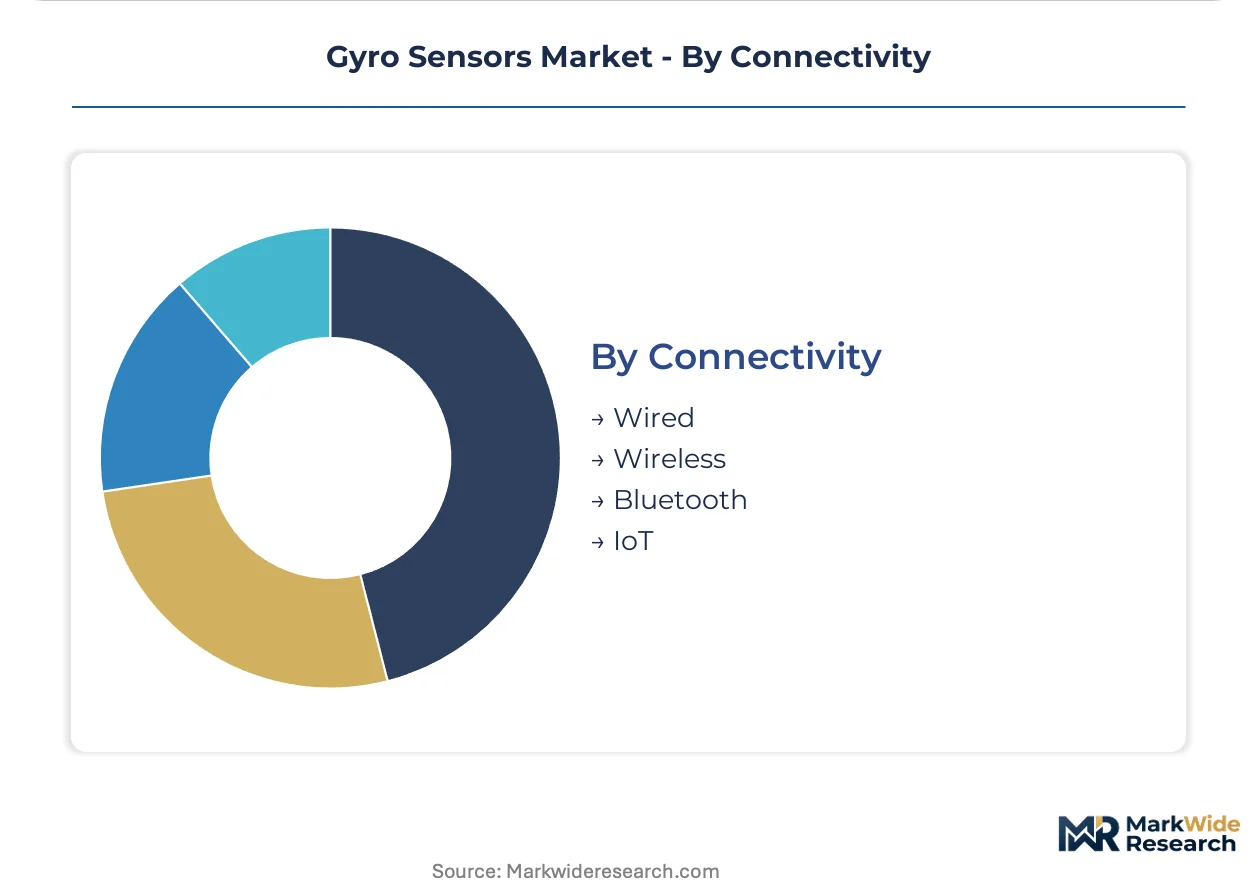
- Wired:Analog and digital serial interfaces dominate aerospace and automotive applications where electromagnetic interference immunity is mandatory.
- Wireless:RF-based telemetry serves remote monitoring and predictive maintenance applications in industrial settings.
- Bluetooth:Low-energy protocols enable smartphone and wearable integration for consumer-grade motion sensing.
- IoT:Cloud-connected architectures support fleet-wide sensor health monitoring across distributed robotics deployments.
Wired interfaces retain volume leadership in safety-critical applications, with IoT connectivity expanding most quickly through industrial automation retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive-grade precision sourcing while the United States anchors defense and aerospace procurement, creating divergent certification pathways across Atlantic supply chains.
United States
FAA airworthiness standards and defense modernization programs drive fiber optic and ring laser demand. The Department of Defense accelerates cold atom gyro R&D through national laboratory partnerships. Boston and Southern California clusters host precision navigation startups targeting autonomous underwater vehicles.
Germany
Automotive OEMs in Stuttgart and Munich anchor MEMS procurement for L4 autonomous programs. EU F-Gas Regulation phases out mechanical designs dependent on sealed gas environments. Bavaria's semiconductor corridor attracts packaging investments from tier-one suppliers seeking captive fabrication.
Japan
METI industrial automation incentives expand six-axis IMU deployment across Osaka and Nagoya robotics clusters. Collaborative robot manufacturers source stabilization sensors from domestic MEMS foundries. Precision fiber optic gyros serve maritime navigation programs through Kobe shipyards.
South Korea
Advanced silicon micromachining capacity concentrates in Hsinchu-linked foundry networks serving consumer electronics scale. Samsung and LG supply chains drive unit economics for smartphone-integrated motion sensors. Government semiconductor subsidies under K-Chips Act attract foreign MEMS packaging investments.
India
PLI scheme subsidies for electronic components draw automotive sensor assembly to Tamil Nadu and Karnataka. Domestic EV programs create first-tier demand for inertial measurement units in two-wheeler and commercial vehicle segments. Bengaluru hardware startups prototype navigation modules for drone delivery networks.
Gyro Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered performance segments. Market structure concentrates around integrated device manufacturers with captive MEMS fabrication and fabless design houses serving consumer electronics scale. Three archetypes dominate: vertically integrated automotive suppliers, precision aerospace specialists, and high-volume consumer electronics fabricators. Competitive moves center on long-term supply agreements with volume guarantees and joint technology roadmap investments.
Among diversified European industrials, Robert Bosch GmbH and STMicroelectronics N.V. exemplify integrated fabrication strategies, while Honeywell International Inc. occupies a position within precision aerospace and defense tiers. These three entities anchor vendor consolidation trends as tier-one buyers reduce qualified sources per program.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| STMicroelectronics N.V. |
| Honeywell International Inc. |
| Murata Manufacturing Co., Ltd. |
| Robert Bosch GmbH |
| NXP Semiconductors N.V. |
| InvenSense, Inc. |
| TDK Corporation |
| KVH Industries, Inc. |
| Others |
Supply & Pricing Matrix
Tier-one automotive OEMs and defense procurement programs anchor contract-based long-term offtake pricing, with volume guarantees and joint roadmap investments displacing spot procurement across German and Japanese supply chains.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for consumer-grade MEMS gyroscopes, compressing margins at the economy tier while premium fiber optic architectures retain project-based pricing power. Three-tier pricing structure across aerospace-grade, automotive-qualified, and consumer-economy levels separates ISO 26262-certified designs from uncertified alternatives, with certification investment acting as the dominant price differentiation driver. Cost compression in high-volume MEMS runs through foundry scale economies, though pricing pressure stems from geopolitical exposure to single-source silicon micromachining. Consumer electronics manufacturers exhibit highest price sensitivity, while defense procurement programs demonstrate lowest elasticity due to bias stability mandates.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and Nagoya operate hub-and-spoke patterns serving automotive and robotics clusters with just-in-time sensor module delivery. Manufacturing concentrates in Taiwan, South Korea, and Germany, with advanced silicon micromachining capacity tethered to Hsinchu-linked foundry networks. Polarization-maintaining fiber, specialty glass, and precision coil winding equipment constitute critical input dependencies. Single-source vulnerability runs through Taiwan's dominance of MEMS foundry services, exposing automotive programs to geopolitical disruption. Distribution runs through tier-one supplier direct contracts with captive fabrication facilities, bypassing traditional component distributors for safety-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state technology transitions and captive fabrication investments compress cost curves, enabling margin expansion as premium-tier fiber optic positioning holds against MEMS commoditization.
For Market Incumbents: Anchor long-term supply agreements with five-year volume guarantees and joint R&D roadmaps to lock out emerging fabless competitors. Deepen backward integration into MEMS packaging through Bavaria semiconductor corridor investments, countering the threat of India's PLI-subsidized assembly entrants. Prioritize ISO 26262 certification maintenance to sustain automotive pricing premiums against uncertified challengers. For New Entrants and Emerging Players: Domestic EV manufacturers in India represent the most penetrable buyer archetype, with PLI scheme subsidies creating first-tier demand gaps unclaimed by established German and Japanese suppliers. Target surgical navigation system OEMs seeking EU MDR-certified fiber optic alternatives, leveraging healthcare's lower volume sensitivity and higher margin tolerance. Pursue qualification partnerships with tier-one automotive suppliers rather than direct OEM sales, accelerating certification timelines through incumbent validation. For Investors and Strategic Acquirers: Automotive tier-one suppliers are the most active acquirer in this space, consolidating fabless design houses to secure captive sensor fabrication capacity. Five-to-ten-year viability favors integrated device manufacturers with proven FAA and ISO qualification histories over pure-play MEMS designers. Monitor cold atom gyroscope prototype announcements from national laboratory partnerships as the signal indicating quantum disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Bosch and Continental locked five-year MEMS commitments with volume guarantees and joint roadmap investments. |
| Backward Integration into Packaging | Bavaria's semiconductor corridor attracts captive fabrication investments from tier-one automotive suppliers. |
| Quantum Sensing R&D Partnership | Department of Defense accelerates cold atom gyro development through national laboratory collaborations. |
| EU MDR Certification Pathway | Fiber optic gyro manufacturers secure premium positioning in image-guided surgical navigation platforms. |
| PLI Scheme Manufacturing Subsidy | India's electronic component incentives draw automotive sensor assembly to Tamil Nadu and Karnataka. |
Research Methodology
Direct dialogue with MEMS fabrication engineers, tier-one automotive procurement managers, FAA certification specialists, and fiber optic gyro manufacturing directors grounded qualitative assessments, combined with secondary validation from SEC 10-K filings, EU F-Gas Regulation implementation reports, and IHS Markit vehicle production databases. Bottom-up and top-down triangulation cross-referenced foundry capacity announcements with OEM platform deployment schedules.
Bottom-up modeling segmented the market by gyro architecture, application tier, and regional production cluster, with value outputs derived from contract pricing disclosures and procurement database analysis across the projection horizon. CAGRs emerged from segment-level growth rate reconciliation against autonomous vehicle deployment timelines and industrial robotics installation forecasts. Modeled inputs included L4/L5 program ramp schedules, EU MDR certification completion rates, and PLI scheme subsidy disbursement patterns.
Underlying measurement precision varies by segment; aerospace-grade fiber optic systems carry tighter precision than consumer MEMS due to disclosed contract values and limited supplier counts. Forecasts reflect documented assumptions regarding autonomous vehicle adoption curves, regulatory phase-out schedules, and foundry capacity expansion plans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
PID Controller Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Electronic Differential Control Module Market