
 Smart Condition Monitoring Market | 2026-2036
Smart Condition Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Condition Monitoring Market Intelligence
The European Union's updated Machinery Regulation, which mandates enhanced safety functions, is expanding the requirement for certified monitoring systems on industrial equipment. Siemens leverages its extensive industrial automation portfolio to offer integrated solutions for complex manufacturing lines. Concurrently, SKF specializes in monitoring rotating equipment through its deep expertise in bearing technology and vibration analysis. Rockwell Automation differentiates its offerings by embedding monitoring capabilities directly into its control and automation platforms.
Smart condition monitoring utilizes advanced sensors to continuously track the health of industrial assets by measuring parameters like vibration signatures or thermal gradients. Its purpose is to enable predictive maintenance, shifting operations away from reactive repairs and minimizing unplanned downtime. While vibration analysis remains the dominant technology for rotating equipment, cloud-based deployments are seeing rapid uptake. This shift allows for scalable, remote monitoring across multiple facilities, a key value proposition for large manufacturers and utilities.
Compliance with ISO 20816 for mechanical vibration and ISO 18436 for personnel certification establishes a baseline for system performance and credibility. Concurrently, sector-specific mandates, such as those from the US EPA for emissions control systems or the EU's F-Gas Regulation for HVAC, create targeted demand. Vendor selection will increasingly depend on the ability to integrate diverse sensor data streams into a unified, actionable analytics platform.
Market Dynamics
The central force is the fusion of AI algorithms with edge computing hardware. This combination enables sophisticated, real-time anomaly detection directly at the asset, moving intelligence away from centralized cloud-only models and toward the factory floor.
Growth Catalysts
- EU Machinery Regulation:Mandates for enhanced safety functions are expanding requirements for certified monitoring systems on industrial equipment.
- Energy Sector Demand:Wind turbine and offshore platform operators require predictive systems to manage maintenance in remote, high-cost environments.
- Manufacturing Optimization:Industrial centers in Germany and Japan use smart monitoring to increase uptime on complex, automated production lines.
Market Restraints
- High Implementation Cost:The capital required for sensor networks and software platforms is a significant barrier for small and medium-sized enterprises.
- Legacy System Integration:Integrating modern monitoring with older industrial equipment in existing facilities presents a major technical and financial hurdle.
- Specialized Skill Scarcity:A shortage of data scientists and reliability engineers qualified to interpret complex asset data limits effective system deployment.
Strategic Opportunities
- HVAC System Monitoring:The EU's F-Gas Regulation creates demand for monitoring refrigerant levels and efficiency in commercial buildings and data centers.
- Multi-Modal Sensing:Combining vibration analysis with acoustic and thermal data provides a more complete assessment of machine health, improving diagnostic accuracy.
- Emerging Market Penetration:Manufacturers in Southeast Asia and Latin America are upgrading industrial infrastructure, creating new demand for monitoring solutions.
Industry Challenges
- Personnel Certification:The slow process for certifying analysts under standards like ISO 18436 creates a bottleneck for qualified system operators.
- Data Interoperability:Ensuring seamless data exchange between multi-vendor sensors and a single analytics platform remains a primary technical hurdle for users.
- Cybersecurity Risks:Securing operational data transmitted from assets to the cloud against cyberattacks is a critical challenge for industrial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Condition Monitoring Market |
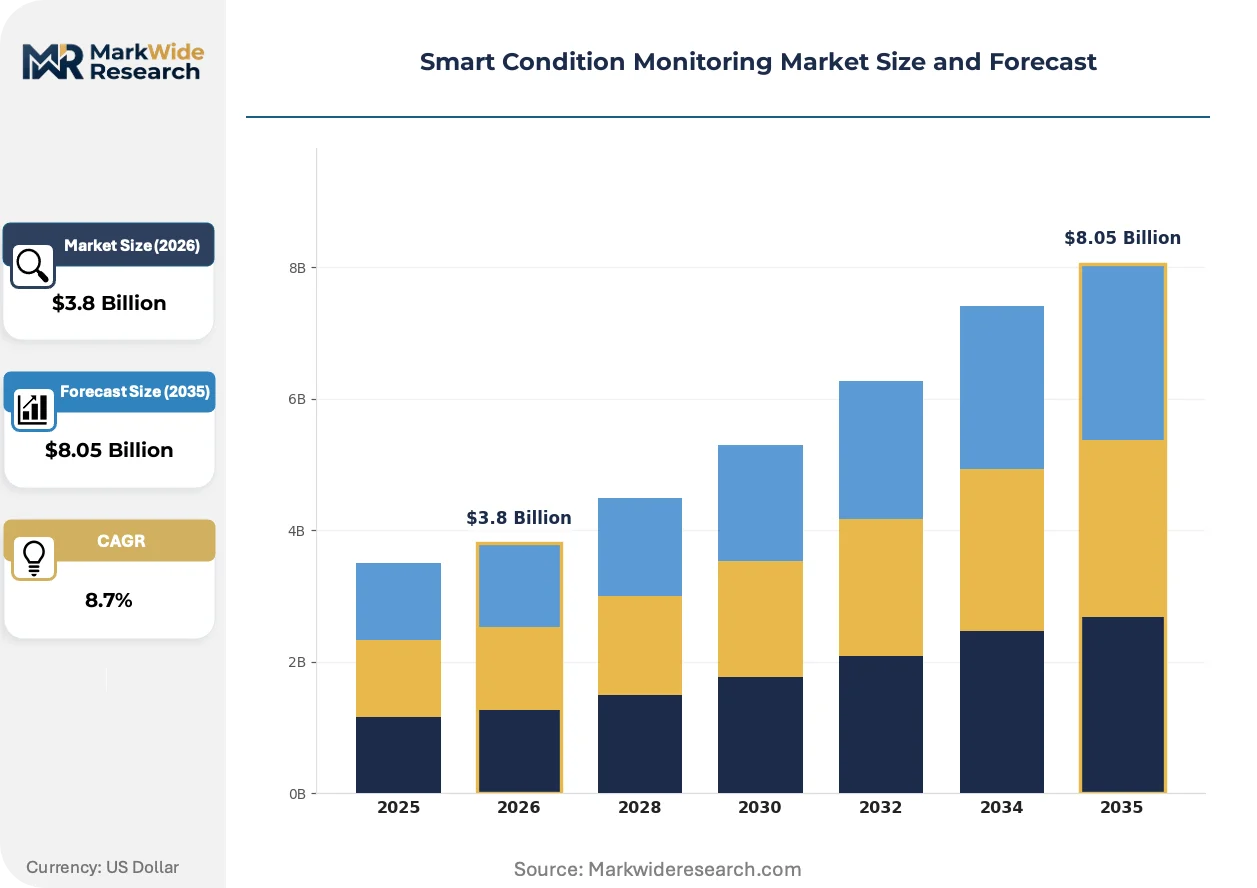
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vibration Analysis, Thermography, Ultrasonic Testing, Acoustic Emission, Motor Current Analysis, Oil Analysis Application: Rotating Equipment, Electrical Systems, Structural Components, HVAC Systems, Power Generation, Manufacturing Lines Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Energy Producers, Manufacturers, Transportation Operators, Mining Facilities, Chemical Plants, Utilities |
| Companies Covered | Siemens, Emerson Electric, SKF, Rockwell Automation, ABB, Honeywell International, General Electric, Mitsubishi Electric, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Condition Monitoring Market Strategic Shifts & Innovations
A fundamental shift from component-level alerts to system-wide predictive intelligence defines the evolution of smart condition monitoring. This transition embeds analytical capabilities closer to the asset, transforming raw data into actionable operational insights.
Edge computing hardware processes sensor data locally on the factory floor. Heavy asset industries like mining and oil and gas adopt it to reduce network latency and enable faster decisions. This technology is integrating AI algorithms at the asset level, enabling real-time anomaly detection without constant cloud connectivity.
The US EPA mandates stringent monitoring for emissions control systems in power generation and chemical processing. This regulation drives the need for certified, continuous monitoring to ensure compliance and avoid financial penalties. The power generation sector is most affected, investing in advanced analyzers and data loggers linked to plant-wide platforms.
Buyers are shifting from purchasing single-parameter sensors to procuring unified analytics platforms. This model displaces transactional hardware sales with subscription-based software and analytics services. The change is most visible among large automotive and aerospace manufacturers in the United States and Germany seeking a standardized view across global operations.
Smart Condition Monitoring Market Segmentation
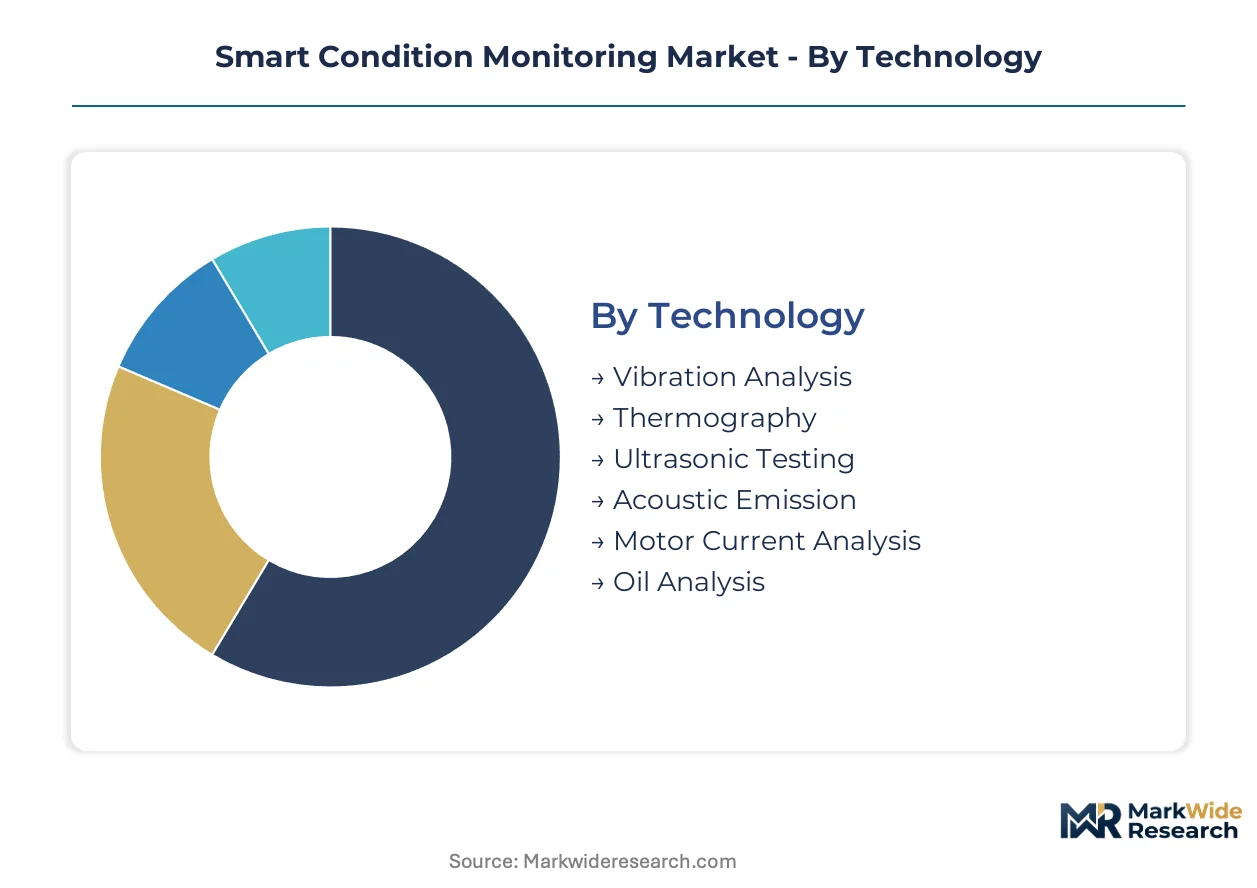
Segmentation within the smart condition monitoring market clarifies how diverse technological approaches and deployment models address specific industrial needs. This differentiation allows for a targeted understanding of solution adoption across various asset types and operational environments.
Technology:
Smart condition monitoring technologies range from highly integrated embedded sensors to standalone analytical tools, addressing diverse asset health assessment needs.
- Vibration Analysis:This technology measures mechanical oscillations in rotating machinery to detect imbalances, misalignment, or bearing faults. Demand concentrates in energy production and manufacturing, driven by the need for predictive maintenance on critical equipment.
- Thermography:Utilizing infrared cameras, thermography detects abnormal heat signatures, indicating electrical faults, mechanical friction, or insulation issues. Manufacturing lines and electrical systems utilize this for early fault detection and preventing catastrophic failures.
- Ultrasonic Testing:This method detects high-frequency sound waves for leak detection, electrical arcing, and early bearing wear in various industrial assets.
- Acoustic Emission:Acoustic emission monitors transient elastic waves generated by material deformation or crack propagation in structures and pressure vessels.
- Motor Current Analysis:This technique analyzes current and voltage signals to diagnose electrical and mechanical issues in electric motors and their driven equipment.
- Oil Analysis:Oil analysis assesses lubricant condition and wear particles to determine the health of machinery components and predict potential failures.
Vibration Analysis leads volumes today; Acoustic Emission is gaining share fastest.
Application:
Applications for smart condition monitoring span critical industrial infrastructure, ensuring operational continuity across diverse asset classes.
- Rotating Equipment:This application monitors assets like turbines, pumps, and motors, which are highly prone to mechanical wear and vibration issues. Energy producers and manufacturers heavily invest in this application to prevent costly downtime.
- HVAC Systems:Focuses on maintaining climate control units, compressors, and fans in commercial buildings and data centers for efficiency. The EU's F-Gas Regulation drives demand for efficient refrigerant monitoring and system health.
- Electrical Systems:This segment monitors transformers, switchgear, and cabling for overheating, partial discharge, and insulation degradation.
- Structural Components:This application assesses the integrity of bridges, pipelines, and offshore platforms for fatigue and corrosion.
- Power Generation:Deploys monitoring across generators, boilers, and auxiliary equipment for reliability and compliance in power plants.
- Manufacturing Lines:Integrates sensors into automated production machinery to optimize uptime and prevent process interruptions.
Demand for smart condition monitoring concentrates heavily in Rotating Equipment and Manufacturing Lines due to their direct impact on production.
Deployment:
Deployment models for smart condition monitoring define where data processing and analytics occur, from centralized platforms to localized intelligence.
- Cloud-Based:This model leverages remote servers for data storage, processing, and scalable analytics, enabling remote monitoring across multiple facilities. Large manufacturers and utilities favor this for its flexibility and reduced local IT burden.
- Edge Computing:Edge computing processes sensor data directly at the asset level, enabling real-time anomaly detection and faster decision-making without constant cloud connectivity. Heavy asset industries like mining and oil and gas adopt this to reduce network latency.
- On-Premise:This model deploys monitoring software and hardware within the user's own infrastructure, offering full data control and security.
- Hybrid:The hybrid model combines local data processing with cloud integration, balancing security and scalability for complex industrial environments.
The market is witnessing a significant shift towards Cloud-Based deployments and the integration of Edge Computing for localized intelligence.
End User:
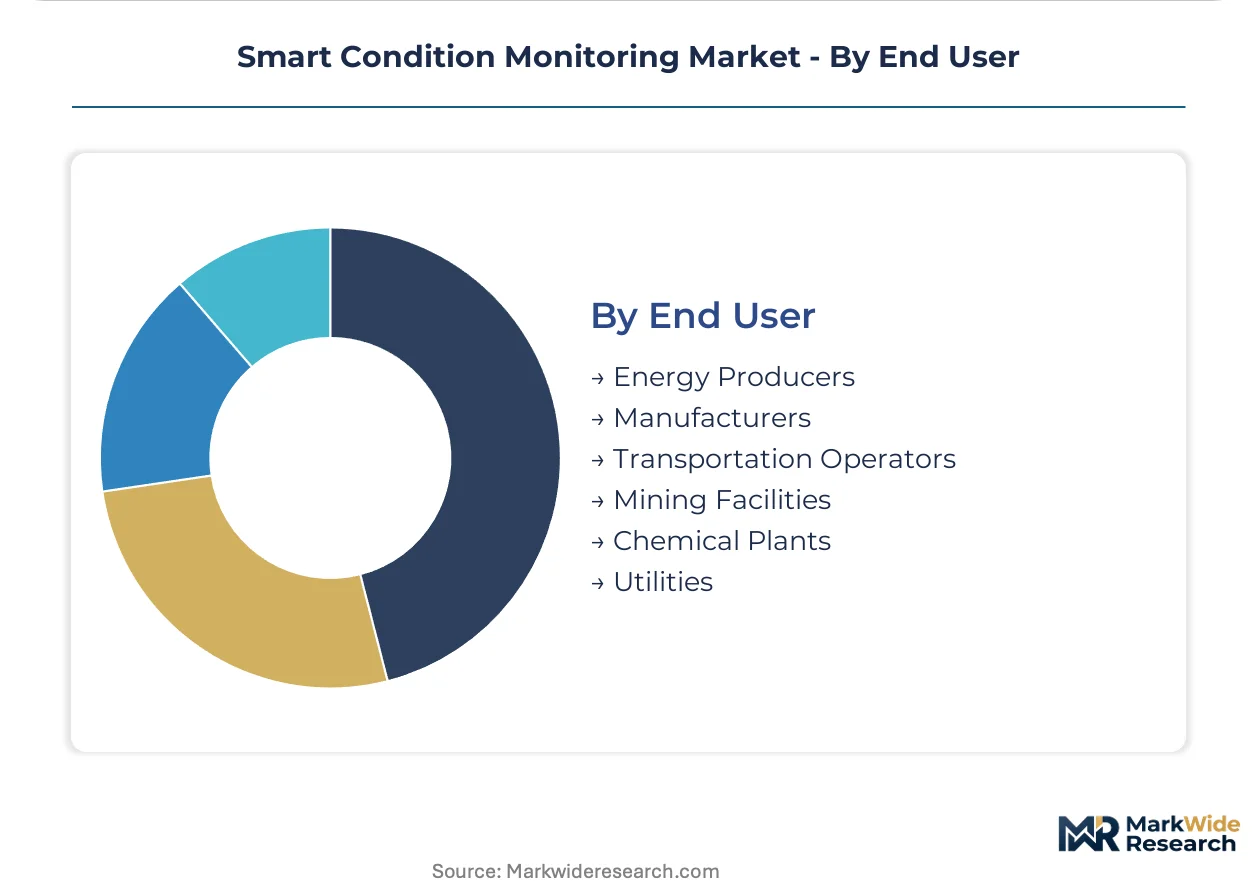
End users of smart condition monitoring are driven by distinct operational imperatives, from asset uptime to safety compliance, across various industrial sectors.
- Energy Producers:These entities monitor critical assets like wind turbines, offshore platforms, and power plants to ensure continuous operation and manage maintenance in remote environments. Demand for predictive systems is high to avoid costly downtime.
- Manufacturers:Manufacturers utilize smart monitoring on complex, automated production lines to increase uptime, optimize processes, and prevent unplanned interruptions. Industrial centers in Germany and Japan are significant adopters.
- Transportation Operators:These operators apply monitoring to fleets, rail systems, and infrastructure for safety and operational efficiency.
- Mining Facilities:Mining facilities use robust systems for heavy machinery and conveyor belts in harsh, remote environments.
- Chemical Plants:Chemical plants implement monitoring for process equipment and safety-critical systems to prevent leaks and failures.
- Utilities:Utilities deploy solutions across water treatment, gas distribution, and electrical grids for infrastructure reliability and regulatory compliance.
Energy Producers and Manufacturers represent the primary demand segments, investing heavily in smart condition monitoring for asset reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled engineering workforce anchors the smart condition monitoring market across key global regions. These regions demonstrate strong industrial bases and a clear imperative for operational efficiency. Demand for predictive maintenance systems is consistently high in these advanced industrial ecosystems.
United States
The United States manufacturing sector demands smart monitoring for complex production lines. US EPA mandates for emissions control systems drive continuous monitoring in power generation. Silicon Valley and industrial hubs like Detroit lead in integrating advanced analytics for asset management.
Germany
German industrial engineers prioritize certified monitoring systems for enhanced safety functions. The EU's Machinery Regulation expands requirements for industrial equipment across the nation. Bavaria and North Rhine-Westphalia house advanced manufacturing clusters adopting these solutions.
Japan
Japanese manufacturers seek smart monitoring to optimize uptime on highly automated production lines. METI initiatives encourage digital transformation in factories, supporting sensor-driven insights. The Kanto region and major automotive centers integrate unified analytics platforms.
China
China's vast industrial base requires smart monitoring for energy production and heavy manufacturing. Government policies promote intelligent manufacturing and industrial upgrading across the country. The Yangtze River Delta and Pearl River Delta drive adoption of cloud-based deployments.
United Arab Emirates
Energy producers in the United Arab Emirates utilize smart monitoring for remote offshore platforms. Robust infrastructure projects and ambitious diversification plans necessitate reliable asset performance. Dubai and Abu Dhabi lead in deploying predictive systems for critical utility assets.
Smart Condition Monitoring Market Key Industry Players
The competitive structure tilts toward integrated solution providers and specialized technology developers. This market features a mix of established industrial automation giants offering broad solutions and focused sensor technology firms providing specific capabilities. Strategic archetypes include comprehensive portfolio providers, niche hardware specialists, and pure-play software analytics platforms. Dominant competitive moves involve strategic partnerships for platform integration, continuous portfolio diversification, and targeted acquisitions to expand technological reach.
Among the comprehensive portfolio providers, Germany-based Siemens AG, with its extensive industrial automation portfolio, offers integrated solutions for complex manufacturing lines. Sweden-based SKF AB exemplifies a specialist in rotating equipment, leveraging its deep expertise in bearing technology and vibration analysis for targeted applications. US-based Rockwell Automation Inc., an automation leader, differentiates its offerings by embedding monitoring capabilities directly into its control and automation platforms, appealing to manufacturers seeking seamless integration across their operations.
| Leading Market Players |
|---|
| Siemens |
| Emerson Electric |
| SKF |
| Rockwell Automation |
| ABB |
| Honeywell International |
| General Electric |
| Mitsubishi Electric |
| Fluke Corporation |
| Others |
Cost & Logistics Intelligence
Specialized sensor components, sourced globally, influence hardware manufacturing costs which then cascade into the final pricing of integrated smart condition monitoring solutions. These costs affect both upfront capital expenditure and ongoing service subscriptions for end-users.
Pricing Analysis
Bundled software and service subscriptions dominate smart condition monitoring pricing, often integrating hardware and analytics. Pricing stratifies across premium, standard, and economy tiers based on certification level and customization requirements for diverse sensor data. Cost compression is intensifying from new entrants offering more modular, unbundled solutions. Small and medium-sized enterprises exhibit the highest price sensitivity, while large manufacturers and utilities prioritize comprehensive, long-term value.
Supply Chain Analysis
Integrated solution providers manage distribution through direct sales to large industrial end-users and specialized channel partners for smaller enterprises. Sensor and hardware manufacturing concentrates in Germany, Japan, and parts of the United States. The supply chain relies on microcontrollers, specialized MEMS sensors, and robust communication modules for data acquisition. Single-source vulnerability for advanced sensor components poses a critical structural risk for system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart condition monitoring market offers significant margin expansion opportunities through a strategic shift towards subscription-based software and analytics services. This transition moves beyond transactional hardware sales, capturing recurring revenue from data insights.
For Market Incumbents: Extend existing industrial automation portfolios by deeply integrating AI algorithms with edge computing hardware for real-time anomaly detection. Invest in personnel certification programs like ISO 18436 to address skill scarcity and enhance service credibility. This defends against disruptive pure-play software analytics platforms by offering certified, comprehensive solutions. R&D in multi-modal sensing capabilities offers a critical lever for diagnostic accuracy.
For New Entrants and Emerging Players: Capture specific niche applications like HVAC system monitoring, driven by EU's F-Gas Regulation, or target emerging markets in Southeast Asia. Focus on providing cost-effective, easily deployable solutions for small and medium-sized enterprises, which represent the most penetrable segment. A go-to-market angle emphasizing rapid deployment and clear, outcome-based ROI will differentiate offerings.
For Investors and Strategic Acquirers: Consolidation pressure builds where data interoperability becomes a critical barrier for end-users seeking unified insights. The long-term viability of this market hinges on continuous demand for asset reliability and regulatory compliance across industrial sectors. Target specialized sensor technology firms or advanced analytics platforms with proven multi-vendor integration capabilities. Watch for the accelerating uptake of unified analytics platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Multi-Modal Sensing Platform | Enhances diagnostic accuracy for complex rotating equipment, reducing unplanned downtime in energy production. |
| Partner with Edge Computing Providers | Enables real-time anomaly detection directly at the asset, reducing network latency for mining facilities. |
| Acquire Analytics Software Developer | Strengthens data interpretation capabilities for diverse sensor streams, providing actionable operational insights for manufacturers. |
| Expand into Emerging Markets | Addresses new demand from upgrading industrial infrastructure in Southeast Asian manufacturing centers. |
| Invest in ISO 20816 Certification | Establishes baseline system performance and credibility, meeting regulatory mandates for industrial equipment across the EU. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary and secondary research. Primary research involved in-depth interviews with plant engineers, maintenance directors, IT procurement officers, and reliability engineers across key industrial sectors. Secondary validation drew from US EPA mandates, EU F-Gas Regulation documents, ISO standards, and industrial automation company reports. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Historical reference periods anchored the forecast window, establishing a robust baseline for market projections. The analytical framework modeled segmentation across technology, application, deployment, and end-user asset class dimensions. Compound annual growth rates were derived from a multi-factor regression analysis, accounting for market dynamics. Industrial production indices and regulatory compliance timelines served as critical forecast inputs over the projection horizon.
Cybersecurity breaches, global economic slowdowns, and rapid technological obsolescence are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding industrial investment cycles and regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Inline Quality Control Sensors Market