
 Industrial Wireless Sensor Market | 2026-2036
Industrial Wireless Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wireless Sensor Market Outlook
Project finance for sensor network infrastructure is fragmenting competitive barriers across the industrial wireless sensor landscape. Emerson Electric Co sustains technology leadership through deep R&D investment in LoRaWAN protocol stacks. Honeywell International Inc anchors its position via backward integration into MEMS fabrication. Siemens AG dominates European manufacturing accounts through channel control over system integrator networks.
An industrial wireless sensor is a self-contained transducer node that transmits process or environmental data via radio frequency links, typically operating on sub-1 GHz or 2.4 GHz bands with battery life targets exceeding five years in field conditions. These devices eliminate cabling costs while enabling real-time monitoring of rotating machinery, pipeline integrity, and ambient conditions across distributed facilities. Temperature sensors occupy the largest installed base due to universal applicability across process industries, while vibration sensors represent the fastest-expanding category as predictive maintenance programs displace scheduled downtime models. NB-IoT technology leads new deployment value in utility and logistics sectors where cellular infrastructure already exists, though LoRaWAN competes aggressively in private network environments.
The FCC governs unlicensed spectrum allocations in the United States that determine available channels and power limits for industrial sensor radios, while the EU Green Deal and REACH frameworks in Europe mandate emissions monitoring that directly stimulates environmental sensor demand. IEEE 802.15.4 and IEC 62591 standards shape interoperability requirements and product certification pathways across both jurisdictions. Stakeholders must monitor spectrum reallocation proceedings and evolving cybersecurity mandates for critical infrastructure IoT devices.
Market Dynamics
LoRaWAN protocol adoption is compressing deployment timelines for predictive maintenance networks, while EU Green Deal emissions mandates are forcing sensor density upgrades across German automotive corridors and US Gulf Coast petrochemical clusters.
Growth Catalysts
- EU Green Deal:REACH framework mandates for emissions monitoring are accelerating environmental sensor deployments across process industries in Germany and the Netherlands.
- Predictive maintenance:Automotive suppliers in Stuttgart and Wolfsburg are replacing scheduled downtime models with vibration sensor networks on rotating machinery.
- IEEE 802.15.4:Evolving interoperability standards are reducing integration friction for multi-vendor sensor deployments in private industrial networks.
Market Restraints
- MEMS fabrication concentration:Supply bottlenecks for microelectromechanical systems concentrate among specialized foundries in Taiwan and South Korea.
- Spectrum fragmentation:Divergent unlicensed band allocations between FCC jurisdictions and EU member states complicate multi-region product certification.
- Battery chemistry volatility:Lithium-thionyl chloride cell prices fluctuate with raw material constraints affecting five-year field life targets.
Strategic Opportunities
- NB-IoT convergence:Cellular infrastructure reuse in US utility sectors creates white space for utility-scale sensor networks without private gateway investment.
- Pipeline integrity monitoring:Midstream operators in Texas and Alberta are deploying pressure and acoustic sensors for leak detection beyond traditional SCADA reach.
- EU AI Act:Emerging compliance requirements for automated industrial decision systems will stimulate demand for verified sensor data provenance.
Industry Challenges
- RF engineering talent scarcity:Sub-1 GHz antenna design and mesh network optimization skills lag deployment demand across system integrator channels.
- IEC 62591 certification timelines:WirelessHART device approval processes extend product launch windows by 8-14 months for safety-critical applications.
- Legacy DCS integration:Brownfield facilities in Rust Belt manufacturing corridors face protocol translation complexity when bridging 4-20 mA systems to IP-based sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wireless Sensor Market |
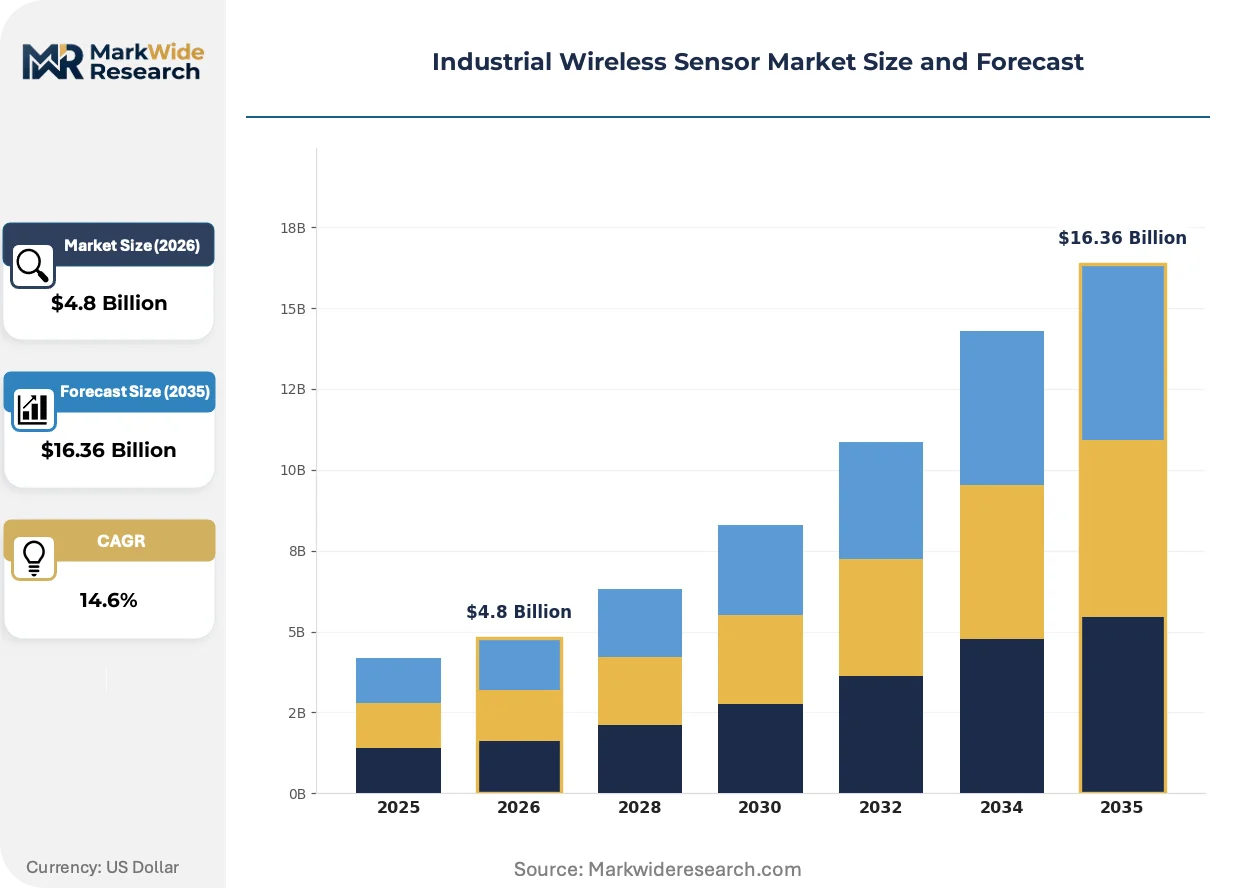
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Vibration Sensors, Humidity Sensors Technology: Zigbee, Bluetooth, LoRaWAN, NB-IoT End User: Manufacturing, Oil & Gas, Utilities, Logistics Application: Condition Monitoring, Asset Tracking, Environmental Monitoring, Predictive Maintenance |
| Companies Covered | Rockwell Automation Inc, Emerson Electric Co, ABB Ltd, NXP Semiconductors N.V., STMicroelectronics N.V., Honeywell International Inc, Schneider Electric SE, Texas Instruments Inc, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wireless Sensor Market Strategic Shifts
Digital twin architectures are virtualizing physical asset monitoring, compressing the boundary between sensor data acquisition and simulation-based optimization across heavy industry.
Edge computing hardware is virtualizing traditional gateway functions, embedding inference capabilities directly into sensor nodes. Oil refineries in Rotterdam and Houston are piloting these devices for real-time anomaly detection on centrifugal compressors. This compression of the compute stack is eliminating latency to cloud platforms while reducing backhaul bandwidth requirements for distributed facilities.
CSRD disclosure requirements in Europe are mandating granular emissions tracking that exceeds current sensor penetration in Scope 1 and Scope 2 monitoring. Chemical processors in Antwerp and Ludwigshafen are retrofitting stack and fugitive emission detection networks to meet 2024 reporting deadlines. The regulation is forcing sensor vendor qualification against new verification protocols before purchase approval.
Buyer committees in German automotive tier-one suppliers are consolidating vendor lists from twelve to four approved sensor platforms, compressing switching cycles and locking in multi-year framework agreements. This concentration is displacing spot procurement through distributor channels in favor of direct OEM relationships with calibration and firmware update obligations bundled into unit pricing. The shift is most visible in Baden-Württemberg supplier corridors serving electric powertrain transitions.
Industrial Wireless Sensor Market Segmentation
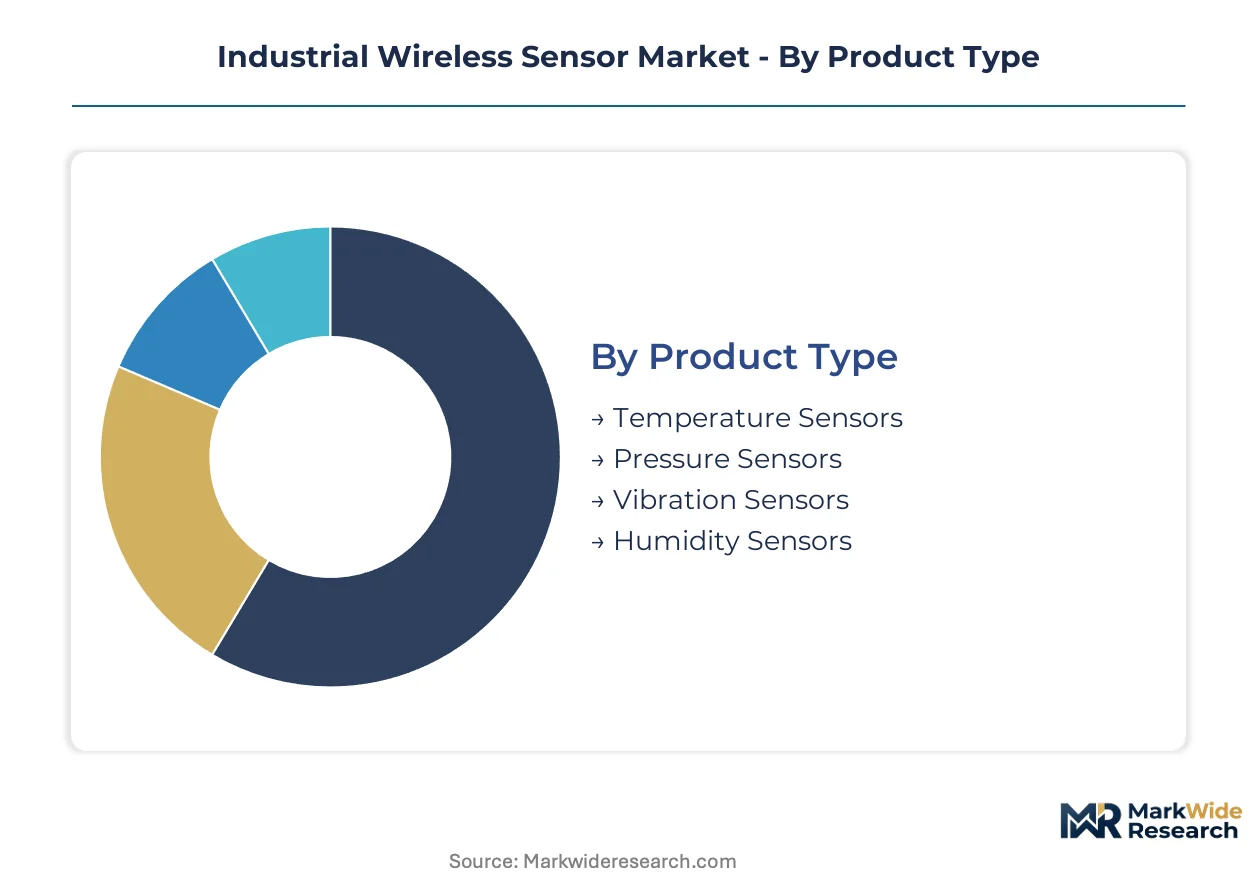
Segmentation in industrial wireless sensors reveals distinct service intensity profiles across product categories. Temperature and pressure sensors demand frequent calibration cycles, while vibration and humidity variants require minimal field intervention over their operational lifespan.
Product Type:
After-sales service intensity varies sharply across sensor categories, with temperature and pressure devices requiring recurring calibration protocols that lock in multi-year vendor relationships.
- Temperature Sensors:Thermocouple and RTD-based nodes measure process fluid and ambient thermal conditions with ±0.1°C precision in harsh environments. Demand concentrates in German chemical processing corridors along the Rhine, where REACH-mandated emissions tracking requires continuous stack monitoring. These units dominate installed base volume due to universal applicability across steam systems, rotating machinery bearings, and reactor vessels.
- Vibration Sensors:Piezoelectric accelerometers detect mechanical anomalies in rotating equipment through frequency spectrum analysis. Stuttgart automotive suppliers deploy these networks on CNC machining centers and conveyor systems to eliminate scheduled downtime. MEMS fabrication advances are compressing unit costs while extending battery life beyond seven years in field conditions.
- Pressure Sensors:Strain gauge and capacitive transducers monitor pipeline integrity and hydraulic system performance across upstream and midstream operations.
- Humidity Sensors:Capacitive polymer and resistive ceramic elements track moisture levels in cleanroom environments, cold chain logistics, and corrosion-sensitive process areas.
By volume, temperature sensors lead. By growth pace, vibration sensors are ahead.
Technology:
Protocol selection dictates gateway infrastructure investment and determines whether deployments rely on private mesh networks or cellular carrier backhaul.
- LoRaWAN:Sub-1 GHz spread-spectrum modulation enables kilometer-range links with minimal power draw, supporting ten-year battery targets in remote asset monitoring. Private network deployments dominate German automotive supplier campuses in Wolfsburg and Ingolstadt, where IT security policies restrict external connectivity. Gateways aggregate data from hundreds of nodes across distributed production halls.
- NB-IoT:Licensed cellular spectrum delivers deep indoor penetration through existing carrier infrastructure, eliminating private gateway capital expenditure. US utilities in Texas and California leverage this technology for smart meter and transformer monitoring without site-specific radio engineering. FCC spectrum allocations in 700 MHz and 800 MHz bands determine coverage reliability.
- Zigbee:IEEE 802.15.4-based mesh networking supports high-density deployments in controlled industrial environments with guaranteed latency bounds.
- Bluetooth:Short-range protocol dominates asset tracking and proximity-based maintenance workflows within confined facility footprints.
By deployment value, NB-IoT leads in utility sectors. By expansion rate, LoRaWAN is climbing fastest in private manufacturing networks.
End User:
Vertical-specific reliability requirements shape procurement specifications, with oil and gas applications demanding SIL-rated devices while logistics tolerates consumer-grade alternatives.
- Manufacturing:Discrete and process factories deploy sensor grids for equipment health monitoring, energy optimization, and quality assurance. German automotive tier-one suppliers in Baden-Württemberg are consolidating vendor lists from twelve to four approved platforms, locking in direct OEM relationships with bundled firmware update obligations.
- Oil & Gas:Upstream and midstream operators face hazardous area certification requirements under IEC 60079 standards for explosive atmosphere deployment. US Gulf Coast petrochemical clusters and Alberta oil sands operations drive demand for pressure and acoustic sensors in leak detection beyond traditional SCADA infrastructure reach.
- Utilities:Electric, water, and gas distribution networks prioritize wide-area coverage and decade-long field life over measurement precision.
- Logistics:Warehouse and cold chain operators value low unit cost and rapid deployment over calibration traceability.
By sensor density per facility, manufacturing leads. By project scale, utilities are expanding most quickly.
Application:
Use case maturity determines whether buyers seek point solutions or integrated platforms spanning multiple monitoring domains.
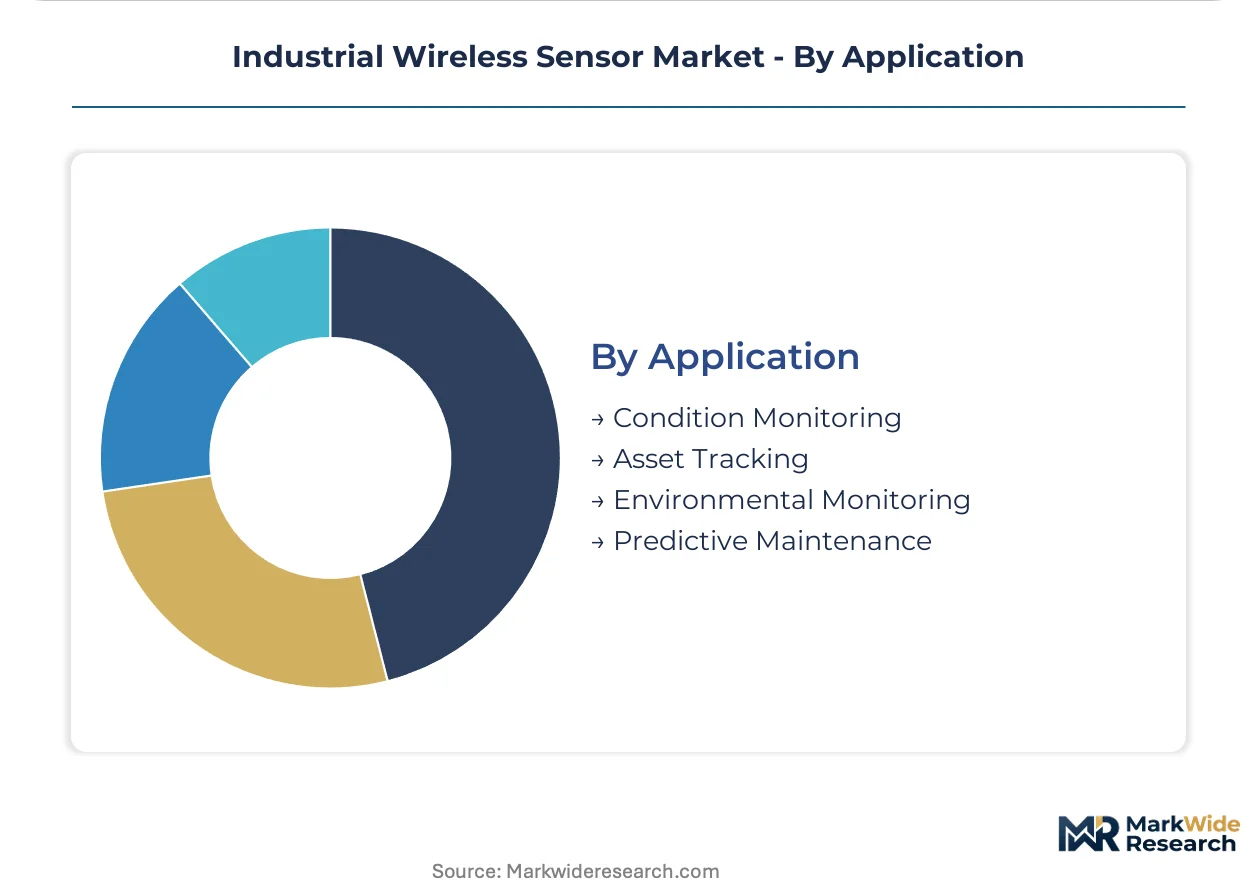
- Predictive Maintenance:Vibration and thermal anomaly detection algorithms forecast bearing failures and lubrication degradation before catastrophic breakdown. Rotterdam and Houston oil refineries pilot edge-computing sensor nodes that embed inference capabilities directly on device, eliminating cloud latency for centrifugal compressor monitoring. This application commands premium pricing due to quantifiable downtime avoidance.
- Environmental Monitoring:Emissions and ambient condition tracking responds to regulatory mandates under EU Green Deal and EPA frameworks. Chemical processors in Antwerp and Ludwigshafen retrofit stack and fugitive emission detection networks to meet CSRD disclosure requirements for granular Scope 1 and Scope 2 reporting.
- Condition Monitoring:Continuous equipment health assessment supports transition from calendar-based to condition-based maintenance regimes.
- Asset Tracking:Location and status monitoring of mobile equipment, inventory, and personnel drives logistics and warehouse optimization.
By solution maturity, condition monitoring leads. By regulatory tailwinds, environmental monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive corridors where vendor consolidation locks in multi-year frameworks, while US Gulf Coast buyers face volatile lithium-thionyl chloride costs that compress margin capture.
United States
Petrochemical clusters in Texas and Louisiana drive pressure sensor demand for pipeline integrity monitoring beyond traditional SCADA reach. FCC spectrum allocations in 700 MHz and 800 MHz bands shape NB-IoT deployment reliability for utility-scale networks. Houston refineries pilot edge-computing sensor nodes embedding inference capabilities directly on device for centrifugal compressor monitoring.
Germany
Automotive tier-one suppliers in Baden-Württemberg consolidate vendor lists from twelve to four approved platforms, locking in direct OEM relationships. EU Green Deal REACH mandates accelerate emissions tracking sensor density across Stuttgart and Wolfsburg production halls. Wolfsburg and Ingolstadt campuses deploy private LoRaWAN networks where IT security policies restrict external connectivity.
China
Dual carbon goals under MEE frameworks stimulate environmental sensor deployment across Yangtze River Delta chemical processing zones. GB standards and MIIT spectrum policy shape sub-1 GHz product certification pathways for industrial radio devices. Sichuan-Chongqing manufacturing corridors expand vibration sensor networks for equipment health monitoring in heavy machinery production.
Japan
METI industrial digitization programs accelerate predictive maintenance adoption across Kansai region automotive component suppliers. JIS interoperability requirements reduce integration friction for multi-vendor sensor deployments in private industrial networks. Nagoya-area precision manufacturers deploy high-density sensor grids for quality assurance in semiconductor fabrication equipment.
Netherlands
CSRD disclosure requirements force chemical processors in Antwerp and Rotterdam to retrofit stack and fugitive emission detection networks for granular Scope 1 reporting. ECHA REACH enforcement drives sensor vendor qualification against new verification protocols before purchase approval. Rotterdam oil refineries compress latency through edge-computing architectures eliminating cloud backhaul for distributed facilities.
Industrial Wireless Sensor Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying MEMS transducers and RF modules. The industrial wireless sensor market exhibits tiered concentration with diversified industrial conglomerates anchoring large-account relationships alongside focused sensor specialists. Two strategic archetypes dominate: full-stack automation vendors bundling sensors into control system architectures, and pure-play wireless specialists optimizing protocol stacks for private network deployment. Competitive dynamics center on backward integration into MEMS fabrication and channel control over system integrator networks.
Within the diversified automation tier, Emerson Electric Co and Siemens AG exemplify platform integrators leveraging deep R&D investment and European channel dominance respectively. Honeywell International Inc occupies a position bridging component fabrication and system integration through captive MEMS supply. Among semiconductor-based specialists, Texas Instruments Inc and NXP Semiconductors N.V. represent the RF and connectivity silicon layer supplying module vendors across multiple industrial end markets.
| Leading Market Players |
|---|
| Rockwell Automation Inc |
| Emerson Electric Co |
| ABB Ltd |
| NXP Semiconductors N.V. |
| STMicroelectronics N.V. |
| Honeywell International Inc |
| Schneider Electric SE |
| Texas Instruments Inc |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwanese MEMS foundries is compressing lead times for vibration sensor accelerometers while amplifying pricing leverage for suppliers serving German automotive corridors. This utilization squeeze tightens margins for module integrators and accelerates backward integration moves among diversified automation conglomerates.
Pricing Analysis
Configured-to-order pricing for Safety Integrity Level-certified vibration sensors commands 40-60% premiums over standard temperature monitoring nodes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and after-sales calibration bundling. Price erosion runs through economy-tier humidity sensors as logistics buyers prioritize unit cost over traceability. Manufacturing accounts in Baden-Württemberg exhibit lowest price sensitivity due to multi-year framework agreements, while cold chain logistics operators in US distribution networks drive hardest bargain negotiations.
Supply Chain Analysis
Export-control restrictions on RF front-end semiconductors limit component flows from US and Dutch suppliers to Chinese module vendors. MEMS fabrication concentrates in Taiwan, South Korea, and Japan, drawing from lithium-thionyl chloride cell supply anchored in China and Japan. Single-source vulnerability pervades specialized sub-1 GHz antenna substrates. Distribution runs through system integrator networks in European manufacturing corridors and direct OEM relationships in US utility sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock manufacturing accounts into calibration-dependent vendor relationships. Regulatory entrenchment through IEC 62591 certification timelines extends incumbent advantages.
For Market Incumbents: Harden position through captive MEMS fabrication investments in Taiwan or South Korea to offset foundry undercapacity. Deepen channel control over Stuttgart and Wolfsburg system integrators before vendor list consolidation completes. Threat substitution from edge-computing sensor nodes demands accelerated R&D in on-device inference capabilities. For New Entrants and Emerging Players: US Gulf Coast petrochemical clusters present geographic underpenetration for pressure sensor specialists lacking hazardous area certifications. Pipeline integrity monitoring beyond traditional SCADA reach offers white-space entry with acoustic leak detection differentiation. Target midstream operators through project-based commissioning models rather than spot hardware sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-computing sensor architectures as inference hardware embeds into node designs. Long-term viability favors targets with protocol stack IP and existing IEC 62591 approval pathways. Watch for inflection when German automotive buyer committees complete vendor consolidation from twelve to four approved platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive supply of accelerometers insulates Emerson and Honeywell from Taiwanese foundry bottlenecks. |
| Private LoRaWAN Network Deployment | Wolfsburg automotive campuses deploy gateways aggregating hundreds of nodes under strict IT security policies. |
| Edge-Computing Sensor Development | Rotterdam refineries pilot nodes embedding inference capabilities for centrifugal compressor anomaly detection. |
| CSRD Compliance Service Bundling | Antwerp chemical processors retrofit stack monitoring networks with vendor-qualified verification protocols. |
| Channel Consolidation Partnerships | Baden-Württemberg supplier corridors lock direct OEM relationships displacing distributor spot procurement. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads and refined through secondary validation. Primary interviews with system integrators in German automotive corridors and US Gulf Coast petrochemical clusters combined with SEC 10-K filings, customs trade data, IEEE standards documentation, and FCC spectrum allocation records. Bottom-up sensor shipment estimates triangulated against top-down industrial automation capital expenditure patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor product type, wireless protocol technology, end-user vertical, and application use case. CAGRs derived from unit volume trajectories and average selling price evolution throughout the forecast period. Industry-specific inputs incorporated MEMS fabrication capacity utilization and EU Green Deal implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese module vendors or edge-computing specialists would shift outcomes. Material shifts in IEEE 802.15.4 standard evolution or lithium-thionyl chloride supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Gimbal Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Taiwan Sensors Market