
 Ingestible Sensor Market | 2026-2036
Ingestible Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Ingestible Sensor Market Intelligence
The EU Green Deal's objective for more sustainable and resource-efficient healthcare systems is recalibrating investment toward less invasive diagnostics, including ingestible sensors. This shift favors companies developing technologies that reduce hospital stays and procedural waste. Medtronic leverages its extensive distribution network in hospital settings to introduce advanced diagnostic tools. Meanwhile, CapsoVision, Inc. specializes in capsule endoscopy with its unique 360-degree imaging technology. Otsuka Holdings Co., Ltd. pioneers the drug-device combination space, integrating sensors with pharmaceuticals to monitor patient adherence.
An ingestible sensor is a miniaturized electronic device, encapsulated in biocompatible materials, designed for safe oral ingestion and passage through the digestive system. These devices are often powered by electrochemical reactions with gastric fluids and transmit data wirelessly to an external receiver. Their primary purpose is to capture physiological data, images, or track medication adherence from within the gastrointestinal tract. Image sensors currently command a significant portion of the market value due to their technical complexity, while gastrointestinal monitoring remains the dominant application. Pharmaceutical companies and clinical research organizations are the primary end users, utilizing the technology to enhance clinical trial data and develop smart therapeutics.
The regulatory environment is defined by stringent safety and efficacy standards set by national and regional health authorities. In the United States, the FDA's 510(k) and De Novo pathways are critical for market entry, while in Europe, compliance with the Medical Device Regulation (MDR) is mandatory. Japan's PMDA imposes its own rigorous approval process for medical devices. These regulations govern biocompatibility, data security, and clinical validation, directly influencing product design and market access strategies. Stakeholder success depends on navigating complex reimbursement pathways and demonstrating clear clinical utility to both providers and payers.
Market Dynamics
The central structural force shaping the ingestible sensor market is the demand from developed healthcare systems for non-invasive diagnostic tools that improve patient outcomes and reduce procedural costs. This is driven by regulatory frameworks favoring novel medical devices.
Growth Catalysts
- Favorable Regulatory Pathways:The FDA's De Novo classification process and the EU's Medical Device Regulation (MDR) provide structured routes for market entry, encouraging innovation in diagnostic technologies.
- Advancements in Biocompatible Materials:Progress in medical-grade polymers and silicones enhances device safety and patient tolerance, expanding the scope of gastrointestinal monitoring applications.
- Pharmaceutical Sector Demand:Clinical research organizations utilize ingestible sensors to monitor medication adherence and gather precise physiological data, improving the quality and reliability of clinical trial outcomes.
Market Restraints
- High Unit Cost:The technical complexity and manufacturing expense of advanced image sensors create high per-procedure costs, limiting their use to specific, well-reimbursed applications in markets like Japan and Germany.
- Data Security and Privacy Concerns:The transmission of sensitive patient data requires robust encryption and compliance with strict regulations like HIPAA in the US and GDPR in Europe, adding development complexity.
- Power Source Limitations:Dependence on electrochemical reactions with gastric fluids for power restricts the operational lifespan of devices, posing a limitation for applications requiring extended monitoring periods.
Strategic Opportunities
- Expansion into New Applications:Development of sensors for targeted drug delivery and microbiome analysis offers significant growth potential beyond the current focus on imaging and basic physiological monitoring.
- AI and Software Integration:Combining sensor data with AI-powered analytical platforms can automate image analysis and diagnostic suggestions, creating high-value data services for healthcare providers.
- Penetration of Tier-Two Markets:As reimbursement frameworks mature, countries like South Korea and Australia present untapped opportunities for market entry, supported by their advanced healthcare infrastructures.
Industry Challenges
- Complex Reimbursement Navigation:Securing coverage and favorable payment rates from a fragmented landscape of public and private payers in the United States remains a significant operational hurdle for manufacturers.
- Interoperability with Hospital IT Systems:Integrating data streams from ingestible sensors into existing Electronic Health Record (EHR) platforms requires significant technical effort and collaboration with hospital IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ingestible Sensor Market |
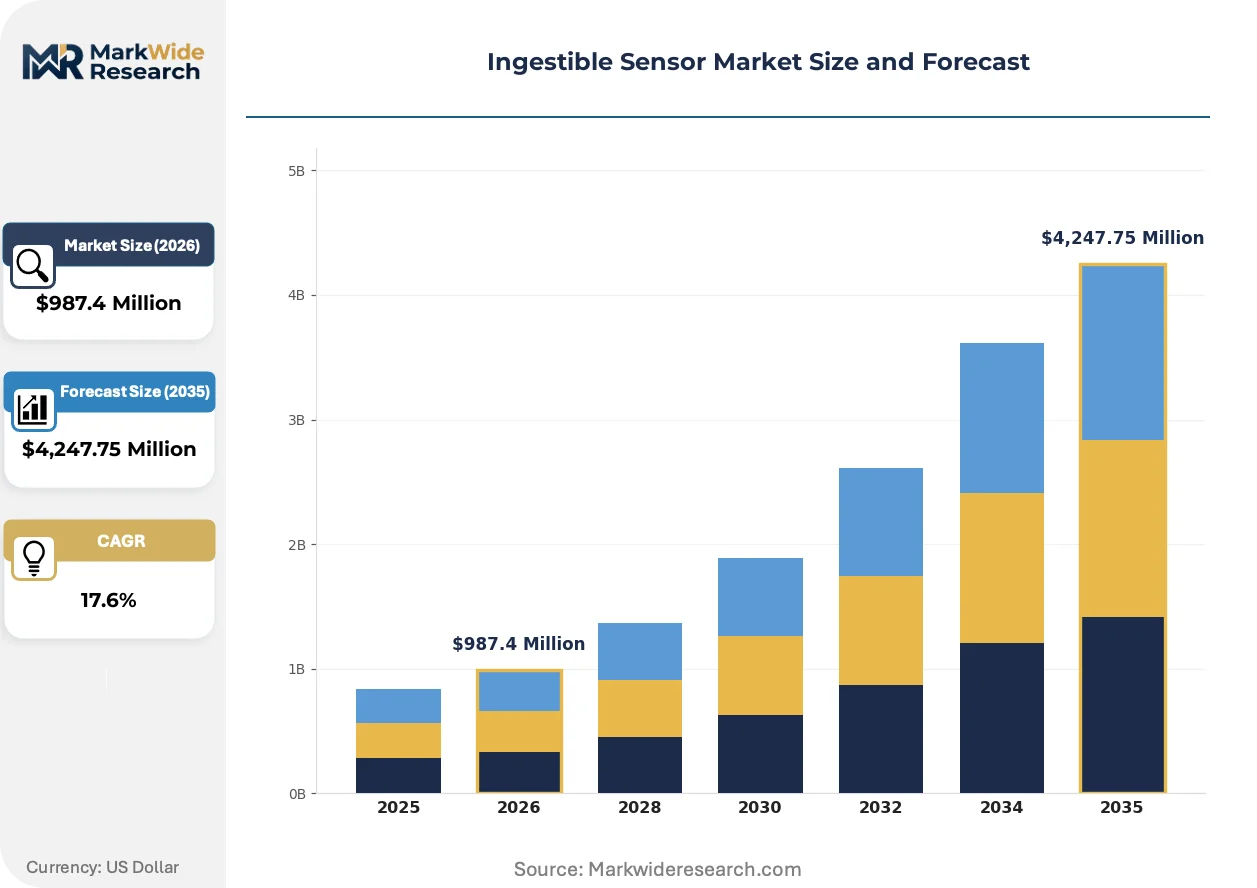
| Market Size in 2026 | $987.4 Million |
| Market Size in 2035 | $4,247.75 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Sensors, Pressure Sensors, Temperature Sensors, Image Sensors, Gas Sensors Application: Gastrointestinal Monitoring, Drug Delivery Tracking, Nutritional Evaluation, Disease Diagnosis, Motility Monitoring End User: Pharmaceutical Companies, Clinical Research Organizations, Diagnostic Laboratories, Telemedicine Providers Deployment: Hospital Settings, Outpatient Clinics, Home Care, Research Institutions |
| Companies Covered | Proteus Digital Health, Inc., etectRx, Medtronic, JINSHAN Science & Technology, HQ, Inc., Olympus Corporation, IntroMedic Co., Ltd., Otsuka Holdings Co., Ltd., CapsoVision, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ingestible Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from passive data collection to active, intelligent diagnostic systems. This shift is enabled by sensor fusion, advanced materials, and the integration of analytical software that provides actionable clinical insights directly to providers.
Multi-parameter sensors are becoming a key product innovation. These devices incorporate capabilities to measure pH, temperature, and pressure alongside imaging within a single capsule. Gastroenterology specialists and clinical research organizations are the primary adopters. This technology is converging with AI-driven software to build comprehensive physiological models, moving beyond simple visual inspection to offer deeper diagnostic context.
Europe's Medical Device Regulation (MDR) is a defining policy shift. It elevates the requirements for clinical evidence and post-market surveillance, increasing the burden of proof for manufacturers seeking market access. Consequently, companies are investing more in longitudinal studies to validate the safety and efficacy of their devices. This trend particularly affects vendors targeting major hospital systems in Germany and France.
A notable behavioral shift is occurring in how end-users acquire this technology, moving from one-time hardware purchases toward data-as-a-service (DaaS) subscription models. This disrupts the traditional capital expenditure cycle for clinics and hospitals, aligning costs with patient volume. The trend is most visible in the United States, where value-based care initiatives encourage continuous monitoring solutions that can demonstrate improved patient outcomes over time.
Ingestible Sensor Market Segmentation
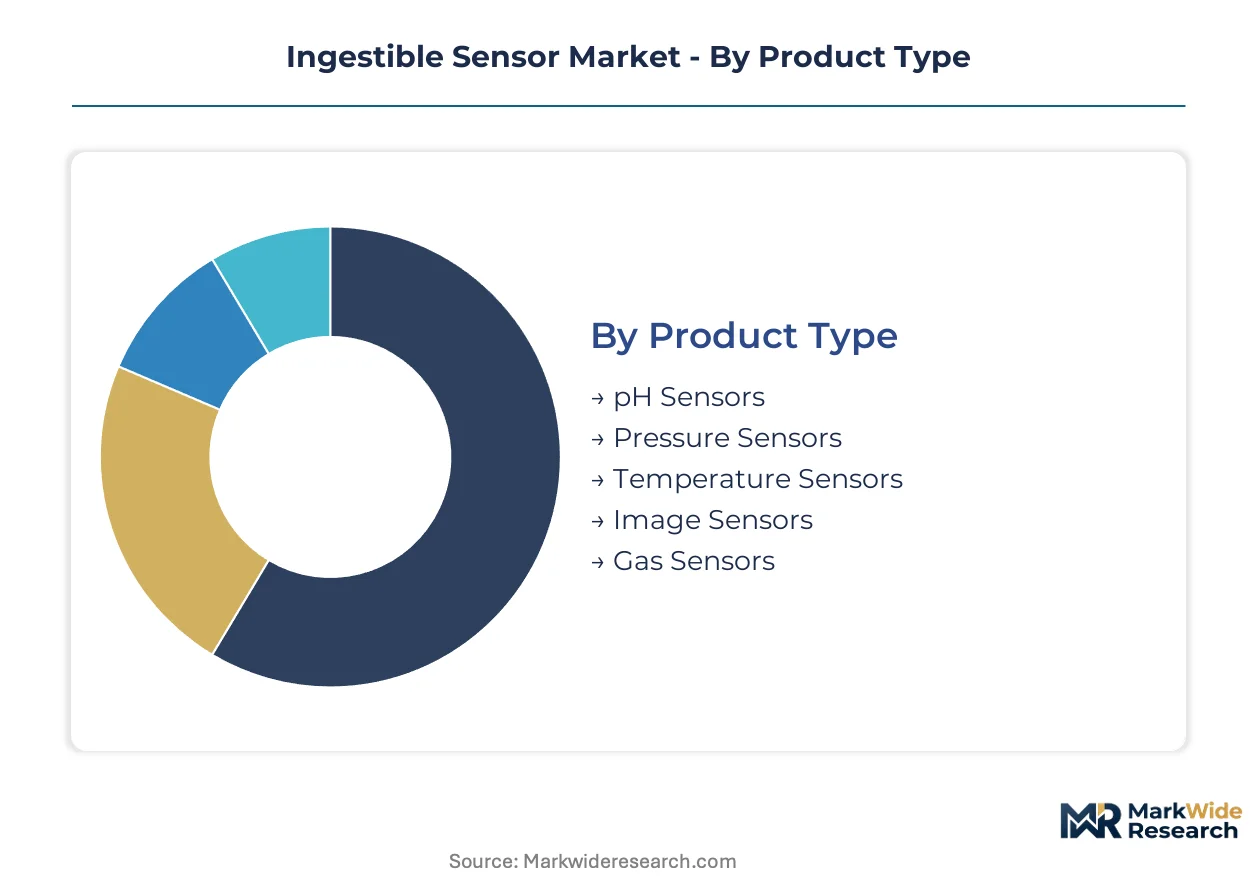
The ingestible sensor market segments reflect diverse technological capabilities and varied clinical applications across the healthcare ecosystem. Understanding these divisions helps stakeholders identify areas of concentrated investment and market expansion. Strategic positioning within these segments allows companies to optimize product development and market access initiatives.
Product Type:
Capital intensity heavily influences the development and market entry of ingestible sensor product types, with advanced imaging technologies requiring substantial upfront investment.
- Image Sensors:These miniaturized cameras capture high-resolution images from within the gastrointestinal tract, enabling detailed visual inspection for diagnostic purposes. Demand concentrates in developed healthcare markets like the United States and Germany, driven by established reimbursement pathways for advanced diagnostic tools.
- pH Sensors:These devices measure the acidity or alkalinity levels within the digestive system, providing crucial data for diagnosing conditions like GERD or assessing drug dissolution. Pharmaceutical companies utilize pH sensors to optimize drug formulations and monitor drug release profiles during clinical trials.
- Pressure Sensors:These sensors evaluate the mechanical forces and motility patterns within the GI tract.
- Temperature Sensors:These devices monitor core body temperature variations from inside the digestive system.
- Gas Sensors:These sensors detect specific gases produced in the gut, aiding in the diagnosis of certain digestive disorders.
Most installed capacity flows through Image Sensors. Expansion is steepest in pH Sensors.
Application:
The application segments delineate the primary clinical problems ingestible sensors are designed to address, ranging from diagnosis to therapeutic monitoring.
- Gastrointestinal Monitoring:This dominant application involves using sensors to assess the health, function, and pathology of the entire digestive system, including imaging and physiological data collection. Demand is particularly high in the United States and Japan, where chronic GI diseases are prevalent and advanced diagnostics are well-reimbursed.
- Drug Delivery Tracking:Sensors integrated with pharmaceuticals monitor medication adherence and drug release kinetics, providing real-time data on patient compliance and therapeutic efficacy. Clinical research organizations are primary adopters, seeking to enhance data quality in drug development.
- Nutritional Evaluation:Sensors analyze nutrient absorption and digestive processes to inform dietary interventions.
- Disease Diagnosis:This application focuses on identifying specific medical conditions through internal physiological data or imaging.
- Motility Monitoring:Sensors track the movement and transit times of food and waste through the digestive tract.
Market volume is predominantly captured by Gastrointestinal Monitoring, with Drug Delivery Tracking gaining share fastest.
End User:
End user segments reflect the institutional and organizational structures that procure and deploy ingestible sensor technology, each with distinct purchasing patterns.
- Pharmaceutical Companies:These entities utilize ingestible sensors primarily for clinical trials, monitoring medication adherence, and gathering precise physiological data to inform drug development and post-market surveillance. Their demand focuses on high-precision data collection for regulatory submissions.
- Clinical Research Organizations:CROs deploy ingestible sensors to enhance the quality and reliability of clinical trial outcomes, particularly for drug-device combination products and studies requiring objective patient adherence data. They prioritize devices that offer robust data security and seamless integration.
- Diagnostic Laboratories:These facilities process data from sensors to provide specialized diagnostic insights to clinicians.
- Telemedicine Providers:These providers integrate sensor data into remote patient monitoring platforms for chronic disease management.
Revenue generation is primarily driven by Pharmaceutical Companies, while Telemedicine Providers exhibits rapid expansion.
Deployment:
Deployment segments categorize the diverse settings where ingestible sensors are utilized, each presenting unique logistical and infrastructural requirements.
- Hospital Settings:These environments represent a major deployment channel, where sensors are used for in-patient diagnostics, pre-surgical assessments, and post-procedural monitoring, leveraging existing medical infrastructure. Medtronic utilizes its extensive distribution network to introduce advanced diagnostic tools within hospitals.
- Home Care:This segment involves patients using ingestible sensors in their own homes for continuous monitoring, medication adherence tracking, and managing chronic conditions. The United States sees significant growth in home care due to value-based care initiatives encouraging remote monitoring.
- Outpatient Clinics:These facilities use sensors for routine diagnostic procedures and follow-up care.
- Research Institutions:Academic and private research bodies employ sensors for scientific studies and technology development.
The largest patient throughput occurs in Hospital Settings, with Home Care showing significant growth in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device engineering talent across key global hubs drives innovation in the ingestible sensor market. These regions exhibit strong clinical research infrastructure and robust regulatory support for advanced diagnostic tools. Developed healthcare systems prioritize non-invasive solutions for chronic disease management.
United States
The United States exhibits strong demand for ingestible sensors due to high chronic gastrointestinal disease prevalence and value-based care models. The FDA's 510(k) and De Novo pathways provide clear routes for market entry and technology adoption. Boston's MedTech corridor fosters collaboration between startups and major pharmaceutical companies, accelerating product development.
Germany
Germany's advanced healthcare infrastructure and emphasis on sustainable, less invasive diagnostics fuel demand for ingestible sensors. Compliance with the EU's Medical Device Regulation (MDR) is mandatory for market access, ensuring high safety standards. Munich's medical technology cluster attracts significant investment in sensor R&D, focusing on precision diagnostics.
Japan
Japan's aging population and established reimbursement pathways for advanced medical technologies contribute to significant ingestible sensor adoption. The PMDA imposes rigorous approval processes, ensuring devices meet stringent safety and efficacy standards. Tokyo's pharmaceutical and medical device companies actively integrate ingestible sensors into drug development and patient monitoring.
South Korea
Maturing reimbursement frameworks and an advanced healthcare infrastructure drive the adoption of ingestible sensors in South Korea. The MFDS guides medical device approvals, balancing innovation with patient safety requirements. Seoul's vibrant biotech ecosystem supports the development of AI-powered diagnostic platforms for ingestible sensor data.
Australia
Australia demonstrates a growing focus on remote patient monitoring and chronic disease management, increasing interest in ingestible sensors. The TGA oversees medical device registration, ensuring products meet national quality and safety criteria. Melbourne's research institutions are exploring new applications for ingestible sensors in microbiome analysis and targeted drug delivery.
Ingestible Sensor Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the ingestible sensor market, creating a tiered competitive structure. The market sees a mix of established medical device giants and specialized technology firms. Strategic archetypes include diversified healthcare conglomerates, focused imaging solution providers, and drug-device combination innovators. Companies primarily pursue strategic partnerships to expand distribution and invest in portfolio diversification to capture new application areas.
Specialists in capsule endoscopy include CapsoVision, Inc., a United States-based firm known for its imaging solutions with unique 360-degree technology. Medtronic, Inc., a diversified global healthcare technology company, represents the established medical device giant archetype, leveraging its extensive hospital distribution network. Otsuka Holdings Co., Ltd., a Japan-based pharmaceutical group, exemplifies innovators in the drug-device combination space, integrating sensors with pharmaceuticals to monitor patient adherence. These entities anchor distinct segments of the market, from advanced diagnostic imaging to precise medication adherence monitoring, demonstrating varied strategic focuses.
| Leading Market Players |
|---|
| Proteus Digital Health, Inc. |
| etectRx |
| Medtronic |
| JINSHAN Science & Technology |
| HQ, Inc. |
| Olympus Corporation |
| IntroMedic Co., Ltd. |
| Otsuka Holdings Co., Ltd. |
| CapsoVision, Inc. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's objective for more sustainable healthcare systems gates both qualified supply and premium-tier pricing access for ingestible sensors. This mandate drives demand for devices that reduce hospital stays and procedural waste, influencing market value. The market's structural forces shape pricing power and supply choices.
Pricing Analysis
Bundled data-as-a-service (DaaS) subscription models compete with per-procedure transactional costs in the ingestible sensor market. Price differentiation stems from technical complexity, particularly for image sensors, and the depth of diagnostic insights provided by integrated AI software. Pricing softness reflects pressure from value-based care initiatives in the United States, which prioritize cost-effectiveness and patient outcomes. Telemedicine Providers exhibit the highest price sensitivity, while Pharmaceutical Companies are least sensitive due to critical clinical trial data requirements.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by buyers to mitigate supply chain risks for ingestible sensors. Geographic supply concentration for advanced manufacturing centers on the United States, Germany, and Japan, where specialized medical device engineering talent resides. Raw material dependencies include biocompatible polymers, miniaturized electronic components, and advanced imaging sensors. Regulatory compliance variations, particularly across FDA, MDR, and PMDA frameworks, present a significant structural risk. Distribution runs through established direct sales channels to hospitals and clinical research organizations, supplemented by specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ingestible sensor market presents a geographic-arbitrage play, with differing regulatory clearance pathways like the FDA's 510(k) and PMDA's rigorous approval processes creating varied market access opportunities.
For Market Incumbents: Hedge against market fragmentation by diversifying product portfolios into adjacent applications like targeted drug delivery and microbiome analysis. Invest heavily in AI-powered software integration to transform passive data collection into actionable diagnostic insights, leveraging existing distribution networks in hospital settings. Reinforce channel control by securing long-term contracts with major hospital systems, countering the threat of specialized new entrants.
For New Entrants and Emerging Players: Enter via niche applications or underserved geographic markets, focusing on areas like home care monitoring for chronic GI conditions. Target tier-two markets such as South Korea and Australia, where reimbursement frameworks are maturing and healthcare infrastructure is advanced. A compelling go-to-market angle involves offering data-as-a-service (DaaS) subscription models, aligning costs with patient volume for clinics and telemedicine providers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized technology firms because structural fragmentation across application areas creates distinct acquisition targets. Long-term viability hinges on the sustained demand for non-invasive diagnostic tools in aging populations and the shift towards value-based care. Identify acquisition targets with strong intellectual property in multi-parameter sensors or AI integration capabilities. The signal to watch is increasing reimbursement for remote patient monitoring solutions in developed markets.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Integration | Automates image analysis and diagnostic suggestions for healthcare providers. |
| Multi-Parameter Sensor Development | Expands diagnostic capabilities beyond imaging for gastroenterology specialists. |
| Reimbursement Pathway Navigation | Secures favorable payment rates from public and private payers in key markets. |
| Home Care Channel Partnership | Extends market reach for continuous monitoring solutions in chronic disease management. |
| Biocompatible Material Innovation | Enhances device safety and patient tolerance for extended monitoring applications. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for the ingestible sensor market. This approach combines extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary insights were gathered from clinical researchers, pharmaceutical procurement leads, hospital IT managers, and medical device engineers. Secondary sources included FDA 510(k) clearances, EU MDR compliance documents, PMDA approval records, and medical journal databases.
The input-output matrix framing guided the construction of the forecast framework across the projection horizon. This involved modeling market segments by product type, application, end user, deployment, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected market drivers such as the increasing prevalence of gastrointestinal diseases and evolving healthcare expenditure patterns.
Inputs from regulatory bodies and industry reports were available through the study window; gaps in real-time patient data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and healthcare policy stability. Deviation in unforeseen regulatory changes or rapid technological obsolescence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market