
 Middle East and Africa Wearable Sensors Market | 2026-2036
Middle East and Africa Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Wearable Sensors Market Foresight
A capital-intensity divergence between foundry-dependent and vertically integrated players is rotating competitive advantage toward firms with captive MEMS fabrication. STMicroelectronics leverages its in-house sensor foundry to sustain margin control across temperature and pressure wearable modules. Infineon Technologies AG anchors its position through specialized biometric authentication chipsets designed for arid-climate reliability.
Wearable sensors in the Middle East and Africa comprise microelectromechanical systems, photoplethysmography arrays, and electrochemical transducers packaged for skin-contact deployment, typically operating at power budgets below 1 milliwatt to preserve battery life in Bluetooth-connected form factors. These devices enable continuous physiological signal acquisition for clinical decision support and occupational safety monitoring. Smart watches occupy the dominant revenue position due to consumer familiarity and healthcare provider pilot programs, while biosensors represent the fastest-expanding category as remote patient monitoring protocols gain reimbursement traction. Fitness trackers face margin compression from white-label competition, though cellular-enabled models for elderly fall detection command premium positioning.
South Africa's Health Products Regulatory Authority and the UAE's Ministry of Health and Prevention enforce medical device classification standards that determine market access timelines for connected wearables, with Saudi Arabia's Food and Drug Authority introducing software-as-a-medical-device guidelines that reshape product registration requirements. CE marking alignment remains essential for manufacturers serving Gulf Cooperation Council procurement channels. Stakeholders must monitor harmonization between national medical device frameworks and emerging data sovereignty laws governing cross-border health telemetry.
Market Dynamics
Capable MEMS foundry access is fragmenting competitive advantage across the Middle East and Africa wearable sensors landscape, rewarding firms with captive fabrication while squeezing margins for fabless designers dependent on external wafer supply.
Growth Catalysts
- Remote patient monitoring reimbursement:South Africa's Health Products Regulatory Authority is accelerating registration pathways for connected biosensors used in chronic disease management protocols.
- Smart city infrastructure deployment:Dubai Health Authority corridor investments are embedding environmental and physiological sensors into municipal wellness networks.
- Photoplethysmography miniaturization:Advances in optical array packaging are enabling continuous SpO2 and heart-rate monitoring at sub-milliwatt power budgets.
Market Restraints
- MEMS wafer supply concentration:Foundry capacity for piezoelectric sensor substrates concentrates in East Asian contract manufacturers, exposing regional assemblers to allocation risk.
- Medical device classification friction:Saudi Arabia's Food and Drug Authority software-as-a-medical-device guidelines are extending product registration timelines for algorithm-enabled wearables.
- Cellular module cost structure:Qualcomm and MediaTek baseband chipsets represent 35-40% of bill-of-materials for LTE-M enabled fall-detection trackers.
Strategic Opportunities
- Occupational safety monitoring in mining:South Africa's platinum and gold extraction sectors are piloting heat-stress and fatigue biosensors for underground workforce protection.
- CE marking harmonization:Alignment with EU MDR standards is opening Gulf Cooperation Council procurement channels for European-certified manufacturers.
- Electrochemical transducer convergence:Integration of continuous glucose monitoring with multi-analyte sweat sensors is creating metabolic health monitoring white space.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 skin-contact testing protocols are extending time-to-market for new adhesive patch form factors by 8-14 months.
- Embedded firmware talent scarcity:Bluetooth Low Energy stack optimization and sensor fusion algorithm development skills concentrate in Cairo, Lagos, and Johannesburg metro labor pools.
- Cross-border health telemetry compliance:Emerging data sovereignty laws in Nigeria and Kenya are complicating cloud architecture for multi-national remote monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Wearable Sensors Market |
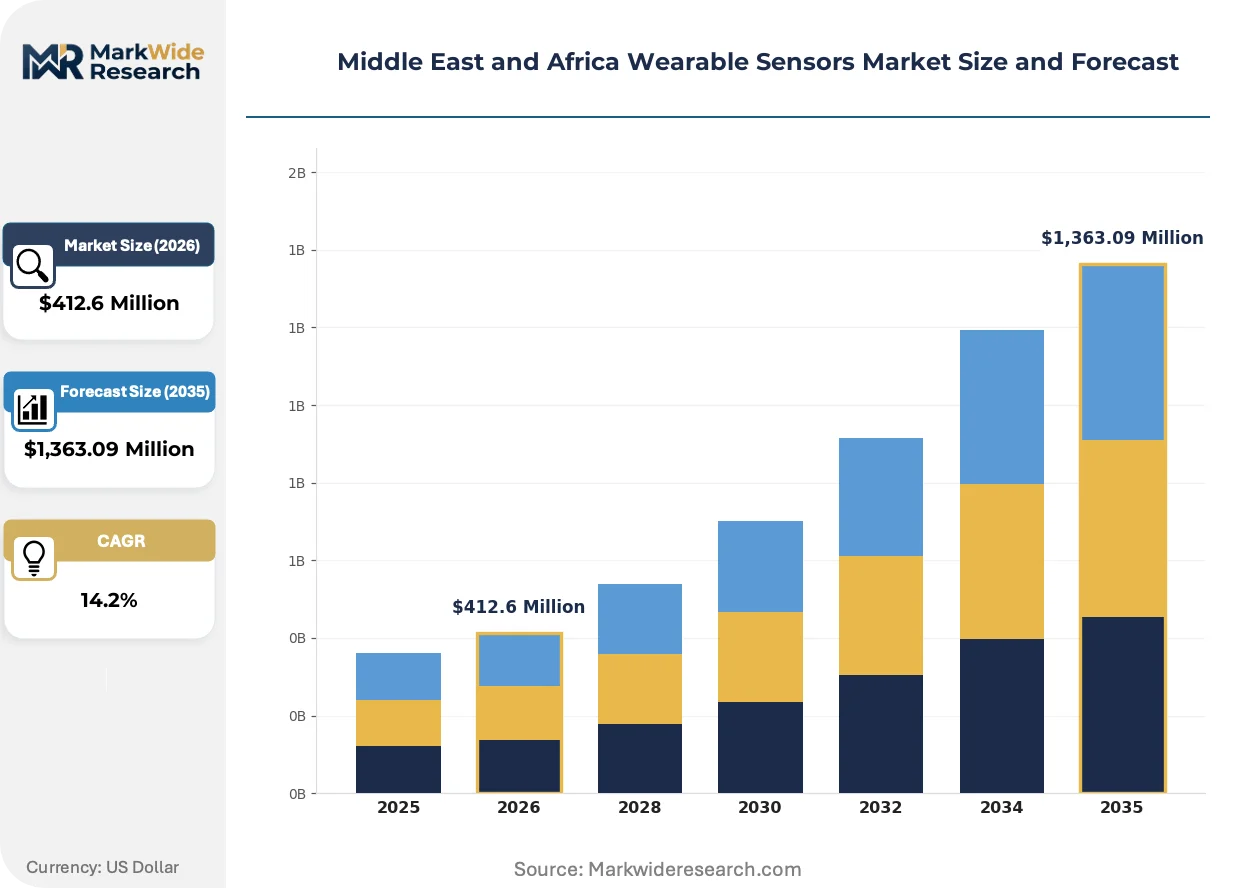
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Fitness Trackers, Smart Clothing, Biosensors Technology: Bluetooth, NFC, Wi-Fi, Cellular End User: Healthcare Providers, Fitness Enthusiasts, Consumers, Industrial Users Application: Health Monitoring, Fitness Tracking, Remote Patient Monitoring, Biometric Authentication |
| Companies Covered | Analog Devices, Huawei Technologies, STMicroelectronics, Honeywell International, NXP Semiconductors, Infineon Technologies AG, Panasonic Corporation, Mitsubishi Electric Corporation, Texas Instruments Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Wearable Sensors Market Shifts & Advancements
Power-efficient signal processing architectures are redefining wearable sensor competitive economics, while regulatory alignment and procurement model evolution are reshaping how devices reach end-users across the Middle East and Africa.
Photoplethysmography array integration is fragmenting the optical heart-rate monitoring segment. Smart watch manufacturers in the UAE are adopting discrete multi-LED configurations to differentiate clinical-grade accuracy from fitness-tier approximations. This technology is fragmenting supplier tiers into medical-certified and consumer-grade camps, compressing margins for undifferentiated optical module vendors.
Saudi Arabia's Food and Drug Authority software-as-a-medical-device guidelines are recalibrating product development roadmaps. Algorithm-enabled wearables now require standalone clinical validation dossiers separate from hardware registration. Cardiovascular monitoring applications face the steepest compliance burden, driving some manufacturers to strip diagnostic claims from initial submissions.
Hospital procurement consortia are consolidating wearable sensor purchasing across the Gulf Cooperation Council. Dubai Health Authority and Abu Dhabi Health Services are negotiating multi-year framework agreements that displace distributor networks. This concentration is most visible in the UAE, where single-source contracts for remote patient monitoring kits now cover 12-18 month deployment cycles.
Middle East and Africa Wearable Sensors Market Segmentation
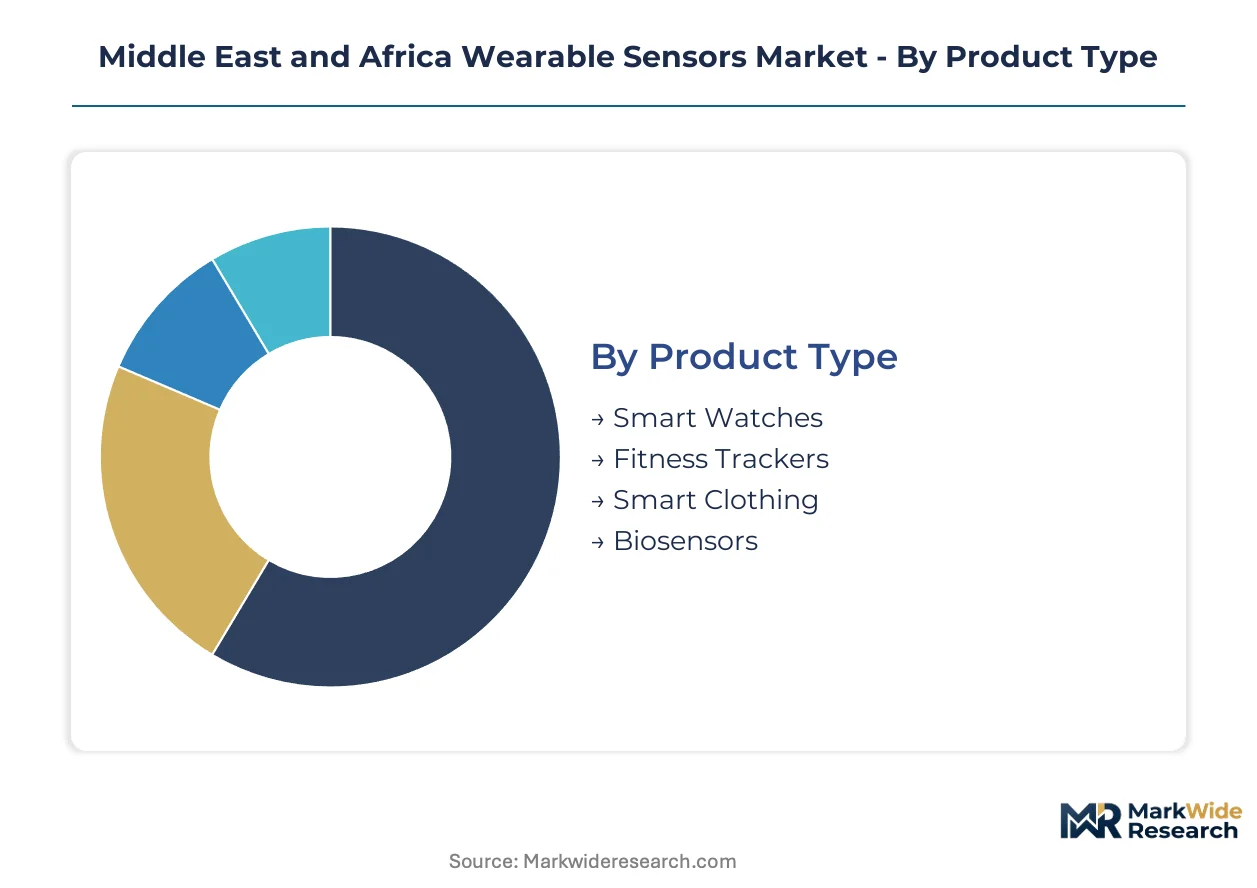
Wearable sensor segmentation across the Middle East and Africa reveals divergent margin architectures. Product type and technology choices determine whether vendors capture healthcare reimbursement premiums or compete in commoditized consumer tiers.
Product Type:
Margin pools concentrate in clinical-grade form factors that command regulatory certification premiums, while consumer electronics face white-label compression.
- Smart Watches:These devices integrate photoplethysmography arrays, accelerometers, and temperature sensors within sealed enclosures rated for continuous skin contact. Demand clusters in the UAE's Dubai Health Authority corridor, where hospital procurement consortia specify clinical-grade accuracy for remote patient monitoring pilots. Smart watches hold installed capacity. Biosensors is rotating up the share rankings.
- Fitness Trackers:Basic step-counting and sleep-monitoring modules operate at stripped power budgets below 0.5 milliwatts to extend coin-cell battery life. South African retail channels and Nigerian e-commerce platforms drive volume, though cellular-enabled elderly fall-detection variants command premium positioning in Johannesburg metro healthcare networks.
- Smart Clothing:Textile-integrated conductive yarns and stretchable electrodes enable whole-body physiological mapping without skin-adhesive interfaces. Israeli sports technology firms and UAE occupational safety programs are piloting heat-stress monitoring garments for outdoor workforce deployment.
- Biosensors:Electrochemical transducers packaged as adhesive patches enable continuous glucose, lactate, and cortisol monitoring through interstitial fluid analysis. Saudi Arabia's SFDA software-as-a-medical-device guidelines are accelerating registration pathways for algorithm-enabled metabolic monitoring platforms.
Smart watches capture the largest revenue base. Biosensors is climbing the fastest as chronic disease management protocols expand reimbursement coverage.
Technology:
Connectivity selection determines power budget allocation and bill-of-materials structure, with cellular modules imposing the steepest cost premiums.
- Bluetooth:Low-energy stacks dominate wrist-worn consumer devices, with Nordic Semiconductor and Silicon Labs chipsets enabling sub-1-milliwatt standby consumption. Bluetooth holds installed capacity. Cellular is rotating up the share rankings.
- NFC:Near-field communication enables tap-to-authenticate medical device pairing and payment integration in UAE smart city deployments. The Dubai Health Authority corridor specifies NFC for secure patient identity verification in hospital-issued wearable kits.
- Wi-Fi:Higher throughput supports firmware-over-the-air updates and bulk physiological data offload in clinical settings. South African private hospital networks deploy Wi-Fi-enabled patches for inpatient continuous monitoring where cellular coverage is unreliable.
- Cellular:LTE-M and NB-IoT baseband chipsets from Qualcomm and MediaTek enable standalone operation without smartphone tethering. Elderly fall-detection and lone-worker safety applications in Saudi Arabia and the UAE absorb module costs that reach 40% of device bill-of-materials.
Bluetooth dominates shipment volume. Cellular is expanding most quickly as standalone safety applications displace smartphone-dependent architectures.
End User:
Customer type determines pricing architecture and regulatory pathway complexity, with healthcare procurement commanding multi-year framework premiums.
- Healthcare Providers:Hospital systems and clinic networks specify ISO 13485 quality management and CE marking alignment for connected diagnostic devices. The UAE's Ministry of Health and Prevention and Saudi Arabia's SFDA enforce medical device classification standards that extend registration timelines for algorithm-enabled wearables.
- Fitness Enthusiasts:Performance-oriented consumers demand GPS accuracy and training load metrics that exceed basic consumer-tier specifications. South African endurance sports retail channels and Kenyan running clubs drive demand for multi-sensor wrist-worn devices.
- Consumers:Mass-market purchasers prioritize aesthetics and smartphone ecosystem compatibility over clinical accuracy. Nigerian and Egyptian e-commerce platforms distribute white-label devices that compete primarily on price positioning.
- Industrial Users:Mining, oil and gas, and logistics operators deploy environmental and physiological monitoring for workforce safety compliance. South Africa's platinum and gold extraction sectors pilot heat-stress and fatigue biosensors for underground worker protection.
Healthcare providers anchor premium pricing. Industrial users are gaining share fastest as occupational safety regulations tighten across extractive industries.
Application:
Use case specificity determines sensor fusion complexity and algorithm validation requirements, with diagnostic claims triggering the steepest regulatory burdens.
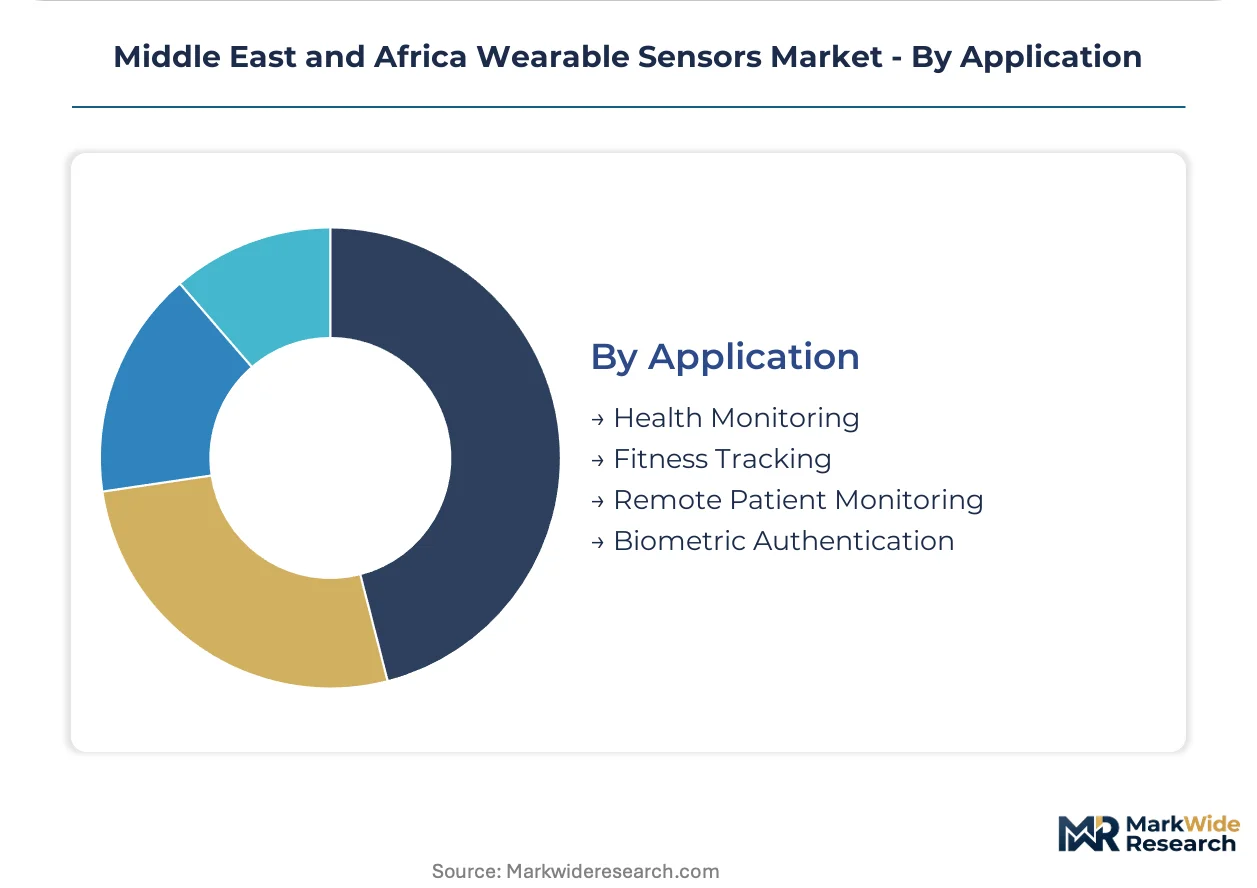
- Health Monitoring:Continuous heart rate, SpO2, and temperature tracking for general wellness awareness. Consumer smart watches in the UAE and Saudi Arabia compete on optical array LED count and FDA-cleared algorithm claims.
- Fitness Tracking:Activity classification, calorie estimation, and recovery metrics for athletic performance optimization. Kenyan and Ethiopian distance running communities drive demand for GPS-accurate multi-sport watches.
- Remote Patient Monitoring:Clinical-grade physiological data transmission to healthcare providers for chronic disease management. South Africa's Health Products Regulatory Authority is accelerating registration pathways for connected biosensors used in hypertension and diabetes protocols.
- Biometric Authentication:Heart rate variability and gait pattern recognition for continuous identity verification. UAE smart city infrastructure and Saudi financial services pilot behavioral biometrics for frictionless security.
Health monitoring holds installed capacity. Remote patient monitoring is rotating up the share rankings as reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across the Middle East and Africa wearable sensors landscape, with South African public health procurement demanding sub-dollar unit economics while UAE hospital consortia absorb 40% premiums for clinical-grade certification.
United Arab Emirates
Dubai Health Authority corridor investments are embedding biosensors into municipal wellness networks. The Ministry of Health and Prevention enforces medical device classification standards that extend registration timelines for algorithm-enabled wearables. Abu Dhabi Health Services negotiates multi-year framework agreements that consolidate procurement across remote patient monitoring kits.
Saudi Arabia
The Food and Drug Authority software-as-a-medical-device guidelines are recalibrating product development roadmaps for cardiovascular monitoring applications. Reimbursement traction for chronic disease management protocols is accelerating biosensor deployment in Riyadh and Jeddah hospital networks. NEOM Northwest smart city infrastructure pilots continuous physiological monitoring for workforce safety compliance.
South Africa
The Health Products Regulatory Authority is accelerating registration pathways for connected biosensors used in hypertension and diabetes protocols. Platinum and gold extraction sectors in the North West and Gauteng provinces pilot heat-stress and fatigue sensors for underground worker protection. Johannesburg metro healthcare networks command premium positioning for cellular-enabled elderly fall-detection trackers.
Israel
Sports technology firms in Tel Aviv and Haifa are piloting textile-integrated conductive yarns for whole-body physiological mapping. The national medical device regulator aligns with EU MDR standards to open European export channels. Defense and aerospace clusters in the Negev region are adapting biometric authentication chipsets for arid-climate reliability specifications.
Egypt
E-commerce platforms in Cairo and Alexandria distribute white-label fitness trackers that compete primarily on price positioning. The central health authority is drafting data sovereignty laws governing cross-border health telemetry that complicate cloud architecture for multi-national platforms. Nile Delta manufacturing zones are assembling Bluetooth Low Energy modules for regional re-export.
Middle East and Africa Wearable Sensors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa wearable sensors market. Captive MEMS fabrication capabilities concentrate margin control with vertically integrated semiconductor houses, while fabless designers dependent on East Asian foundry capacity face allocation risk and compressed pricing power. Three archetypes dominate: integrated device manufacturers with in-house sensor foundries, specialized biometric chipset providers, and contract assemblers serving white-label consumer tiers. Competitive moves center on backward integration into wafer supply and strategic partnerships with Gulf Cooperation Council hospital procurement consortia.
Within the integrated device manufacturer tier, STMicroelectronics and Infineon Technologies AG exemplify players with captive MEMS fabrication capabilities that sustain margin control across temperature and pressure wearable modules. Texas Instruments Incorporated occupies a position among diversified semiconductor houses with broad analog and embedded processing portfolios. These companies represent the technology leadership vector where clinical-grade certification premiums accrue to firms with in-house quality management systems aligned to ISO 13485 standards.
| Leading Market Players |
|---|
| Analog Devices |
| Huawei Technologies |
| STMicroelectronics |
| Honeywell International |
| NXP Semiconductors |
| Infineon Technologies AG |
| Panasonic Corporation |
| Mitsubishi Electric Corporation |
| Texas Instruments Incorporated |
| Others |
Supply & Pricing Matrix
Photoplethysmography array miniaturization is displacing discrete optical modules across Middle East and Africa wearable sensor production, simultaneously shifting procurement geography toward East Asian LED packaging clusters and compressing unit economics for clinical-grade wrist-worn devices destined for Dubai Health Authority hospital consortia.
Pricing Analysis
After-sales firmware subscription tiers now drive lifetime value capture across remote patient monitoring deployments, with healthcare providers in the UAE and Saudi Arabia absorbing multi-year service contracts that offset hardware margin compression. Pricing stratifies across clinical-certified, consumer-grade, and white-label economy tiers, with ISO 13485 alignment commanding 35-40% premiums in Gulf Cooperation Council procurement channels. Cost compression in fitness tracker segments is intensifying because white-label competition from Egyptian and Nigerian distributors floods retail channels with sub-dollar units. Hospital procurement committees exhibit lowest price sensitivity, while mass-market consumers in Cairo and Lagos metro areas drive aggressive unit economics demands.
Supply Chain Analysis
Strategic stockpile preferences dominate MEMS wafer procurement as South African assemblers buffer against East Asian foundry allocation volatility, while UAE-based manufacturers maintain lean just-in-time inventories for Bluetooth Low Energy chipsets with shorter replenishment cycles. Captive fabrication concentrates in Taiwan and South Korea for piezoelectric sensor substrates, with raw material dependencies spanning silicon wafers, indium phosphide for optical arrays, and specialty polymers for skin-contact adhesives. Single-source vulnerability in Qualcomm and MediaTek baseband supply exposes LTE-M enabled fall-detection tracker production to allocation risk. Distribution runs through Dubai-based logistics hubs serving Gulf Cooperation Council hospital networks, with Johannesburg and Cairo anchoring sub-Saharan African channel reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where SFDA software-as-a-medical-device compliance timelines and ISO 10993 biocompatibility certification create switching costs that cement incumbent positions across chronic disease management protocols.
For Market Incumbents: Consolidate backward integration into captive MEMS fabrication to defend margin control against fabless competitors exposed to East Asian wafer allocation risk. Deepen certification investment in Saudi Arabia's evolving software-as-a-medical-device framework to extend registration timeline advantages over emerging entrants lacking clinical validation infrastructure. Prioritize channel control through direct hospital procurement consortia relationships in the UAE, displacing distributor networks that fragment pricing power. For New Entrants and Emerging Players: Anchor in occupational safety monitoring for South African mining operations, where heat-stress and fatigue biosensor demand outpaces established vendor supply and regulatory barriers remain lower than clinical diagnostic tiers. Target cellular-enabled elderly fall-detection variants in Johannesburg metro healthcare networks, where premium positioning absorbs module cost structures that exclude commodity competitors. Pursue go-to-market angles through industrial safety compliance officers rather than hospital biomedical engineering committees to bypass entrenched procurement relationships. For Investors and Strategic Acquirers: The market sits at a reimbursement-expansion phase that favors vertically integrated device manufacturers with captive fabrication and ISO 13485 quality management alignment. Long-term viability over the next decade hinges on regulatory entrenchment depth rather than consumer brand recognition, privileging acquisition targets with established SFDA and MOHAP registration dossiers. Watch reimbursement framework maturation for remote patient monitoring protocols as the primary inflection signal; accelerated coverage expansion would warrant model refresh toward clinical-grade biosensor platforms.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Software-as-a-Medical-Device Registration | Algorithm-enabled cardiovascular monitoring platforms require standalone clinical validation dossiers separate from hardware submissions. |
| Hospital Procurement Consortium Partnership | Dubai Health Authority and Abu Dhabi Health Services negotiate multi-year framework agreements that displace distributor networks. |
| Captive MEMS Fabrication Investment | In-house sensor foundry capacity insulates margin control from East Asian contract manufacturer allocation volatility. |
| Occupational Safety Pilot Deployment | South African platinum and gold extraction sectors trial heat-stress biosensors for underground workforce protection compliance. |
| Cellular Module Cost Structure Optimization | Qualcomm and MediaTek baseband chipsets represent 35-40% of bill-of-materials for standalone LTE-M safety applications. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at SFDA and MOHAP, then refined through secondary validation across FDA 510(k) filings, CE marking databases, hospital procurement records, and customs trade data for MEMS component flows. Bottom-up shipment estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Variance decomposition across product type, connectivity technology, end-user category, and application use case shaped the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against macro healthcare infrastructure investment trajectories. Modeled inputs included reimbursement policy velocity for remote patient monitoring protocols, foundry capacity expansion announcements, and smart city biosensor deployment schedules.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions between Gulf Cooperation Council medical device frameworks and EU MDR standards; material deviation would warrant model refresh. Revision becomes warranted when data sovereignty law implementation in Nigeria or Kenya crosses thresholds that fragment cloud architecture for multi-national remote monitoring platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Europe Water Detection Sensors Market