
 CZ Silicon Wafer Market | 2026-2036
CZ Silicon Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
CZ Silicon Wafer Market Insights
ISO 9001 quality management certification is reorganizing supplier qualification protocols for automotive and aerospace silicon buyers. Shin-Etsu Chemical leverages captive polysilicon supply to control raw material costs across its CZ wafer divisions. SUMCO Corporation anchors its position through dedicated 300mm epitaxial wafer capacity serving logic and memory foundries. GlobalWafers competes by extending manufacturing footprints across Europe and Asia to reduce logistics exposure.
Czochralski (CZ) silicon wafers are single-crystal semiconductor substrates produced by pulling a seed crystal from molten silicon at approximately 1,412°C, with dopant precision controlling resistivity from 0.001 to 10,000 ohm-cm for targeted electronic performance. These wafers serve as the foundational platform for integrated circuit fabrication, photovoltaic cell construction, and MEMS sensor manufacturing where crystalline perfection determines device yield. The 12-inch diameter segment leads in revenue contribution as foundries migrate to larger formats for die-cost optimization, while single crystal form dominates technical applications requiring minimal defect density. Polycrystalline alternatives occupy cost-sensitive solar segments where efficiency trade-offs align with module economics.
Japan's METI enforces JIS standards for semiconductor material traceability, while South Korea's MFDS coordinates with industry on export control classifications for advanced substrate technologies. China's SAMR and MIIT jointly administer GB standards that mandate furnace energy efficiency disclosures and restrict obsolete crystal growth equipment imports. REACH compliance in Europe constrains dopant chemistries and surface treatment agents, forcing reformulation investments across Asian suppliers serving EU chipmakers. Stakeholders must monitor evolving multilateral export control alignments between Japan, the Netherlands, and the United States that threaten to fragment equipment and substrate procurement channels.
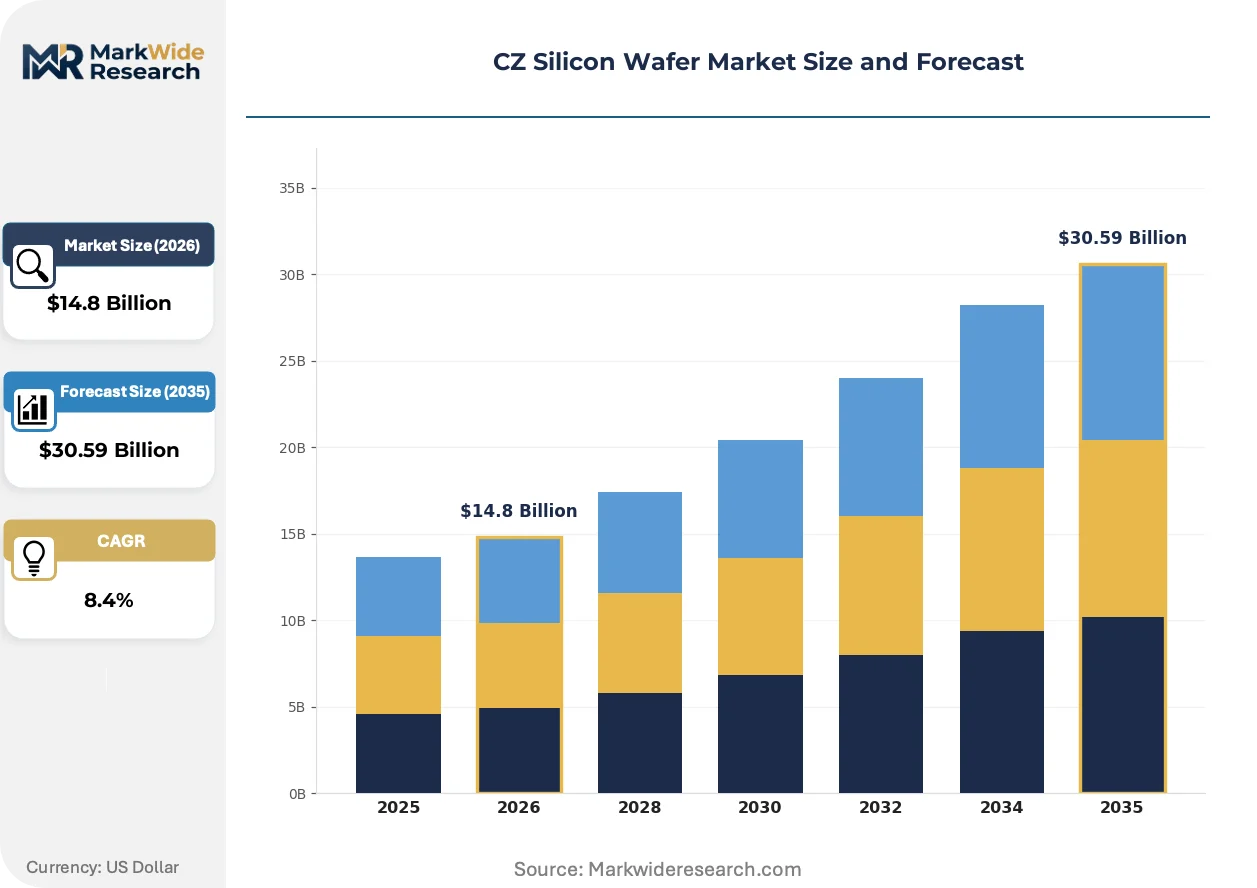
Market Dynamics
Advanced node migration at logic foundries is compressing substrate qualification cycles while furnace energy regulations in China force capital retooling decisions.
Growth Catalysts
- Automotive silicon carbide integration:Power module manufacturers are qualifying 300mm CZ substrates for traction inverter applications under AEC-Q100 standards. Vehicle electrification mandates from regulators in Germany and Japan accelerate substrate sampling volumes.
- MIIT furnace efficiency mandates:China's GB standards for crystal growth equipment energy intensity are phasing out obsolete pullers. Domestic fab expansion creates captive demand for compliant 12-inch wafers.
- MEMS sensor proliferation:IoT device manufacturers are specifying low-resistivity CZ wafers for pressure and inertial sensors. Medical and industrial automation end-uses drive batch consistency requirements.
Market Restraints
- Polysilicon supply concentration:Metallurgical-grade silicon refining capacity clusters in specific Chinese provinces. Geopolitical trade measures threaten feedstock cost stability for non-integrated wafer manufacturers.
- REACH dopant constraints:European chemical regulations restrict arsenic and antimony surface treatments. Reformulation investments burden Asian suppliers serving EU semiconductor fabs.
- Epitaxial deposition substitution:Silicon-on-insulator and advanced epitaxial stacks reduce reliance on bulk CZ substrates for certain RF applications. Process integration at foundries compresses addressable wafer volume.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme allocations for display and logic fabs create virgin demand for 200mm and 300mm substrates. Domestic crystal growth capability gaps invite technology partnerships.
- Photonics substrate specification:Silicon photonics foundries require specialized resistivity profiles for modulator and detector integration. Telecom datacenter buildouts in Japan and South Korea drive custom wafer development.
- Carbon border adjustment mechanisms:EU CBAM implementation favors low-carbon-intensity crystal growth processes. Furnace electrification and renewable energy sourcing become competitive differentiators.
Industry Challenges
- Crystal defect engineering expertise:Advanced node substrate manufacturing requires precise oxygen precipitate control. Foundry customers report qualification failures from interstitial cluster variations.
- Multi-standard certification timelines:Automotive, aerospace, and medical device wafer specifications demand overlapping ISO 9001, IATF 16949, and AS9100 audits. Concurrent qualification extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CZ Silicon Wafer Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-Inch, 6-Inch, 8-Inch, 12-Inch Form: Single Crystal, Polycrystalline, Amorphous, Wafer Thinning End User: Semiconductors, Solar Cells, Sensors, Electronics Technology: CZ Method, FZ Method, LEC Method, Float Zone |
| Companies Covered | Shin-Etsu Chemical, SUMCO Corporation, GlobalWafers, Siltronic AG, SK Siltron, Wafer Works, Topsil GlobalWafers, Okmetic Oy, Silfab Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CZ Silicon Wafer Market Trends and Innovations
Continuous crystal growth methods and AI-assisted puller control are redefining yield economics while regulatory pressure on embodied carbon reshapes furnace technology roadmaps.
Magnetic field-applied Czochralski (MCZ) technology is fragmenting the high-resistivity substrate segment for power device applications. Discrete and module manufacturers in Japan are adopting MCZ wafers for reduced oxygen content and improved breakdown voltage consistency. The technology is fragmenting procurement patterns as IDMs establish separate qualification tracks for MCZ versus standard CZ supply.
China's dual carbon policy framework and associated GB standards are mandating furnace energy disclosure and carbon intensity reduction targets. Crystal growth equipment manufacturers must retrofit pullers with regenerative thermal oxidizers and power monitoring systems. Domestic wafer suppliers serving SMIC and Hua Hong are prioritizing electrification retrofits over greenfield coal-dependent capacity.
Long-term supply agreements with foundry customers now specify defect density bands and resistivity uniformity metrics rather than commodity wafer grades. Memory and logic fabs in South Korea and Taiwan are unbundling substrate procurement from equipment purchasing decisions. This specification tightening is most visible at 300mm diameter where die-cost optimization demands tighter parametric control.
CZ Silicon Wafer Market Segmentation
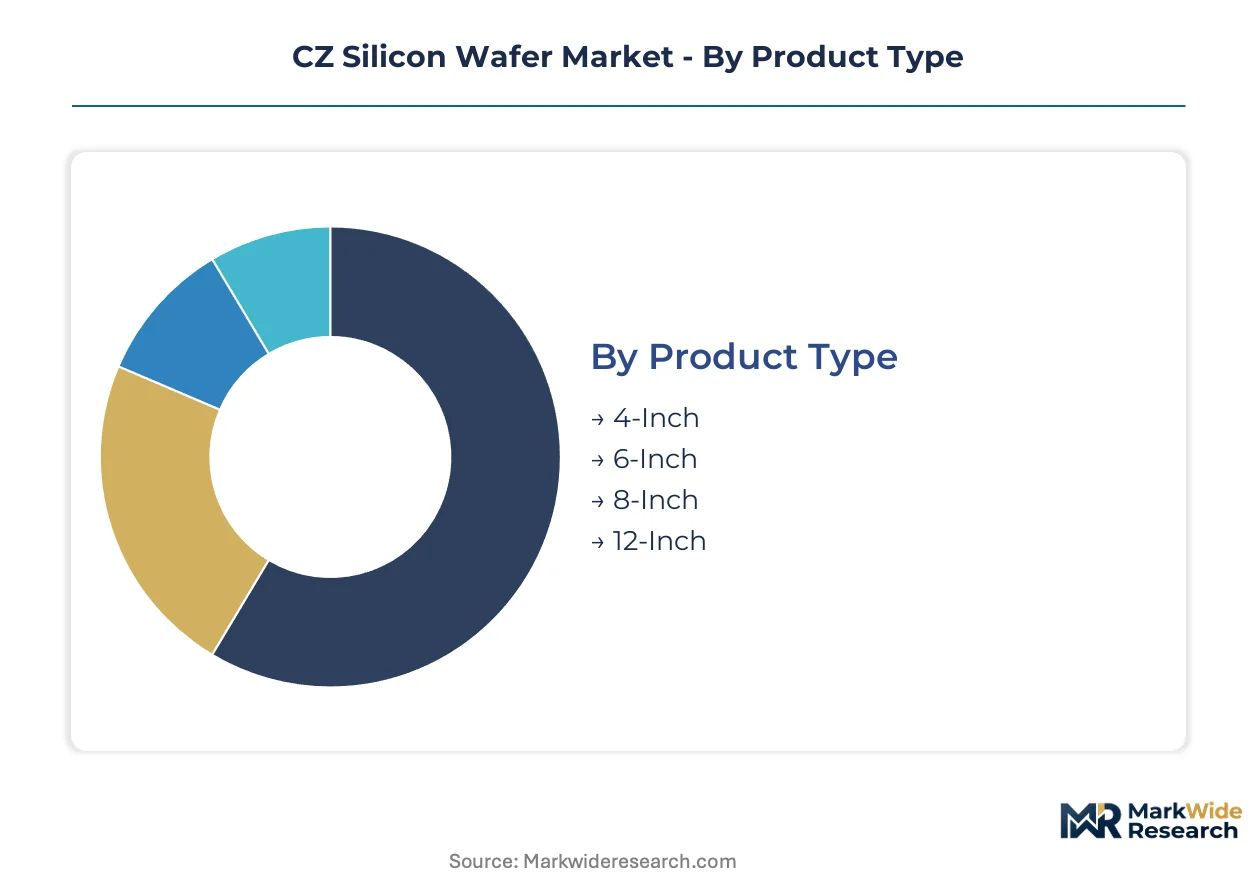
Segmentation in the CZ silicon wafer market reveals how substrate specifications align with distinct manufacturing economics and regulatory environments. Diameter formats, crystal structures, end-use applications, and growth technologies each concentrate in specific geographic clusters shaped by local fab capacity and trade policy.
Product Type:
Domestic consumption in China, South Korea, and Taiwan absorbs the majority of 300mm output, while 200mm and smaller formats serve export markets for mature node and power device production.
- 12-Inch:These 300mm substrates enable die-cost optimization at advanced logic and memory foundries. Demand concentrates in Hsinchu, Pyeongtaek, and Shanghai manufacturing clusters where SMIC, Samsung, and TSMC operate leading-edge fabs. MIIT furnace efficiency mandates are accelerating domestic Chinese supply qualification for these formats.
- 8-Inch:The 200mm diameter serves automotive MCU, power discrete, and analog foundry applications. Japanese and European IDMs source these wafers for mixed-signal and BCD process nodes. Export volumes from Taiwanese suppliers remain substantial for this segment serving Germany's automotive semiconductor demand.
- 6-Inch:Mature power device and MEMS sensor manufacturing consumes these substrates. Chinese domestic fabs and European industrial semiconductor producers represent primary offtake.
- 4-Inch:Legacy discrete component and specialized research applications sustain limited volumes. Southeast Asian back-end packaging facilities and Indian educational institutions drive residual demand.
12-Inch holds the largest share; momentum sits with 8-Inch as automotive qualification cycles accelerate.
Form:
Cost tier differentiation separates premium single-crystal substrates from commodity polycrystalline alternatives, with margin structures reflecting defect density requirements.
- Single Crystal:Czochralski-grown monocrystalline silicon provides the lattice perfection required for CMOS logic and DRAM fabrication. Taiwan and South Korean foundries specify these substrates exclusively for sub-7nm production. Oxygen precipitate engineering demands intensive crystal defect control expertise concentrated in Japanese and German equipment supply chains.
- Polycrystalline:Multi-crystalline formats serve photovoltaic cell manufacturing where efficiency trade-offs align with module economics. Chinese solar wafer producers in Jiangsu and Zhejiang provinces dominate procurement of these lower-cost substrates.
- Amorphous:Non-crystalline silicon layers deposit on foreign substrates for thin-film transistor and certain sensor applications. Display panel manufacturers in Japan and South Korea specify these for OLED backplane integration.
- Wafer Thinning:Post-growth thickness reduction processes enable 3D stacking and advanced packaging architectures. Memory fabs in South Korea deploy these techniques for HBM die preparation.
Single Crystal commands premium pricing; Polycrystalline is climbing the fastest as solar capacity expands.
End User:
Customer type fragmentation creates divergent specification regimes, with automotive and medical device buyers imposing certification burdens distinct from commodity electronics procurement.
- Semiconductors:Integrated circuit fabs consume the highest-purity substrates with tight resistivity uniformity. Logic and memory manufacturers in Taiwan, South Korea, and China specify A-grade wafers with minimal metal contamination.
- Solar Cells:Photovoltaic module assemblers prioritize cost efficiency over crystalline perfection. Chinese vertically integrated solar companies source heavily from domestic polysilicon and wafer suppliers.
- Sensors:MEMS and image sensor manufacturers require tailored dopant profiles for piezoelectric and photodetector performance. Automotive tier-1 suppliers in Germany and Japan drive qualification for AEC-Q100 compliant substrate supply.
- Electronics:Discrete component and power module producers specify medium-resistivity wafers for diode and thyristor fabrication. Industrial equipment OEMs across Europe and North America sustain steady offtake.
Semiconductors holds the largest share; Sensors is expanding most quickly with automotive electrification mandates.
Technology:
Supply concentration in crystal growth equipment manufacturing shapes technology adoption patterns, with Japanese and European vendors controlling puller and zone-refinement system supply.
- CZ Method:The Czochralski pulling process dominates commercial wafer production for its scalability to 300mm diameters. Chinese domestic equipment makers are advancing puller capabilities under MIIT localization directives.
- FZ Method:Float-zone refining produces ultra-high-resistivity silicon for power device and detector applications. German and Japanese specialty wafer suppliers retain process leadership for these premium substrates.
- LEC Method:Liquid-encapsulated Czochralski growth addresses compound semiconductor applications beyond silicon. III-V material producers in Japan and the United States deploy these systems for GaAs and InP substrate manufacturing.
- Float Zone:Containerless zone melting eliminates crucible contamination for the highest-purity requirements. Neutron detector and scientific instrument manufacturers in Europe and North America specify these wafers.
CZ Method holds the largest share; FZ Method is gaining share fastest with silicon carbide integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Tokyo-Seoul air cargo corridor underwrites East Asia's dominance in CZ silicon wafer logistics, with dedicated freighter capacity moving 300mm substrates between Hsinchu, Pyeongtaek, and Yokkaichi manufacturing clusters.
China
SMIC and Hua Hong Semiconductor are expanding 12-inch fab capacity in Shanghai and Wuxi. MIIT's GB standards mandate furnace energy efficiency disclosures and restrict obsolete crystal growth equipment imports. Yangtze River Delta crystal growth facilities are retrofitting pullers with regenerative thermal oxidizers to comply with dual carbon targets.
Japan
Automotive power module manufacturers in Nagoya are qualifying MCZ wafers for traction inverter applications under AEC-Q100 standards. METI enforces JIS standards for semiconductor material traceability across substrate supply chains. Shin-Etsu Chemical's captive polysilicon supply in Gunma Prefecture insulates its CZ divisions from feedstock volatility.
South Korea
Samsung and SK Hynix are unbundling substrate procurement from equipment purchasing decisions for advanced memory production. MFDS coordinates with industry on export control classifications for advanced substrate technologies. Pyeongtaek's semiconductor cluster demands tighter resistivity uniformity metrics than commodity wafer grades.
Taiwan
TSMC's sub-7nm production at Hsinchu Science Park specifies single-crystal substrates exclusively. The island's dedicated 300mm epitaxial wafer capacity serves logic and memory foundries with minimal defect density requirements. Kaohsiung port infrastructure handles inbound polysilicon and outbound processed wafers for European automotive customers.
Germany
Automotive tier-1 suppliers in Munich and Stuttgart are driving AEC-Q100 compliant substrate qualification for silicon carbide power modules. REACH compliance constrains arsenic and antimony surface treatments, forcing Asian suppliers to reformulate chemistries. Siltronic AG's specialty wafer production in Burghausen retains process leadership for ultra-high-resistivity float-zone applications.
CZ Silicon Wafer Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology access. The market structure concentrates around integrated chemical conglomerates with captive polysilicon supply, independent wafer specialists with dedicated epitaxial capacity, and regional fabricators serving mature node demand. Three archetypes dominate: vertically integrated chemical majors, pure-play wafer manufacturers, and equipment-integrated regional suppliers. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with furnace electrification retrofits and long-term foundry agreements reshaping positioning.
Among Japanese chemical conglomerates, Shin-Etsu Chemical exemplifies the integrated archetype through its captive raw material control, while SUMCO Corporation occupies a position emphasizing dedicated 300mm epitaxial capacity. GlobalWafers represents the geographic diversification strategy, with manufacturing footprints across multiple continents reducing logistics exposure.
| Leading Market Players |
|---|
| Shin-Etsu Chemical |
| SUMCO Corporation |
| GlobalWafers |
| Siltronic AG |
| SK Siltron |
| Wafer Works |
| Topsil GlobalWafers |
| Okmetic Oy |
| Silfab Solar |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 certification gates both supply qualification and price differentiation simultaneously, as automotive and aerospace buyers mandate audited quality systems before contract eligibility while paying premiums for IATF 16949 and AS9100 tiered grades above baseline substrates.
Pricing Analysis
Volume-discount tiering structures separate long-term foundry offtake agreements from spot market transactions. Three-tier pricing stratifies across A-grade epitaxial wafers, standard prime substrates, and reclaim-grade materials. Pricing pressure stems from polysilicon feedstock volatility concentrated in Chinese metallurgical-grade refining. Memory fabs in South Korea exhibit lowest price sensitivity due to die-cost optimization priorities, while solar cell assemblers in Jiangsu province drive hardest bargain negotiations.
Supply Chain Analysis
Kaohsiung-Yokkaichi container availability shapes inbound logistics costs for polysilicon feedstock moving into Taiwanese crystal growth facilities. Supply concentrates in Japan, South Korea, and Taiwan for 300mm single-crystal output, with China expanding domestic puller capacity under MIIT localization directives. Raw material dependencies span metallurgical-grade silicon, high-purity graphite crucibles, and argon purge gas. Single-source vulnerability runs through Japanese equipment vendors controlling MCZ magnetic field systems. Distribution runs through dedicated freighter capacity on the East Asia air cargo corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in automotive power module substrates where AEC-Q100 qualification requirements create defensible niches against commodity wafer competition.
For Market Incumbents: Fortify captive polysilicon positions through backward integration into metallurgical-grade silicon refining or long-term offtake agreements with Yangtze River Delta suppliers. Expand MCZ capacity in Japan and South Korea before Chinese equipment makers close the magnetic field technology gap. Defend against epitaxial deposition substitution by embedding defect density guarantees into long-term memory fab contracts. For New Entrants and Emerging Players: Custom resistivity profiling for silicon photonics foundries represents an underserved service layer where incumbent qualification cycles lag telecom datacenter buildout timelines. Target India's PLI-backed display and logic fabs with technology partnerships bridging domestic crystal growth capability gaps. Pursue furnace electrification retrofit services for Chinese suppliers facing MIIT carbon intensity deadlines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 300mm epitaxial capacity expansions as South Korean and Taiwanese foundries unbundle substrate procurement from equipment purchasing. Long-term viability favors specialists with demonstrated oxygen precipitate engineering expertise and existing automotive certification portfolios. Watch for MIIT enforcement actions on obsolete puller imports as signal for domestic Chinese supply displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Retrofit | MIIT dual carbon compliance separates qualified Chinese suppliers from obsolete capacity. |
| MCZ Magnetic Field Technology Licensing | Japanese equipment vendors monetize high-resistivity substrate process leadership. |
| Long-term Foundry Supply Agreement | TSMC and Samsung unbundling creates specification-tightened contract opportunities. |
| Automotive Certification Investment | AEC-Q100 qualification opens traction inverter substrate demand from German and Japanese tier-1 suppliers. |
| India Technology Partnership | PLI scheme allocations for display and logic fabs invite 200mm and 300mm substrate supply alliances. |
Research Methodology
Cross-validation between primary fieldwork and secondary trade data anchors the qualitative findings. Semiconductor fab procurement directors, crystal growth equipment engineers, and polysilicon supply planners provided operational perspectives. Secondary sources include customs manifests for silicon wafer trade flows, SEC filings from listed wafer manufacturers, MIIT equipment import records, and JIS standard certification databases. Bottom-up capacity tallies triangulate against top-down demand estimates from foundry capex disclosures.
Sensitivity analysis tested forecast outputs against polysilicon price volatility bands and furnace energy cost scenarios across the projection horizon. Segmentation dimensions span diameter format, crystal structure, end-use application, and growth technology. CAGRs derive from installed fab capacity expansion schedules and die-cost optimization trends at advanced nodes. Industry-specific inputs include AEC-Q100 qualification timelines and MCZ adoption rates in power device manufacturing.
Underlying assumptions cover sustained East Asian foundry capacity expansion, stable multilateral export control alignments, and REACH compliance continuity, with deviation risk concentrated in geopolitical trade measures affecting polysilicon feedstock flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Rad-Hard Mosfets Market