
 Clamp-On Ultrasonic Gas Flow Meter Market | 2026-2036
Clamp-On Ultrasonic Gas Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Clamp-On Ultrasonic Gas Flow Meter Market Insights
The capital-intensity divergence between integrated sensor manufacturers and assembly-focused vendors is unwinding competitive stability across the sector. KROHNE Group leverages in-house transducer fabrication to sustain margin control across European utility contracts. Emerson anchors its position through North American channel density in oil and gas infrastructure. Siemens competes via embedded diagnostics software that extends hardware lifecycle value for industrial buyers.
A clamp-on ultrasonic gas flow meter measures natural gas velocity by transmitting acoustic pulses through pipe walls without mechanical intrusion, typically operating at frequencies between 0.5 and 2 MHz and achieving accuracies within one percent of reading. Transit-time technology dominates custody-transfer applications where precision requirements are most stringent, while Doppler variants occupy niche markets handling entrained particulate or wet gas streams. Fixed installations generate the steadiest revenue base across utility networks, though wireless configurations are gaining traction in remote monitoring scenarios where cabling costs prove prohibitive.
The EPA mandates periodic methane leak surveys under updated greenhouse gas reporting rules, directly stimulating replacement demand for legacy orifice meters with clamp-on alternatives. In Europe, MID certification and the F-Gas Regulation shape product development priorities for manufacturers seeking cross-border market access. Stakeholders must weigh calibration protocol standardization against the interoperability demands of digital twin integration in forthcoming infrastructure planning.
Market Dynamics
The transition from intrusive to non-intrusive metering architectures is restructuring capital deployment across natural gas infrastructure, as operators prioritize installation continuity over legacy mechanical precision.
Growth Catalysts
- EPA Methane Regulations:Mandatory greenhouse gas reporting rules in the United States compel pipeline operators to replace orifice meters with clamp-on alternatives that enable continuous leak detection without flow interruption.
- Industrial Cluster Demand:Germany's chemical processing corridors in Ludwigshafen and Leverkusen specify transit-time ultrasonic meters for custody-transfer accuracy in high-volume petrochemical streams.
- Transit-Time Technology Maturation:Signal processing advances at 0.5–2 MHz frequencies now deliver sub-one-percent measurement uncertainty, satisfying custody-transfer standards previously reserved for differential-pressure systems.
Market Restraints
- Transducer Supply Concentration:Piezoelectric crystal fabrication for high-temperature operation concentrates among specialized Japanese and German component suppliers, creating single-source vulnerability.
- Calibration Infrastructure Gaps:MID certification requirements under EU Directive 2014/32/EU demand traceable gas flow facilities that remain scarce outside metropolitan testing centers.
- Orifice Meter Installed Base:Decades of differential-pressure infrastructure investment across North American transmission networks slows displacement timelines despite regulatory pressure.
Strategic Opportunities
- Wireless Configuration Expansion:Battery-powered clamp-on units with LoRaWAN connectivity address remote monitoring scenarios in Norwegian offshore platforms and Australian coal seam gas fields where cabling costs exceed hardware expenditure.
- Hydrogen Blending Applications:Emerging hydrogen-natural gas mixtures require requalified flow measurement, creating retrofit demand as Netherlands and UK grid operators pilot 20% hydrogen injection.
- Digital Twin Integration:Real-time flow data streams into asset simulation models, positioning meter vendors as data service providers rather than hardware suppliers.
Industry Challenges
- Acoustic Coupling Expertise Shortage:Proper transducer mounting on irregular pipe surfaces demands trained technicians, constraining deployment velocity in markets lacking specialized service networks.
- Multi-Vendor Protocol Harmonization:Proprietary diagnostics formats from Siemens, Emerson, and KROHNE impede unified fleet management for operators seeking centralized monitoring dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clamp-On Ultrasonic Gas Flow Meter Market |
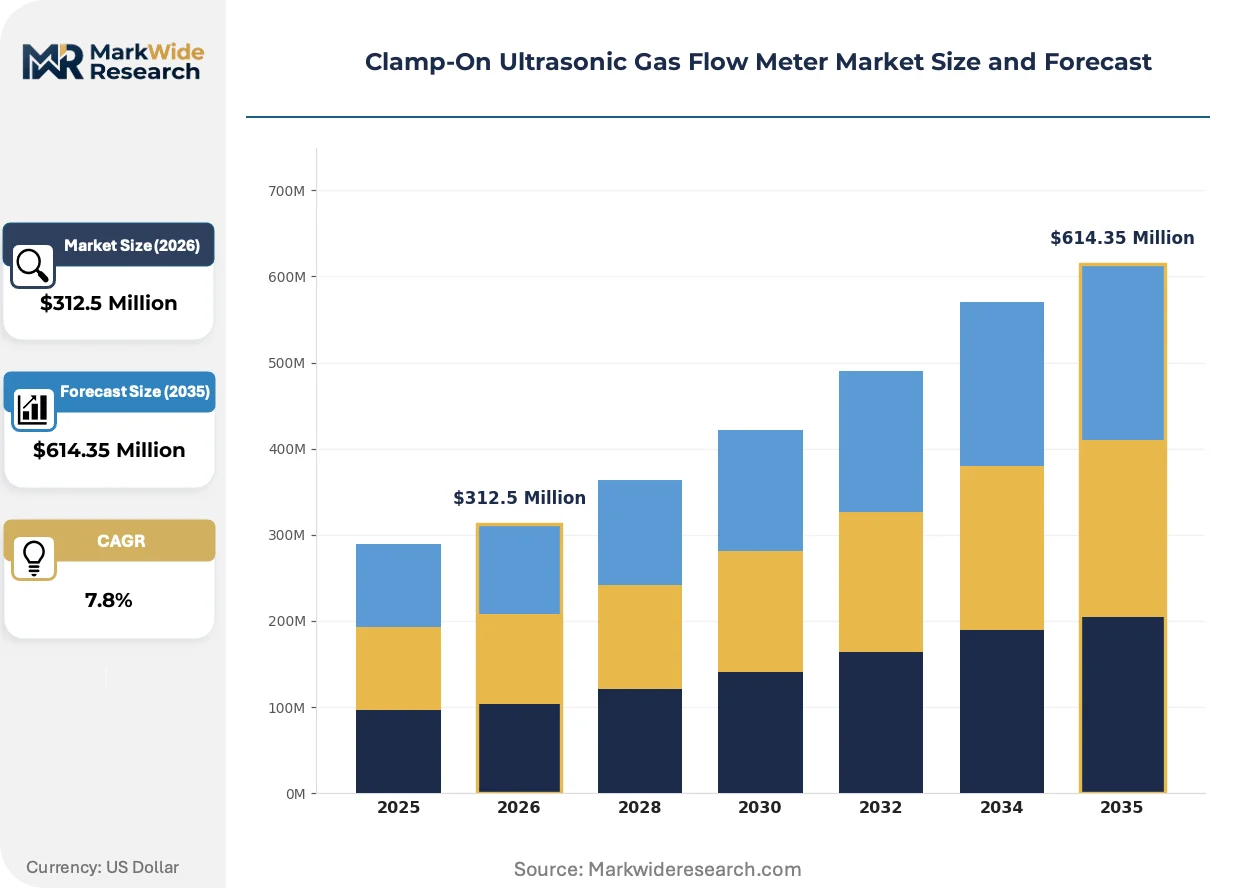
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Wireless, Clamp-On End User: Utilities, Oil & Gas, Chemical Plants, HVAC Application: Flow Measurement, Leak Detection, Process Control, Energy Management Technology: Pulsed Ultrasonic, Continuous Wave, Transit-Time, Doppler |
| Companies Covered | KROHNE Group, Endress+Hauser, Emerson, Siemens, Yokogawa Electric, Honeywell, Fuji Electric, Baker Hughes, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clamp-On Ultrasonic Gas Flow Meter Market Trends and Innovations
Broadband acoustic signal processing and embedded edge computing are converging to redefine how flow data is captured, validated, and monetized across gas transmission networks.
Multi-path transit-time configurations with eight or more acoustic chords are displacing dual-path designs in custody-transfer applications. North American midstream operators now specify these architectures for pipeline interconnects exceeding 36-inch diameter, where velocity profile asymmetry demands spatially distributed measurement. The displacement is compressing price premiums between standard and high-accuracy product tiers.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is redirecting R&D investment toward meter housings and gaskets compatible with alternative thermal management fluids. European manufacturers must recertify enclosure integrity ratings under updated ECHA substance restrictions, accelerating material substitution in sealing systems. Industrial buyers in Germany and the Netherlands now require full material disclosure documentation as a procurement gate.
Service unbundling is fragmenting traditional hardware-plus-maintenance contracts. North American utilities now procure calibration and diagnostics separately from initial meter supply, pressuring vendors to modularize software subscriptions. This shift is most pronounced in Texas and Louisiana, where independent metrology laboratories compete directly with manufacturer service arms for recurring revenue streams.
Clamp-On Ultrasonic Gas Flow Meter Market Segmentation
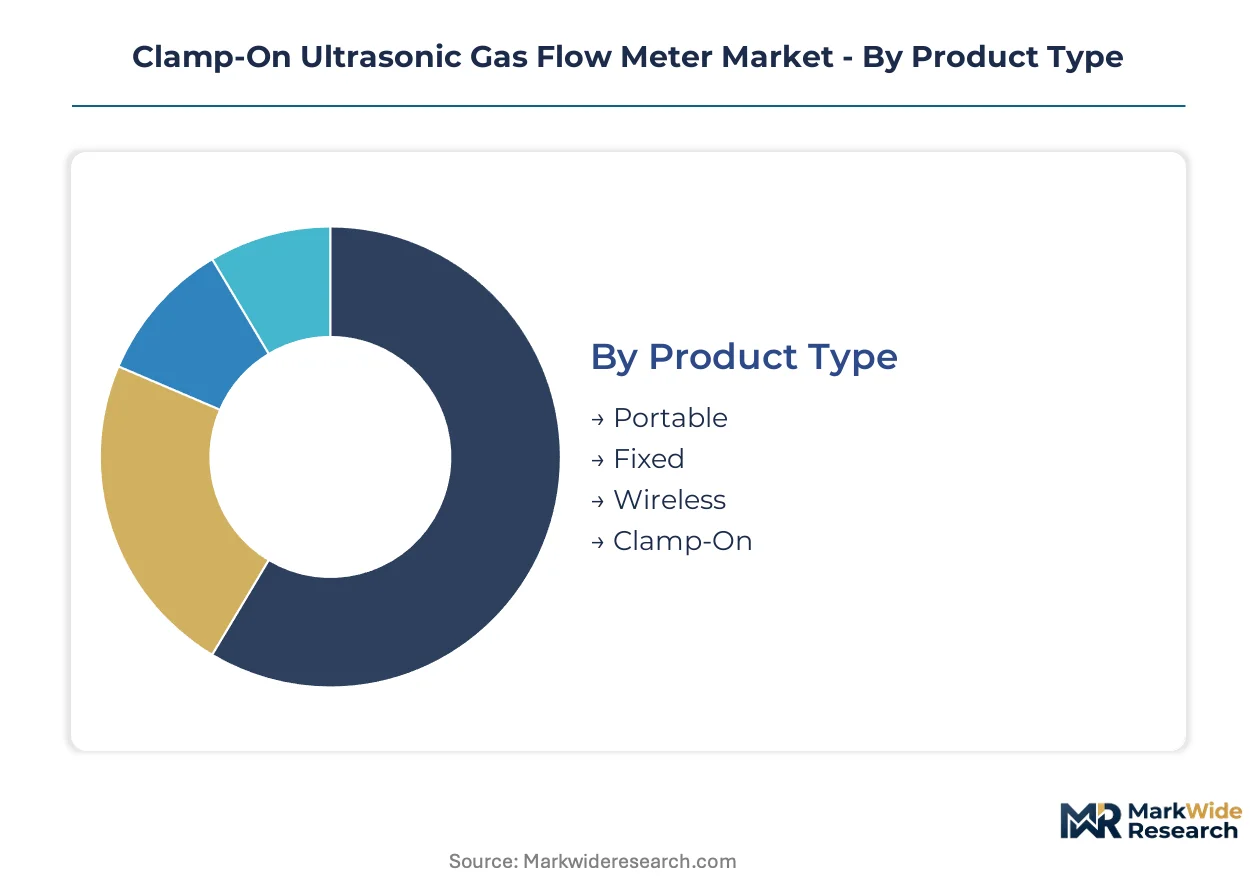
Segmentation in the clamp-on ultrasonic gas flow meter market reflects divergent certification requirements and installation constraints across custody-transfer, environmental compliance, and process control applications. Product architecture, end-user infrastructure maturity, and measurement technology specifications each create distinct procurement criteria and margin profiles.
Product Type:
EPA methane reporting mandates and EU MID certification create divergent hardware requirements between permanent utility installations and temporary compliance verification tools.
- Fixed:Permanently mounted installations dominate natural gas utility networks, with stainless steel enclosures and IP66 ratings satisfying F-Gas Regulation durability standards for German chemical corridors. Revenue concentrates in 36-inch pipeline interconnects where multi-path transit-time configurations deliver custody-transfer precision without flow interruption.
- Wireless:Battery-powered units with LoRaWAN connectivity address Norwegian offshore platforms and Australian coal seam gas fields where cabling infrastructure costs exceed hardware expenditure by factors of three to five. The segment climbs fastest on share as remote monitoring demand outpaces wired alternatives in greenfield developments.
- Portable:Handheld diagnostic tools support EPA-mandated periodic leak surveys across US transmission networks, enabling spot-check verification without permanent installation.
- Clamp-On:The foundational non-intrusive architecture underpins all product variants, with transducer mounting kits standardized for carbon steel and ductile iron pipe specifications.
Fixed installations handle the majority of throughput; wireless configurations are expanding most quickly on share.
End User:
Capital deployment cycles and regulatory exposure determine procurement sophistication across customer categories.
- Utilities:Natural gas distribution operators in the United States and Germany drive replacement demand as EPA greenhouse gas rules and EU methane strategy deadlines force orifice meter retirement. These buyers prioritize MID-certified transit-time systems with embedded diagnostics for predictive maintenance.
- Oil & Gas:Midstream pipeline operators specify multi-path configurations for custody-transfer accuracy at interconnection points exceeding 24-inch diameter. North American shale producers favor wireless clamp-on units for wellhead flow monitoring in pad-drilling configurations.
- Chemical Plants:Ludwigshafen and Leverkusen industrial clusters demand sub-one-percent measurement uncertainty for high-volume petrochemical feedstock accounting.
- HVAC:Commercial building energy management systems adopt lower-cost single-path units for natural gas consumption tracking and carbon reporting compliance.
Utilities generate the steadiest revenue base; oil and gas applications show the steepest expansion trajectory as midstream infrastructure investment accelerates.
Application:
Functional requirements span precision measurement, safety compliance, and operational optimization with distinct technical specifications.
- Flow Measurement:Custody-transfer applications demand eight-path transit-time architectures with temperature-compensated signal processing, satisfying OIML R137 accuracy classes for German and Dutch grid operators. These installations carry the highest hardware margins due to calibration traceability requirements.
- Leak Detection:Continuous monitoring configurations support EPA-mandated methane emissions surveys, with acoustic signature analysis identifying pipeline anomalies before atmospheric release. Demand concentrates in Texas and Louisiana production basins under intensifying regulatory scrutiny.
- Process Control:Petrochemical reactors integrate clamp-on meters for real-time feedstock ratio management, leveraging 0.5–2 MHz frequency ranges for entrained gas handling.
- Energy Management:Building automation systems utilize simplified transit-time units for natural gas consumption allocation across tenant billing and sustainability reporting.
Flow measurement commands premium pricing; leak detection is gaining share fastest as methane regulations tighten across North America and Europe.
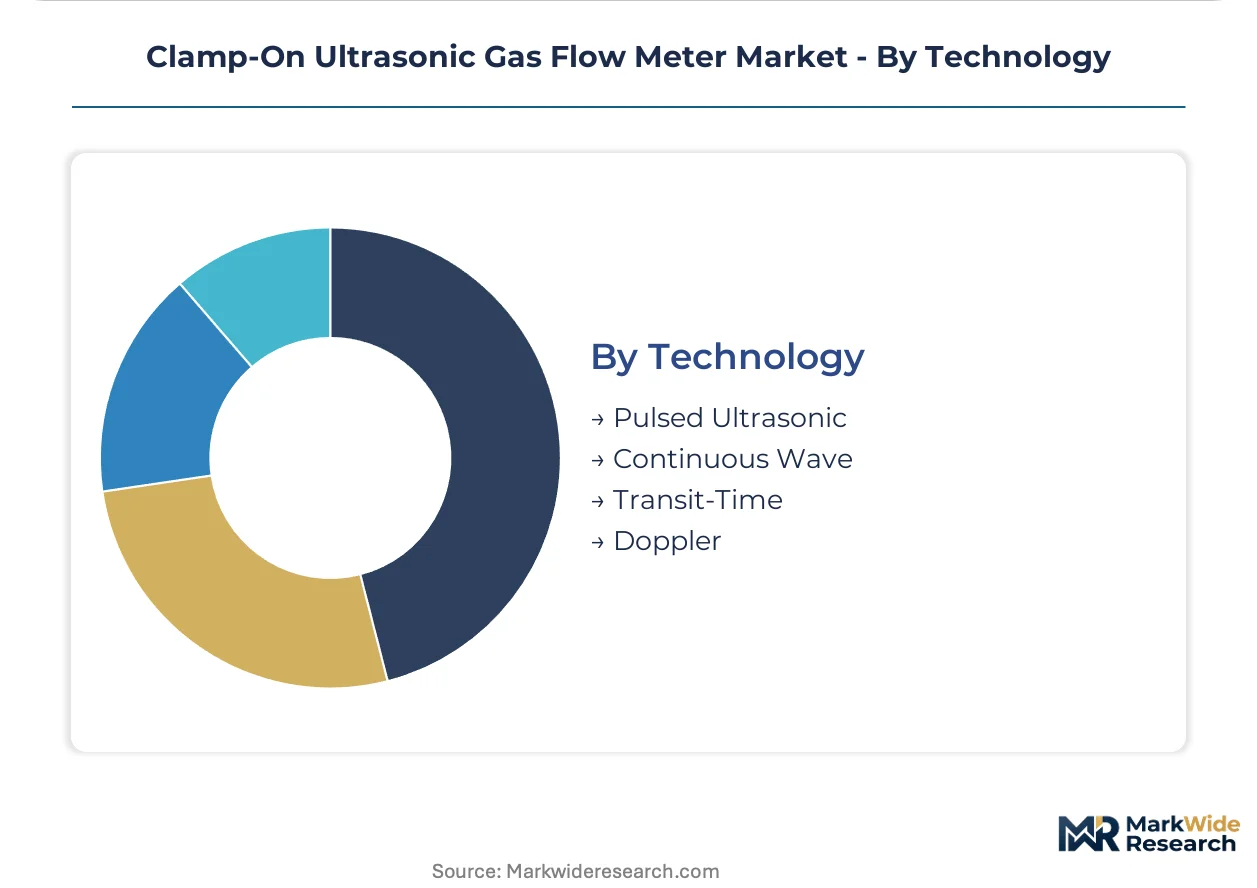
Technology:
Signal processing methodology determines accuracy ceilings, fluid compatibility, and calibration complexity.
- Transit-Time:Pulsed acoustic measurement at 0.5–2 MHz frequencies delivers sub-one-percent uncertainty for clean natural gas streams, dominating custody-transfer applications where OIML and MID certifications are mandatory. German and Netherlands grid operators specify this technology exclusively for hydrogen blending pilot programs.
- Doppler:Frequency-shift detection handles wet gas and entrained particulate streams in unconventional production scenarios, occupying niche positions where transit-time signal attenuation proves prohibitive.
- Pulsed Ultrasonic:Burst-mode transmission reduces power consumption for battery-powered wireless configurations, extending field deployment intervals to five-plus years.
- Continuous Wave:Sustained acoustic emission supports high-sampling-rate process control loops in chemical reactor feed management.
Transit-time technology anchors commercial volume; pulsed ultrasonic variants are climbing fastest on share as wireless deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for precision flow instrumentation tilt toward surplus positions in Germany and the United States, while Asian manufacturing centers absorb component shipments to serve regional energy infrastructure buildouts. Trade flows concentrate around high-accuracy transit-time systems for custody-transfer applications.
United States
EPA methane regulations under Subpart W of the Greenhouse Gas Reporting Program compel pipeline operators to retire orifice meters across Texas and Louisiana production basins. The FERC oversees interstate transmission standards that increasingly reference clamp-on alternatives for continuous monitoring. Houston anchors procurement activity for midstream infrastructure serving Permian and Appalachian shale developments.
Germany
Ludwigshafen and Leverkusen chemical corridors specify MID-certified transit-time meters for petrochemical feedstock accounting with sub-one-percent uncertainty requirements. The F-Gas Regulation mandates enclosure integrity recertification for thermal management compatibility. Industrial clusters in North Rhine-Westphalia drive standard-setting for hydrogen blending measurement protocols.
Netherlands
Grid operators pilot 20% hydrogen-natural gas mixtures requiring requalified flow measurement at Rotterdam and Eindhoven interconnection points. The ECHA substance restrictions accelerate material disclosure requirements for sealing systems. Port of Rotterdam throughput volumes create concentrated demand for custody-transfer accuracy in high-volume import terminals.
Norway
Offshore platform operators in the North Sea deploy wireless clamp-on configurations with LoRaWAN connectivity to eliminate subsea cabling expenditure. The country's petroleum regulator mandates continuous leak detection for aging infrastructure. Stavanger and Bergen service hubs specialize in acoustic coupling expertise for irregular pipe geometries.
Australia
Coal seam gas fields in Queensland and Western Australia favor battery-powered units for wellhead flow monitoring where grid connectivity remains uneconomical. The country's resources regulator aligns with ISO 17025 calibration traceability for export LNG custody transfer. Perth engineering consultancies build specialized service networks for remote deployment support.
Clamp-On Ultrasonic Gas Flow Meter Market Competitive Landscape
Concentration sits with integrated sensor manufacturers controlling piezoelectric transducer fabrication, while assembly-focused vendors compete on channel density and service reach. The vendor base stratifies across three tiers: captive component producers, full-system integrators with embedded software capabilities, and regional packagers sourcing standardized modules. Competitive moves center on backward integration into crystal manufacturing and geographic expansion through metrology laboratory partnerships.
Among European-integrated fabricators, KROHNE Group and SICK AG exemplify the captive-transducer archetype sustaining margin control through in-house piezoelectric production. Siemens occupies a position representing the diagnostics-software tier, extending hardware lifecycle value through predictive maintenance platforms. Emerson anchors North American channel density in oil and gas infrastructure, sitting within the full-system integrator category with established utility relationships.
| Leading Market Players |
|---|
| KROHNE Group |
| Endress+Hauser |
| Emerson |
| Siemens |
| Yokogawa Electric |
| Honeywell |
| Fuji Electric |
| Baker Hughes |
| SICK AG |
| Others |
Pricing and Supply Chain Analysis
MID certification under EU Directive 2014/32/EU gates both supplier qualification and price stratification across the clamp-on ultrasonic gas flow meter sector, compelling manufacturers to absorb traceable calibration facility costs while passing OIML R137 tier premiums to German and Dutch utility buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on OIML R137 accuracy class and embedded diagnostics capability, with custody-transfer certified multi-path units commanding substantial premiums over single-path HVAC configurations. Cost compression in the standard tier intensifies as regional packagers source standardized transducer modules from Japanese component specialists. Chemical plant procurement teams in Ludwigshafen exhibit the lowest price sensitivity due to feedstock accounting precision requirements, while commercial building energy managers drive aggressive economy-tier negotiation.
Supply Chain Analysis
Extended lead times for high-temperature piezoelectric crystals now stretch sixteen to twenty weeks, constraining throughput for European system integrators. Component fabrication concentrates in Japan and Germany, with final assembly distributed across China, the United States, and the Netherlands. Raw material dependencies center on lead zirconate titanate crystals, specialized epoxy potting compounds, and fluorocarbon gasket materials facing ECHA substance restriction phaseouts. Single-source vulnerability in Japanese crystal suppliers exposes the sector to geographic concentration risk. Distribution runs through authorized metrology laboratories and direct utility channel partnerships, with aftermarket service unbundling fragmenting traditional hardware-plus-maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clamp-on ultrasonic gas flow meter sector is navigating a cyclical recovery driven by EPA methane regulation enforcement timelines compelling orifice meter replacement across North American transmission networks.
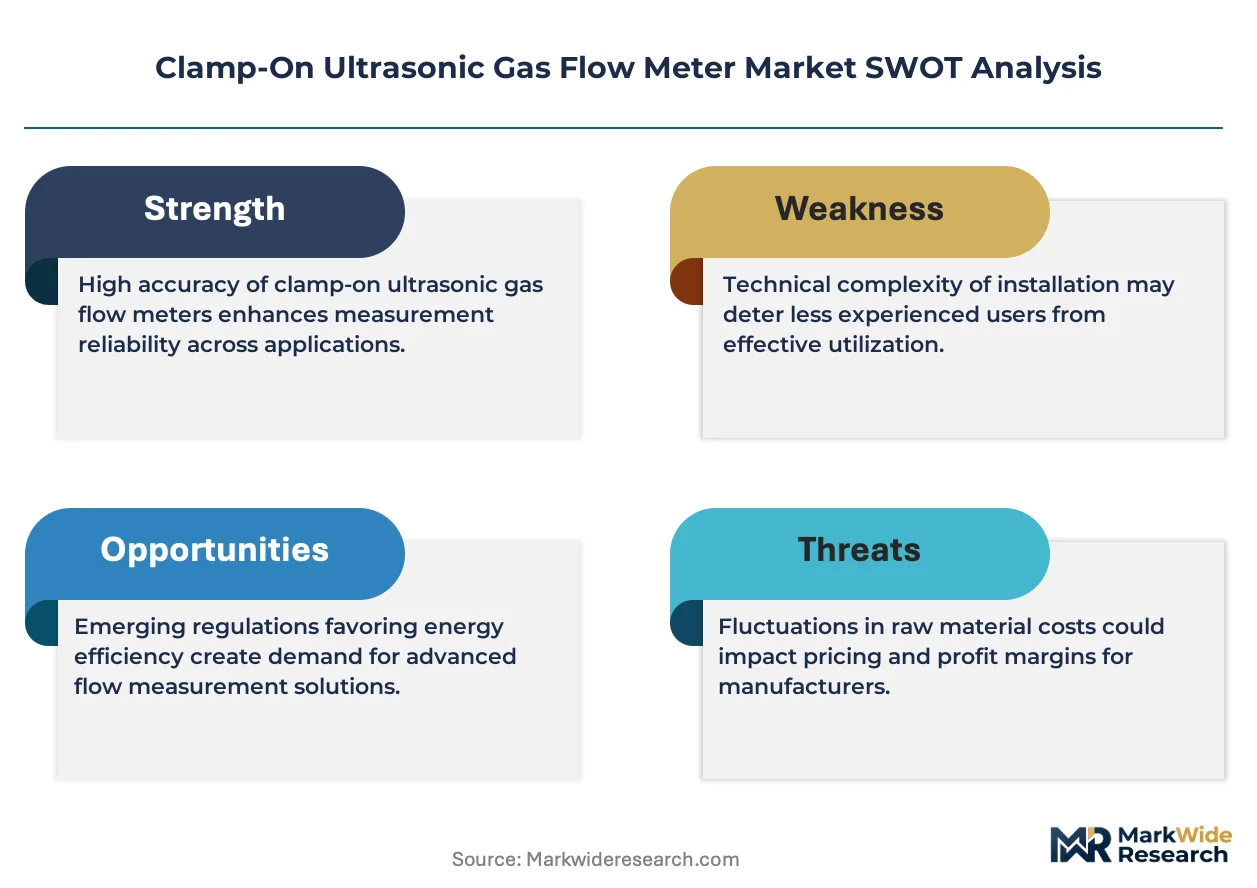
For Market Incumbents: Consolidate backward integration into piezoelectric crystal manufacturing to reduce Japanese supplier dependency and defend margin structure against emerging Asian module assemblers. Deepen captive transducer production capacity in Germany to satisfy MID certification traceability requirements for Dutch hydrogen blending pilots. Lock in long-term calibration facility partnerships across Texas and Louisiana to preempt independent metrology laboratories from capturing recurring service revenue streams.
For New Entrants and Emerging Players: Anchor in wireless configuration development for Australian coal seam gas and Norwegian offshore applications where cabling infrastructure costs create immediate total-cost-of-ownership advantages. Target battery-powered LoRaWAN units as the most penetrable segment, exploiting incumbent reluctance to cannibalize fixed-installation revenue bases. Pursue direct engagement with Perth and Stavanger engineering consultancies lacking established manufacturer service relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates treating flow instrumentation as non-core, particularly European automation divisions lacking embedded diagnostics software capabilities. Long-term viability hinges on digital twin integration positioning meter vendors as data service providers rather than hardware suppliers. Monitor F-Gas Regulation recertification cost burdens as an inflection signal for distressed asset availability among smaller European manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Manufacturing | Captive piezoelectric production reduces Japanese supplier dependency for German fabricators. |
| Wireless Configuration Expansion | Battery-powered LoRaWAN units address Norwegian offshore cabling cost barriers. |
| Digital Twin Platform Development | Real-time flow data integration positions vendors as predictive maintenance service providers. |
| Hydrogen Blending Certification Investment | Requalified measurement protocols capture Netherlands and UK grid operator retrofit demand. |
| Metrology Laboratory Partnership | Calibration facility alliances preempt independent competitors in Texas and Louisiana. |
Research Methodology
The analysis maps transit-time, Doppler, pulsed ultrasonic, and continuous wave technology sub-sectors, each validated through utility planning officers, oil and gas midstream procurement leads, chemical plant instrumentation engineers, and metrology laboratory directors. Primary fieldwork combined structured interviews with secondary validation against EPA Greenhouse Gas Reporting Program filings, FERC interstate transmission standards, EU MID certification registries, and OIML R137 test reports. Bottom-up segment sizing triangulated against top-down infrastructure investment tracking across German chemical corridors and North American shale basins.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled technology type, product architecture, end-user vertical, and application function dimensions. CAGRs were derived from regression analysis of replacement cycle timing, regulatory enforcement phase-ins, and hydrogen blending pilot expansion trajectories. Industry-specific forecast inputs incorporated EPA methane survey mandate compliance schedules and ECHA F-Gas Regulation substance restriction timelines.
Material uncertainties — regulatory delay, hydrogen blend rate policy revision, and transducer supply disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification standardization and digital twin adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
MEMS Market