
 Temperature Controller Market | 2026-2036
Temperature Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Controller Market Intelligence
The European Union's Green Deal, with its focus on industrial energy efficiency, is pivoting customer procurement toward controllers that minimize energy waste. Honeywell International leverages its extensive portfolio in building automation and industrial process control to meet these new standards. Schneider Electric differentiates through its EcoStruxure platform, integrating energy management with process automation. Omron Corporation specializes in high-speed, high-precision controllers for factory automation applications in Japan and across Asia.
A temperature controller is an instrument used to regulate thermal conditions by comparing a sensor's reading to a desired setpoint. The device utilizes control algorithms, such as PID logic, to calculate corrective outputs for heating or cooling elements. PID controllers represent a mature but dominant product segment due to their versatility and precision. Demand from semiconductor manufacturing requires the highest accuracy, while the food and beverage production industry prioritizes controllers that meet stringent hygiene and safety certifications.
Market access is governed by a patchwork of regional certifications and standards. Compliance with Europe's CE marking and UL standards for North America is essential for component safety and electromagnetic compatibility. In parallel, China's GB standards impose specific requirements for products sold within its domestic market. Vendors must therefore decide whether to pursue a global product design or develop region-specific models to optimize cost and compliance.
Market Dynamics
The market's central tension is the need for sub-degree precision in sectors like semiconductor manufacturing against a fragmented and costly global regulatory landscape, forcing design and compliance trade-offs for vendors pursuing a global footprint.
Growth Catalysts
- Semiconductor Manufacturing:Demand for extreme temperature stability in photolithography and etching processes in Taiwan and South Korea requires controllers with sub-second response times and high-resolution inputs.
- EU F-Gas Regulation:Mandates for lower Global Warming Potential refrigerants in HVAC systems necessitate more advanced controllers to manage different thermodynamic properties and maintain energy efficiency.
- Food Safety Modernization:China's stringent food processing standards, aligned with its GB standards, drive investment in certified controllers that provide verifiable temperature logging for cold chain integrity.
Market Restraints
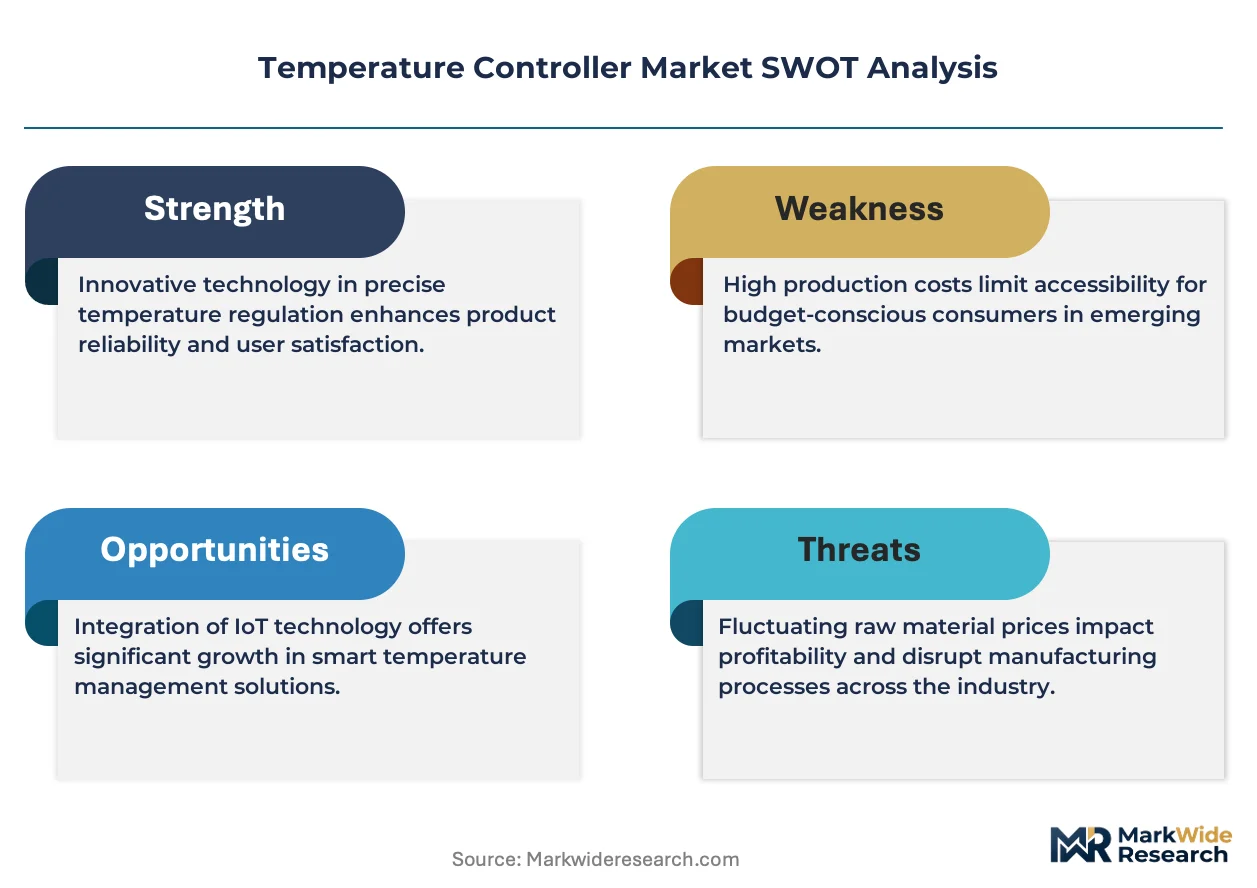
- Component Cost Volatility:The price of high-precision thermistors and platinum resistance thermometers, critical inputs for accurate sensing, is subject to fluctuations in raw material markets and supply chain disruptions.
- Fragmented Certification Paths:Vendors face significant costs and delays in securing separate CE marking for Europe, UL listing for North America, and GB certification for China on a single product line.
- Legacy System Integration:Integrating modern digital controllers with older analog industrial machinery often requires custom interfaces and middleware, adding complexity and cost for asset-heavy industries.
Strategic Opportunities
- Electric Vehicle Battery Production:The precise thermal management required during battery cell formation and pack conditioning creates a new, high-volume application for multi-channel temperature controllers.
- AI-Enabled Predictive Control:Embedding machine learning algorithms into PID logic allows controllers to self-tune and predict thermal deviations, opening service revenue streams for process optimization.
- Energy Storage Systems:Grid-scale battery installations require sophisticated thermal regulation to maximize lifespan and prevent thermal runaway, creating demand for controllers integrated with battery management systems.
Industry Challenges
- Control Algorithm Expertise:A shortage of engineers skilled in tuning complex PID loops for non-linear processes, such as in biopharmaceutical reactors, limits the full performance potential of advanced controllers.
- Cybersecurity for Connected Devices:As controllers become network-connected for remote monitoring, ensuring they are hardened against cyber threats without compromising real-time performance is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Controller Market |
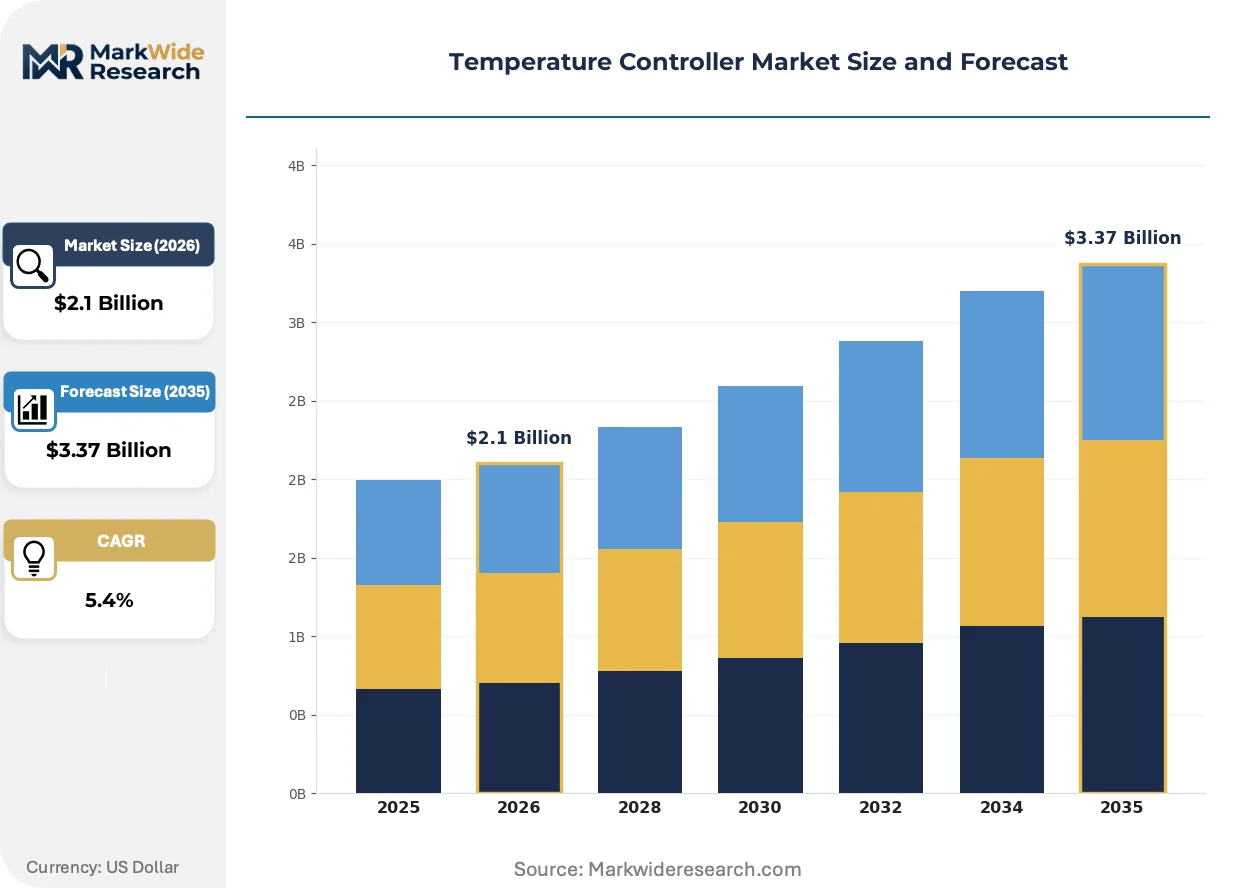
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
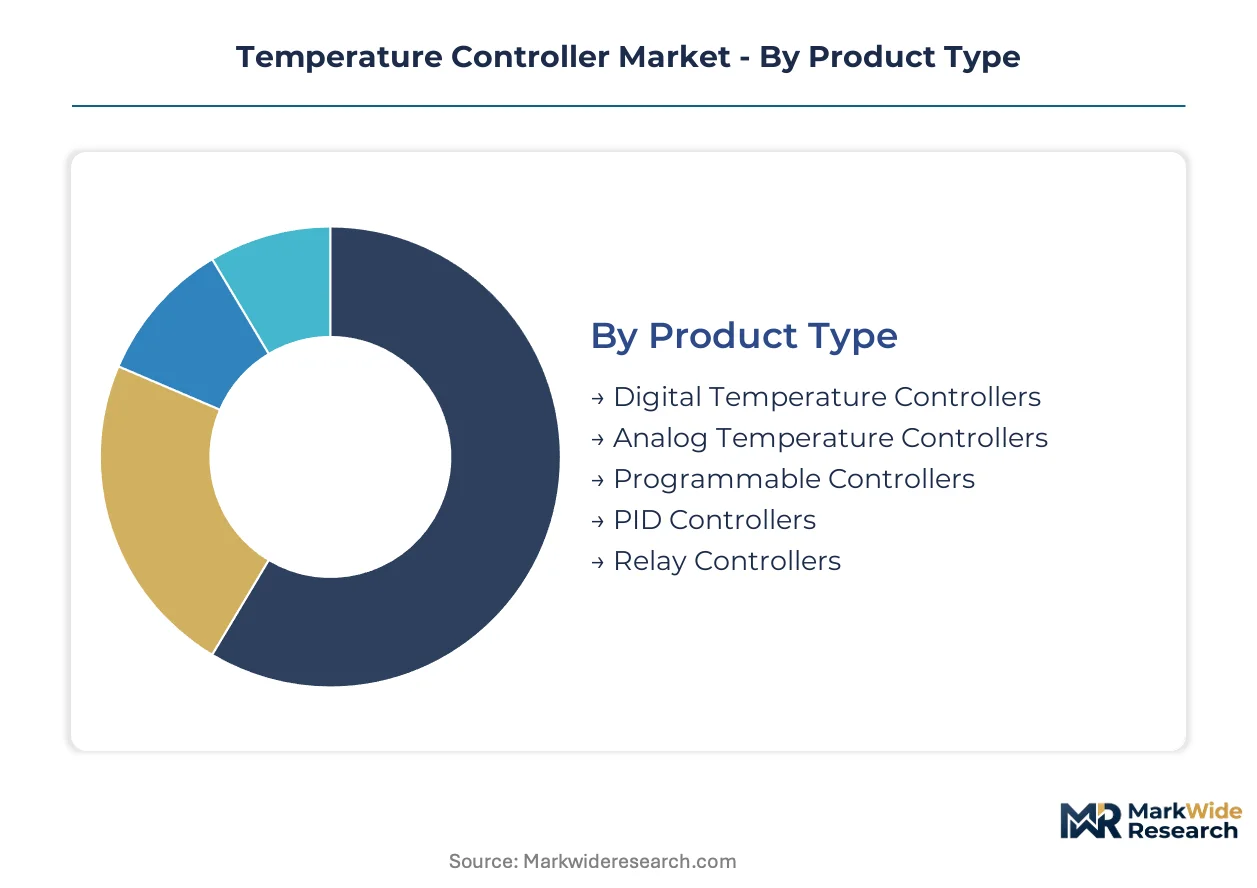
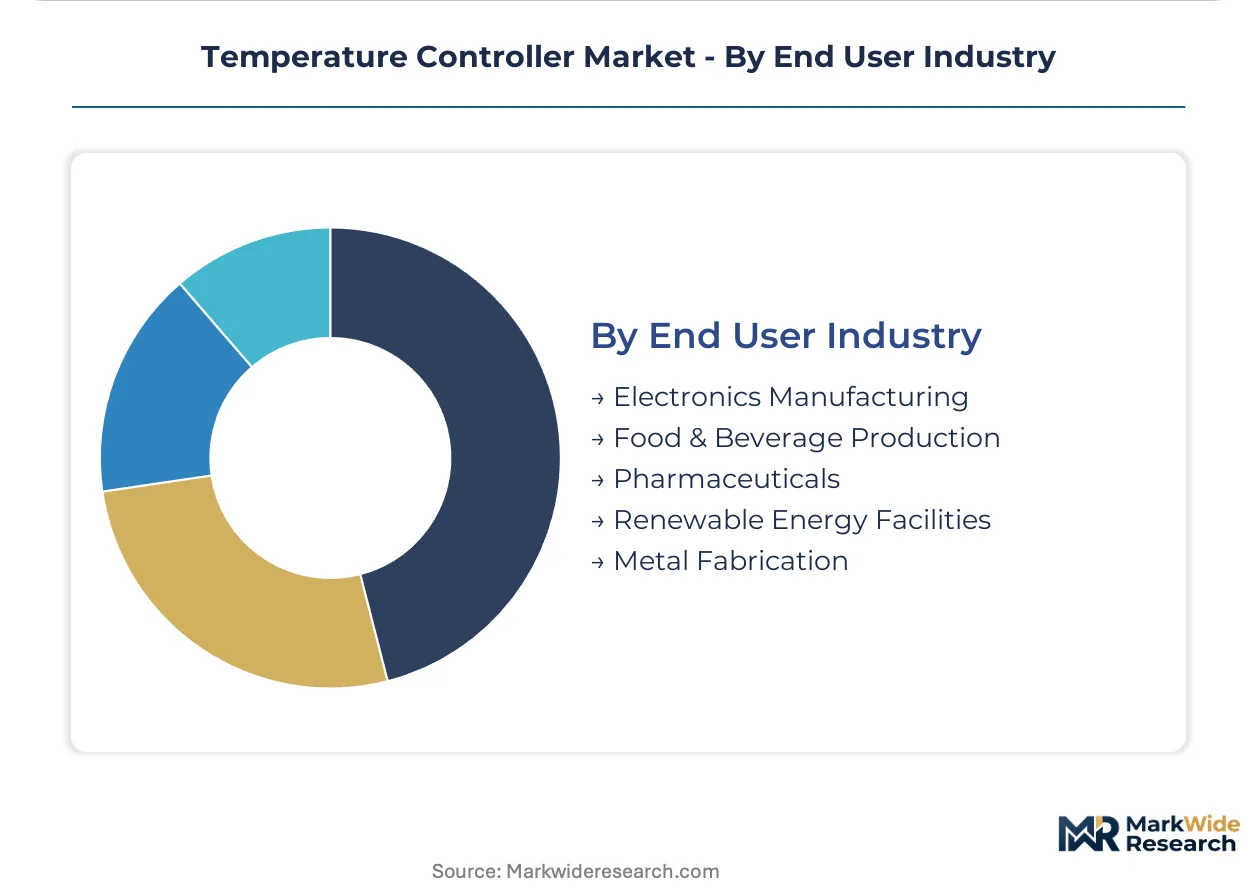
| Segmentation | Product Type: Digital Temperature Controllers, Analog Temperature Controllers, Programmable Controllers, PID Controllers, Relay Controllers Technology: Thermocouple, Resistance Temperature Detector, Infrared Sensors, Bimetallic, Semiconductor Sensors Application: Plastic Processing, Food Packaging, HVAC Systems, Semiconductor Manufacturing, Chemical Processing End User Industry: Electronics Manufacturing, Food & Beverage Production, Pharmaceuticals, Renewable Energy Facilities, Metal Fabrication |
| Companies Covered | Omron Corporation, Honeywell International, Schneider Electric, Watlow, Yokogawa Electric Corporation, Fuji Electric, ABB, Siemens, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Controller Market Strategic Shifts & Innovations
A fundamental re-evaluation of energy consumption is driving innovation, pushing controller design beyond simple setpoint maintenance. The integration of digital connectivity and on-device intelligence is creating new possibilities for process optimization and system-level efficiency.
AI-enhanced PID logic represents a significant evolution in process control. High-value manufacturing sectors, including pharmaceuticals and aerospace, are adopting these systems to achieve unprecedented levels of stability. This advanced control capability is consolidating the market around vendors offering complete automation platforms, marginalizing suppliers of basic, non-networked controllers.
The European Union's F-Gas Regulation is directly impacting equipment design in the HVAC and refrigeration industries. This mandate compels a shift to alternative refrigerants that require more precise thermal management to ensure both safety and operational efficiency. The cold chain logistics and commercial refrigeration segments are most affected, spurring investment in controllers with adaptive algorithms.
A behavioral shift is occurring from buying standalone controllers to specifying them as integrated modules within broader industrial automation ecosystems. This pattern disrupts traditional component distributors and favors system integrators who can provide end-to-end solutions. The trend is most pronounced in the factory automation markets of Germany and Japan, where total process control is a key performance indicator.
Temperature Controller Market Segmentation
Understanding the segmentation of the temperature controller market is crucial for vendors to align product development with specific industry demands and regulatory landscapes. This granular view enables companies to optimize their go-to-market strategies and allocate resources effectively across diverse application needs.
Product Type:
Supply concentration in temperature controller product types often dictates manufacturing specialization and component sourcing strategies for precise thermal management solutions.
- PID Controllers:These devices utilize proportional-integral-derivative algorithms to maintain precise thermal conditions, constantly adjusting outputs to minimize deviation from a setpoint. Their versatility and precision make them dominant in high-accuracy applications, including semiconductor manufacturing and pharmaceutical production.
- Digital Temperature Controllers:Featuring microprocessors for advanced logic and often equipped with connectivity options, these controllers offer enhanced programmability and data logging capabilities. Demand is concentrating in industries requiring remote monitoring and integration into broader automation systems, such as modern HVAC infrastructure and smart factories in Germany.
- Analog Temperature Controllers:These simpler devices provide basic on/off or proportional control using mechanical or electronic components without complex digital processing. They find use in less critical applications where cost-effectiveness and straightforward operation are priorities.
- Programmable Controllers:Offering more flexibility than basic digital units, these controllers allow users to define complex sequences and profiles for temperature regulation. They are frequently deployed in industrial ovens and specialized material processing.
- Relay Controllers:Functioning primarily as on/off switches, these controllers activate or deactivate heating or cooling elements based on a single setpoint. They are common in basic refrigeration units and water heating systems where precise modulation is not required.
Today's leader: PID Controllers. Tomorrow's challenger: Digital Temperature Controllers.
Technology:
The choice of temperature sensing technology directly influences performance characteristics and suitability for specific application environments, impacting overall system accuracy and response time.
- Resistance Temperature Detector:These sensors, often made from platinum, measure temperature by detecting changes in electrical resistance, offering high accuracy and stability over a wide range. Demand for RTDs is particularly high in semiconductor fabrication in Taiwan and biopharmaceutical reactors in the US, where precise temperature measurement is paramount.
- Thermocouple:Composed of two dissimilar metals, thermocouples generate a voltage proportional to temperature differences, providing robust and wide-ranging temperature measurement capabilities. Industries like metal fabrication and chemical processing in China rely on thermocouples for their durability and ability to withstand extreme conditions.
- Infrared Sensors:These non-contact sensors measure thermal radiation emitted by an object, making them ideal for monitoring moving targets or extremely hot surfaces. They are increasingly utilized in food processing for hygiene and in industrial furnaces.
- Bimetallic:Operating on the principle of differential thermal expansion of two joined metals, bimetallic sensors provide simple, mechanical temperature indication or switching. They are commonly found in basic thermostats and appliance controls.
- Semiconductor Sensors:Integrating temperature sensing directly onto silicon chips, these compact and low-cost sensors offer good linearity and are prevalent in consumer electronics and embedded systems. They are widely used in devices manufactured across Asia.
Resistance Temperature Detectors continue to offer superior accuracy, while infrared sensors are expanding most quickly in non-contact measurement.
Application:
Application-specific requirements drive significant volume differentiation across the temperature controller market, influencing design complexity and regulatory compliance needs.
- Semiconductor Manufacturing:This sector requires controllers with sub-second response times and extreme temperature stability for processes like photolithography and etching. Demand for these highly specialized controllers is concentrated in leading production hubs such as Taiwan and South Korea.
- HVAC Systems:Temperature controllers in HVAC systems manage heating, ventilation, and air conditioning to optimize energy efficiency and indoor climate control. Stricter environmental rules, such as the EU's F-Gas Regulation, necessitate more advanced controllers to manage new refrigerants and minimize energy waste in Europe.
- Plastic Processing:Controllers regulate mold temperatures and extrusion processes to ensure consistent material properties and product quality. They are crucial for maintaining uniformity in manufacturing operations.
- Food Packaging:Temperature controllers maintain precise conditions during processing and packaging to ensure food safety and extend shelf life. These systems must often meet stringent hygiene certifications for cold chain integrity.
- Chemical Processing:Controllers manage exothermic and endothermic reactions in chemical reactors, crucial for process safety and product yield. Accurate thermal regulation prevents runaway reactions and optimizes synthesis.
Semiconductor manufacturing maintains its demand for precision, while HVAC systems are undergoing significant controller upgrades.
End User Industry:
Customer type segmentation highlights varying procurement patterns and regulatory compliance needs across industrial sectors, influencing controller features and integration requirements.
- Food & Beverage Production:This industry prioritizes controllers that meet stringent hygiene and safety certifications, providing verifiable temperature logging for cold chain integrity. China's stringent GB standards drive investment in certified controllers for food processing facilities.
- Electronics Manufacturing:This sector demands high-precision temperature control for processes like semiconductor fabrication and component assembly. China's expansive electronics production drives significant demand for advanced thermal management solutions.
- Pharmaceuticals:Biopharmaceutical reactors and drug manufacturing processes require extremely stable and precise temperature control, often involving complex PID loops. Compliance with regulatory bodies like the FDA and EMA is critical for these applications.
- Renewable Energy Facilities:Applications in this sector, such as grid-scale battery installations, require sophisticated thermal regulation to maximize lifespan and prevent thermal runaway events. Controllers are integrated with battery management systems for optimal performance.
- Metal Fabrication:Controllers are essential for managing furnace temperatures in heat treatment, forging, and casting processes to achieve desired material properties. These systems ensure consistent quality and energy efficiency in industrial operations.
Food & Beverage Production prioritizes verifiable safety, while Renewable Energy Facilities are rapidly expanding their thermal management needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled engineering workforces across key industrial hubs anchor demand for temperature controllers. These regions, characterized by advanced manufacturing and stringent regulatory frameworks, drive innovation in thermal management. Global market dynamics reflect these concentrations of expertise and industrial activity.
United States
The United States market sees strong demand from biopharmaceutical reactors and renewable energy facilities. FDA regulations mandate precise temperature control for drug manufacturing processes. Boston's biotech cluster consistently drives investment in advanced thermal management solutions.
Germany
Germany's advanced factory automation and high-value manufacturing sectors require sophisticated temperature control. The EU Green Deal promotes energy-efficient industrial processes, necessitating advanced controllers. Bavaria's industrial automation sector remains a core hub for innovative controller deployment.
China
China's expansive electronics production and food processing industries generate significant controller demand. Stringent GB standards ensure product safety and cold chain integrity across various sectors. The Yangtze River Delta region drives extensive adoption of advanced thermal management systems.
Taiwan
Taiwan's dominant semiconductor manufacturing sector requires sub-degree precision for photolithography processes. Local standards prioritize extreme temperature stability for critical chip fabrication. The Hsinchu Science Park leads global demand for high-accuracy temperature controllers.
South Korea
South Korea's advanced semiconductor etching and electric vehicle battery production necessitate precise thermal management. Environmental regulations drive demand for energy-efficient controllers in industrial applications. Gyeonggi Province's manufacturing hubs are key adopters of these technologies.
Temperature Controller Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the temperature controller market, creating a dynamic competitive environment. This landscape exhibits a blend of highly integrated global players and specialized regional providers. Strategic archetypes include broad industrial automation conglomerates offering comprehensive solutions and niche precision control specialists. Companies pursue both capacity expansion and technology licensing to maintain their market positions and technological edge.
At the scale-driven end, Omron Corporation exemplifies specialists in high-speed, high-precision controllers for factory automation applications across Asia. Honeywell International occupies a position as a broad industrial automation conglomerate, leveraging its extensive portfolio in building automation and industrial process control. Schneider Electric represents a key player differentiating through its comprehensive EcoStruxure platform, integrating energy management with process automation. These entities collectively anchor significant market share by offering integrated solutions and adapting to evolving regulatory standards.
| Leading Market Players |
|---|
| Omron Corporation |
| Honeywell International |
| Schneider Electric |
| Watlow |
| Yokogawa Electric Corporation |
| Fuji Electric |
| ABB |
| Siemens |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
The European Union's F-Gas Regulation necessitates advanced controllers for new refrigerants, impacting supply chain investments and driving pricing for compliant solutions. Demand from semiconductor manufacturing for sub-degree precision also shapes how suppliers configure their offerings and price their specialized products.
Pricing Analysis
Bundled solutions, combining advanced controllers with integration services, command premium pricing, while basic units are priced transactionally. Pricing stratifies across premium, standard, and economy tiers based on certification level (e.g., CE, UL, GB) and required precision. Price differentiation also stems from after-sales support and customization levels. Upward pricing pressure arises from the demand for AI-enabled features and stringent regulatory compliance. Analog controller buyers remain highly price-sensitive, whereas semiconductor and biopharmaceutical manufacturers prioritize performance over cost.
Supply Chain Analysis
Logistics and freight costs for high-precision components influence final product pricing and regional competitiveness. Geographic supply concentration for critical components rests in China for electronics, Taiwan for semiconductor-grade inputs, and Japan for precision manufacturing. The market relies on specific raw materials like high-precision thermistors and platinum resistance thermometers. Component cost volatility, driven by raw material markets, represents a significant supply chain risk. Distribution runs through direct sales to large industrial integrators and OEMs, supplemented by specialized regional distributors for smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The temperature controller market represents a stable compounder. The continuous need for thermal regulation across diverse industrial processes, from food safety to semiconductor manufacturing, drives steady growth.
For Market Incumbents:
Cement leadership by investing heavily in AI-enabled predictive control R&D, anticipating future process optimization demands. Acquire niche precision control specialists to expand technological breadth and address specific high-value applications. Focus on strengthening cybersecurity features for connected devices to mitigate growing threats. Invest in comprehensive certification programs, particularly for China's GB standards, to ensure broad market access and compliance.
For New Entrants and Emerging Players:
A significant price-point gap exists between premium, integrated solutions and basic, standalone controllers. Target thermal management in Electric Vehicle battery production and specialized biopharmaceutical reactors, which are high-growth, underserved areas. The most penetrable segment for new entrants involves replacing older analog controllers in less critical industrial applications. Partner with regional system integrators to offer custom interfaces and middleware for seamless integration into legacy systems.
For Investors and Strategic Acquirers:
Asymmetric upside sits with companies developing advanced control algorithms and sensor technologies. This market offers sustained growth over the next decade, driven by industrial automation and regulatory mandates. Target acquisition profiles include firms specializing in AI-enabled control algorithms or those with strong intellectual property in advanced sensor technologies. A key signal to watch for inflection is increased M&A activity focused on software-centric control and integration firms.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development | Enhances controller precision and enables predictive maintenance for high-value manufacturing. |
| Regional Certification Investment | Ensures compliance with specific market standards like China's GB, expanding market access. |
| Integration Platform Expansion | Bundles hardware with software, capturing more value from end-to-end automation projects. |
| High-Precision Sensor R&D | Addresses demand for sub-degree stability in semiconductor and biopharma applications. |
| Strategic Partnership with BMS Providers | Secures market share in rapidly growing electric vehicle battery production. |
Research Approach
Direct dialogue with plant engineers, R&D directors, procurement managers at semiconductor fabs, and HVAC system integrators provided primary insights. This was combined with secondary validation from sources such as EU F-Gas Regulation documents, UL standards, China GB standards, and semiconductor industry reports. The analysis leveraged both bottom-up data from company reports and top-down market sizing for triangulation.
A bottom-up analysis of end-use sectors, validated by top-down market sizing, formed the analytical framework. Segmentation dimensions modeled include product type, technology, application, end-user industry, geographic region, and precision requirement. CAGRs were derived from historical trends and projected technological advancements across the analysis window. Industry-specific forecast inputs included semiconductor fab expansion plans and Electric Vehicle battery production forecasts.
Caveats apply where sudden shifts in raw material prices or major geopolitical trade restrictions could materially shift the outlook. Forecasts reflect assumptions documented in the full report. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Timing Device Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market