
 Wireless Network Test Equipment Market | 2026-2036
Wireless Network Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Network Test Equipment Market Intelligence
FCC spectrum reallocation mandates for mid-band 5G is expanding the capital intensity of network validation. Keysight Technologies Inc. anchors North American supply through its dominance in mmWave signal generation. Rohde & Schwarz GmbH & Co. KG leverages its European manufacturing base to sustain R&D intensity in vector network analysis. Huawei Technologies Co. Ltd. navigates export control complexity while competing on price-performance in Asia-Pacific base station emulation.
Wireless network test equipment comprises calibrated measurement instruments that characterize radio frequency performance across parameters including error vector magnitude, adjacent channel leakage ratio, and spurious emissions. These systems verify transmitter and receiver integrity before commercial network activation. Spectrum analyzers capture the largest margin pools as carriers validate increasingly congested frequency assignments. Network emulators represent the fastest-growing hardware category because 5G standalone protocol testing requires real-time replication of multi-cell interference. Software solutions within the solution segment are displacing legacy hardware-only configurations as virtualized radio access networks demand cloud-native test orchestration.
3GPP, the FCC, and ETSI collectively determine which test methodologies achieve regulatory recognition across deployment jurisdictions. 3GPP conformance specifications directly shape product roadmaps, while FCC equipment authorization rules gate market access for any transmitter sold in the United States. Stakeholders must decide whether to absorb certification complexity in-house or outsource to accredited test houses as regional spectrum fragmentation intensifies.
Market Dynamics
3GPP Release 18 specifications are compressing test validation cycles as carriers race to certify millimeter-wave base stations before spectrum licenses activate. This regulatory compression is forcing equipment vendors to parallelize conformance testing with R&D rather than sequencing them.
Growth Catalysts
- Mid-band spectrum reallocation:FCC mandates in the United States are mandating fresh validation cycles for C-band equipment, pulling demand for vector signal analyzers and channel emulators.
- Base station densification:South Korean operators are validating propagation models across Seoul and Busan metropolitan testbeds, creating concentrated demand spikes for portable spectrum monitoring systems.
- Open RAN disaggregation:Multi-vendor interoperability testing is expanding addressable scope for protocol analyzers as carriers dismantle single-supplier radio access networks.
Market Restraints
- GaN substrate cost volatility:Gallium nitride wafer prices for high-frequency test components swing with power electronics demand, squeezing margin predictability for instrument manufacturers.
- Calibration equipment concentration:Primary standards laboratories cluster in Germany, Japan, and the United States, creating geographic chokepoints for metrology traceability.
- Sub-6 GHz saturation:Mature LTE test suites face substitution pressure as carriers redirect capital toward millimeter-wave validation platforms.
Strategic Opportunities
- India spectrum auctions:TRAI's scheduled 5G mid-band releases are creating virgin demand for network emulators among domestic system integrators lacking legacy test infrastructure.
- Automotive V2X certification:DSRC and C-V2X protocol validation for connected vehicles represents an emerging application vector with distinct latency and reliability benchmarks.
- Cloud-native orchestration:Kubernetes-based test automation is enabling subscription revenue models that displace perpetual hardware licenses among virtualized RAN operators.
Industry Challenges
- Millimeter-wave calibration expertise:Technicians capable of traceable E-band measurements command salary premiums that inflate service delivery costs.
- Multi-standard certification backlog:Simultaneous 3GPP, FCC, and ETSI conformance submissions are stretching test house capacity and extending time-to-market for new instrument platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Network Test Equipment Market |
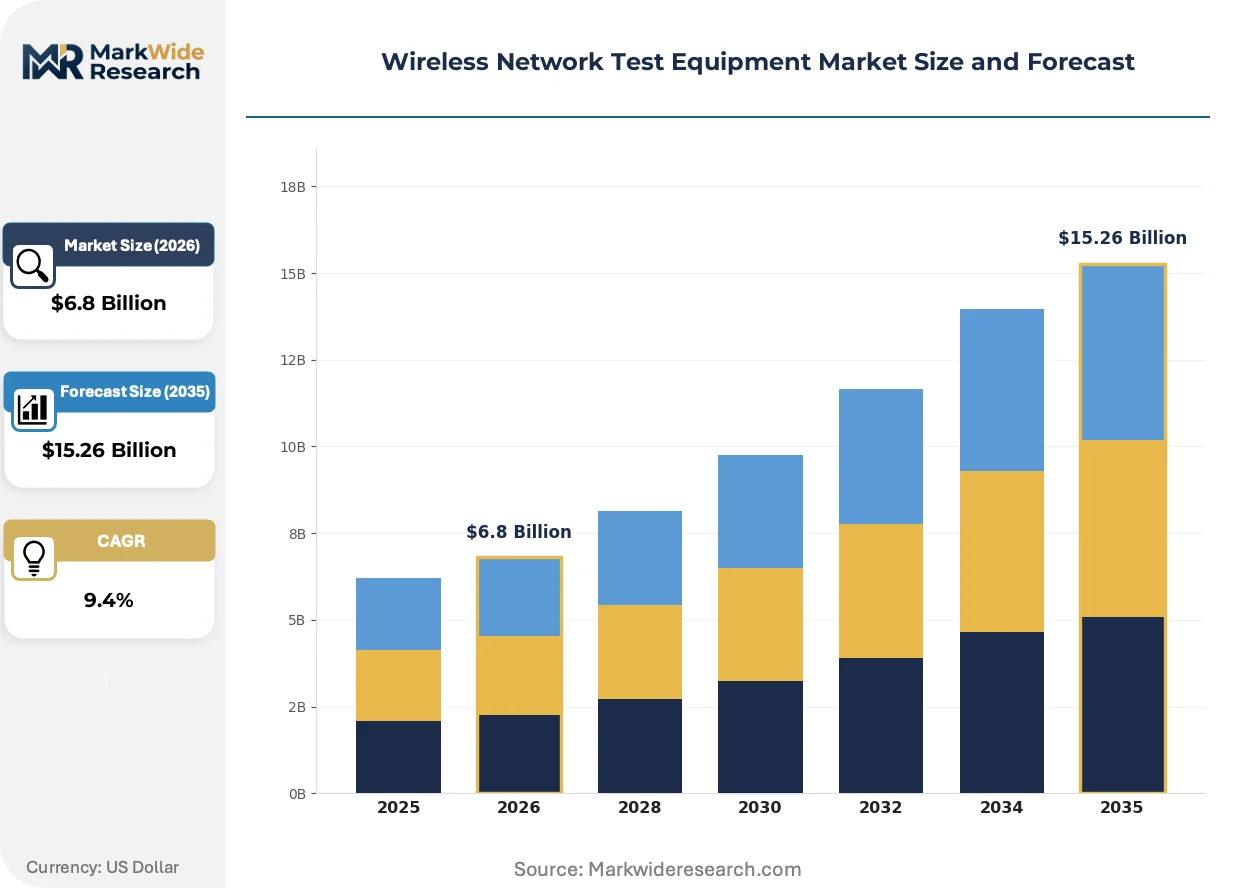
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Analyzers, Spectrum Analyzers, Cable Testers, Network Emulators Technology: 5G, LTE, Wi-Fi, Bluetooth End User: Telecom Providers, IT Companies, Government Agencies, Enterprises Solution: Hardware Solutions, Software Solutions, Managed Services, Consulting Services |
| Companies Covered | Ericsson AB, Keysight Technologies Inc., Huawei Technologies Co. Ltd., NETSCOUT Systems Inc., Rohde & Schwarz GmbH & Co. KG, Cisco Systems Inc., Nokia Corporation, Anritsu Corporation, Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Network Test Equipment Market Strategic Shifts & Innovations
Test instrumentation architecture is fragmenting as software-defined radio platforms displace fixed-function hardware. This shift is compressing product lifecycles while expanding customization depth for vertical-specific validation protocols.
Modular PXIe-based test systems are decentralizing signal generation and analysis functions across distributed edge computing nodes. Telecom equipment manufacturers are adopting these platforms to parallelize base station conformance testing across multiple sites simultaneously. This topology is collapsing the centralized rack-scale instrumentation model that dominated 4G validation workflows.
ETSI's harmonized standards for 5G advanced are mandating updated test methodologies across European Economic Area member states. Equipment manufacturers must resubmit existing product lines for fresh CE marking compliance, triggering replacement demand for legacy spectrum analyzers. German test houses are expanding capacity to absorb this certification surge ahead of enforcement deadlines.
Carrier procurement teams are unbundling hardware acquisition from calibration service contracts, reversing the integrated sourcing model that prevailed through 2020. Independent metrology providers are capturing recurring revenue streams previously held by original equipment manufacturers. This disaggregation is most pronounced in South Korea, where SK Telecom and KT Corporation have separated test asset ownership from operational support agreements.
Wireless Network Test Equipment Market Segmentation
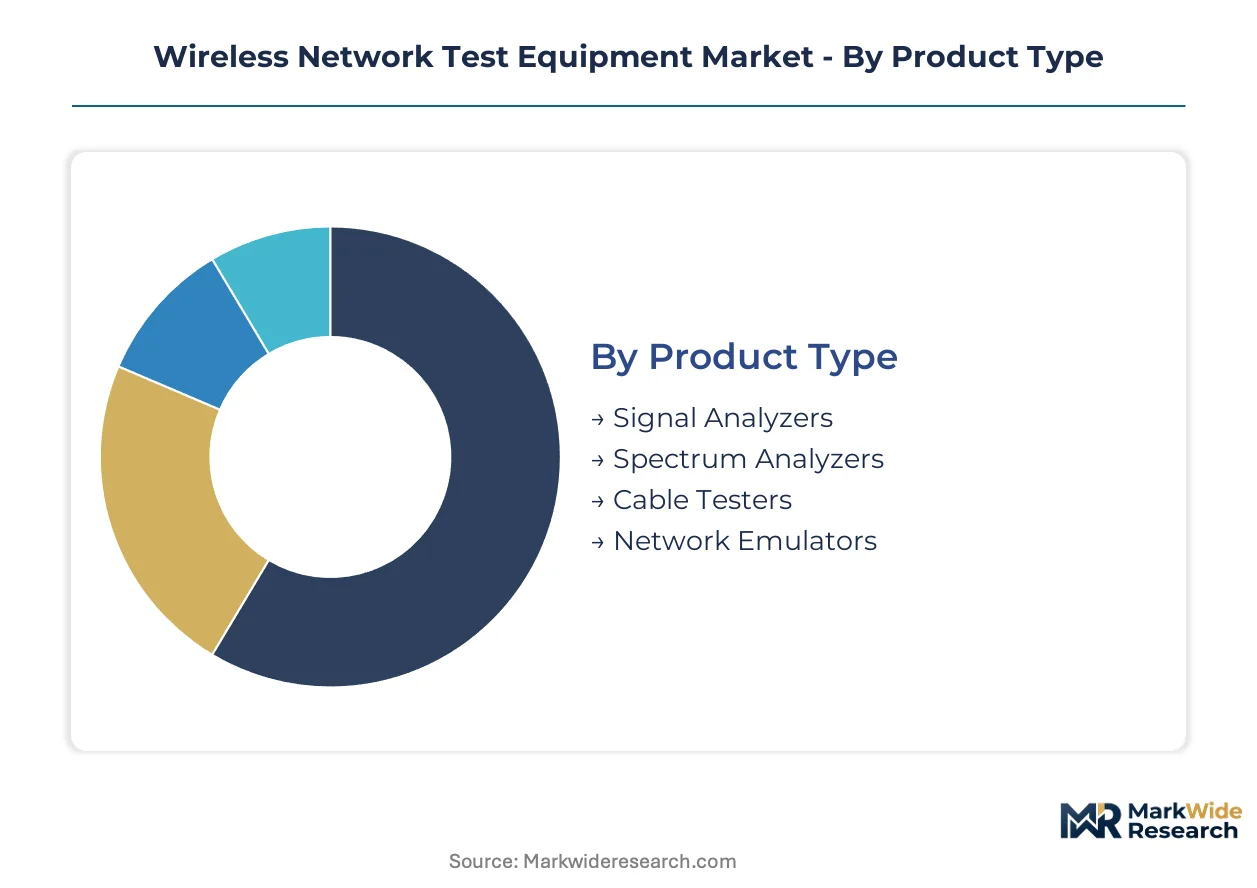
Segmentation in wireless network test equipment reveals how procurement priorities diverge across deployment scenarios. Equipment vendors must calibrate product portfolios against distinct technical requirements and budget cycles that separate carrier-grade validation from enterprise installation.
Product Type:
Customization intensity varies sharply across this category, with portable field instruments demanding ruggedized variants while rack-mounted laboratory systems require modular expansion paths.
- Signal Analyzers:These instruments measure modulation accuracy, phase noise, and harmonic distortion across carrier aggregation configurations. German telecom providers are standardizing on multi-channel vector signal analysis platforms that compress 5G base station certification timelines. Cost concentration in high-end PXIe architectures is squeezing mid-tier suppliers.
- Spectrum Analyzers:Real-time frequency domain capture systems with swept-tuned or FFT-based architectures dominate regulatory compliance workflows. South Korean operators in Seoul metropolitan testbeds are deploying portable spectrum monitors to validate millimeter-wave propagation models before national 5G standalone activation.
- Cable Testers:Time-domain reflectometry instruments characterize feeder line integrity and antenna port matching.
- Network Emulators:Protocol test systems replicate multi-cell interference scenarios for 5G standalone conformance validation.
Most installed capacity flows through Spectrum Analyzers. Expansion is steepest in Network Emulators.
Technology:
Technology segments map directly to capital allocation cycles, with 5G commanding premium instrumentation spend while legacy cellular test suites face substitution pressure.
- 5G:Test requirements span sub-6 GHz and millimeter-wave bands with massive MIMO beamforming validation. FCC mid-band reallocation mandates in the United States are pulling fresh demand for channel emulators and over-the-air test chambers.
- LTE:Mature test methodologies face margin compression as carriers redirect capital toward 5G advanced validation platforms. Japanese equipment manufacturers are maintaining LTE test capacity primarily for IoT module certification and roaming interoperability.
- Wi-Fi:Wi-Fi 6E and Wi-Fi 7 test requirements are expanding addressable scope for spectrum analyzers in enterprise deployment.
- Bluetooth:Low-energy protocol test systems serve consumer electronics and automotive infotainment module validation.
Deployment volume concentrates in 5G. Wi-Fi is gaining share fastest among enterprise segments.
End User:
End user segmentation separates centralized procurement with multi-year service contracts from transactional hardware purchases with minimal calibration attachment.
- Telecom Providers:Tier-1 carriers operate dedicated validation laboratories with 24/7 conformance testing schedules. South Korean operators including SK Telecom and KT Corporation have unbundled test asset ownership from operational support agreements, creating recurring revenue opportunities for independent metrology providers.
- IT Companies:Data center interconnect and private 5G network deployments drive demand for portable cable certification and fiber characterization tools.
- Government Agencies:National spectrum regulators and defense communications programs require traceable measurement standards with primary laboratory calibration chains.
- Enterprises:Manufacturing facilities and logistics hubs are deploying private cellular networks with simplified installation verification protocols.
Capital deployment is heaviest among Telecom Providers. Procurement activity is climbing fastest in Enterprises.
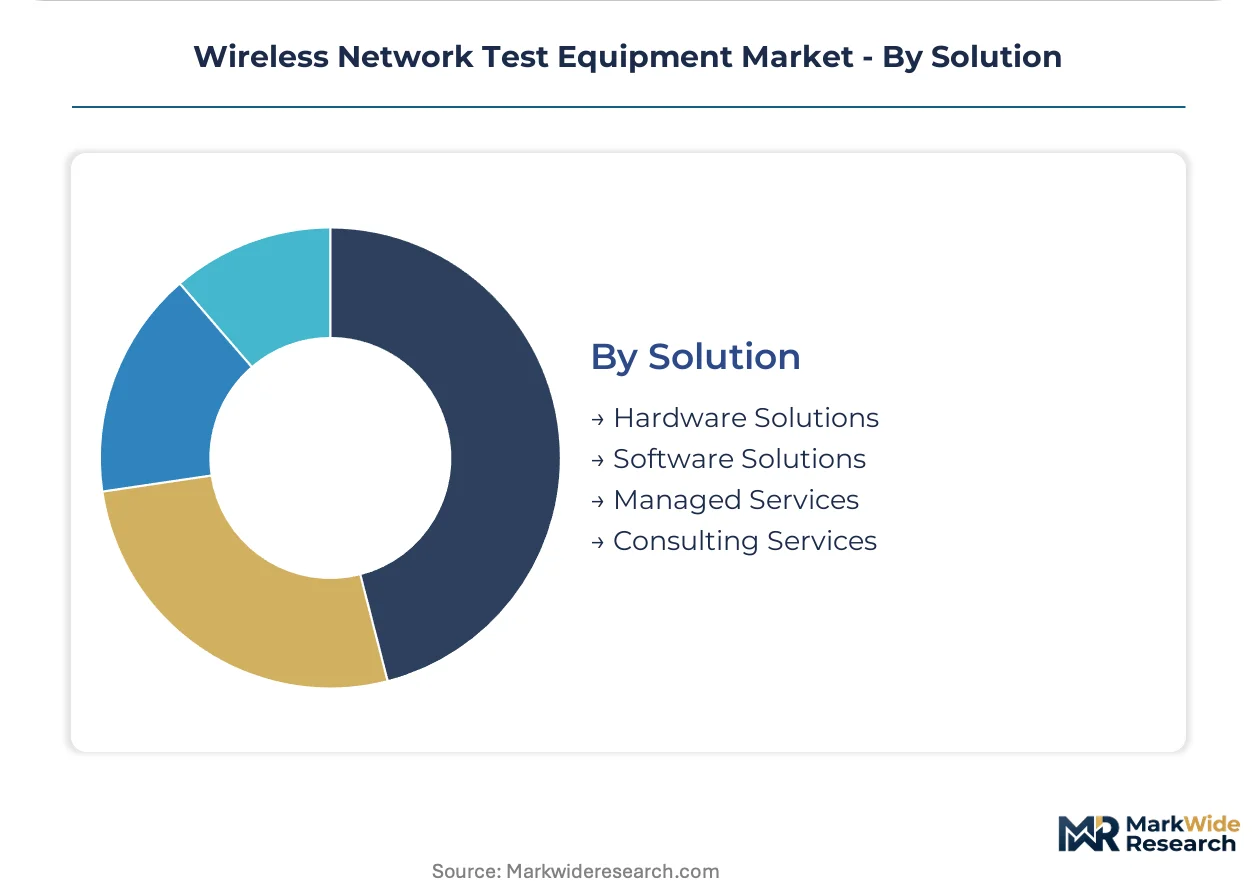
Solution:
Solution architecture determines margin structure, with perpetual hardware licenses yielding upfront revenue while subscription orchestration platforms build recurring streams.
- Hardware Solutions:Calibrated measurement instruments with factory warranty and depot repair programs remain the revenue foundation. Keysight Technologies and Rohde & Schwarz dominate high-frequency signal generation through proprietary ASIC architectures.
- Software Solutions:Cloud-native test orchestration platforms are displacing legacy hardware-only configurations as virtualized RAN deployments demand Kubernetes-based automation.
- Managed Services:Outsourced test house capacity absorbs certification complexity for equipment manufacturers facing simultaneous 3GPP, FCC, and ETSI submission deadlines.
- Consulting Services:Protocol expertise and regulatory navigation support compress time-to-market for new instrument platforms.
Revenue concentration sits with Hardware Solutions. Subscription expansion is steepest in Software Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless network test equipment originated in German precision instrumentation laboratories during the 1980s cellular expansion, then migrated to US defense contractors and Japanese consumer electronics manufacturers before consolidating in South Korean 5G testbeds during the past decade.
United States
FCC mid-band spectrum reallocation mandates are compressing validation cycles for C-band base station certification. Equipment authorization rules under FCC Part 27 gate market access for millimeter-wave transmitters. Test house capacity concentrates in Silicon Valley and Greater Boston corridors where carriers parallelize conformance submissions.
Germany
ETSI harmonized standards for 5G advanced trigger fresh CE marking compliance cycles across industrial automation networks. Primary standards laboratories in Munich and Berlin anchor metrology traceability for vector network analysis. Bavarian test houses expand capacity to absorb certification surges ahead of enforcement deadlines.
South Korea
SK Telecom and KT Corporation unbundled test asset ownership from operational support agreements, creating recurring revenue pools for independent metrology providers. National spectrum regulators mandate over-the-air validation before commercial 5G standalone activation. Seoul and Busan metropolitan testbeds validate millimeter-wave propagation models at scale.
Japan
METI industrial policy directs capital toward 6G pre-standardization research, extending R&D timelines for test instrument manufacturers. Anritsu and Yokogawa heritage concentrates vector signal analysis expertise in Kanto and Kansai industrial corridors. Equipment manufacturers maintain LTE test capacity primarily for IoT module certification.
India
TRAI scheduled 5G mid-band spectrum releases generate virgin demand for network emulators among domestic system integrators. PLI scheme incentives attract test equipment assembly operations to Gujarat and Tamil Nadu manufacturing zones. Bangalore and Hyderabad tech clusters absorb protocol expertise for multi-vendor interoperability validation.
Wireless Network Test Equipment Market Key Industry Players
The competitive structure tilts toward diversified technology conglomerates with captive semiconductor fabrication capabilities. Consolidation pressure intensifies as 5G advanced conformance requirements demand simultaneous multi-band validation platforms. Three archetypes dominate: precision instrumentation specialists with primary metrology heritage, diversified telecom equipment vendors with integrated test divisions, and modular software-defined radio platform providers. Geographic expansion and strategic technology licensing represent the dominant competitive vectors as regional spectrum fragmentation deepens.
Among precision instrumentation specialists, Keysight Technologies Inc. and Rohde & Schwarz GmbH & Co. KG exemplify the metrology-anchored archetype through their dominance in high-frequency signal generation and vector network analysis. Huawei Technologies Co. Ltd. occupies a distinct position navigating export control complexity while competing on price-performance metrics in Asia-Pacific base station emulation. These three companies represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Ericsson AB |
| Keysight Technologies Inc. |
| Huawei Technologies Co. Ltd. |
| NETSCOUT Systems Inc. |
| Rohde & Schwarz GmbH & Co. KG |
| Cisco Systems Inc. |
| Nokia Corporation |
| Anritsu Corporation |
| Qualcomm Incorporated |
| Others |
Cost & Logistics Intelligence
Gallium nitride wafer price volatility cascades through instrument manufacturing tiers, compressing margins for high-frequency test components while carriers unbundle hardware from calibration contracts to offset capital intensity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade PXIe architectures from field-portable units and refurbished legacy systems. Certification-grade differentiation hinges on NIST-traceable calibration chains and FCC Part 27 authorization status. Cost compression in mid-tier signal analyzers is intensifying because South Korean operators are consolidating procurement volumes. Enterprise private network deployments exhibit highest price sensitivity, while national spectrum regulators demonstrate lowest sensitivity due to mandate-driven replacement cycles.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese primary standards laboratories for metrology traceability. Manufacturing concentration clusters in Germany, the United States, and South Korea for precision RF components. Instrument production draws from GaN substrates, high-purity sapphire wafers, and proprietary ASIC architectures. Tariff exposure runs through semiconductor fabrication equipment subject to export control classifications. Distribution runs through authorized channel partners with factory-certified calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
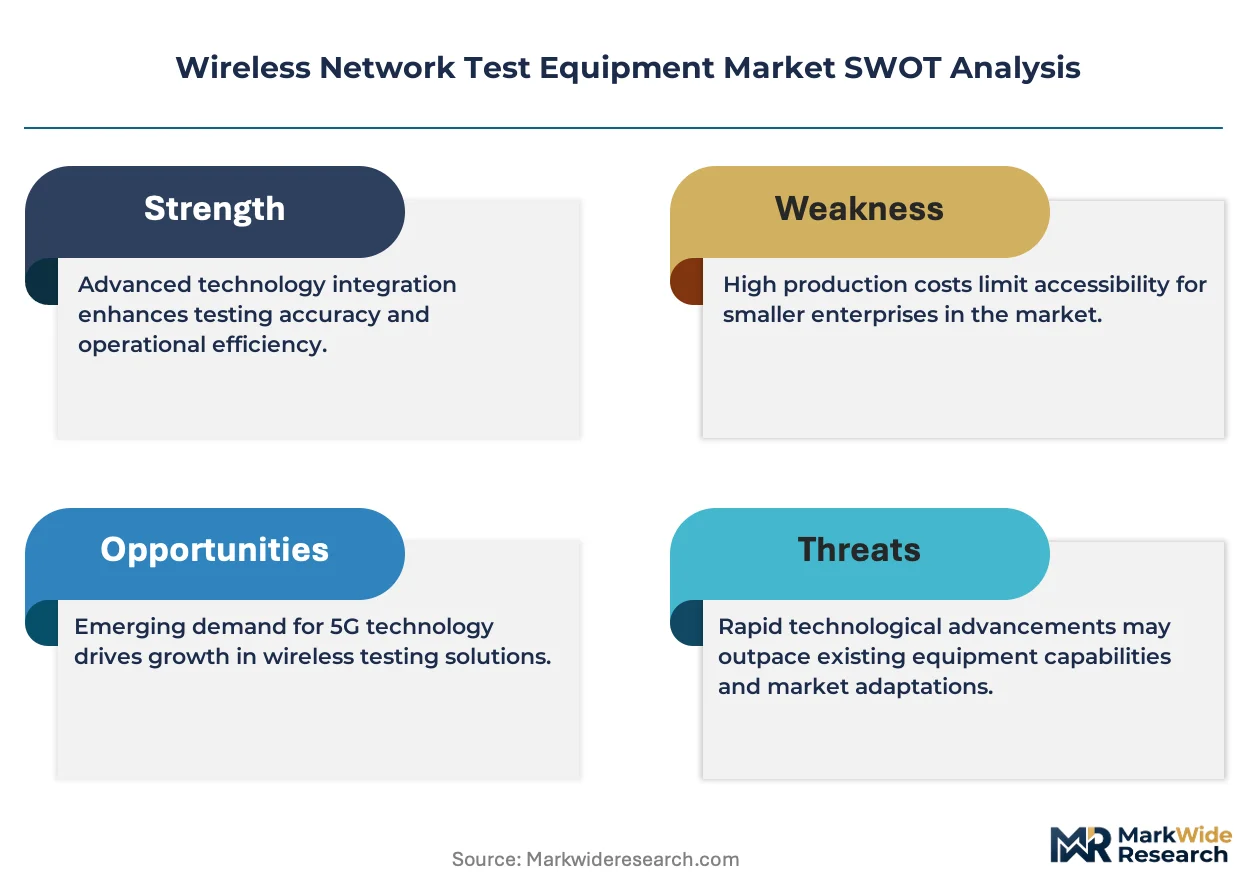
This market represents a late-cycle quality story as 5G advanced conformance requirements shift procurement toward multi-band validation platforms with embedded protocol expertise.
For Market Incumbents: Cement metrology leadership by captive control over primary calibration laboratory capacity in Munich and Berlin. Deepen backward integration into GaN substrate supply through long-term offtake agreements with Japanese wafer suppliers. Defensive positioning must counter modular software-defined radio platforms that displace fixed-function hardware architectures. For New Entrants and Emerging Players: Begin with cloud-native test orchestration subscriptions targeting Indian system integrators lacking legacy infrastructure investment. The most penetrable white-space sits with Kubernetes-based automation for virtualized RAN deployments. A direct enterprise sales motion bypassing carrier procurement committees accelerates initial traction. For Investors and Strategic Acquirers: Asymmetric upside sits with precision instrumentation specialists possessing primary metrology heritage and ETSI harmonized standards expertise. Long-term viability centers on recurring calibration revenue streams as hardware ownership unbundles from operational support. The signal to monitor is FCC enforcement acceleration for mid-band reallocation deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | Primary standards capacity in Germany absorbs ETSI certification surges ahead of enforcement deadlines. |
| Cloud-Native Platform Launch | Kubernetes-based orchestration captures subscription revenue from virtualized RAN operators unbundling hardware. |
| GaN Supply Agreement | Long-term wafer offtake secures margin predictability against power electronics demand swings. |
| Multi-Vendor Interoperability Certification | Open RAN validation protocols expand addressable scope beyond single-supplier radio access networks. |
| Automotive V2X Protocol Investment | DSRC and C-V2X certification builds emerging revenue vector with distinct latency benchmarks. |
Research Approach
Bottom-up carrier procurement modeling reconciled against top-down semiconductor supply tracking forms the analytical core. Primary interviews with validation laboratory directors, carrier network engineers, test house operations managers, and regulatory compliance officers combine with secondary validation from FCC equipment authorization databases, 3GPP release documentation, ETSI harmonized standards filings, and customs trade records for RF component flows.
Input-output matrices map instrument shipments through end-use segments across the projection horizon. Segmentation dimensions span product type, technology generation, end-user category, and solution architecture. CAGRs derive from regression analysis against carrier capital expenditure cycles and spectrum license activation timelines. Industry-specific forecast inputs include GaN substrate price indices and 3GPP conformance specification release schedules.
Several conditions sit outside the modeled scope, including pre-commercial 6G research expenditures and defense classified test programs. Forecasts reflect documented assumptions regarding spectrum reallocation timelines and regulatory enforcement intensity. Unmodeled risks encompass export control expansion affecting semiconductor fabrication equipment and calibration technician labor shortages. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Volte Testing Market
Test and Measurement
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Flow Meter Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
DSL Tester Market
Test and Measurement
Digital Inspection Market