
 Digital Inspection Market | 2026-2036
Digital Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Inspection Market Intelligence
Consolidation among large-scale manufacturers in the automotive and electronics sectors is restructuring procurement patterns for inspection technologies. Zeiss Group specializes in high-precision metrology and microscopy systems for demanding applications. Cognex Corporation leverages its expertise in machine vision for factory automation. Hexagon AB provides a broad portfolio of sensor, software, and autonomous solutions for industrial measurement.
Digital inspection automates quality control by using hardware like cameras and sensors with analytical software. These systems can identify surface flaws, dimensional inaccuracies, or internal defects at micron-level precision, enhancing manufacturing yield. While hardware, including visual and X-ray systems, holds significant value, the software and services segments are expanding rapidly. This growth is driven by demand for AI-powered analytics in quality control and compliance checking applications.
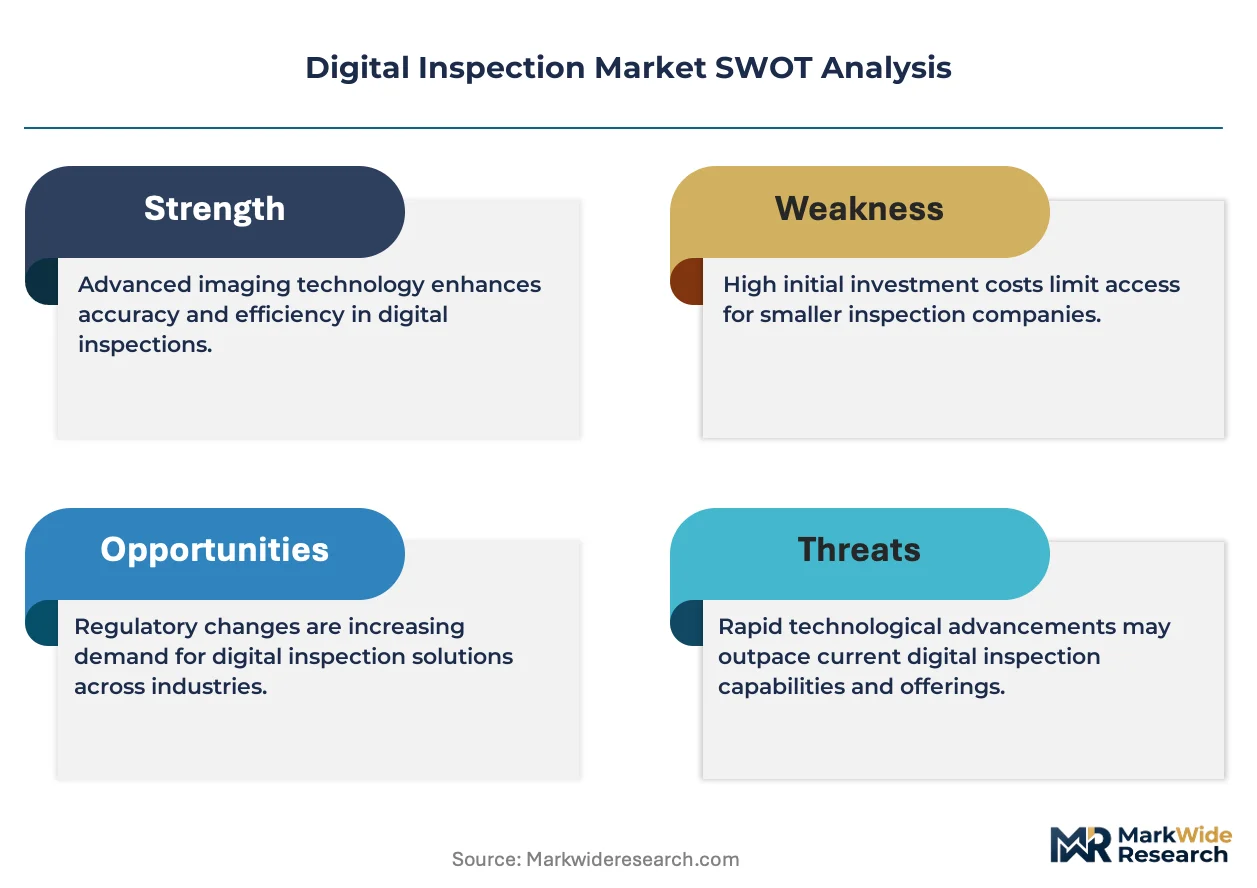
Regulatory frameworks are a significant driver of adoption. The FDA in the United States, CE marking requirements in the European Union, and GB standards in China all mandate stringent quality verification. These rules necessitate auditable, repeatable inspection data that digital systems provide. The strategic decision for vendors now centers on balancing specialization in a single technology, like ultrasonic, against developing integrated, multi-modal platforms.
Market Dynamics
The primary structural force is the transition from hardware-centric sales to recurring revenue models based on software and services. This shift is driven by demand for AI-powered analytics and integrated data from connected inspection devices across manufacturing operations.
Growth Catalysts
- Industry 4.0 Principles:Integration of connected devices and data analytics in manufacturing hubs like Germany acts as a catalyst for automated quality control.
- Regulatory Mandates:Stringent rules from bodies like the FDA and the EU's CE marking framework necessitate auditable, repeatable inspection data.
- Aerospace Component Integrity:The aerospace sector’s need for flawless component verification drives demand for high-precision X-ray and ultrasonic inspection technologies.
Market Restraints
- High Capital Outlay:Significant upfront investment for advanced hardware like X-ray systems is a barrier for smaller manufacturers.
- Legacy System Integration:Integrating modern digital platforms with existing, proprietary manufacturing execution systems (MES) is complex, costly, and slows adoption.
- Component Supply Concentration:A concentrated supply chain for critical components like high-performance sensors creates potential bottlenecks and price volatility for vendors.
Strategic Opportunities
- Integrated Multi-Modal Platforms:Developing systems combining technologies like visual and ultrasonic inspection addresses complex quality control needs in one solution.
- AI-Powered Predictive Analytics:Offering software that uses inspection data to predict process drift and prevent future quality issues is a significant growth area.
- SME Market Penetration:Creating scalable, cost-effective inspection solutions for small and medium-sized enterprises (SMEs) opens a large, underpenetrated market segment.
Industry Challenges
- Data Science Talent Gap:A shortage of technicians and data scientists skilled in implementing and maintaining AI-powered analytical software limits the effective deployment of advanced systems.
- Lack of Data Standardization:The absence of universal standards for data formats and communication protocols complicates interoperability between equipment from different vendors, increasing integration complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Inspection Market |
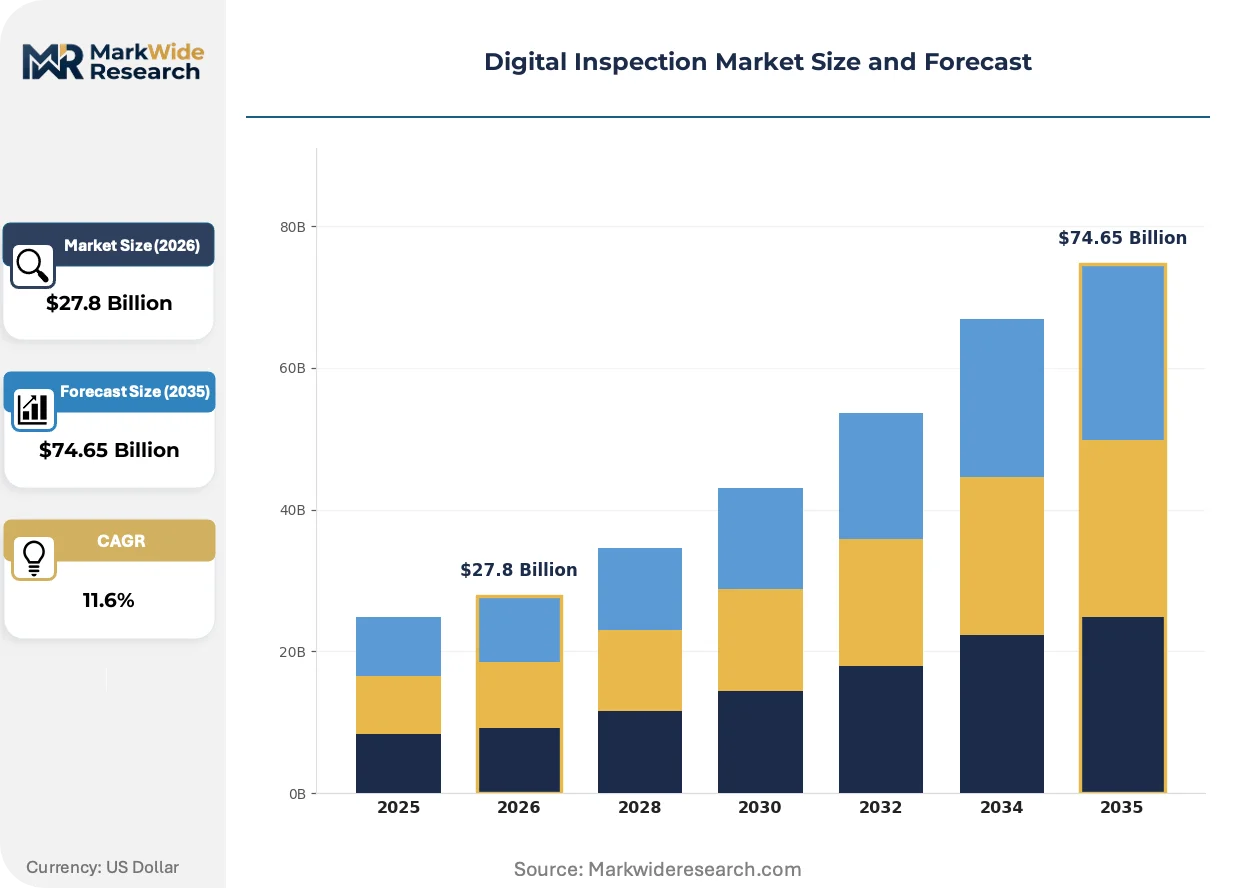
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $74.65 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions End User: Manufacturers, Construction, Aerospace, Automotive Technology: Visual, X-Ray, Ultrasonic, Laser Application: Quality Control, Compliance Checking, Safety Inspection, Maintenance |
| Companies Covered | Teledyne Technologies, Zeiss Group, Cognex Corporation, FLIR Systems, National Instruments, Keyence Corporation, Omron Corporation, KLA Corporation, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Inspection Market Strategic Shifts & Innovations
Digital inspection's evolution is defined by its shift from reactive quality checks to proactive, integrated process control. This transition is powered by software-driven intelligence and connectivity, fundamentally changing how manufacturers manage quality.
AI-powered algorithms provide the core technology for advanced image recognition and defect classification. High-volume electronics and automotive manufacturing sectors are rapidly adopting these systems to achieve micron-level precision. This technology is integrating quality data directly into production line controls, enabling real-time process adjustments and reducing scrap rates significantly.
The ISO 13485 standard for medical devices mandates comprehensive quality management systems, including stringent device history records. This regulation compels manufacturers to implement digital inspection systems that generate auditable, electronic data for every component and assembly. The cardiovascular and orthopedic device segments are most affected, investing heavily in automated visual and metrology systems for compliance.
A behavioral shift from one-time capital equipment purchases toward flexible, subscription-based service models is gaining traction. This "Inspection-as-a-Service" approach allows manufacturers to access the latest technology without a large upfront investment, unbundling hardware from software and support. This model is most visible among contract electronics manufacturers in Asia who prioritize operational agility and cost management.
Digital Inspection Market Segmentation
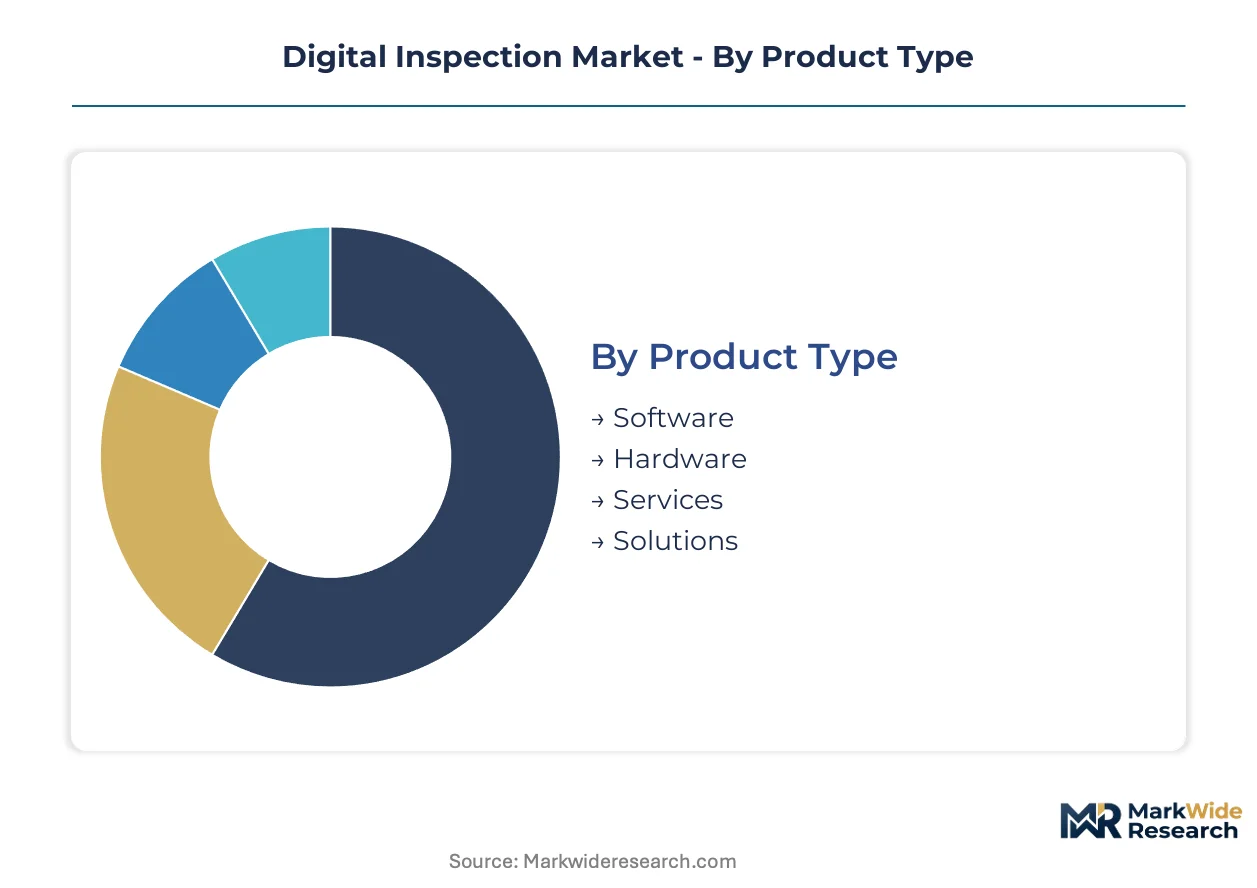
Digital inspection market segmentation reveals the diverse operational requirements and technological preferences across various industrial verticals. Understanding these distinctions allows vendors to tailor solutions precisely, addressing specific challenges from regulatory compliance to process optimization. Each segment reflects unique demand patterns and adoption drivers within the broader digital inspection landscape.
Product Type:
Digital inspection product types vary significantly in their regulatory compliance requirements, with some components demanding rigorous certification for safety-critical applications.
- Hardware:This segment includes physical devices like cameras, sensors, X-ray systems, and ultrasonic probes used for data acquisition. Demand concentrates in the aerospace and automotive sectors for high-precision component integrity verification.
- Software:This segment encompasses analytical platforms, AI-powered algorithms for defect classification, and data integration tools. Manufacturing hubs like Germany and South Korea show strong demand, driven by Industry 4.0 principles.
- Services:This includes implementation support, maintenance contracts, data analytics consultation, and Inspection-as-a-Service models. Contract electronics manufacturers in Asia prioritize these flexible, subscription-based offerings.
- Solutions:Integrated platforms combine hardware, software, and services to provide comprehensive digital inspection capabilities. These platforms address complex quality control needs across multiple industrial applications.
Hardware sits at the top of the volume ranking, with Software climbing the fastest.
End User:
End-user segments for digital inspection systems are differentiated by their operational scale and the complexity of their quality control requirements.
- Aerospace:This sector requires flawless component integrity verification for critical parts, often using high-precision X-ray and ultrasonic inspection technologies. Stringent regulations from bodies like the FAA necessitate auditable inspection data for every component.
- Automotive:High-volume automotive manufacturing demands micron-level precision for dimensional accuracy and surface flaw detection. Consolidation among large-scale manufacturers drives procurement of advanced inspection systems.
- Manufacturers:A broad category covering diverse industrial applications for quality control, process optimization, and defect detection. This segment includes general manufacturing processes beyond automotive and aerospace.
- Construction:Digital inspection aids in structural integrity assessment, material verification, and infrastructure monitoring. Drones equipped with visual and thermal cameras are increasingly deployed for large-scale projects.
The aerospace sector drives demand for the most stringent inspection capabilities, while manufacturing remains the largest volume consumer.
Technology:
Digital inspection technologies are primarily segmented by their operational principles, addressing varying levels of precision and defect detection requirements.
- X-Ray:This technology provides non-destructive internal defect detection and material analysis, crucial for components where surface inspection is insufficient. Aerospace and medical device manufacturers heavily utilize X-ray systems for critical component verification.
- Ultrasonic:Ultrasonic inspection detects sub-surface flaws, measures material thickness, and assesses structural integrity using sound waves. The aerospace and infrastructure sectors rely on ultrasonic systems for complex material analysis and fatigue detection.
- Visual:Utilizes cameras and advanced image processing for surface flaw detection, dimensional checks, and assembly verification. This technology is widely adopted across electronics and automotive manufacturing for high-speed quality control.
- Laser:Laser-based systems provide high-precision 3D scanning, dimensional metrology, and surface profiling for complex geometries. These systems are essential for intricate parts in electronics and precision engineering.
X-ray and ultrasonic technologies command premium pricing due to their advanced capabilities, while visual inspection offers broad accessibility.
Application:
Digital inspection applications are delineated by their direct impact on product quality, regulatory compliance, and operational safety.
- Quality Control:This application focuses on identifying surface flaws, dimensional inaccuracies, and internal defects to enhance manufacturing yield and reduce scrap rates. AI-powered algorithms provide core technology for advanced image recognition in quality control.
- Compliance Checking:This application generates auditable, repeatable inspection data required by regulatory bodies such as the FDA in the United States and CE marking in the European Union. Medical device manufacturers use these systems extensively for stringent quality verification.
- Safety Inspection:Ensures the structural integrity and operational safety of critical infrastructure, components, and machinery. This application is vital in sectors like aerospace, energy, and transportation to prevent catastrophic failures.
- Maintenance:Utilizes inspection data for predictive analytics, enabling proactive identification of equipment wear, potential failures, and process drift. This shifts maintenance from reactive to preventative strategies.
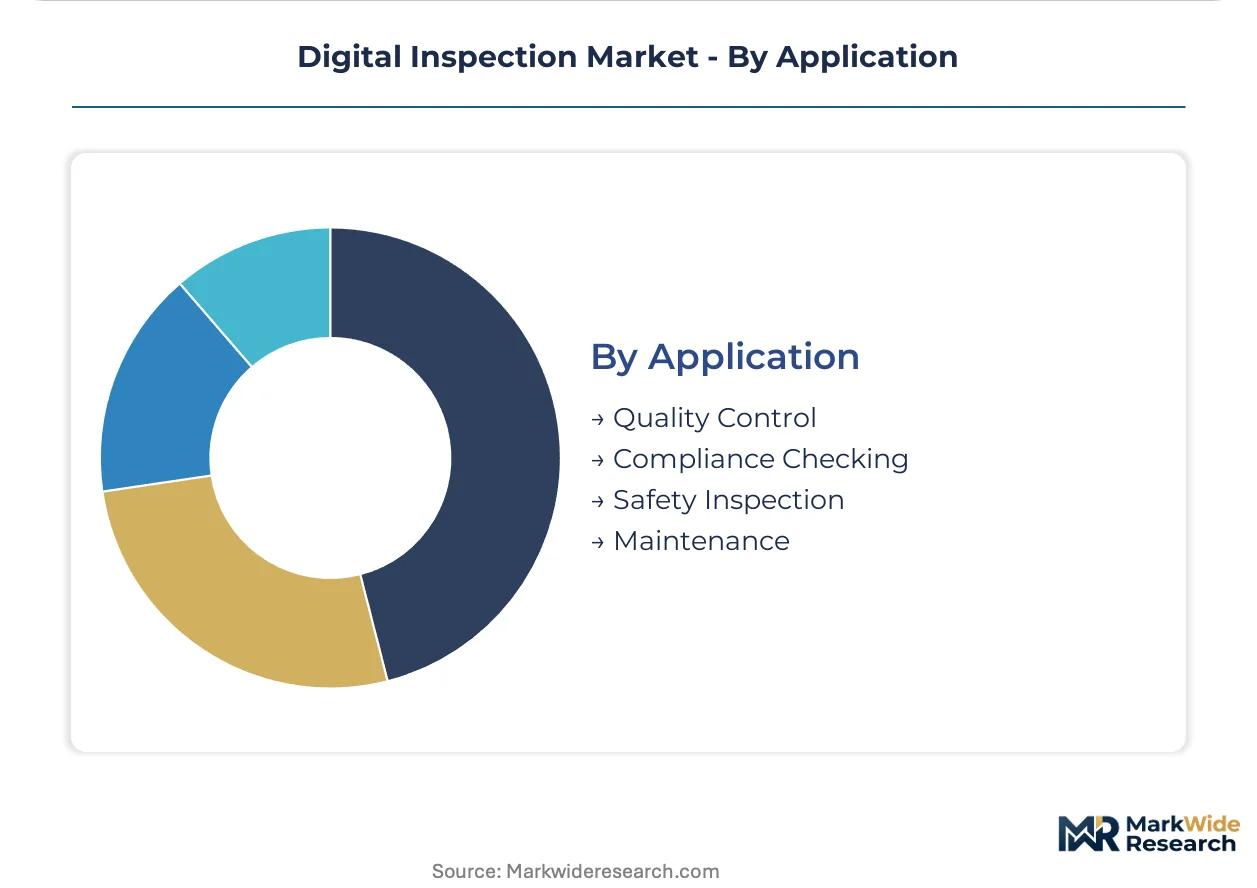
Quality Control represents the foundational application, with Compliance Checking exhibiting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital inspection demand varies significantly across industrial powerhouses, with some nations driving innovation while others focus on high-volume deployment. Germany, for instance, exhibits strong demand for advanced analytics in manufacturing, whereas China prioritizes scalable solutions for its vast electronics and automotive production lines.
United States
The United States aerospace sector drives demand for high-precision X-ray and ultrasonic inspection technologies to verify critical component integrity. Stringent regulations from the FAA necessitate auditable inspection data for every aircraft part. Major aerospace and defense clusters in states like California and Washington heavily invest in these advanced systems.
Germany
German manufacturing, particularly in automotive and industrial machinery, requires micron-level precision for quality control and process optimization. Industry 4.0 initiatives, supported by CE marking requirements, accelerate the integration of digital inspection into production lines. Industrial hubs in Bavaria and North Rhine-Westphalia are centers for advanced metrology adoption.
China
China's extensive electronics and automotive manufacturing bases fuel demand for high-volume visual inspection and AI-powered defect classification. GB standards enforce strict quality verification across numerous product categories. The Yangtze River Delta region, including Shanghai and Jiangsu, leads in the deployment of automated quality control systems.
South Korea
South Korea's advanced electronics and automotive industries are early adopters of digital inspection for surface flaw detection and dimensional accuracy. Government programs supporting smart factory initiatives encourage the integration of connected inspection devices. Technology manufacturing clusters in Gyeonggi Province are actively deploying AI-driven analytics for quality assurance.
Japan
Japan's precision engineering and robotics sectors demand highly accurate laser and visual inspection systems for complex geometries. JIS standards ensure rigorous quality control for both domestic and export markets. Industrial zones around Tokyo and Nagoya are key areas for research and implementation of next-generation inspection technologies.
Digital Inspection Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the digital inspection market, creating a varied competitive structure. The market exhibits a tiered landscape, with established providers offering comprehensive solutions alongside agile innovators targeting niche applications. Companies frequently engage in strategic partnerships to expand their technology portfolios and geographic reach.
Among leading technology providers, Zeiss Group exemplifies high-precision metrology and microscopy systems for demanding applications. Cognex Corporation occupies a position as a specialist in machine vision for factory automation, leveraging its expertise in image processing. Hexagon AB represents a broad portfolio provider, offering sensor, software, and autonomous solutions for industrial measurement across various verticals.
| Leading Market Players |
|---|
| Teledyne Technologies |
| Zeiss Group |
| Cognex Corporation |
| FLIR Systems |
| National Instruments |
| Keyence Corporation |
| Omron Corporation |
| KLA Corporation |
| Hexagon AB |
| Others |
Cost & Logistics Intelligence
Data science talent concentrations in regions like Germany and South Korea influence pricing for advanced software, creating tiered offerings linked to labor-cost differentials for AI-powered analytics and service contracts.
Pricing Analysis
Capacity additions in manufacturing hubs like China are reshaping price floors for standardized visual inspection hardware. The dominant pricing model for integrated solutions often combines project-based implementation with subscription-based software and services. Price differentiation drivers include technology sophistication, such as X-ray versus visual systems, and specific regulatory certification levels like FDA compliance. Pricing pressure stems from component supply concentration for hardware, while software and services experience upward pressure due to the data science talent gap. Small and medium-sized enterprises (SMEs) represent the most price-sensitive buyers, contrasting with aerospace and medical device manufacturers who prioritize precision over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for high-performance sensors and X-ray tubes. Geographic supply concentration for critical inputs is notable in China for electronics components, Germany for precision engineering, and South Korea for advanced sensors. Raw material dependencies include rare earth elements for certain sensor technologies and specialized glass for optical systems. A structural supply chain risk is the concentrated supply chain for critical components, which creates potential bottlenecks and price volatility. Distribution for complex integrated solutions typically runs through direct sales channels, while standardized hardware often leverages channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital inspection market presents a late-cycle quality story, driven by a demand-shift toward premium specifications for auditable, repeatable inspection data.
For Market Incumbents: Anchor long-term growth by investing heavily in AI talent acquisition and retention programs. Expand multi-modal platform offerings to address complex quality control needs, mitigating the threat from agile software specialists. Prioritize R&D in predictive analytics to integrate quality data directly into production line controls. Pursue strategic partnerships for specialized hardware components to reduce supply chain vulnerabilities.
For New Entrants and Emerging Players: Small and medium-sized enterprises (SMEs) represent an underserved buyer archetype, offering significant market penetration opportunities. Target cost-effective, scalable inspection solutions for general manufacturing applications, particularly in regions with growing industrial bases. A compelling go-to-market angle involves flexible, subscription-based Inspection-as-a-Service models, reducing upfront capital outlay for manufacturers. Focus on niche applications like construction monitoring with drone-based visual inspection.
For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-centric firms with limited software integration capabilities. The market offers long-term viability, driven by persistent regulatory mandates and the global adoption of Industry 4.0 principles. Identify acquisition targets among software-centric firms specializing in AI-powered analytics or those with proprietary sensor technologies. The successful integration of AI-powered analytics into production line controls across diverse sectors is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Talent Development | Addresses the data science talent gap for advanced analytical software deployment. |
| Integrated Platform Expansion | Combines diverse inspection technologies to meet complex quality control needs. |
| Subscription Model Adoption | Lowers upfront capital outlay for manufacturers, expanding market access. |
| Certification Standard Pursuit | Ensures compliance with stringent regulations like FDA and CE marking requirements. |
| Component Supply Diversification | Reduces vulnerability to concentrated supply chain risks for critical hardware. |
Research Approach
Direct dialogue with manufacturing quality managers, R&D engineers, procurement specialists, and regulatory compliance officers provided qualitative grounding. This primary research was complemented by secondary validation from industry association reports, patent databases, government regulatory filings, and academic research. Bottom-up market sizing was performed by analyzing product type and end-user segments, with top-down validation against macroeconomic indicators and global manufacturing output trends.
The quantitative model generated granular forecasts for the digital inspection market across the analysis window. This framework integrated demand-side analysis, supply-side capacity assessments, and technological penetration rates. Segmentation dimensions modeled included product type, end-user, technology, application, and regional adoption patterns. Compound annual growth rates were derived through regression analysis and market penetration rate projections, with Industry 4.0 adoption rates and regulatory enforcement trends as key inputs.
Underlying measurement precision varies by segment; aerospace and medical device applications carry tighter precision than others. Forecasts reflect assumptions regarding technological advancements and market dynamics. Global economic slowdowns, rapid technological obsolescence, and geopolitical trade restrictions represent specific risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Calibration Management Software Market