
 Global Nondestructive Testing Equipment Market | 2026-2036
Global Nondestructive Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nondestructive Testing Equipment Market Intelligence
The EU AI Act is rebalancing the cost-of-entry calculus for automated defect-recognition systems in European inspection workflows. Olympus Corporation leverages its transducer manufacturing scale to dominate high-frequency ultrasonic probes for aerospace turbine blades. Baker Hughes anchors its position through backward integration into digital radiography detectors for pipeline corrosion mapping. Waygate Technologies specializes in computed tomography systems that compete on throughput speed for electronics manufacturing quality gates.
Nondestructive Testing Equipment comprises instrumentation that evaluates material integrity, discontinuities, and structural properties without impairing serviceability, typically operating across frequency ranges from kilohertz ultrasonic to megaelectronvolt gamma radiography with resolution thresholds measured in micrometers. Its primary industrial purpose is to certify safety-critical components in operational environments where failure carries catastrophic liability. Ultrasonic Testing commands the largest revenue pool due to its versatility across metal thicknesses and established operator certification frameworks, while Phased Array technology displaces conventional radiography in weld inspection by delivering real-time volumetric data without ionizing radiation hazards. Digital Radiography segments capture expanding margin pools as flat-panel detector costs decline and power generation utilities retire film-based systems.
The American Society of Mechanical Engineers (ASME) inspection codes, European Pressure Equipment Directive (PED), and ISO 9712 personnel certification standards collectively dictate equipment specifications and operator competency requirements across major procurement channels. Japan's Ministry of Economy, Trade and Industry (METI) reinforces domestic demand through mandatory seismic reassessment protocols for nuclear and chemical infrastructure. Stakeholders must monitor how regulatory convergence between EMA machinery safety requirements and FAA airworthiness directives reshapes cross-border equipment qualification pathways.
Market Dynamics
The transition from film-based radiography to digital detector arrays is compressing inspection cycle times while elevating data archival requirements, forcing equipment vendors to reconfigure service revenue models around software licensing rather than hardware replacement.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must deploy automated defect-recognition systems for safety-critical welds, creating immediate procurement pull for integrated hardware-software platforms.
- Aerospace turbine blade inspection:Airframe integrity programs at precision manufacturing clusters in Germany and Japan sustain elevated order volumes for high-frequency ultrasonic phased array systems.
- Nuclear refurbishment protocols:Japan's METI-mandated seismic reassessment drives replacement of obsolete eddy current and ultrasonic equipment across aging reactor fleets.
Market Restraints
- Scandium oxide supply concentration:Flat-panel detector manufacturing depends on rare-earth phosphor substrates sourced primarily from Chinese processing facilities, exposing margins to export control volatility.
- ISO 9712 certification bottlenecks:Personnel qualification timelines stretch 18-24 months in jurisdictions with limited accredited training bodies, throttling deployment velocity for advanced techniques.
- Radiographic film substitution inertia:Power generation utilities in regulated markets face capital committee resistance to retiring fully depreciated film processors despite total-cost advantages of digital systems.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Domestic content requirements for aerospace and defense contractors create localized assembly opportunities for ultrasonic and radiography equipment providers.
- Additive manufacturing quality gates:In-process computed tomography inspection for metal powder-bed fusion parts opens new attach-rate potential for real-time volumetric analysis systems.
- CSRD-aligned predictive maintenance:European industrial asset operators must document structural integrity monitoring under corporate sustainability reporting rules, expanding recurring revenue for connected NDT sensor networks.
Industry Challenges
- Phased array data interpretation expertise:The shift from 2D radiographic film reading to 3D ultrasonic imaging demands retraining of certified inspectors, stretching workforce transition timelines.
- Legacy system integration friction:Digital radiography retrofit projects face mechanical incompatibility with existing pipeline crawler platforms and exposure vault geometries, complicating upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nondestructive Testing Equipment Market |
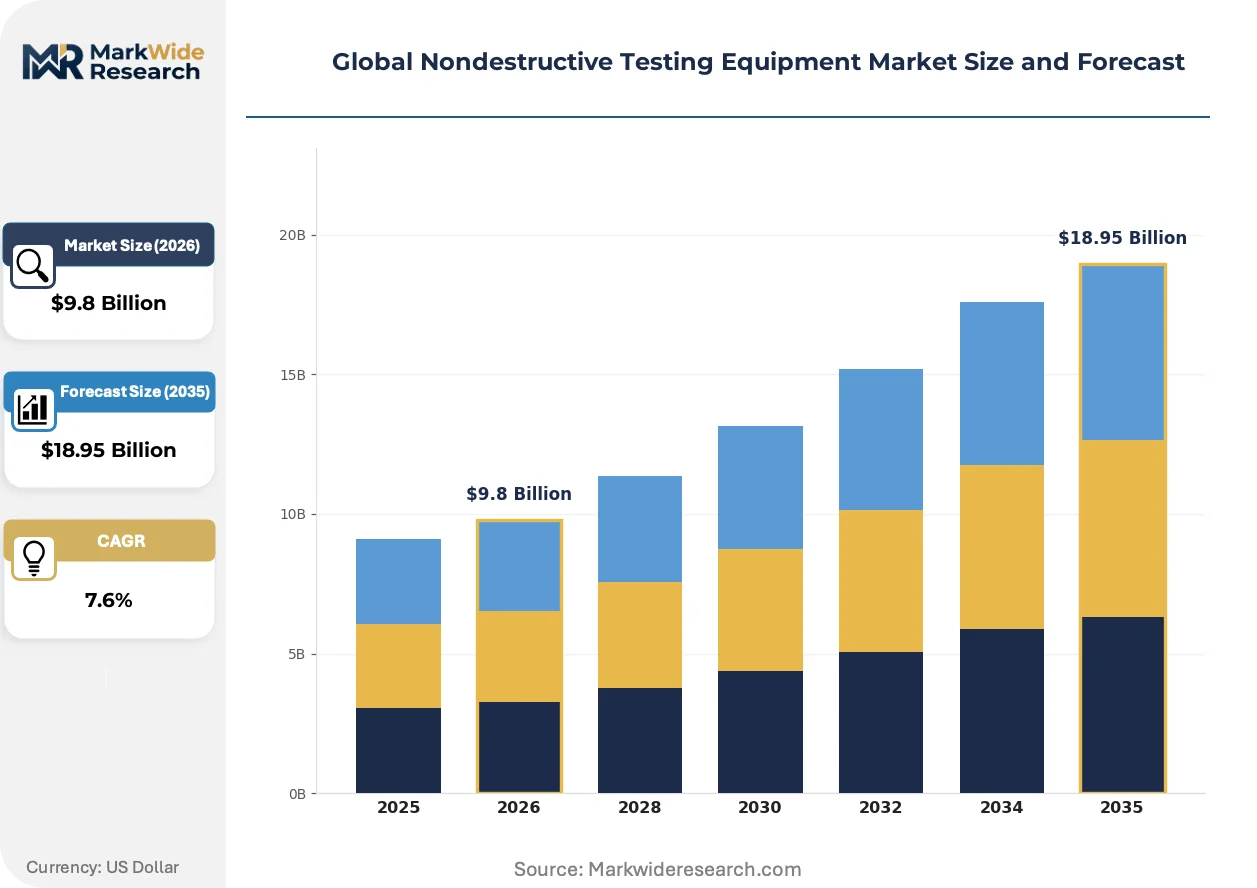
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Eddy Current Testing, Visual Inspection, Acoustic Emission Testing Technology: Phased Array, Digital Radiography, Computed Tomography, Time-of-Flight Diffraction, Laser Shearography, Thermography Application: Aerospace, Petrochemical Plants, Power Generation, Construction, Marine Structures, Electronics Manufacturing End User: Oil & Gas Operators, Aerospace Manufacturers, Power Utilities, Shipyards, Electronics Fabricators, Civil Engineering Firms |
| Companies Covered | Olympus Corporation, Baker Hughes, YXLON International GmbH, Mistras Group, Nikon Metrology, Waygate Technologies, GE Inspection Technologies, Eddyfi Technologies, Zetec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nondestructive Testing Equipment Market Strategic Shifts & Innovations
Artificial intelligence inference at the inspection point is collapsing the latency between data acquisition and defect classification, compressing decision cycles from hours to seconds while generating new liability frameworks for automated certification.
Machine learning defect classification algorithms trained on aerospace turbine blade datasets are automating the triage of ultrasonic A-scan signals, reducing operator interpretation burden in high-throughput manufacturing environments. Tier-1 suppliers at precision clusters in Germany and Japan deploy these systems for 100% inspection coverage of safety-critical rotating components. The technology is automating the shift from sampling-based quality control to zero-defect process validation, elevating capital intensity but collapsing scrap rates.
The EU AI Act's risk-classification framework for safety-critical industrial applications imposes documentation and human-oversight requirements on automated NDT systems deployed in pressure equipment manufacturing. European notified bodies are revising conformity assessment procedures to address algorithmic transparency in defect-recognition software. Phased array ultrasonic equipment with embedded AI inference engines faces extended qualification timelines as manufacturers establish audit trails for training data provenance and model versioning.
Asset operators in North American oil and gas midstream segments are unbundling inspection hardware ownership from analytical service contracts, preferring per-mile pipeline assessment fees over capital equipment purchases. This consumption-pattern shift favors vendors with captive crews of certified technicians and mobile radiography units. The model is concentrating procurement authority with integrity management departments rather than maintenance capital committees, shortening sales cycles but compressing hardware margins in favor of recurring service revenue.
Global Nondestructive Testing Equipment Market Segmentation
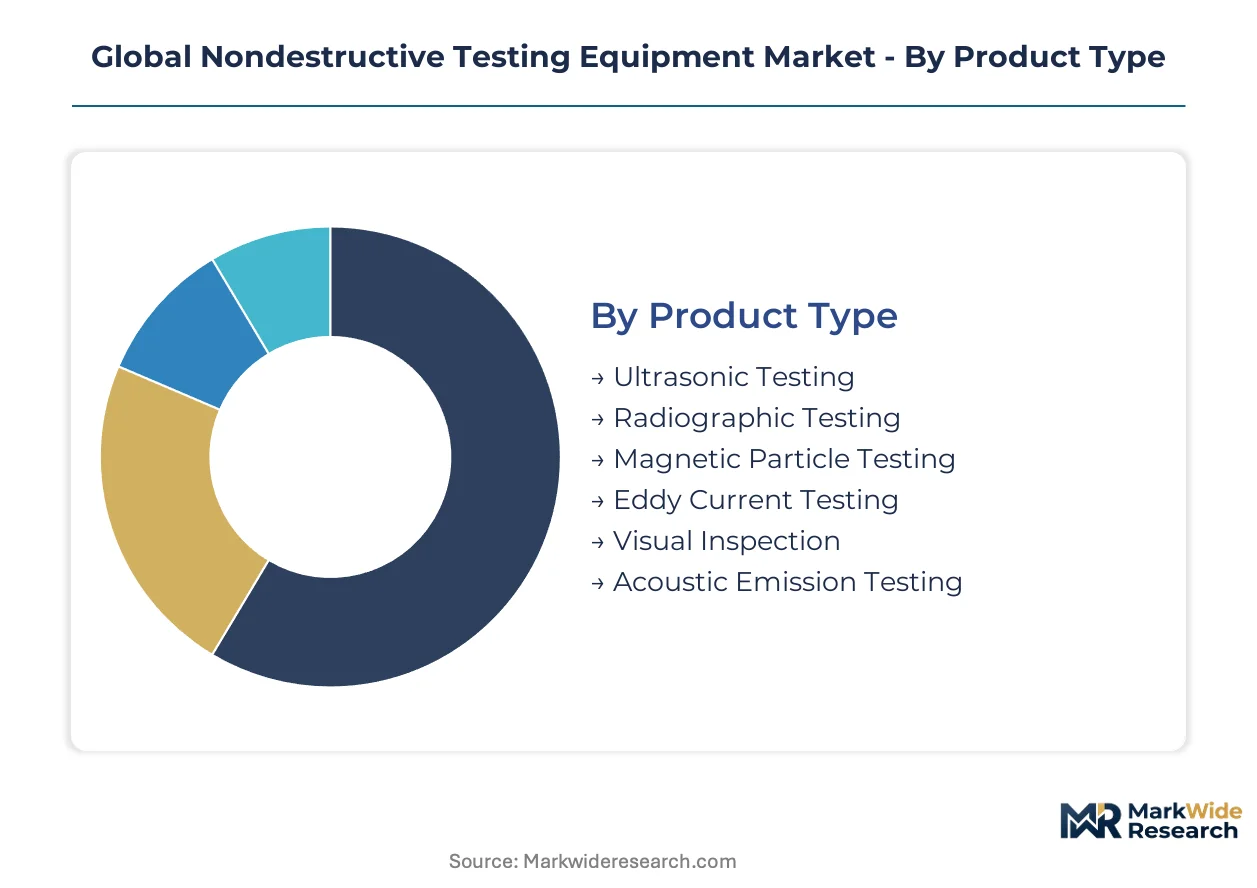
Equipment specifications diverge sharply across inspection regimes, with aerospace turbine blade protocols demanding micrometer-resolution ultrasonic systems while pipeline corrosion surveys prioritize portable digital radiography units. Certification requirements from ASME, ISO 9712, and EU AI Act risk classifications segment procurement channels by compliance burden rather than hardware cost alone.
Product Type:
ISO 9712 personnel certification frameworks and ASME code compliance dictate operator qualification depth for each technique, with ultrasonic and radiographic methods requiring the most extensive training pipelines.
- Ultrasonic Testing:High-frequency piezoelectric transducers generate mechanical waves to detect internal discontinuities across metal thicknesses from millimeters to meters. German precision manufacturing clusters and Japanese nuclear refurbishment programs sustain dominant order volumes for phased-array-capable units.
- Radiographic Testing:Ionizing radiation penetrates dense materials to reveal volumetric defects on digital detector arrays or film. Power generation utilities in regulated markets drive substitution from analog film to flat-panel systems despite capital committee resistance.
- Magnetic Particle Testing:Surface-breaking defect detection for ferromagnetic components through magnetic field disturbance visualization.
- Eddy Current Testing:Electromagnetic induction identifies conductivity variations in conductive materials without surface preparation.
- Visual Inspection:Direct optical examination augmented by borescope and remote camera systems for accessible surfaces.
- Acoustic Emission Testing:Passive monitoring of stress-wave emissions from active crack propagation in pressure vessels.
Ultrasonic Testing sits at the top of the volume ranking, with Digital Radiography climbing the fastest.
Technology:
Capital intensity stratifies sharply, with computed tomography systems commanding premium pricing for electronics manufacturing quality gates while thermography offers lower entry thresholds for building envelope surveys.
- Phased Array:Electronically steered ultrasonic beams deliver real-time volumetric imaging without ionizing radiation hazards. Aerospace manufacturers in Germany and Japan deploy these systems for 100% coverage of safety-critical rotating components.
- Digital Radiography:Amorphous silicon flat-panel detectors capture radiographic images with immediate digital archival. Pipeline integrity management departments in North American oil and gas midstream segments favor per-mile service contracts over hardware ownership.
- Computed Tomography:X-ray rotational scanning reconstructs three-dimensional internal geometries for additive manufacturing validation.
- Time-of-Flight Diffraction:Ultrasonic diffraction timing precisely measures crack height in welded structures.
- Laser Shearography:Laser interferometry detects surface strain anomalies indicating subsurface delamination.
- Thermography:Infrared imaging maps thermal patterns to identify insulation defects or electrical hot spots.
Phased Array captures the steepest expansion trajectory as weld inspection displaces conventional radiography.
Application:
End-use liability exposure determines equipment specification rigor, with aerospace and nuclear applications mandating redundant inspection modalities while construction tolerates single-technique verification.
- Aerospace:Airframe integrity programs combine ultrasonic, radiographic, and penetrant methods for turbine blade and structural component certification. FAA airworthiness directives and EASA regulations enforce multi-modal inspection protocols.
- Petrochemical Plants:Pressure vessel and piping inspection under ASME and PED mandates drives recurring demand for automated ultrasonic corrosion mapping systems.
- Power Generation:METI-mandated seismic reassessment in Japan and nuclear refurbishment across multiple jurisdictions sustain eddy current and ultrasonic equipment replacement cycles.
- Construction:Structural steel weld verification and concrete integrity assessment utilize portable ultrasonic and ground-penetrating radar systems.
- Marine Structures:Hull thickness monitoring and offshore platform inspection require diver-deployable or remotely operated underwater ultrasonic equipment.
- Electronics Manufacturing:Solder joint and semiconductor package validation employs high-resolution X-ray and computed tomography systems.
Aerospace commands premium pricing tiers, with Electronics Manufacturing gaining share fastest on additive manufacturing quality gate expansion.
End User:
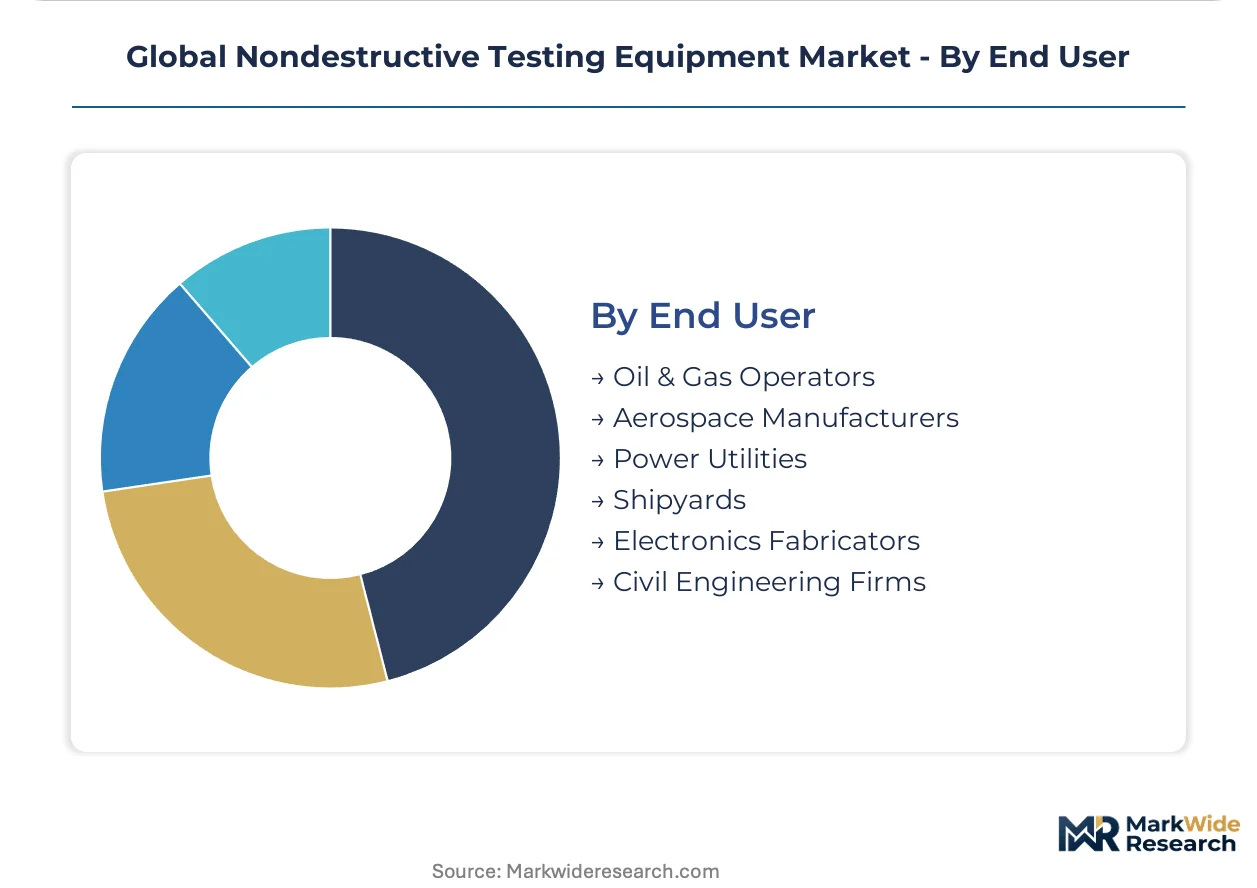
Procurement authority concentration varies by sector, with oil and gas integrity management departments consolidating vendor relationships while aerospace OEMs fragment purchases across specialized technique suppliers.
- Oil & Gas Operators:Pipeline corrosion assessment and refinery turnaround inspection drive demand for mobile radiography and automated ultrasonic crawler systems. Unbundling of hardware ownership from analytical services reshapes vendor relationships toward recurring revenue models.
- Aerospace Manufacturers:Precision manufacturing clusters in Germany and Japan sustain elevated order volumes for high-frequency ultrasonic phased array systems with embedded AI inference engines.
- Power Utilities:Generation asset life extension and nuclear license renewal programs mandate eddy current steam generator inspection and ultrasonic reactor vessel monitoring.
- Shipyards:New construction classification surveys and in-service hull inspections require portable magnetic particle and ultrasonic thickness gauges.
- Electronics Fabricators:Miniaturized component inspection and failure analysis laboratories utilize benchtop X-ray and computed tomography systems.
- Civil Engineering Firms:Bridge structural health monitoring and tunnel lining assessment deploy ground-penetrating radar and impact-echo equipment.
Aerospace Manufacturers anchor the highest-value procurement segment, with Electronics Fabricators expanding most quickly on CSRD-aligned predictive maintenance documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nondestructive testing equipment traces its industrial lineage to post-war German precision engineering and Japanese nuclear safety protocols, with both nations establishing foundational inspection standards that migrated into ASME codes and EU directives. Equipment demand now clusters where aerospace manufacturing, nuclear infrastructure, and petrochemical processing intersect.
United States
FAA airworthiness directives and pipeline safety mandates from PHMSA sustain procurement of ultrasonic and radiographic systems across aerospace clusters in Seattle and Houston. The IRA's clean energy provisions accelerate inspection equipment orders for offshore wind foundation welding. Oklahoma's oil and gas midstream operators favor per-mile service contracts over hardware ownership.
Germany
Precision manufacturing clusters in Bavaria and Baden-Württemberg deploy phased array systems for 100% turbine blade coverage under EASA regulations. The EU AI Act's risk-classification framework extends qualification timelines for automated defect-recognition platforms. Munich-area aerospace suppliers integrate embedded AI inference engines into existing ultrasonic workflows.
Japan
METI-mandated seismic reassessment protocols drive replacement of obsolete eddy current equipment across reactor fleets in Fukui and Niigata prefectures. JIS standards enforcement sustains domestic demand for high-frequency transducer manufacturing. Nagoya's aerospace precision cluster anchors regional orders for automated corrosion mapping systems.
China
GB standards alignment with ISO 9712 frameworks expands certified inspector training capacity for petrochemical construction in Jiangsu and Zhejiang provinces. MIIT industrial upgrading directives prioritize domestic digital radiography detector production. Shanghai's LNG terminal expansion projects import phased array systems for cryogenic weld verification.
India
PLI scheme domestic content requirements for aerospace contractors localize assembly opportunities in Karnataka and Tamil Nadu manufacturing corridors. CEA nuclear liability protocols mandate redundant inspection modalities for reactor pressure vessels. Gujarat's specialty chemicals complexes adopt portable ultrasonic thickness gauges under state industrial safety mandates.
Global Nondestructive Testing Equipment Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive sensor manufacturing capabilities. Consolidation pressure concentrates procurement authority with oil and gas integrity management departments and aerospace OEM supply chain offices. Two strategic archetypes dominate: transducer-scale specialists leveraging piezoelectric manufacturing depth, and integrated service providers unbundling hardware ownership from analytical contracts. Competitive moves center on backward integration into detector substrate supply and software licensing revenue model migration.
Among diversified technology conglomerates, Olympus Corporation and Baker Hughes occupy positions that exemplify scale-driven sensor manufacturing and integrated digital platform deployment respectively. YXLON International GmbH represents the European precision-engineering archetype with heritage radiography expertise. Waygate Technologies anchors the computed tomography specialization vector for electronics manufacturing quality gates. These three named entities collectively illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Olympus Corporation |
| Baker Hughes |
| YXLON International GmbH |
| Mistras Group |
| Nikon Metrology |
| Waygate Technologies |
| GE Inspection Technologies |
| Eddyfi Technologies |
| Zetec |
| Others |
Cost & Logistics Intelligence
The EU AI Act's risk-classification framework for safety-critical industrial applications gates qualified supply access to European aerospace and pressure equipment manufacturers, while simultaneously stratifying pricing tiers around algorithmic transparency documentation and human-oversight compliance burdens. Premium-tier equipment vendors capture margin pools through bundled software licensing and audit-trail capabilities that economy-tier competitors cannot replicate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement channels by certification depth and after-sales service bundling. Price differentiation centers on ISO 9712 operator training inclusion and embedded AI inference engine qualification status. Cost compression in standard-tier ultrasonic systems is intensifying because Chinese manufacturers are expanding amorphous silicon flat-panel detector production. Power generation utilities in regulated markets exhibit highest price sensitivity due to capital committee resistance, while aerospace OEMs in Germany and Japan demonstrate lowest sensitivity for zero-defect validation requirements.
Supply Chain Analysis
Dual-sourcing mandates from Japan's METI and the EU AI Act's conformity assessment procedures require aerospace manufacturers to qualify redundant transducer and detector substrate suppliers. Manufacturing concentration centers on Japan for high-frequency piezoelectric ceramics, China for rare-earth phosphor processing, and Germany for precision-engineered phased array systems. Raw material dependencies include scandium oxide for flat-panel detectors, lithium niobate for ultrasonic transducers, and specialized optical glass for radiography tubes. Single-source vulnerability in Chinese rare-earth processing exposes margins to export control volatility. Distribution runs through authorized service networks with captive technician certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU AI Act's automated defect-recognition mandates create sustained procurement pull for integrated hardware-software platforms across European manufacturing.
For Market Incumbents: Anticipate displacement risk from Chinese digital radiography detector manufacturers expanding into phased array system assembly. Backward integration into scandium oxide phosphor substrate supply and captive AI training dataset development defend margin position against modular software entrants. Certification investment in EU notified body partnerships extends qualification timelines that new competitors cannot compress. For New Entrants and Emerging Players: The mid-tier pricing gap between Olympus Corporation's premium aerospace systems and economy-grade portable thickness gauges opens white-space targeting. India's PLI scheme domestic content requirements for aerospace contractors present the most penetrable geography. Portable ultrasonic corrosion mapping systems for Gujarat's specialty chemicals complexes offer a service-led go-to-market angle that bypasses capital committee resistance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service providers with captive ISO 9712 training capacity and mobile radiography fleets. Long-term viability over a five-to-ten year window favors asset-light inspection service models over hardware manufacturers facing detector cost commoditization. Watch for inflection in Japan's nuclear license renewal timelines as a signal for eddy current equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrates | Captive scandium oxide supply insulates margins from Chinese export control volatility. |
| AI Inference Engine Certification Investment | EU notified body partnerships extend qualification barriers against modular software competitors. |
| Per-Mile Service Contract Expansion | Oklahoma pipeline operators prefer consumption models over hardware ownership. |
| India PLI Scheme Localization | Karnataka aerospace corridors create domestic assembly opportunities for ultrasonic systems. |
| Additive Manufacturing CT Validation Partnerships | Electronics fabricators require real-time volumetric analysis for metal powder-bed fusion quality gates. |
Research Approach
Bottom-up aerospace and power utility demand modeling reconciled against top-down transducer and detector manufacturing capacity tracking forms the analytical core of this study. Primary interviews with NDT equipment procurement managers, ISO 9712 certification body directors, plant maintenance engineers at petrochemical facilities, and integrity management officers at oil and gas midstream operators combined with secondary validation from ASME code filings, EMA machinery safety directives, METI seismic reassessment protocols, and customs trade data for ultrasonic transducer imports.
Historical trendline analysis of equipment replacement cycles across Japanese nuclear refurbishment programs and German precision manufacturing clusters established baseline demand patterns. Segmentation modeling incorporated product type, technology tier, application liability exposure, and end-user procurement authority concentration. CAGRs were derived from regression analysis of capital expenditure trajectories and regulatory mandate implementation timelines. Forecast inputs included EU AI Act conformity assessment procedure rollout schedules and India's PLI scheme domestic content phase-in requirements.
The model assumes a particular technology adoption path; alternative pathways for film-to-digital radiography substitution would alter the outlook if power generation utilities accelerate retirement timelines or resist capital committee approvals. Forecasts reflect assumptions around METI-mandated seismic reassessment completion rates and EASA airworthiness directive enforcement intensity. Deviation in Chinese rare-earth export control severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Signal Generator Market
Test and Measurement
Calibration Services Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Dosimeter Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Test Benches Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Digital Thickness Gauge Market