
 Volte Testing Market | 2026-2036
Volte Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Volte Testing Market Analytics
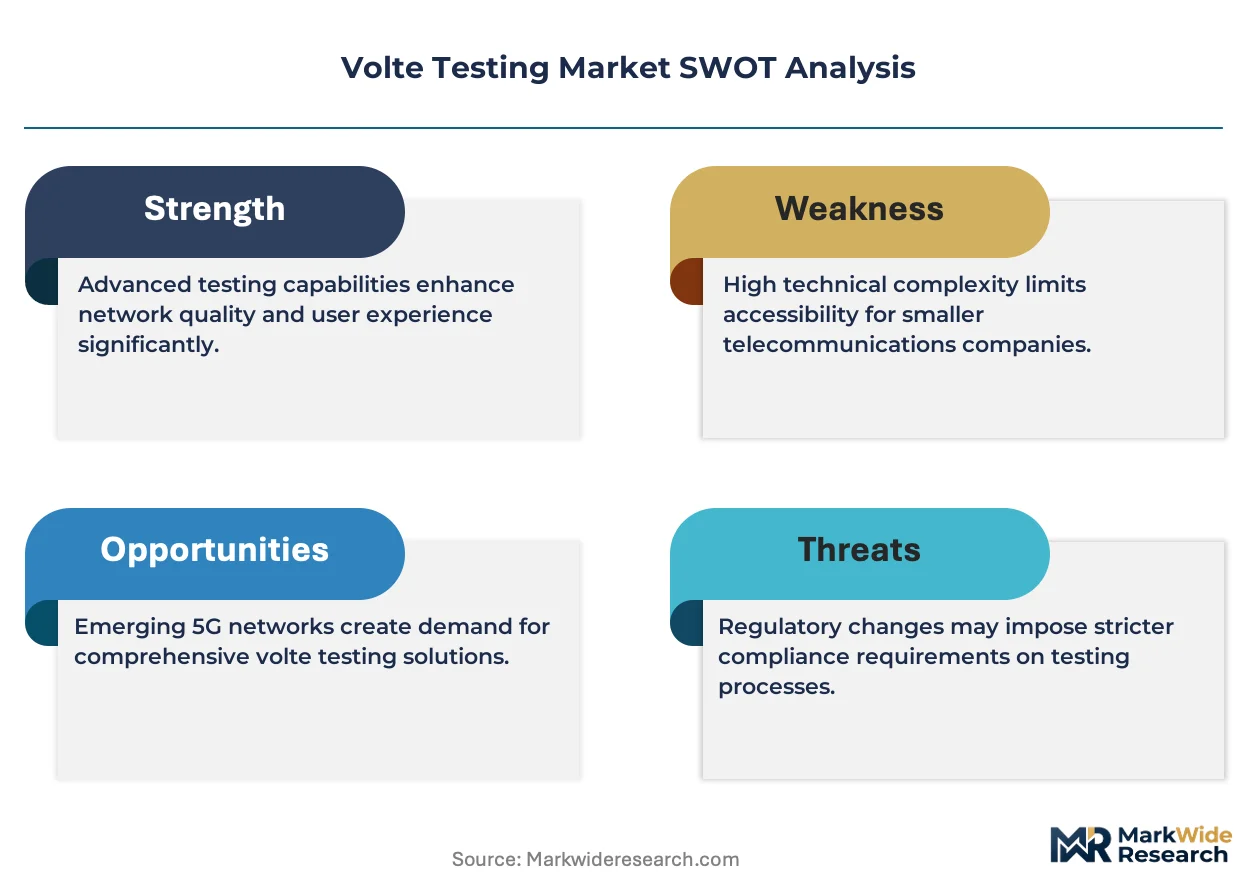
Software-defined test architectures are restructuring capital allocation across the VoLTE testing value chain, displacing legacy hardware-heavy setups with programmable instrumentation. Keysight Technologies leverages its PXI modular platform to sustain R&D intensity in 5G-VoLTE convergence. Rohde & Schwarz GmbH & Co KG anchors European calibration standards through its vector signal generator portfolio. Viavi Solutions differentiates via cloud-native analytics layers that compress troubleshooting cycles for tier-one carriers.
VoLTE testing encompasses protocol validation, voice quality assessment, and network interoperability verification across IMS core and radio access interfaces, employing metrics such as MOS scores, jitter buffers, and packet loss thresholds below one percent to guarantee toll-grade voice over LTE bearers. Test equipment and software solutions together command the dominant share of spending, though cloud-based deployment models represent the fastest-expanding configuration as operators virtualize test labs and shift OpEx profiles. Monitoring solutions concentrate margin pools where real-time analytics integrate with subscriber experience management platforms.
The Federal Communications Commission in the United States mandates E911 location accuracy and voice service reliability benchmarks that directly shape VoLTE test scope, while India's Telecom Engineering Centre issues network performance standards that operators must certify against through accredited testing labs. Stakeholders must weigh capital intensity against automation depth when selecting between on-premise validation stacks and elastic cloud testbeds as network slicing complicates interoperability matrices.
Market Dynamics
Software-defined instrumentation is collapsing test lab capital cycles as operators virtualize VoLTE validation stacks, forcing equipment vendors to pivot from hardware margins toward recurring software licenses and cloud-native analytics subscriptions.
Growth Catalysts
- India's Telecom Engineering Centre mandates:Accredited testing lab certification for voice quality benchmarks creates compulsory demand for protocol analyzers and IMS core simulators among Bharti Airtel, Reliance Jio, and Vodafone Idea.
- 5G-VoLTE interworking:Network slicing architectures require new interoperability test matrices between legacy LTE voice bearers and 5G NR radio access, expanding test scope for equipment vendors.
- South Korea's cloud migration:Samsung Electronics and LG Uplus drive disproportionate investment in elastic testbed deployment models, compressing validation cycle times from weeks to days.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in SIP protocol stacks and IMS signaling analysis concentrates among legacy telecom equipment veterans, constraining vendor R&D scaling.
- Radio frequency component volatility:Gallium nitride and silicon germanium substrate costs fluctuate with defense and aerospace demand, pressuring vector signal generator margins.
- Legacy hardware depreciation traps:Operators face stranded asset risk from PXI chassis and proprietary probe hardware as virtualization accelerates, dampening refresh cycles.
Strategic Opportunities
- Indonesia's VoLTE rollout lag:Southeast Asia's largest mobile market shows sub-40% VoLTE penetration, creating greenfield demand for turnkey validation solutions as Telkomsel accelerates migration.
- FCC E911 location accuracy mandates:Tightening emergency call positioning requirements in the United States expand test scope to include hybrid GPS-OTDOA validation suites.
- AI-driven anomaly detection:Machine learning models trained on packet capture datasets are converging with real-time monitoring platforms, enabling predictive voice quality degradation alerts.
Industry Challenges
- Multi-vendor interoperability matrices:Fragmented IMS core implementations across Nokia, Ericsson, Huawei, and ZTE equipment force test vendors to maintain exhaustive protocol variant libraries, inflating R&D overhead.
- Certification timeline compression:India's Department of Telecommunications quality-of-service mandates require accelerated lab accreditation turnaround, straining testing service provider capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volte Testing Market |
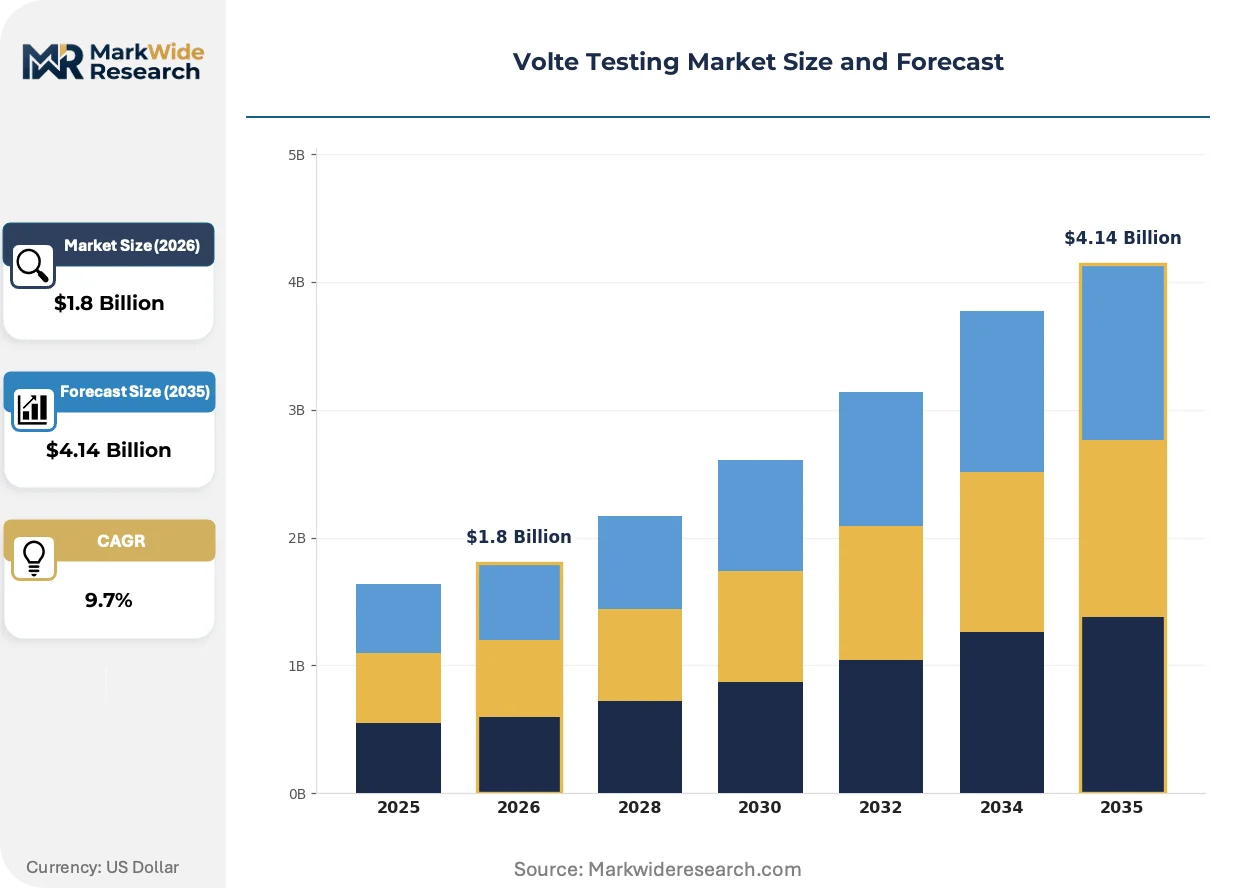
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Equipment, Software Solutions, Validation Tools, Monitoring Solutions End User: Telecom Operators, Service Providers, Device Manufacturers, Testing Labs Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Technology: Packet Switching, Circuit Switching, VoIP, Multimedia Messaging |
| Companies Covered | Rohde & Schwarz GmbH & Co KG, Telefonaktiebolaget LM Ericsson, Keysight Technologies, Viavi Solutions, Anritsu, Spirent Communications, GL Communications, EXFO, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volte Testing Market Evolving Landscape
Containerized test workloads are redistributing competitive advantage from capital-intensive hardware incumbents toward software-native challengers with DevOps-integrated release pipelines.
Cloud-native test orchestration platforms are converging with subscriber experience management systems. Tier-one carriers in Germany and France deploy these stacks to automate regression testing across multi-vendor radio access networks. The shift compresses troubleshooting cycles from days to hours while reducing on-premise lab footprint.
The FCC's voice service reliability benchmarks and India's Telecom Engineering Centre network performance standards are tightening in parallel, forcing test scope expansion into emergency call latency and handover failure rates. Equipment vendors must now certify against divergent national requirements rather than unified global protocols. This fragmentation elevates compliance engineering costs but creates premium pricing power for vendors with accredited multi-country lab networks.
Carrier procurement patterns favor subscription-based test-as-a-service models over perpetual license purchases. European and Asia-Pacific operators particularly drive this shift, preferring OpEx-aligned spending that scales with network slicing deployment velocity. Vendors respond with usage-metered analytics platforms that align pricing to actual test execution volume rather than provisioned capacity.
Volte Testing Market Segmentation
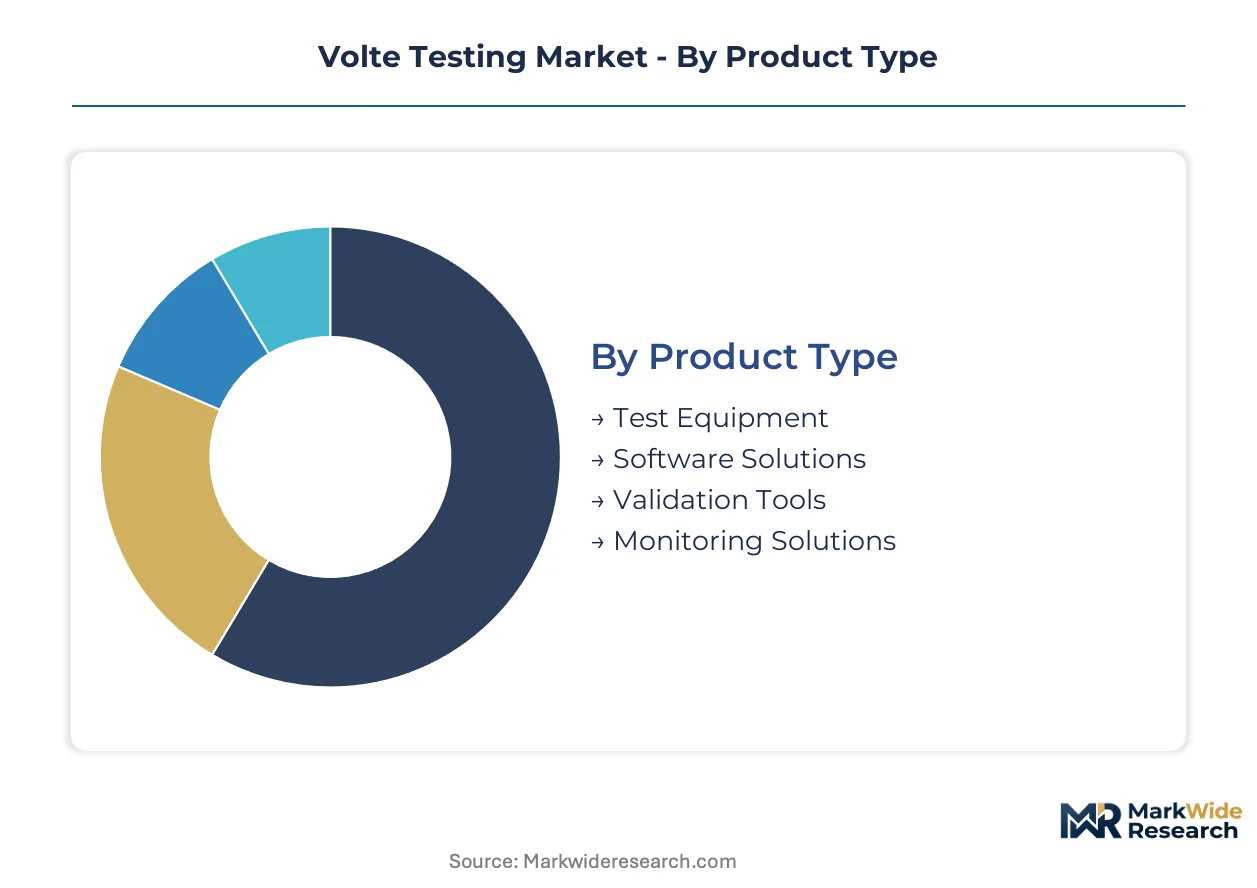
VoLTE testing procurement splits sharply between capital-intensive hardware installations and recurring software subscriptions, with deployment architecture choices now reshaping vendor competitive position. Understanding where volume concentrates versus where margins expand reveals which product configurations operators prioritize as network virtualization accelerates.
Product Type:
Test equipment commands the largest revenue base through PXI modular platforms and vector signal generators, while software solutions capture the steepest expansion trajectory as programmable instrumentation displaces fixed-function hardware.
- Test Equipment:Hardware platforms including protocol analyzers, IMS core simulators, and radio frequency signal generators perform physical layer validation and bearer establishment testing. Demand concentrates among Indian operators facing Telecom Engineering Centre certification mandates, where Bharti Airtel and Reliance Jio maintain extensive on-premise validation labs.
- Software Solutions:Programmable test stacks enable virtualized protocol validation, voice quality assessment algorithms, and automated regression suites through license-based delivery. South Korean operators at Samsung Electronics and LG Uplus drive disproportionate investment here as elastic testbed deployment compresses validation cycles from weeks to days.
- Validation Tools:Specialized suites for SIP signaling analysis, MOS scoring, and jitter buffer optimization target interoperability verification across multi-vendor IMS cores.
- Monitoring Solutions:Real-time analytics platforms integrate with subscriber experience management systems to deliver predictive voice quality degradation alerts.
Today's leader: Test Equipment. Tomorrow's challenger: Software Solutions.
End User:
Telecom operators absorb the majority of procurement volume through direct equipment purchases, though testing labs are gaining structural importance as national regulators mandate accredited third-party certification.
- Telecom Operators:Tier-one carriers including Bharti Airtel, Reliance Jio, and Vodafone Idea in India deploy comprehensive validation infrastructure to satisfy Department of Telecommunications quality-of-service mandates. These entities require end-to-end testing across radio access, IMS core, and emergency services domains.
- Testing Labs:Accredited facilities perform compulsory certification against Telecom Engineering Centre voice quality benchmarks and FCC E911 location accuracy requirements. India's accelerated lab accreditation timelines strain provider capacity while elevating pricing power for multi-country accredited networks.
- Service Providers:Managed network operators and MVNOs procure targeted validation services rather than full test infrastructure ownership.
- Device Manufacturers:Smartphone and IoT device vendors require pre-certification testing for VoLTE modem integration and audio subsystem validation.
Telecom operators anchor current spending. Testing labs are climbing fastest as regulatory outsourcing deepens.
Deployment Model:
On-premise installations retain entrenched positions in markets with stringent data sovereignty requirements, while cloud-based configurations expand most quickly where operators prioritize OpEx alignment over capital deployment.
- Cloud-Based:Elastic testbed platforms enable usage-metered analytics that scale with network slicing deployment velocity. European and Asia-Pacific operators particularly favor subscription-based test-as-a-service models that reduce stranded asset risk from proprietary probe hardware.
- Hybrid:Mixed architectures combine on-premise core validation with cloud-native analytics layers, allowing gradual virtualization without full hardware displacement.
- On-Premise:Traditional capital-intensive lab configurations persist where regulators mandate physical audit trails or where operators face restricted cloud adoption.
- Managed Services:Outsourced test operations deliver turnkey validation without internal engineering expertise, appealing to mid-tier carriers lacking SIP protocol specialists.
On-premise holds installed base dominance. Cloud-based configurations are gaining share fastest through procurement pattern shifts.
Technology:
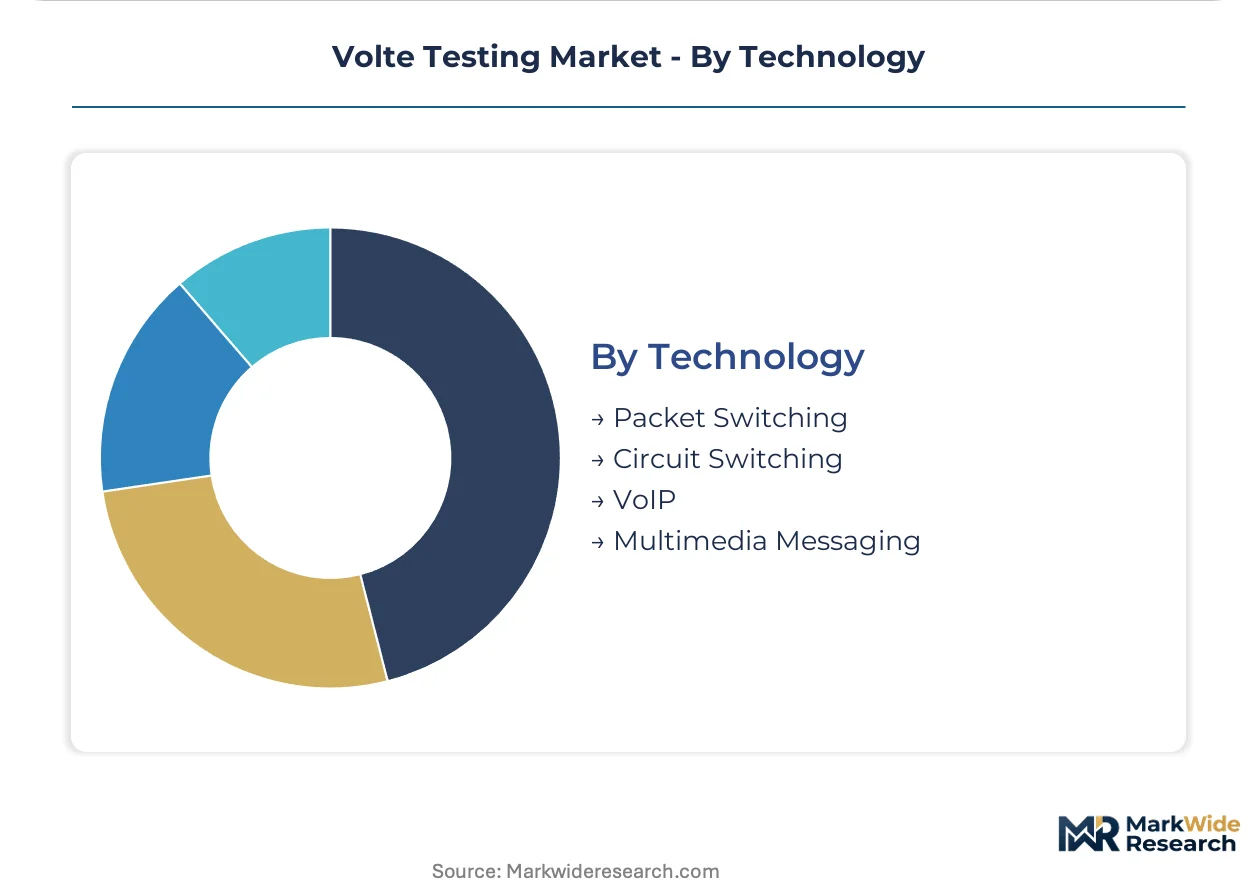
Packet switching foundations enable the dominant VoLTE implementation, while circuit switching legacy requirements persist for interworking verification and fallback scenario testing.
- Packet Switching:IP-based bearer establishment, QoS marking, and IMS registration procedures form the technical core of VoLTE validation. This technology demands testing of SIP signaling flows, RTP media path integrity, and policy and charging control integration across evolved packet core networks.
- VoIP:Underlying voice over IP protocols including codec negotiation, echo cancellation, and silence suppression require dedicated test coverage for toll-grade quality assurance.
- Circuit Switching:Legacy TDM interworking and CSFB (Circuit Switched Fallback) verification maintain relevance for comprehensive network validation.
- Multimedia Messaging:SMS-over-IP and rich communication services testing extends validation scope beyond pure voice bearer analysis.
Packet switching defines current architecture. VoIP specialization is expanding most quickly as codec complexity multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Samsung Electronics' Suwon campus anchors the densest concentration of VoLTE validation infrastructure worldwide, with South Korean operators driving cloud-native testbed adoption that compresses validation cycles from weeks to days.
United States
FCC E911 location accuracy mandates and voice service reliability benchmarks expand test scope to hybrid GPS-OTDOA validation suites. The Federal Communications Commission tightens emergency call positioning requirements annually. Greater Boston hosts concentrated testing lab networks serving tier-one carriers through accredited multi-country certification facilities.
India
Bharti Airtel, Reliance Jio, and Vodafone Idea deploy extensive on-premise validation labs to satisfy Telecom Engineering Centre voice quality benchmarks. The Department of Telecommunications accelerates lab accreditation timelines under tightening quality-of-service mandates. Mumbai and Delhi-NCR concentrate accredited testing capacity where certification demand strains provider throughput.
Germany
Deutsche Telekom and Vodafone Germany drive protocol analyzer procurement for IMS core interoperability verification across multi-vendor radio access networks. CE marking requirements and EU-wide network performance standards shape test equipment specifications. Munich and Stuttgart anchor European calibration standard development through vector signal generator manufacturing clusters.
South Korea
Samsung Electronics and LG Uplus disproportionately invest in elastic cloud testbed deployment models that virtualize validation stacks. The Korea Communications Commission enforces stringent VoLTE quality benchmarks that exceed regional norms. Seoul Capital Area concentrates software-defined instrumentation R&D where programmable platforms displace fixed-function hardware.
Japan
NTT Docomo and KDDI maintain rigorous VoLTE certification programs for device interoperability across evolved packet core networks. METI guidelines on network reliability influence test scope expansion into handover failure rate monitoring. Tokyo and Osaka metro areas host dense concentrations of SIP protocol specialists and IMS signaling analysis expertise.
Volte Testing Market Competitive Landscape
Global majors compete with regional champions across test equipment standardization and cloud-native analytics delivery. The vendor base organizes around three tiers: PXI modular platform specialists, vector signal generator incumbents, and cloud-native analytics challengers. Strategic differentiation concentrates on software licensing transitions, recurring revenue models, and accredited multi-country lab network expansion.
Among German precision instrumentation specialists, Rohde & Schwarz GmbH & Co KG occupies a position exemplifying European calibration standard anchoring. Keysight Technologies and Viavi Solutions represent contrasting archetypes within the software-defined instrumentation transition, with the former anchoring modular hardware platforms and the latter exemplifying cloud-native analytics layer specialization. These three entities collectively illustrate the competitive tension between capital-intensive legacy installations and elastic OpEx-aligned testbed configurations.
| Leading Market Players |
|---|
| Rohde & Schwarz GmbH & Co KG |
| Telefonaktiebolaget LM Ericsson |
| Keysight Technologies |
| Viavi Solutions |
| Anritsu |
| Spirent Communications |
| GL Communications |
| EXFO |
| Nokia |
| Others |
Value Network & Pricing Analysis
SIP protocol specialists and IMS signaling analysts concentrated in Japan's Tokyo-Osaka corridor create labor-cost differentials that widen pricing-tier spreads between premium accredited validation suites and economy-tier monitoring tools. India's Telecom Engineering Centre certification mandates amplify this spread as operators absorb premium pricing for accredited lab networks while mid-tier carriers gravitate toward subscription-based test-as-a-service models.
Pricing Analysis
Input-cost pass-through from gallium nitride and silicon germanium substrate volatility shapes pricing dynamics across vector signal generator portfolios. Subscription-based SaaS-tiered pricing dominates as European and Asia-Pacific operators prefer OpEx-aligned spending that scales with network slicing deployment velocity. Price differentiation rests on certification grade—Telecom Engineering Centre and FCC E911 accreditation command premiums—and volume scale for hyperscale carrier procurement. Pricing pressure stems from cloud-native challengers compressing margins on legacy hardware-heavy setups. Tier-one carriers show lowest price sensitivity given regulatory compliance imperatives, while MVNOs and managed service providers exhibit highest sensitivity and drive demand for usage-metered analytics platforms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Bharti Airtel, Reliance Jio, and Samsung Electronics, while tier-two distribution partners serve testing labs and mid-tier carriers. Geographic supply concentration centers on Germany for vector signal generator manufacturing, South Korea for software-defined instrumentation R&D, and the United States for PXI modular platform assembly. Raw material dependencies include gallium nitride substrates, silicon germanium wafers, and specialized FPGA components. Single-source vulnerability around precision RF components creates supply chain risk given defense and aerospace demand competition. Distribution runs through authorized value-added resellers for enterprise accounts and direct field sales for tier-one carrier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VoLTE testing functions as a regulatory compounder where India's Department of Telecommunications quality-of-service mandates and FCC E911 location accuracy requirements generate recurring compliance-driven demand that expands test scope and compresses certification timelines.
For Market Incumbents: Extend accredited multi-country lab network coverage to capture premium pricing from operators facing divergent national certification requirements. Deepen backward integration into programmable FPGA components to offset gallium nitride cost volatility and defend margins against cloud-native challengers. Lock in long-term subscription contracts with tier-one carriers before virtualization accelerates hardware displacement.
For New Entrants and Emerging Players: Capture Indonesia's sub-40% VoLTE penetration greenfield where Telkomsel's accelerated migration creates turnkey validation demand without entrenched incumbent relationships. Target AI-driven anomaly detection convergence with subscriber experience management platforms as the most penetrable application layer. Lead with DevOps-integrated release pipelines and containerized test workloads to differentiate against legacy hardware vendors.
For Investors and Strategic Acquirers: Telecom equipment manufacturers with IMS core portfolios are the most active acquirer in this space, seeking vertical integration into test and validation capabilities. Long-term viability hinges on software licensing transitions and recurring revenue model maturity rather than perpetual hardware sales. Monitor cloud-native analytics platform adoption rates as the critical inflection indicator for valuation multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Testbed Deployment | South Korean operators at Samsung Electronics compress validation cycles from weeks to days through elastic infrastructure. |
| Multi-Country Lab Accreditation | Testing service providers capture premium pricing from Bharti Airtel and Vodafone Idea under India's accelerated Telecom Engineering Centre timelines. |
| AI-Driven Anomaly Detection Integration | Machine learning models trained on packet capture datasets converge with real-time monitoring platforms for predictive alerts. |
| Backward Integration into Programmable Components | Vector signal generator vendors hedge gallium nitride cost volatility through captive FPGA supply chains. |
| Subscription-Based Test-as-a-Service Launch | European operators align OpEx spending to actual test execution volume rather than provisioned capacity. |
Research Methodology
Bottom-up telecom operator procurement modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with network engineering directors, testing lab accreditation officers, IMS core procurement leads, and SIP protocol specialists were cross-validated against secondary sources including FCC regulatory filings, Telecom Engineering Centre certification databases, SEC 10-K equipment vendor disclosures, and carrier capital expenditure reports. This approach enables triangulation between demand-side validation requirements and supply-side capacity deployment.
Historical trendline analysis of VoLTE penetration rates, network slicing deployment velocity, and cloud migration patterns informs the projection framework. Segmentation dimensions modeled include deployment architecture, end-user category, product type, and geographic regulatory cluster. CAGRs were derived through regression analysis of capital intensity shifts and automation depth adoption curves across the projection horizon. Industry-specific forecast inputs incorporate 5G-VoLTE interworking test matrix expansion and India's accelerated lab accreditation timeline compression.
Regulatory mandate delays, gallium nitride supply disruption, and cloud-native platform substitution acceleration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding virtualization velocity and operator procurement pattern shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
United States Borescope Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Megohmmeters Market