

High-Aspect-Ratio 3D NAND Metrology Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
High-Aspect-Ratio 3D NAND Metrology Equipment Market Insights
South Korea's memory fabrication expansion is narrowing the gap between process node requirements and existing metrology capabilities. KLA dominates optical and e-beam defect detection for high-aspect-ratio architectures, leveraging its installed base across Samsung and SK hynix fabs. Onto Innovation anchors critical dimension overlay measurement for string-stacking processes, sustaining R&D intensity in computational lithography integration. Nova competes on film thickness and composition analysis, differentiating through optical solutions tailored to alternating layer stacks.
High-aspect-ratio 3D NAND metrology equipment encompasses precision measurement systems engineered to characterize vertical channel holes, word line slits, and staircase contacts with aspect ratios exceeding 10:1 in stacked memory architectures, typically employing electron beam, X-ray, or optical interferometry techniques operating at sub-nanometer resolution to ensure yield control in 200-plus layer devices. Atomic force microscopes and scanning electron microscopes occupy the largest product segments, with X-ray metrology systems representing the fastest-growing category as void detection and buried interface analysis become critical at advanced layer counts. Semiconductor manufacturers drive the dominant end-user demand, while research laboratories capture expanding share as consortium-based pre-competitive development accelerates for next-generation gate-all-around transitions.
FDA oversight of semiconductor manufacturing equipment imports into the United States intersects with EPA hazardous substance regulations governing the etch chemistries and deposition precursors that metrology systems must monitor, while South Korea's national standards body enforces dimensional traceability protocols for domestic memory suppliers. Japan's METI coordinates industry-academic consortia advancing measurement science for sub-7nm equivalent 3D structures, shaping procurement specifications for equipment vendors. Stakeholders must monitor how EU REACH chemical restrictions and evolving ISO dimensional standards interact with customer qualification timelines as layer counts escalate beyond 300 tiers.
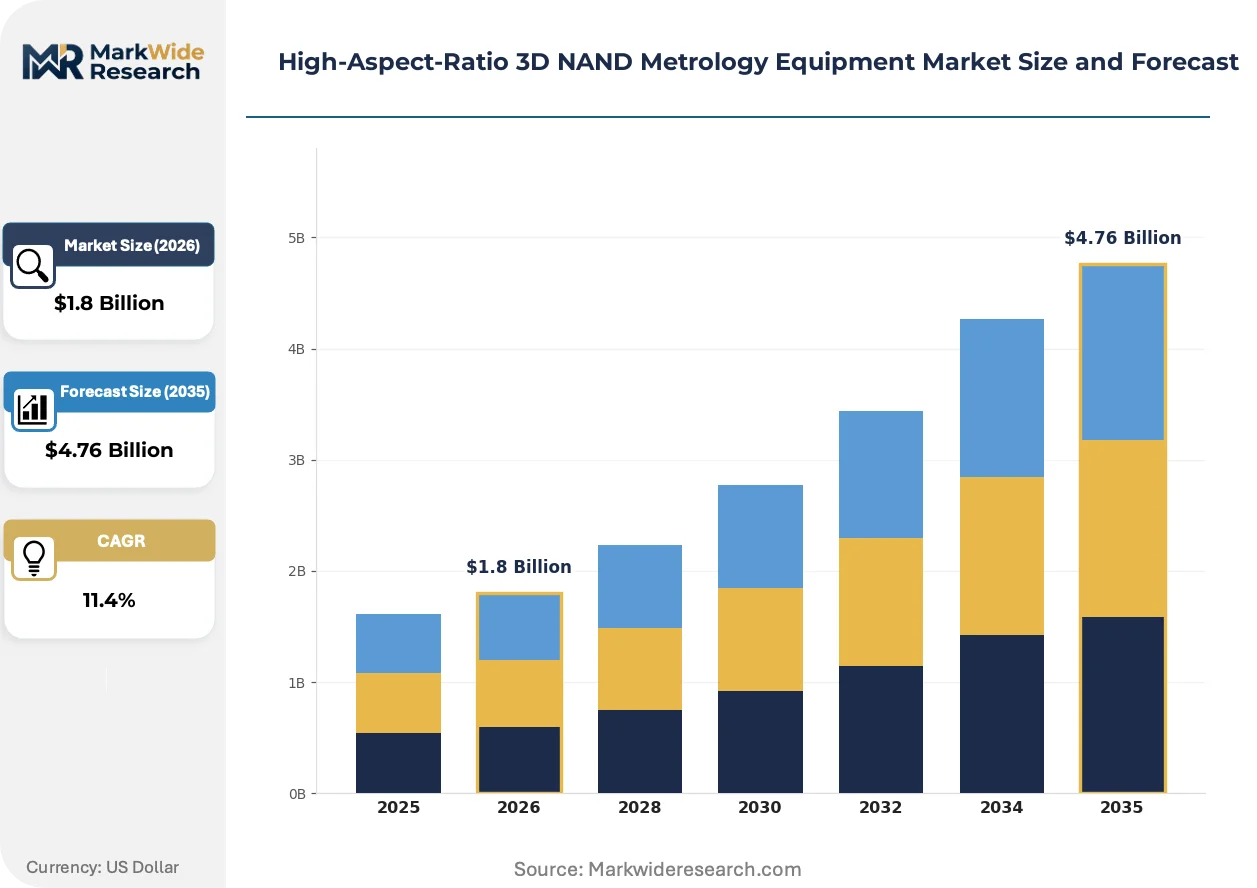
Market Dynamics
Layer-stacking density races past 200 tiers are compressing measurement tolerances for vertical channel holes, forcing metrology vendors to recalibrate electron-beam and optical systems before each new node transition. This structural pressure cascades through equipment procurement cycles, qualification timelines, and R&D allocation decisions.
Growth Catalysts
- Memory Fab Expansion:South Korea's Samsung and SK hynix are commissioning new cleanroom capacity for string-stacking architectures, pulling in high-precision metrology suites for process control qualification.
- REACH Chemical Monitoring:EU restrictions on etch chemistries and deposition precursors mandate real-time compositional analysis, expanding optical film thickness measurement deployments at European-bound production lines.
- EUV Multi-Patterning:Extreme ultraviolet lithography integration with quadruple patterning techniques tightens overlay specifications, elevating critical dimension scanning electron microscope utilization rates.
Market Restraints
- Electron-Beam System Cost Concentration:High-voltage e-beam columns and precision stage assemblies concentrate with Japanese and German component suppliers, exposing equipment vendors to input cost volatility and extended lead times.
- Technical Resolution Ceilings:Optical interferometry approaches physical limits at sub-nanometer scales for buried interface detection, constraining void identification capabilities in 300-plus layer devices.
- Qualification Timeline Friction:ISO dimensional traceability protocols and customer-specific fab qualification cycles extend revenue recognition intervals, compressing vendor cash conversion metrics.
Strategic Opportunities
- Gate-All-Around Transition:Pre-competitive consortium development for next-generation memory architectures opens metrology specification windows for atomic force microscope vendors capable of nanowire characterization.
- X-Ray Metrology White Space:Buried defect detection requirements in Taiwan's advanced packaging clusters create demand for high-flux X-ray computed tomography systems previously deployed only in research settings.
- India PLI Scheme:Production-linked incentive structures for semiconductor manufacturing equipment assembly establish localized service and calibration hubs serving emerging South Asian memory packaging operations.
Industry Challenges
- Computational Lithography Talent Scarcity:Integration of machine learning algorithms into measurement system software requires specialized optical physics and data science expertise concentrated at select academic institutions.
- Legacy Tool Interoperability:String-stacking process control demands real-time data exchange between 200mm-qualified metrology platforms and newer 300mm systems, complicating fab-wide automation architectures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Aspect-Ratio 3D NAND Metrology Equipment Market Trends and Innovations
Measurement virtualization and computational overlay correction are compressing physical inspection cycles, enabling predictive process control before wafers reach dedicated metrology stations. These shifts recalibrate capital allocation between hardware sensors and software analytics layers.
Hybrid metrology architectures combining electron-beam critical dimension measurement with optical film analysis are virtualizing traditional sequential inspection workflows. Memory manufacturers in South Korea now deploy these integrated systems for simultaneous channel hole profiling and alternating stack composition verification. This convergence is virtualizing standalone tool footprints, reducing cleanroom space requirements and qualification overhead for new fab ramps.
South Korea's national standards body enforcement of dimensional traceability protocols is tightening calibration certificate requirements for imported metrology equipment. Domestic memory suppliers must now document measurement uncertainty budgets across entire tool chains, extending vendor pre-shipment validation cycles. Equipment manufacturers are responding by embedding self-calibration routines and reference artifact libraries directly into system software.
Equipment-as-a-service contracting is displacing traditional capital purchase models for high-aspect-ratio metrology suites. Taiwanese foundries and integrated device manufacturers now favor performance-based agreements tying vendor payments to measurement accuracy guarantees and uptime thresholds. This restructuring concentrates most visibly in East Asian semiconductor clusters where fab utilization rates and yield targets dominate procurement negotiations.
High-Aspect-Ratio 3D NAND Metrology Equipment Market Segmentation
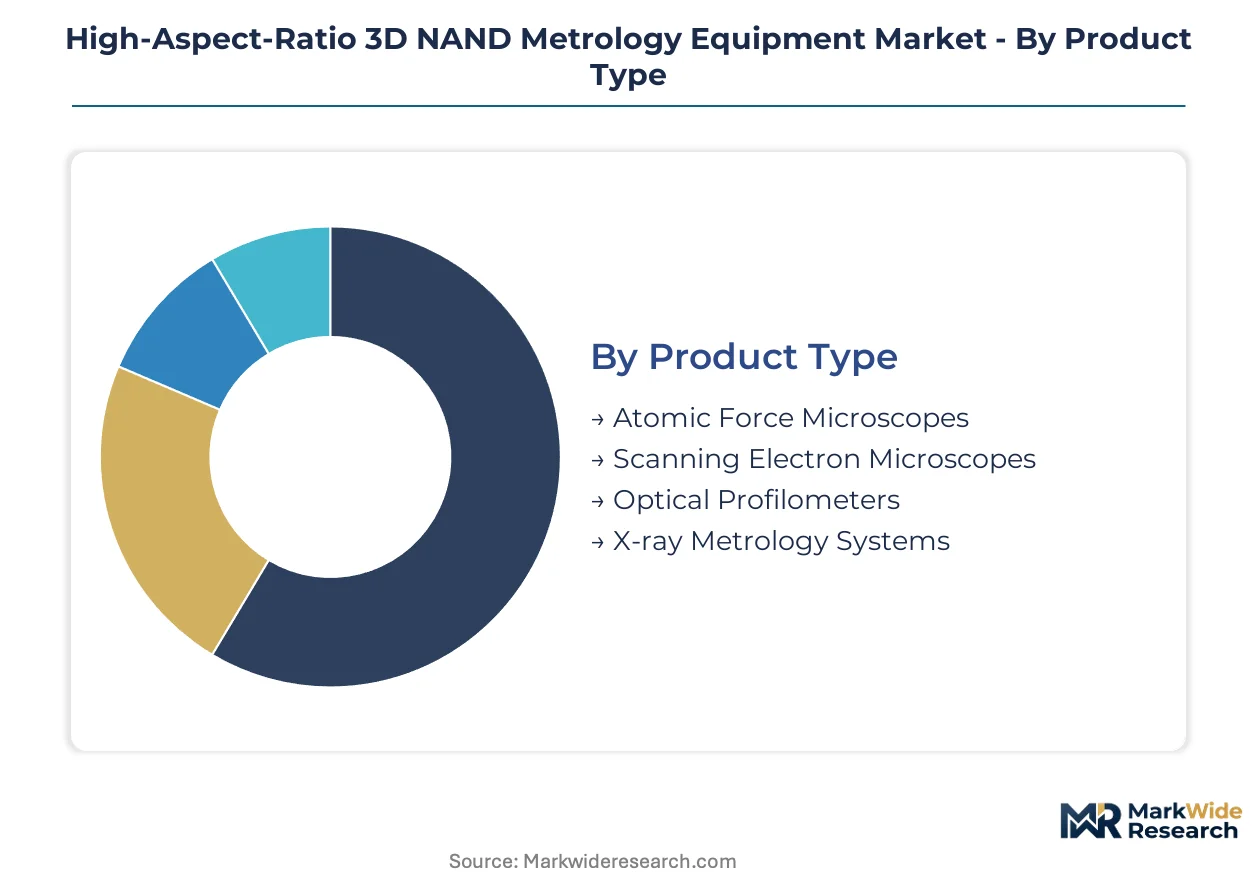
Metrology equipment segmentation for high-aspect-ratio 3D NAND reflects distinct technical requirements across measurement modalities. Each product and technology category addresses specific failure modes in vertical channel architectures, driving differentiated procurement patterns among memory fabs.
Product Type:
Cost tiers separate installed-base platforms from emerging inspection technologies, with capital intensity varying by resolution specification and throughput capability.
- Atomic Force Microscopes:These systems deliver sub-nanometer vertical resolution for surface topography and sidewall roughness characterization in staircase contact structures. Samsung and SK hynix fabs in South Korea deploy AFM suites for word line edge roughness monitoring at 200-plus layer nodes, though throughput constraints limit deployment to critical sampling points rather than full-wafer coverage.
- Scanning Electron Microscopes:Critical dimension-SEM platforms dominate channel hole diameter and overlay measurement for string-stacking processes, leveraging high-voltage electron columns to penetrate deep trench architectures. Taiwan's foundry clusters sustain highest utilization rates as multi-patterning integration tightens measurement frequency requirements.
- Optical Profilometers:White-light interferometry systems provide non-destructive film thickness monitoring for alternating oxide-nitride stacks.
- X-ray Metrology Systems:High-flux computed tomography enables void detection and buried interface analysis without destructive sample preparation.
Scanning Electron Microscopes hold installed capacity. X-ray Metrology Systems is rotating up the share rankings.
Technology:
Application requirements dictate technology selection, with resolution demands and sample destructiveness driving divergent deployment patterns across process steps.
- Focused Ion Beam:Gallium and xenon plasma ion sources enable site-specific cross-section preparation for transmission imaging of vertical channel profiles. Memory manufacturers reserve FIB-SEM workflows for failure analysis and process development rather than inline monitoring due to destructive sampling requirements.
- White Light Interferometry:Broadband optical interference patterns reconstruct surface topography across millimeter-scale fields of view, supporting staircase contact height uniformity measurement. South Korean fabs integrate these systems at etch-stop verification stages where speed outweighs atomic-scale resolution needs.
- Transmission Electron Microscopy:Atomic-resolution imaging resolves individual layer interfaces in gate-stack architectures.
- Ellipsometry:Polarized light analysis quantifies film thickness and optical constants for deposition process control.
White Light Interferometry holds installed capacity. Focused Ion Beam is rotating up the share rankings.
Application:
Volume concentration tracks process complexity, with measurement frequency escalating at nodes exceeding 200 active layers.
- Defect Inspection:Patterned and unpatterned wafer inspection systems identify killer defects in channel hole arrays before subsequent processing stages compound yield loss. Taiwan's advanced packaging clusters drive fastest adoption of multi-beam electron inspection for throughput scaling.
- Critical Dimension Measurement:CD-SEM and optical scatterometry quantify channel diameter, word line width, and overlay registration with sub-nanometer precision. South Korean memory fabs operate these tools at highest sampling rates, with measurement points increasing proportionally to layer count.
- Layer Thickness Analysis:Spectroscopic ellipsometry and X-ray reflectometry monitor alternating stack deposition uniformity.
- Surface Roughness Evaluation:AFM and optical profilometry characterize etch sidewall morphology affecting device reliability.
- Film Stack Characterization:Multi-technique integration determines composition and stress in oxide-nitride pairs.
Critical Dimension Measurement holds installed capacity. Defect Inspection is rotating up the share rankings.
End User:
Customer type determines procurement scale and qualification rigor, with integrated manufacturers exhibiting distinct vendor consolidation patterns versus research institutions.
- Semiconductor Manufacturers:Integrated device manufacturers and memory specialists operate largest installed bases, with Samsung and SK hynix in South Korea maintaining multi-vendor strategies to mitigate supply concentration risk. These buyers drive specification roadmaps through direct R&D collaboration and pre-competitive consortium participation.
- Foundries:Pure-play foundries in Taiwan prioritize measurement standardization across diverse customer tape-outs, favoring platforms with automated recipe generation and fleet matching capabilities. Procurement cycles align with leading-edge node ramps rather than memory-specific layer stacking transitions.
- Research Laboratories:Academic and national laboratory facilities access metrology platforms through consortium funding and shared user facilities.
- Quality Assurance Laboratories:Third-party testing services support supply chain verification and failure analysis outsourcing.
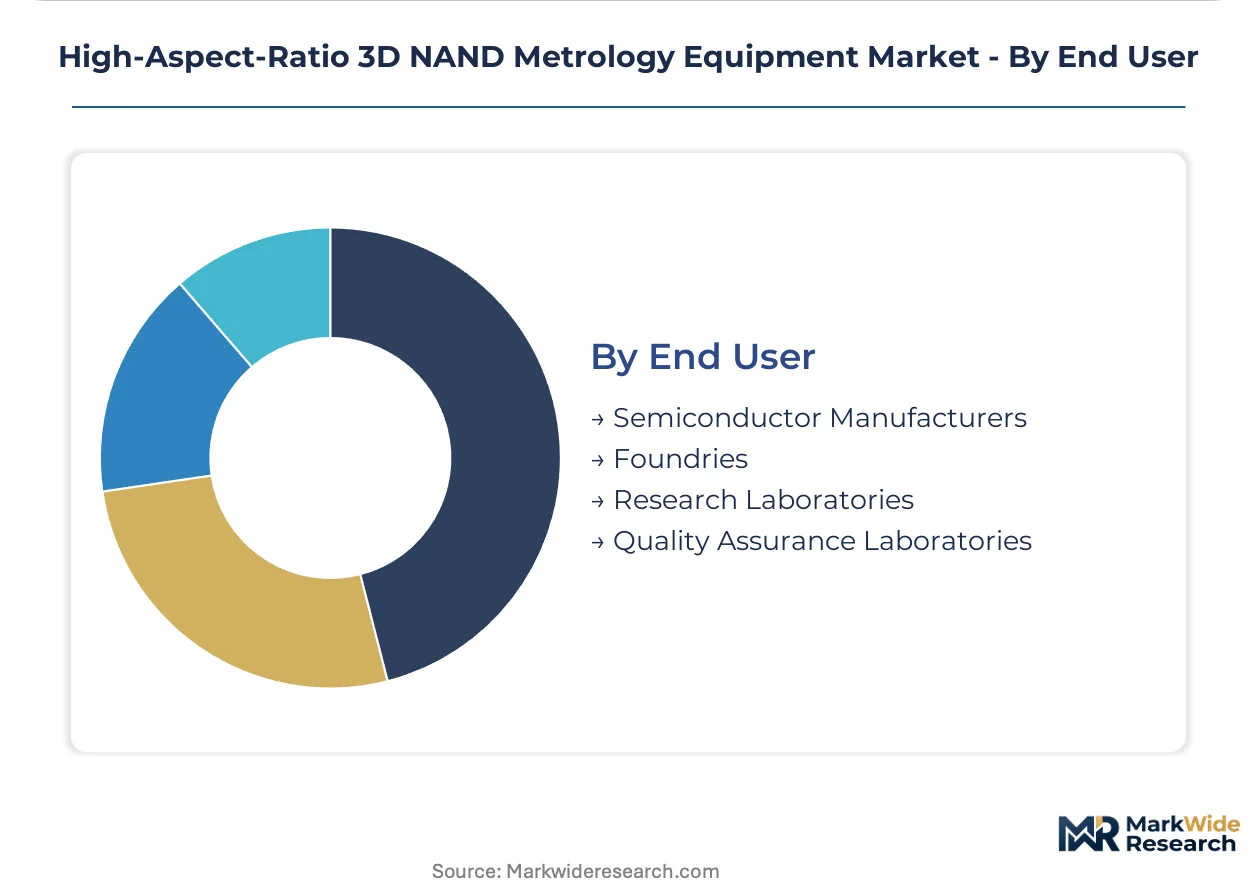
Semiconductor Manufacturers hold installed capacity. Research Laboratories is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's national standards body anchors dimensional traceability enforcement across East Asian semiconductor clusters, tightening calibration requirements for imported metrology equipment serving 200-plus layer memory fabrication.
South Korea
Samsung and SK hynix are commissioning new cleanroom capacity for string-stacking architectures, pulling precision metrology suites for process control qualification. The Korean Agency for Technology and Standards enforces measurement uncertainty documentation across entire tool chains. Pyeongtaek and Icheon host the densest concentrations of high-aspect-ratio metrology deployments, with vendors embedding self-calibration routines to satisfy extended pre-shipment validation cycles.
Taiwan
Pure-play foundries and integrated device manufacturers drive multi-patterning integration, elevating critical dimension scanning electron microscope utilization rates. The Industrial Technology Research Institute coordinates pre-competitive measurement science consortia for advanced packaging clusters. Hsinchu Science Park concentrates equipment-as-a-service contracting models, with performance-based agreements tying vendor payments to measurement accuracy guarantees and uptime thresholds.
United States
Research laboratories capture expanding share as consortium-based development accelerates for next-generation gate-all-around transitions. FDA oversight intersects with EPA hazardous substance regulations governing etch chemistries that metrology systems must monitor. Albany NanoTech Complex and Sandia National Laboratories anchor public-private partnerships advancing sub-nanometer resolution techniques for buried interface detection.
Japan
High-voltage electron-beam columns and precision stage assemblies concentrate with domestic component suppliers, exposing equipment vendors to input cost volatility. METI coordinates industry-academic consortia advancing measurement science for sub-7nm equivalent 3D structures. Tokyo and Yokohama fabrication clusters shape procurement specifications through direct vendor collaboration on next-node roadmaps.
China
Domestic memory manufacturers are expanding 3D NAND fabrication capacity, driving demand for high-precision metrology tools as layer counts escalate beyond 300 tiers. MIIT coordinates national standards development for semiconductor manufacturing equipment under dual carbon goals. Yangtze River Delta clusters in Shanghai and Wuxi concentrate pilot line deployments, with local vendors developing optical film thickness solutions for alternating stack deposition monitoring.
High-Aspect-Ratio 3D NAND Metrology Equipment Market Competitive Landscape
Full-stack metrology platforms and specialized component suppliers split the market into consolidated and fragmented tiers. Equipment vendors with captive electron-beam column supply chains command premium positioning against optical-specialist challengers. Two dominant strategic archetypes emerge: integrated measurement suite providers spanning multiple modalities, and focused vendors dominating single-technique categories. Competitive moves concentrate on backward integration into precision stage manufacturing and technology licensing partnerships for computational lithography software.
Within the integrated platform tier, KLA and Applied Materials occupy positions exemplifying full-modalities coverage, while Lasertec represents the specialized optical inspection archetype. Onto Innovation and Nova sit within the precision measurement software layer, anchoring critical dimension overlay and film composition analysis respectively. These five entities illustrate how vendor consolidation around memory fabrication clusters in South Korea and Taiwan determines competitive positioning, with equipment-as-a-service contracting restructuring traditional capital purchase relationships.
| Leading Market Players |
|---|
| KLA |
| Onto Innovation |
| Nova |
| Hitachi High-Tech |
| Applied Materials |
| Lasertec |
| Camtek |
| SCREEN Semiconductor Solutions |
| Thermo Fisher Scientific |
| Others |
Pricing and Supply Chain Analysis
Tokyo-Yokohama fabrication clusters concentrate high-voltage electron-beam column manufacturing, granting Japanese precision stage suppliers outsized leverage over metrology equipment pricing. This geographic chokepoint compresses margins for optical-specialist vendors while amplifying premium capture for integrated platform providers with captive component supply.
Pricing Analysis
East Asian price spreads exceed North American benchmarks by substantial margins, reflecting cleanroom proximity premiums and localized service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by measurement resolution specification and ISO dimensional traceability certification tier. Pricing pressure stems from Taiwanese foundry consolidation around equipment-as-a-service contracting, with performance-based agreements displacing capital purchase models. Memory manufacturers in South Korea exhibit lowest price sensitivity due to yield-loss exposure, while Indian emerging packaging operations drive hardest bargain terms.
Supply Chain Analysis
High-voltage electron-beam columns and precision stage assemblies draw from concentrated Japanese and German component suppliers, with secondary optical sensor sourcing from Taiwan and South Korea. Raw material dependencies center on high-purity ceramics for vacuum chambers, precision-machined aluminum alloys for motion stages, and rare-earth phosphors for detector arrays. Single-source vulnerability around gallium liquid metal ion sources for focused ion beam systems exposes equipment vendors to extended lead time volatility. Distribution runs through direct vendor-fab relationships in East Asian semiconductor clusters, with service and calibration hubs anchoring localized aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting expands recurring revenue attachment faster than hardware shipment growth, elevating software analytics and uptime guarantee layers as valuation drivers. This service-attach dynamic restructures vendor-customer relationships around performance accountability rather than capital transfer.
For Market Incumbents: Harden captive supply chains around precision stage manufacturing to neutralize Japanese component supplier pricing leverage. Deepen backward integration into electron-beam column assembly while embedding self-calibration software to compress qualification timelines. Korean national standards body enforcement of dimensional traceability protocols threatens vendors lacking embedded reference artifact libraries. For New Entrants and Emerging Players: Build out X-ray metrology system capabilities for buried defect detection in Taiwan's advanced packaging clusters, where high-flux computed tomography demand outpaces established supplier capacity. Target research laboratory segments through consortium-funded shared user facilities, leveraging pre-competitive gate-all-around development programs as qualification pathway. Lead with computational lithography software licensing rather than hardware platforms to minimize capital intensity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because equipment-as-a-service contracting concentrates vendor relationships around measurement accuracy guarantees and fleet matching capabilities, favoring scaled platform providers over single-technique specialists. Acquisition target archetype: optical-specialist vendors with computational overlay correction software and established foundry relationships. Signal to watch: gate-all-around transition timeline acceleration in South Korean consortium roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Stage Manufacturing | Captive supply of motion control hardware neutralizes Japanese supplier pricing leverage for KLA and Applied Materials. |
| Computational Lithography Software Licensing | Onto Innovation and Nova anchor critical dimension overlay measurement through algorithmic rather than hardware differentiation. |
| Equipment-as-a-Service Contracting Expansion | Taiwanese foundries tie vendor payments to uptime thresholds, restructuring cash conversion metrics across East Asian clusters. |
| X-Ray Metrology System Development | High-flux computed tomography addresses void detection gaps in 300-plus layer devices at Taiwan advanced packaging facilities. |
| Embedded Self-Calibration Routine Deployment | Korean Agency for Technology and Standards enforcement extends pre-shipment validation cycles, favoring vendors with automated calibration. |
Research Methodology
A standing panel of process control engineers at memory fabs, metrology equipment procurement managers, national standards body technical directors, and semiconductor consortium research leads provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with secondary source triangulation across SEC equipment vendor filings, Korean Agency for Technology and Standards dimensional traceability protocols, Taiwan Industrial Technology Research Institute consortium disclosures, and Japanese METI measurement science program documentation. Bottom-up segment sizing and top-down market reconciliation anchored volume estimates.
Scenario-bracketing across technology transition timelines and foundry capex cycles bounded projection uncertainty. Segmentation modeling spanned product type, measurement technology, application workflow, and end-user archetype across the analysis window. CAGRs derived from layer-stacking density roadmaps and equipment procurement cycle analysis, with EU REACH chemical monitoring mandates and India PLI scheme incentive structures incorporated as demand shapers.
Stress conditions across electron-beam column supply disruption, optical interferometry resolution ceiling constraints, and gate-all-around transition timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions regarding ISO dimensional standard evolution and memory fab utilization sustainability. Cross-checking against Japanese METI industry-academic consortium publication timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.