
 Bursting Strength Tester Market | 2026-2036
Bursting Strength Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Bursting Strength Tester Market Analysis
Buyer concentration across the packaging sector is rebalancing as multinational corrugated board producers consolidate testing protocols while mid-size converters fragment procurement across regional equipment vendors. Thwing-Albert Instrument Company leverages its ASTM-compliant instrumentation lines to anchor North American laboratory demand. James Heal competes through specialized textile bursting fixtures that extend its reach beyond paper applications. PRESTO dominates price-sensitive segments in South Asia with mechanical-digital hybrid units that control local distribution channels.
A bursting strength tester measures the maximum hydrostatic pressure required to rupture a material specimen, typically expressed in kilopascals or pounds per square inch, using a rubber diaphragm expansion method standardized under ISO 2758 and TAPPI T 403 protocols. Electronic and microprocessor-based configurations lead product type and technology segments due to automated data logging and repeatability advantages in high-throughput quality control environments. Pneumatic systems represent the fastest-growing sub-category where compressed-air infrastructure already exists in integrated packaging mills. Manual units retain residual share in small testing laboratories where capital constraints outweigh throughput requirements.
FDA food-contact packaging rules, EPA recycled content mandates, and ISO 17025 laboratory accreditation standards collectively shape equipment specification sheets and capital approval workflows across end-user facilities. TAPPI and ASTM International publish test method revisions that force instrumentation upgrades or calibration protocol changes. Stakeholders must monitor harmonization gaps between regional standards bodies before committing to multi-site equipment deployments.
Market Dynamics
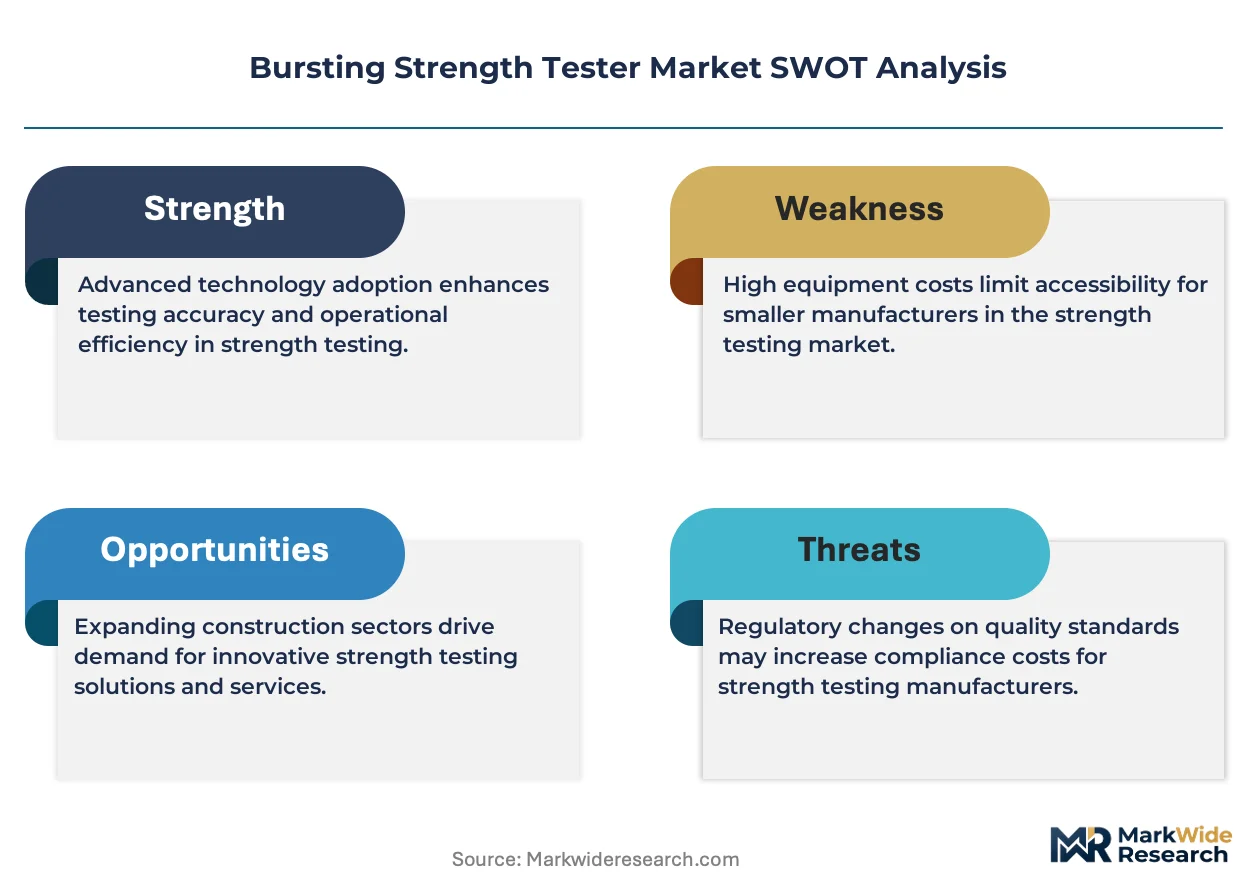
ISO 17025 laboratory accreditation mandates are compressing equipment replacement cycles as packaging manufacturers face audit-driven instrumentation upgrades across multi-site quality networks.
Growth Catalysts
- E-commerce fulfillment expansion:Corrugated board producers in China and India are scaling burst testing capacity to meet export packaging specifications for cross-border retail shipments.
- ISO 2758 protocol harmonization:Testing laboratories in Germany and the United States are consolidating equipment purchases around unified calibration standards to reduce inter-lab variance.
- Pneumatic infrastructure retrofitting:Integrated paper mills with existing compressed-air systems are replacing hydraulic testers to capture energy efficiency gains in high-throughput environments.
Market Restraints
- Steel and aluminum input volatility:Frame and diaphragm material costs fluctuate with commodity indices, squeezing margins for mechanical-digital hybrid unit producers.
- Single-source rubber diaphragm supply:Specialized elastomer suppliers in Southeast Asia create concentration risk for diaphragm replacement part availability.
- Manual unit substitution ceiling:Capital-constrained small laboratories retain legacy hand-operated equipment, capping addressable market expansion in the entry-tier segment.
Strategic Opportunities
- Recycled fiber compliance testing:EPA recycled content mandates and EU Green Deal packaging rules are creating dedicated testing workflows for post-consumer corrugated validation.
- Textile bursting fixture cross-selling:Nonwoven and technical textile manufacturers in South Korea and Japan represent adjacent application demand for diaphragm-based pressure testing.
- Remote calibration service models:Cloud-connected electronic testers enable subscription-based verification protocols, shifting revenue from hardware to recurring service streams.
Industry Challenges
- ISO 17025 auditor qualification gaps:Third-party certification bodies face staffing shortages for laboratory equipment audit capacity, elongating accreditation timelines.
- Legacy system integration friction:Microprocessor-based testers require data bridge development to connect with existing LIMS infrastructure in established paper mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bursting Strength Tester Market |
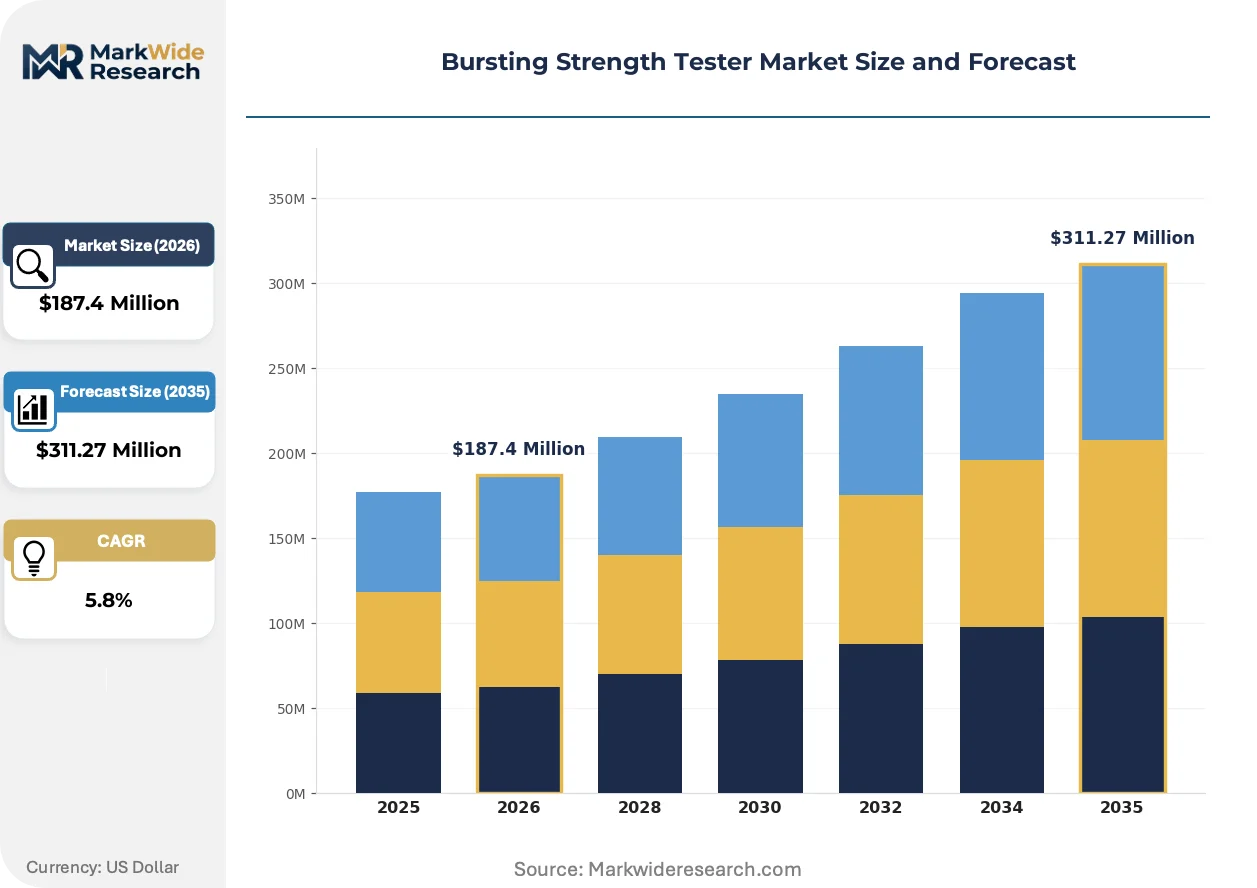
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Hydraulic, Pneumatic, Manual End User: Pulp & Paper, Textile, Plastic, Packaging Technology: Microprocessor-Based, Mechanical, Digital, Analog Application: Quality Control, Research & Development, Production Line, Testing Laboratory |
| Companies Covered | Thwing-Albert Instrument Company, James Heal, PRESTO, TESTEX, GESTER, Asian Test Equipment, Qualitest International, Pacorr, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bursting Strength Tester Market Emerging Trajectories
Automation architectures are restructuring capital deployment patterns as quality control budgets shift from standalone equipment toward networked testing ecosystems with predictive maintenance capabilities.
Microprocessor-based bursting testers with embedded pressure transducers and automated diaphragm conditioning are electrifying quality control workflows in high-volume corrugated facilities. Major packaging converters in the United States are replacing pneumatic-hydraulic hybrids at 18-month refresh intervals. The technology is electrifying throughput benchmarks while compressing technician training requirements across third-shift operations.
REACH substance restrictions on certain elastomer formulations are forcing diaphragm material substitutions in European laboratory equipment. Manufacturers serving German and French markets must reformulate rubber compounds to maintain CE marking compliance. The paper testing segment faces the steepest reformulation timeline as existing diaphragm inventories deplete against certification deadlines.
Consolidated procurement by multinational corrugated producers is displacing regional equipment vendor relationships with framework agreements covering 15-20 site deployments. Tier-one packaging groups in India and Brazil are centralizing tester specifications to standardize inter-facility data comparability. This concentration pattern is most visible in integrated board mills where quality directors now mandate identical instrumentation models across all production locations.
Bursting Strength Tester Market Segmentation
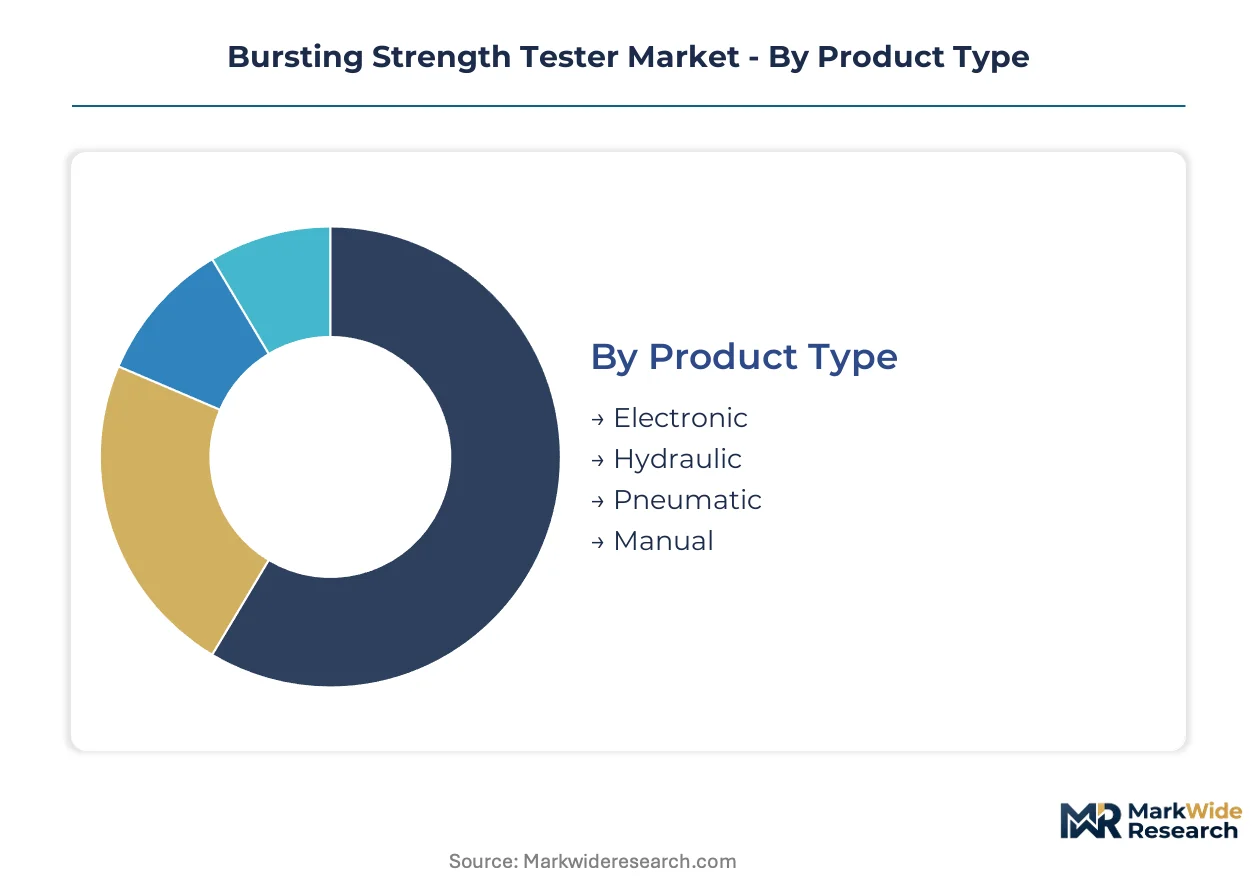
Equipment configuration choices in bursting strength testing reflect divergent capital deployment strategies across facility types. Standalone laboratory units demand precision instrumentation while production line integration prioritizes throughput speed and data connectivity.
Product Type:
Electronic and pneumatic systems embed into centralized quality networks, whereas manual and hydraulic units operate as isolated standalone instruments without data bridge requirements.
- Electronic:Microprocessor-controlled pressure transducers deliver automated data logging with repeatability precision for ISO 17025-accredited laboratories. Demand concentrates in Germany and United States testing facilities where audit-driven calibration protocols compress replacement cycles.
- Pneumatic:Compressed-air diaphragm actuation leverages existing mill infrastructure for energy efficiency in high-throughput corrugated board plants. Integrated packaging mills in China and India retrofit these systems where compressed-air networks already serve converting equipment.
- Hydraulic:Oil-pressure diaphragm expansion provides stable force application for heavy-gauge material testing in legacy facilities.
- Manual:Hand-operated pump mechanisms serve capital-constrained small laboratories where technician labor substitutes for automation.
Electronic systems lead volumes today; pneumatic configurations are gaining share fastest in integrated mill environments.
End User:
Packaging converters anchor procurement volumes through multi-site standardization mandates, while textile and plastic applications represent cost-tier expansion opportunities.
- Packaging:Corrugated board producers deploy networked tester fleets across 15-20 site frameworks to ensure inter-facility data comparability. Multinational converters in Brazil and India centralize specifications to harmonize quality director mandates.
- Pulp & Paper:Integrated mills combine burst testing with furnish optimization workflows for recycled fiber compliance validation.
- Textile:Nonwoven manufacturers in South Korea and Japan adopt diaphragm-based fixtures for technical fabric rupture testing.
- Plastic:Film and sheet producers apply modified protocols for polymer membrane burst resistance characterization.
Packaging commands the dominant revenue share; textile applications show the steepest expansion trajectory among adjacent sectors.
Technology:
Digital and microprocessor architectures displace mechanical systems through predictive maintenance integration, while analog units persist in margin-constrained retrofit scenarios.
- Microprocessor-Based:Embedded sensors enable cloud-connected calibration subscriptions and LIMS integration for automated quality networks. Major United States packaging converters refresh these units at accelerated intervals to compress technician training requirements.
- Digital:Discrete electronic displays with solid-state pressure measurement bridge legacy mechanical systems toward modern data capture without full microprocessor architecture.
- Mechanical:Spring-loaded dial indicators serve basic pass-fail testing in small converter operations without accreditation requirements.
- Analog:Needle-gauge displays with manual recording persist where capital constraints block electronics adoption.
Microprocessor-based systems dominate new installations; digital platforms capture the fastest growth among mid-tier converters.
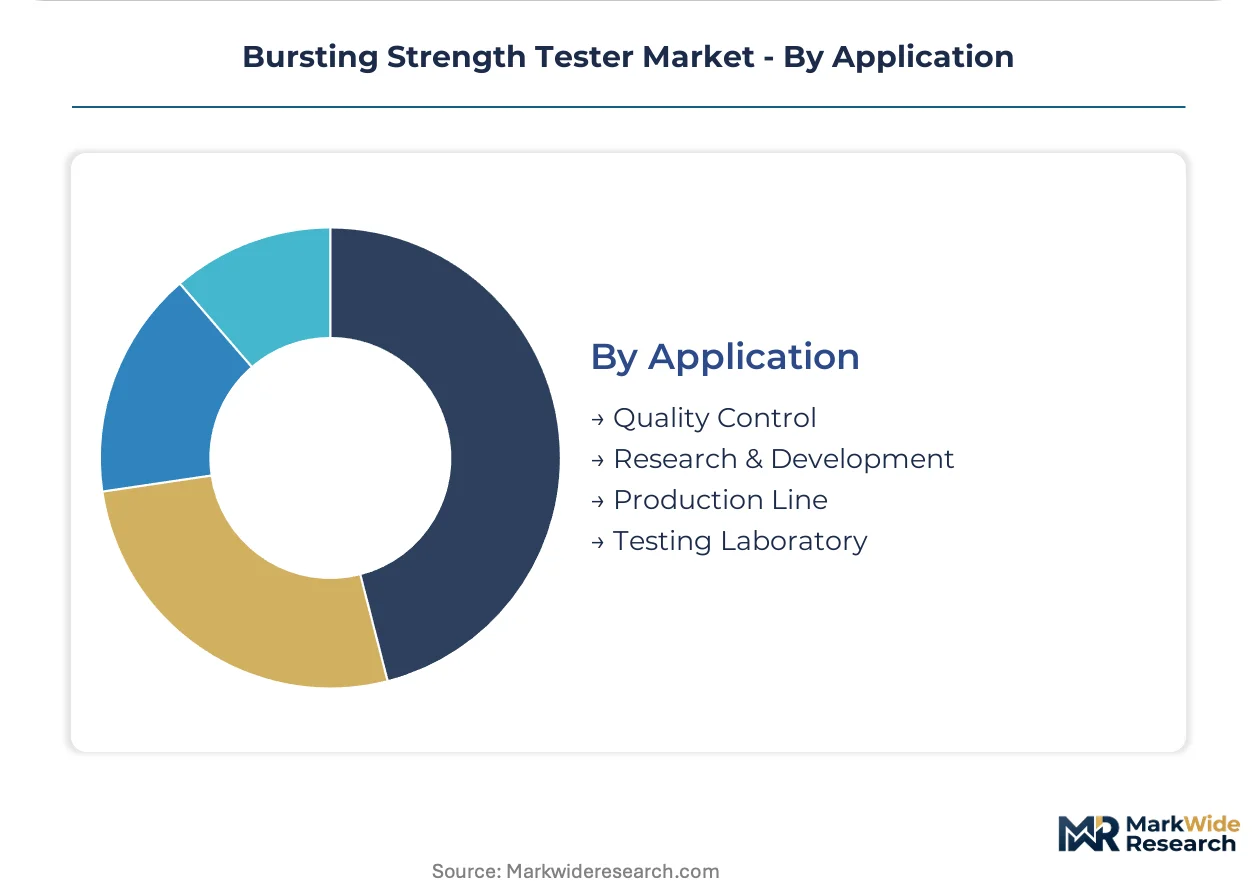
Application:
Quality control workflows concentrate tester deployment at finished goods inspection points, while research applications demand specification flexibility absent in production environments.
- Quality Control:High-throughput inspection stations at corrugated board finishing lines require automated diaphragm conditioning and rapid specimen cycling. E-commerce fulfillment expansion in China drives capacity scaling across export packaging certification workflows.
- Testing Laboratory:Third-party certification facilities combine multi-standard compliance (ISO 2758, TAPPI T 403) with inter-lab variance reduction protocols.
- Production Line:In-line integration with slitter-scorer systems enables real-time burst monitoring without offline sampling delays.
- Research & Development:Pulp and paper laboratories employ variable-rate pressure ramping for furnish behavior characterization in new recycled fiber formulations.
Quality control applications anchor installed base; testing laboratory demand is climbing the fastest amid accreditation mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India are scaling bursting strength testing capacity at markedly different velocities, with China prioritizing export certification automation while India concentrates on domestic converter network expansion. Germany and the United States anchor precision instrumentation demand through accreditation mandates. Brazil and Japan represent adjacent growth vectors through packaging consolidation and technical textile diversification respectively.
China
E-commerce export corridors through Shenzhen and Guangzhou are driving multi-site tester deployments across corrugated board networks. GB standards harmonization with ISO 2758 protocols is compressing equipment replacement timelines for laboratories seeking international recognition. Yangtze River Delta packaging clusters are retrofitting pneumatic systems into existing compressed-air infrastructure at integrated mills serving cross-border retail fulfillment.
Germany
REACH substance restrictions on elastomer formulations are forcing diaphragm material substitutions in laboratory equipment serving corrugated and paper testing segments. CE marking compliance deadlines are accelerating refresh cycles for microprocessor-based units across third-party certification facilities. Bavarian packaging converters are centralizing procurement frameworks across 15-20 site networks to standardize inter-facility data comparability.
United States
FDA food-contact packaging rules and EPA recycled content mandates are reshaping equipment specification sheets for quality directors at multinational board producers. TAPPI T 403 protocol revisions are triggering instrumentation upgrades at ISO 17025-accredited laboratories facing audit-driven compliance pressure. Midwestern corrugated clusters in Illinois and Ohio are replacing pneumatic-hydraulic hybrids with electronic systems at 18-month refresh intervals.
India
Bureau of Indian Standards packaging quality mandates are expanding testing laboratory accreditation requirements for domestic converter networks scaling export capacity. Maharashtra and Gujarat packaging corridors are deploying mechanical-digital hybrid units through regional distribution channels serving price-sensitive mid-size converters. PRESTO's localized supply chain is capturing share in South Asian markets where capital constraints favor hybrid configurations over full electronic architectures.
Brazil
ANVISA pharmaceutical packaging regulations are extending burst testing requirements into secondary packaging workflows for temperature-sensitive drug distribution. São Paulo state corrugated producers are consolidating procurement under framework agreements covering multi-site standardization mandates. Integrated board mills in Minas Gerais are retrofitting existing hydraulic testers rather than full replacement, stretching capital deployment timelines.
Bursting Strength Tester Market Vendor Landscape
North American producers anchor the precision-tier instrumentation segment; Asian fabricators hold dominant positions in price-sensitive mechanical-digital hybrid configurations. The vendor base stratifies across three functional tiers: ASTM-compliant precision laboratories, pneumatic infrastructure specialists, and regional distribution channel players. Consolidated procurement by multinational packaging groups is displacing fragmented regional vendor relationships with centralized framework agreements. Technology licensing arrangements and backward integration into diaphragm supply chains represent the dominant competitive vectors.
Within the precision-tier instrumentation segment, Thwing-Albert Instrument Company and James Heal exemplify divergent specialization strategies. Thwing-Albert anchors North American laboratory demand through ASTM-compliant instrumentation lines serving accreditation-driven quality networks. James Heal occupies a textile-adjacent position where specialized bursting fixtures extend diaphragm-based pressure testing into nonwoven and technical fabric applications. PRESTO sits within the Asia-Pacific volume tier, representing the mechanical-digital hybrid configuration that dominates South Asian distribution channels through localized pricing and service presence.
| Leading Market Players |
|---|
| Thwing-Albert Instrument Company |
| James Heal |
| PRESTO |
| TESTEX |
| GESTER |
| Asian Test Equipment |
| Qualitest International |
| Pacorr |
| ABB |
| Others |
Supply Flow & Price Mechanics
ASTM-compliant precision instrumentation and mechanical-digital hybrid configurations diverge across a certification-performance gap that simultaneously separates pricing power from supply chain complexity. Electronic units with ISO 17025 audit trails command premium positioning through German and United States laboratory demand, while Southeast Asian fabricators anchor economy-tier production through localized diaphragm sourcing and compressed-air infrastructure compatibility.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for mechanical-digital hybrid units, compressing margins for regional vendors serving price-sensitive converter networks. Three-tier pricing structure across premium electronic, standard pneumatic, and economy manual configurations reflects differentiation by certification grade and after-sales service bundling. Pricing pressure stems from steel and aluminum input volatility squeezing frame and diaphragm producers. Small testing laboratories in South Asia exhibit highest price sensitivity, while ISO 17025-accredited facilities in Germany and the United States prioritize repeatability precision over unit cost.
Supply Chain Analysis
Specialized rubber diaphragm supply rests on concentrated elastomer producers in Southeast Asia, with secondary sourcing from Japan and Germany for REACH-compliant formulations. Steel and aluminum frame materials, pressure transducers, and microprocessor controllers constitute critical component dependencies. Single-source vulnerability in diaphragm supply creates concentration risk for replacement part availability across multi-site quality networks. Distribution runs through regional equipment vendors in South Asia and direct laboratory sales channels in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage positioning between Germany's REACH-driven compliance upgrade cycles and India's capital-constrained domestic converter expansion, where identical mechanical-digital hybrid configurations serve divergent budget tiers.
For Market Incumbents: Lock in diaphragm supply chain control through backward integration into specialized elastomer sourcing or exclusive supplier agreements, insulating against Southeast Asian concentration risk. Secure multi-site framework agreements with multinational corrugated producers standardizing 15-20 site deployments to preempt regional vendor displacement. Certification investment in ISO 17025 calibration protocols anchors laboratory demand against emerging pneumatic retrofit competitors. For New Entrants and Emerging Players: Capital-constrained mid-size converters in Maharashtra and Gujarat packaging corridors represent the most penetrable buyer archetype, underserved by full electronic architectures. Technical textile manufacturers in South Korea and Japan offer adjacent application white space for diaphragm-based fixture cross-selling. Go-to-market positioning should emphasize pneumatic infrastructure compatibility and localized service presence rather than precision-tier feature competition. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional vendor relationships face displacement by centralized procurement frameworks at multinational packaging groups. Long-term viability favors precision-tier instrumentation with recurring calibration service revenue streams over pure hardware plays. Acquisition target archetype: electronic tester producers with embedded sensor platforms and cloud-connected subscription capabilities. Watch REACH substance restriction enforcement timelines as inflection indicators for diaphragm material substitution mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diaphragm Supply | Captive elastomer sourcing mitigates Southeast Asian single-source vulnerability for replacement parts. |
| Cloud-Connected Calibration Subscription | Recurring service revenue shifts economics from hardware sales to predictive maintenance platforms. |
| Pneumatic Infrastructure Retrofit | Compressed-air compatibility captures integrated mill demand in China and India without full replacement. |
| Textile Bursting Fixture Development | Technical fabric testing extends addressable market into South Korean and Japanese nonwoven producers. |
| Multi-Site Framework Agreement | Standardized 15-20 site deployments lock out regional competitors from multinational converter procurement. |
Methodological Framework
Coverage spans North America, Western Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining structured interviews with quality directors at corrugated board producers, laboratory accreditation auditors, procurement leads at packaging converters, and aftermarket service heads at regional equipment distributors. Secondary validation draws from TAPPI technical proceedings, ASTM International standards documentation, ISO 17025 accreditation body reports, and customs trade data for instrument imports. Bottom-up unit deployment estimates triangulate against top-down quality control capital expenditure benchmarks across the packaging sector.
Granularity-level modeling disaggregates volume and value outputs by product type, end user, technology architecture, and application workflow, with additional dimensioning by certification tier and compressed-air infrastructure availability. CAGRs derive from segment-specific replacement cycle compression rates and accreditation mandate proliferation curves. Industry-specific forecast inputs include e-commerce fulfillment volume trajectories in China and recycled fiber compliance testing requirement expansion under EPA mandates.
Underlying measurement precision varies by segment; electronic and microprocessor-based installations carry tighter precision than manual unit estimates due to standardized audit documentation. Forecasts reflect documented assumptions regarding ISO 2758 protocol harmonization timelines and pneumatic infrastructure retrofit adoption curves. Supply chain disruption in specialized elastomer sourcing, steel commodity volatility, and auditor staffing shortages at certification bodies warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Roughness Tester Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Leak Testing Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market