
 Surface Measurement Equipment and Tools Market | 2026-2036
Surface Measurement Equipment and Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Measurement Equipment and Tools Market Analytics
Specialized distribution through integrated metrology service providers is tilting toward direct OEM partnerships in high-volume manufacturing. Mitutoyo Corporation leverages its calibration network across Asia to sustain aftermarket revenue streams. Zeiss International anchors premium positioning through optical coherence tomography systems for medical device validation. Bruker Corporation competes in semiconductor wafer inspection with atomic-force microscopy platforms.
Surface measurement equipment and tools encompass instruments that quantify topography, roughness, form, and texture at micro- to nanometer resolutions using tactile probes, laser triangulation, or white-light interferometry. These systems enforce dimensional conformity in precision manufacturing, with typical repeatability thresholds below fifty nanometers for optical platforms. Optical instruments command the widest installed base across electronics manufacturing, while laser interferometry represents the fastest-expanding technology segment driven by semiconductor node shrinkage. Contact profilometers retain entrenched positions in automotive powertrain quality control where stylus-based traceability remains mandatory.
FDA's 21 CFR Part 820 quality system regulation and ISO 13485 framework compel medical device companies to validate surface finish parameters with documented measurement uncertainty. EMA's MDR technical documentation requirements extend this burden to European orthopedic implant manufacturers, forcing upgrades to automated inspection cells. Stakeholders must weigh capital deployment between multi-sensor platforms and dedicated single-technology systems as end-user consolidation accelerates.
Market Dynamics
Semiconductor node shrinkage below 3nm is compressing tolerance thresholds across precision manufacturing, forcing metrology vendors to recalibrate platform architectures around sub-nanometer repeatability specifications.
Growth Catalysts
- EU MDR technical documentation mandates:European orthopedic implant manufacturers must validate surface finish parameters with documented measurement uncertainty, accelerating automated inspection cell upgrades.
- Electric drivetrain component precision:Automotive OEMs require nanometer-grade roughness control for motor laminations and battery cell interfaces, expanding metrology deployment in powertrain assembly.
- Laser interferometry adoption:Semiconductor wafer manufacturers are replacing stylus-based systems with non-contact platforms to inspect copper interconnects without surface damage.
Market Restraints
- Capital intensity of multi-sensor platforms:Single automated inspection cells exceed $800,000 fully installed, freezing out mid-tier contract manufacturers from in-house capability.
- Stylus tip supply concentration:Diamond probe manufacturing clusters in Japan and Germany create single-source vulnerability for contact profilometer maintenance.
- Optical platform environmental sensitivity:Vibration isolation requirements and temperature stability thresholds limit deployment in shop-floor environments without controlled enclosures.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Contract electronics manufacturers in Tamil Nadu and Karnataka lack indigenous calibration infrastructure, creating service-provider entry points.
- Convergence of white-light interferometry and AI defect classification:Combined platforms reduce manual operator interpretation, cutting inspection cycle times for medical device validation.
- Outcome-based metrology service contracts:Tier-one automotive suppliers are unbundling capital expenditure into per-part inspection fees, shifting revenue models for equipment vendors.
Industry Challenges
- Metrology technician scarcity:Operators capable of programming multi-axis coordinate measuring machines with surface modules command 40% wage premiums in Germany's precision corridor.
- ISO 17025 accreditation timelines:Calibration laboratory certification cycles stretch 18-24 months, delaying aftermarket service network expansion for new geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Measurement Equipment and Tools Market |
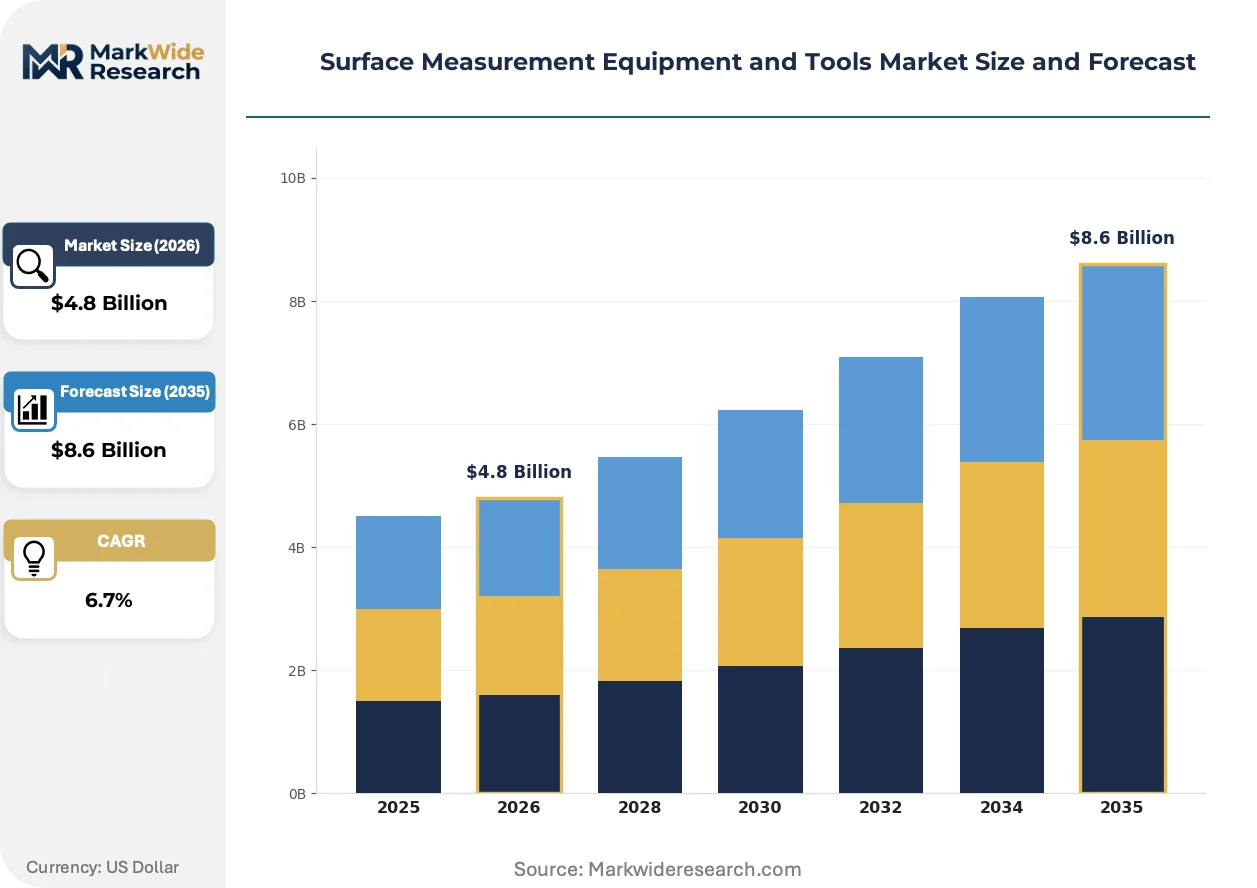
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
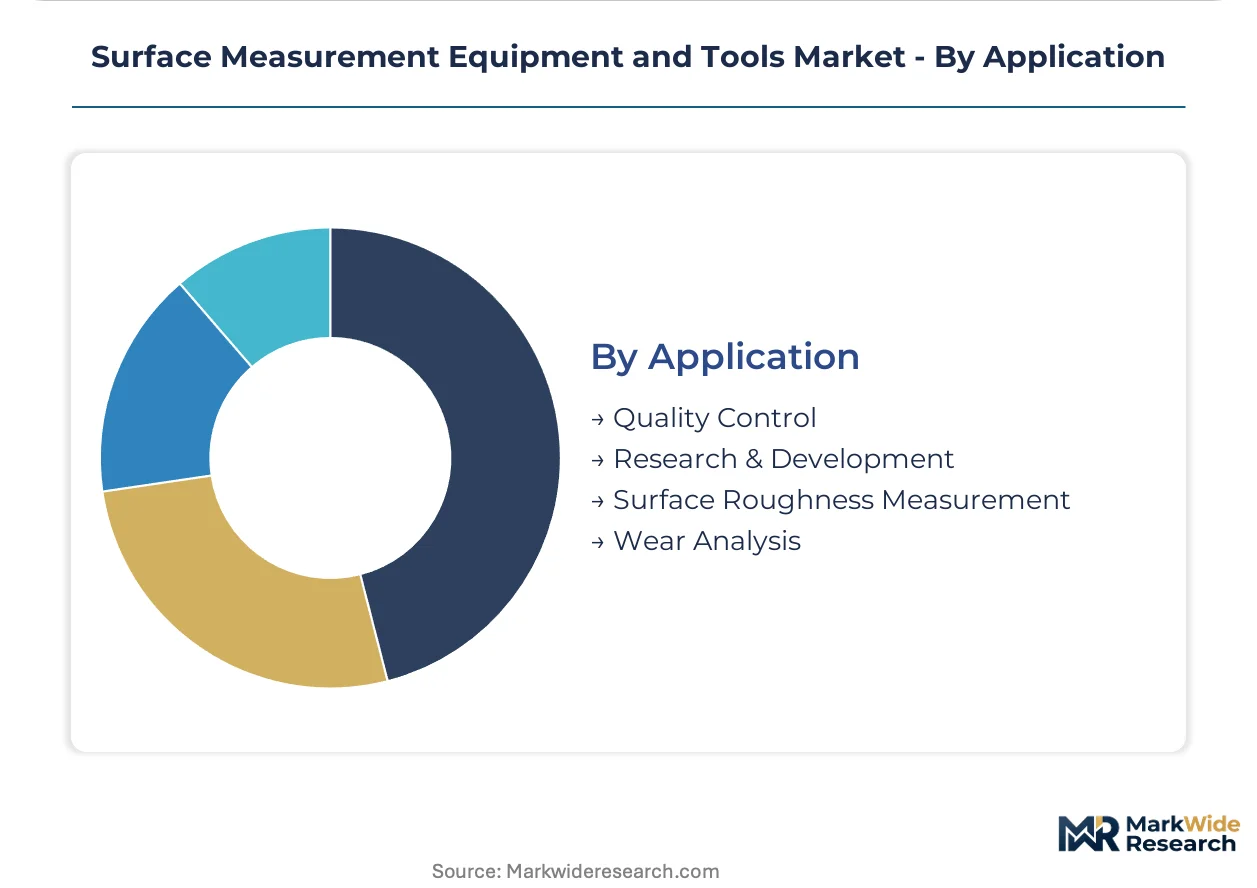
| Segmentation | Product Type: Contact Profilometers, Optical Instruments, 3D Scanners, Laser Scanners Technology: Laser Interferometry, Confocal Microscopy, Tactile Measurement, Optical Coherence Tomography End User: Aerospace, Automotive OEMs, Electronics Manufacturing, Medical Device Companies Application: Quality Control, Research & Development, Surface Roughness Measurement, Wear Analysis |
| Companies Covered | Mitutoyo Corporation, Zeiss International, Bruker Corporation, Kosaka Laboratory Ltd., Mahr Federal Inc., Renishaw PLC, Hexagon AB, Jenoptik, Zygo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Measurement Equipment and Tools Market Evolving Landscape
Measurement systems are converging with manufacturing execution layers, embedding real-time quality feedback directly into CNC machining centers and additive build platforms.
Optical coherence tomography is digitizing subsurface defect detection for transparent medical polymers and layered semiconductor stacks. Ophthalmic lens manufacturers and MEMS foundries are adopting these platforms at 25% annual replacement rates for confocal microscopes. The technology is digitizing quality documentation workflows by generating volumetric datasets that integrate directly with digital twin environments.
China's GB standards for precision mechanical components are tightening surface roughness specifications for aerospace fasteners and hydraulic valve bodies. Domestic certification bodies are rejecting imported equipment lacking Mandarin-language uncertainty documentation. Domestic OEMs in Xi'an and Chengdu are responding by retrofitting existing CMMs with localized software interfaces rather than full platform replacement.
Buyers are consolidating vendor relationships around integrated metrology service providers capable of spanning calibration, inspection, and training. Tier-two automotive suppliers in Mexico and Eastern Europe are displacing single-technology equipment purchases with multi-year service agreements. This pattern is most visible in powertrain component manufacturing where traceability requirements span multiple measurement modalities across dispersed supplier networks.
Surface Measurement Equipment and Tools Market Segmentation
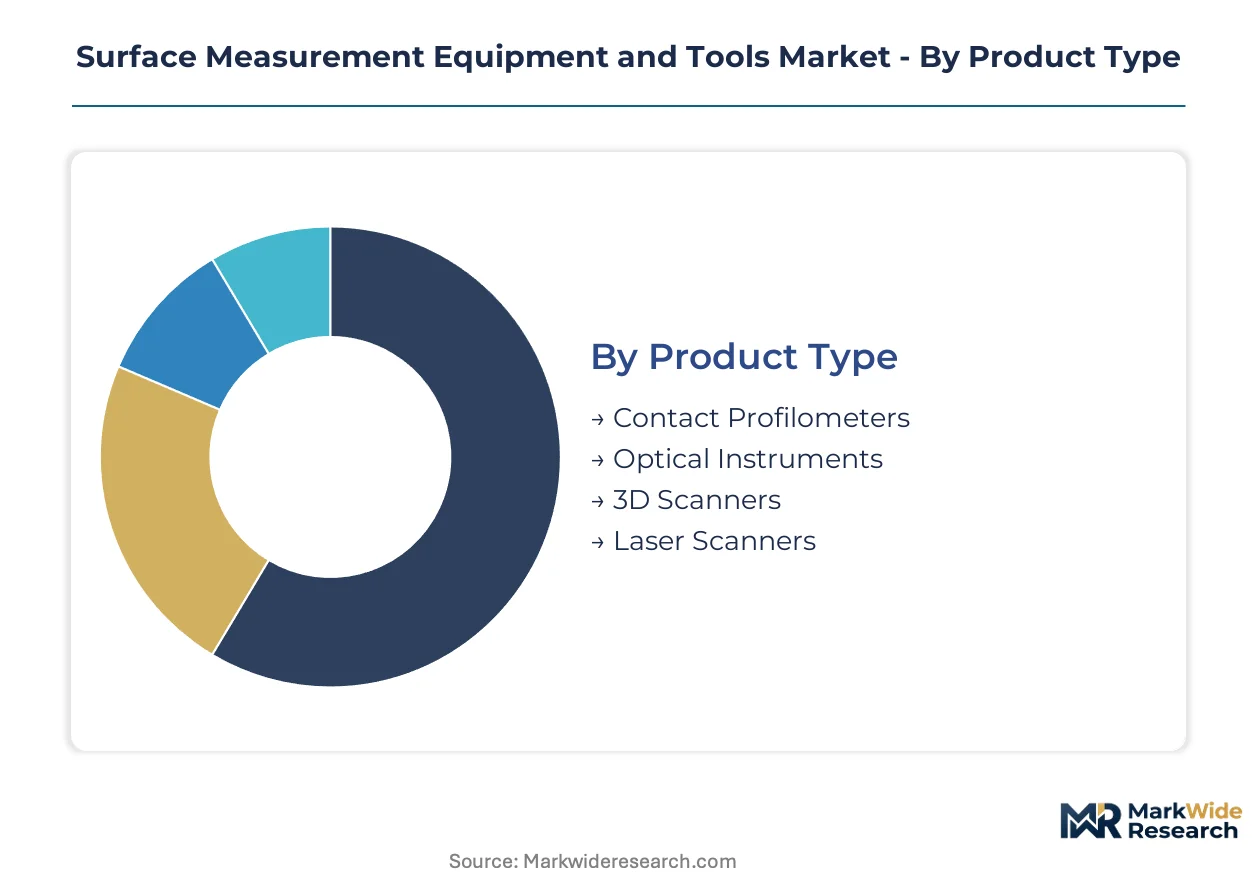
Surface measurement equipment serves divergent precision requirements across semiconductor fabrication, orthopedic implant validation, and electric powertrain assembly. Segmentation reveals how technology choices map to tolerance thresholds, regulatory documentation burdens, and capital deployment constraints.
Product Type:
Use cases span tactile traceability for automotive powertrain certification through non-contact inspection of delicate copper interconnects.
- Contact Profilometers:Diamond-tipped stylus systems deliver ISO 5436-traceable roughness measurements with mandatory calibration chains for automotive bearing surfaces. Stuttgart-based powertrain suppliers deploy these for crankshaft journal validation where stylus-based documentation withstands OEM audit protocols.
- Optical Instruments:White-light interferometry and phase-shifting moiré systems capture sub-nanometer surface topography without mechanical contact. Electronics manufacturers in Taiwan and South Korea favor these for wafer-level inspection where particle generation from physical probes would scrap entire lots.
- 3D Scanners:Structured-light and fringe projection systems digitize complex freeform surfaces for turbine blade reverse engineering.
- Laser Scanners:Triangulation-based line sensors enable high-speed in-process monitoring of cylinder bore geometry.
Established volume favors contact profilometers; emerging adoption favors optical instruments.
Technology:
Resolution requirements and surface damage risk dictate technology selection across end-use environments.
- Laser Interferometry:Heterodyne and homodyne configurations achieve picometer-scale displacement resolution for semiconductor wafer flatness metrology. Foundries transitioning to 2nm nodes require these systems for copper interconnect inspection where stylus contact would induce catastrophic defects.
- Confocal Microscopy:Chromatic aberration-based height mapping delivers sub-micron lateral resolution for MEMS device characterization. Swiss watch component manufacturers and German precision mechanical suppliers retain significant installed bases for small-feature inspection.
- Tactile Measurement:Conventional stylus profilometry remains entrenched where ISO 3274 traceability is contractually mandated.
- Optical Coherence Tomography:Subsurface imaging penetrates transparent polymers and layered semiconductor stacks for defect detection invisible to surface-only techniques.
Process control applications concentrate in tactile measurement; R&D and failure analysis are climbing fastest toward optical coherence tomography.
End User:
Regulatory documentation intensity varies sharply across FDA-regulated medical devices versus automotive production part approval processes.
- Automotive OEMs:Electric drivetrain programs demand nanometer-grade roughness control for motor laminations, battery cell interfaces, and gearbox bearing seats. Tier-one suppliers in Germany's precision corridor face compressed tolerance bands that obsolete legacy CMM-based surface modules.
- Medical Device Companies:FDA 21 CFR Part 820 and EMA MDR technical documentation compel validated surface finish parameters with measurement uncertainty budgets. Orthopedic implant manufacturers in Warsaw and Minneapolis are automating inspection cells to satisfy batch record requirements.
- Aerospace:Nadcap-accredited suppliers inspect turbine blade coatings and landing gear bores for fatigue-critical surface integrity.
- Electronics Manufacturing:Contract assemblers in Tamil Nadu and Penang lack indigenous calibration infrastructure, creating service-provider dependency.
Automotive OEMs anchor current procurement volume; medical device companies are gaining share fastest through regulatory-driven equipment refresh cycles.
Application:
Capital deployment patterns diverge between repetitive production inspection and low-volume experimental characterization.
- Quality Control:Automated inspection cells integrate surface modules directly into CNC machining centers and additive build platforms for real-time conformance feedback. Tier-two automotive suppliers in Mexico and Eastern Europe are displacing capital purchases with multi-year per-part inspection agreements.
- Surface Roughness Measurement:Dedicated profilometry stations enforce ISO 4287 parameters for sealing surfaces, bearing races, and hydraulic valve bodies. China's GB standards tightening for aerospace fasteners is forcing equipment upgrades among Xi'an and Chengdu manufacturers.
- Research & Development:University laboratories and corporate innovation centers require multi-sensor flexibility for exploratory materials characterization.
- Wear Analysis:Tribology studies and failure investigation reconstruct surface degradation histories from scar geometry and debris morphology.
Production quality control commands the widest installed base; wear analysis shows the steepest expansion trajectory from predictive maintenance programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metrology vendors extract 40% price premiums over Taiwanese competitors for equivalent optical platforms, while Chinese domestic suppliers undercut both by 60% on contact profilometers. This asymmetry reflects calibration infrastructure density and regulatory documentation burdens rather than hardware specifications alone.
Germany
Automotive OEMs in Stuttgart and Munich mandate stylus-based traceability for crankshaft journal validation under KBA audit protocols. REACH compliance documentation from ECHA tightens uncertainty budgets for surface finish parameters. The precision manufacturing corridor around Baden-Württemberg concentrates equipment deployment for electric drivetrain programs.
China
Domestic aerospace fastener manufacturers in Xi'an and Chengdu face tightening GB standards for surface roughness specifications. NMPA-aligned certification bodies now reject imported equipment lacking Mandarin-language uncertainty documentation. Local OEMs respond by retrofitting existing CMMs with localized software interfaces rather than full platform replacement.
United States
FDA 21 CFR Part 820 quality system regulation compels medical device companies in Minneapolis and Warsaw to validate surface finish parameters with documented measurement uncertainty. Orthopedic implant manufacturers automate inspection cells to satisfy batch record requirements. The Twin Cities cluster anchors Midwestern metrology service provider expansion.
Japan
Diamond probe manufacturing clusters in Tokyo and Osaka create single-source vulnerability for contact profilometer maintenance. METI-backed precision manufacturing initiatives sustain domestic calibration infrastructure. JIS standards enforcement maintains stylus-based traceability requirements for automotive bearing surface certification.
India
Contract electronics manufacturers in Tamil Nadu and Karnataka lack indigenous calibration infrastructure, creating service-provider dependency under the PLI scheme for precision manufacturing. BIS standards adoption lags equipment deployment, forcing reliance on foreign-accredited laboratories. Bangalore's aerospace subcontracting hub drives initial optical platform adoption.
Surface Measurement Equipment and Tools Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in stylus probes, interferometry objectives, and vibration isolation hardware. The vendor base stratifies across three tiers: multinational metrology conglomerates with calibration networks, regional equipment assemblers serving price-sensitive markets, and niche component fabricators supplying diamond probe tips and optical elements. Dominant competitive moves include backward integration into captive probe manufacturing and geographic expansion of ISO 17025-accredited service laboratories.
Among Japanese precision conglomerates, Mitutoyo Corporation exemplifies the integrated calibration network archetype. German optical specialists including Zeiss International and Mahr Federal Inc. occupy positions anchored by premium-tier positioning through medical device validation credentials. Bruker Corporation represents the diversified instrumentation archetype with roots in analytical equipment rather than pure-play metrology.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Zeiss International |
| Bruker Corporation |
| Kosaka Laboratory Ltd. |
| Mahr Federal Inc. |
| Renishaw PLC |
| Hexagon AB |
| Jenoptik |
| Zygo Corporation |
| Others |
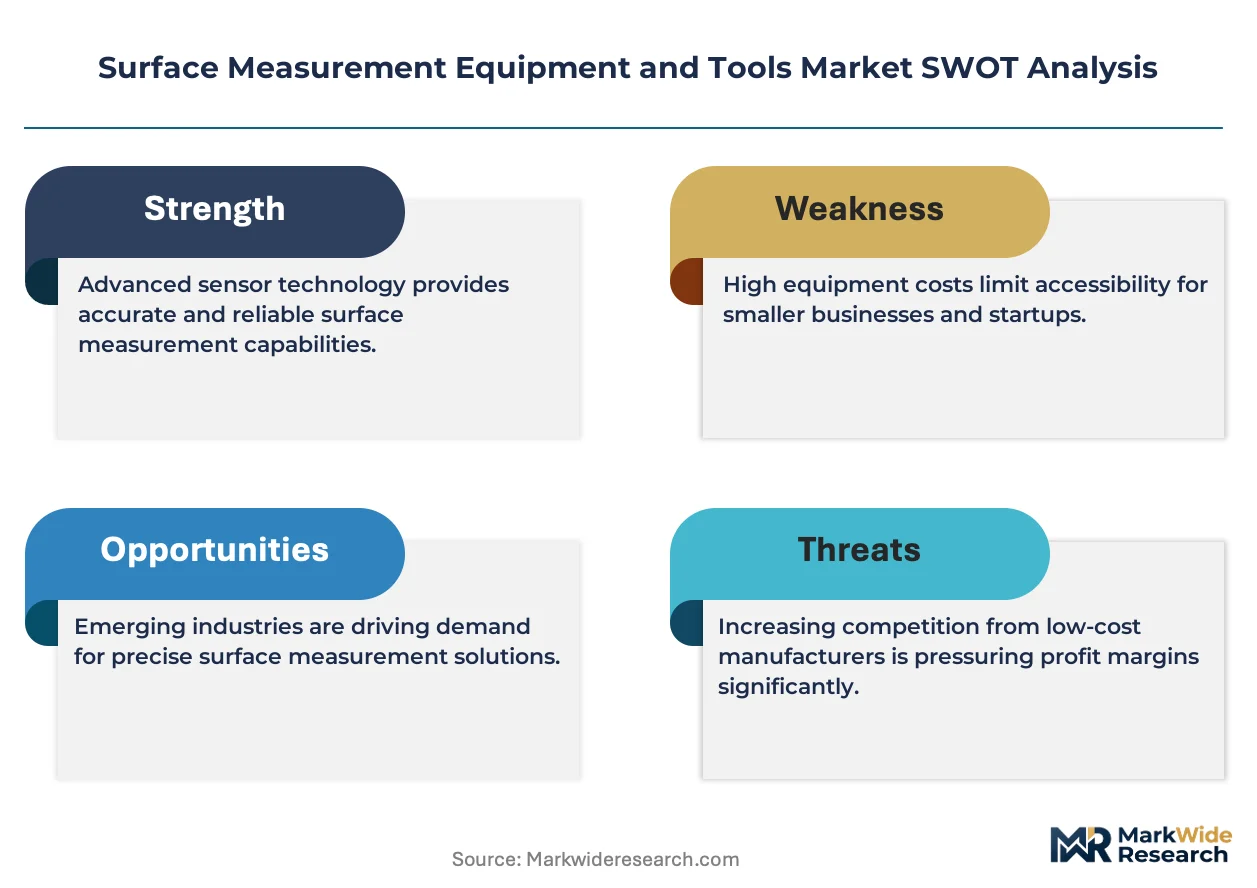
Value Network & Pricing Analysis
Overcapacity in China's domestic optical platform assembly is compressing margins for mid-tier equipment as utilization rates below 70% force aggressive discounting to maintain throughput, reshaping how suppliers allocate diamond probe tip inventory and how buyers negotiate service bundling.
Pricing Analysis
Configured-to-order pricing for multi-sensor automated inspection cells commands spreads exceeding 35% above standard contact profilometer configurations. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 17025 accreditation status and Mandarin-language documentation capability. Cost compression in economy-tier stylus systems is intensifying because Chinese domestic OEMs are retrofitting existing CMMs rather than purchasing new platforms. Tier-two automotive suppliers in Mexico exhibit highest price sensitivity; medical device companies in Minneapolis show lowest due to regulatory compliance mandates.
Supply Chain Analysis
Export-control regimes limiting interferometry objective shipments to semiconductor fabrication facilities in China are forcing equipment vendors to reconfigure supply chains around licensed technology nodes. Diamond probe tip manufacturing concentrates in Japan and Germany; optical element fabrication centers on Taiwan and South Korea. Raw material dependencies include synthetic monocrystalline diamond, fused silica substrates, and piezoelectric ceramics. Single-source vulnerability for stylus tip supply creates maintenance bottlenecks. Distribution runs through integrated metrology service providers rather than direct equipment sales in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as electric drivetrain precision requirements splinter demand across nanometer-grade optical platforms and stylus-traceable automotive certification systems, creating distinct vendor ecosystems rather than consolidated winners.
For Market Incumbents: Entrench calibration network density as the primary defensive moat by accelerating ISO 17025 accreditation in Tamil Nadu and Karnataka before PLI scheme contract manufacturers lock in service-provider relationships. Acquire captive diamond probe manufacturing capability to neutralize Japan-Germany supply concentration risk. Prioritize backward integration into stylus tip fabrication over optical element assembly where Taiwanese suppliers already dominate. For New Entrants and Emerging Players: Pursue outcome-based metrology service contracts in Mexico's Tier-two automotive supplier base, where capital constraints freeze out in-house platform purchases. Target per-part inspection fee models for powertrain component manufacturers lacking multi-sensor capital deployment capacity. Enter through calibration service partnerships rather than equipment sales to bypass incumbent distribution control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated inspection cell manufacturing as modular platform architectures reduce dedicated engineering hours per unit. Long-term viability favors vendors with recurring calibration revenue streams over pure equipment sales. Watch for inflection when semiconductor node transitions below 2nm force sub-nanometer repeatability specification upgrades, triggering replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025 accreditation in India captures PLI scheme contract manufacturers before incumbent lock-in. |
| Backward Integration into Probe Manufacturing | Captive diamond tip production neutralizes Japan-Germany supply concentration vulnerability. |
| AI-Integrated Defect Classification Platforms | White-light interferometry with machine learning reduces medical device inspection cycle times. |
| Outcome-Based Service Contracting | Per-part inspection fees convert capital-constrained Tier-two suppliers to recurring revenue. |
| Mandarin Documentation Localization | Uncertainty documentation in Chinese satisfies NMPA-aligned certification body requirements. |
Research Methodology
A standing panel of metrology service operations directors, automotive Tier-one supplier quality engineers, orthopedic implant manufacturing managers, and semiconductor fab metrology technicians provided ongoing calibration against secondary data. Primary interviews combined with FDA 510(k) filings, EMA MDR technical documentation databases, GB standards revision notices, and customs trade data for optical instrument imports. Bottom-up equipment deployment estimates triangulated against top-down precision manufacturing capital expenditure disclosures.
Scenario-bracketing framed projections across semiconductor node transition timelines and electric vehicle production ramp assumptions. Segmentation dimensions modeled include product type, technology modality, end-user industry, and application environment across the analysis window. CAGRs derived from weighted average of equipment replacement cycles and regulatory-driven upgrade mandates. Forecast inputs incorporated REACH compliance timeline uncertainty and China's GB standards enforcement intensity.
Sensitivities concentrate around semiconductor node shrinkage acceleration and EU MDR audit enforcement rigor. Forecasts reflect assumptions on calibration infrastructure buildout rates in emerging manufacturing clusters. Material shifts in export-control regime scope or NMPA documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Color Meter Market
Test and Measurement
Pump Testers Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Glow Wire Test Apparatus Market