
 Global Semiconductor Equipment Packaging and Test Market | 2026-2036
Global Semiconductor Equipment Packaging and Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Equipment Packaging and Test Market Outlook
The EU Green Deal is broadening compliance obligations for semiconductor packaging and test facilities serving European automotive and industrial clients. Amkor Technology leverages its captive substrate capabilities to sustain margin pools in advanced flip-chip packages. ASE anchors high-volume wire bonding and system-in-package operations across Southeast Asian manufacturing nodes. JCET competes aggressively on cost-adjusted throughput for mature-node integrated circuits bound for consumer and industrial segments.
Semiconductor equipment packaging and test encompasses the capital machinery, materials, and process flows that protect bare silicon dies, establish electrical interconnects, and validate functional performance before shipment to downstream device assemblers. Key technical parameters include bond pad pitch tolerances below 35 micrometers for fine-pitch wire bonding, thermal cycling reliability exceeding 1000 cycles for automotive qualification, and test contactor alignment precision within 5 micrometers for high-pin-count flip-chip devices. Test equipment commands disproportionate capital intensity as heterogeneous integration multiplies die-level validation steps across RF devices and power management integrated circuits. Flip-chip technology leads revenue contribution due to processor and networking demand, while thru-silicon via adoption accelerates in high-bandwidth memory stacks where vertical interconnect density replaces lateral routing constraints.
FDA device-quality traceability requirements, EU REACH substance restrictions on packaging mold compounds, and China's GB standards for electronic product pollution control each reshape material selection and process documentation across multinational supply chains. Taiwan's environmental regulator enforces wastewater and air emissions protocols that elevate operating costs for back-end facilities concentrated in Hsinchu and Tainan Science Parks. Stakeholders must monitor how divergent chemical disclosure regimes between Europe and Asia affect cross-border material qualification timelines and equipment procurement decisions.
Market Dynamics
Heterogeneous integration architectures are compressing traditional packaging hierarchies as chiplets displace monolithic die designs in high-performance computing. This structural shift forces capital equipment makers to recalibrate bond placement precision and thermal management specifications across flip-chip, fan-out wafer-level, and 2.5D/3D stacking platforms.
Growth Catalysts
- EU Green Deal energy benchmarks:Packaging facilities serving European automotive clients must document carbon intensity per unit, accelerating capital replacement cycles for energy-efficient test handlers and mold equipment.
- Electric vehicle platform proliferation:Power module packaging for traction inverters and onboard chargers drives demand for silver-sintering die attach and high-temperature mold compounds qualified to automotive thermal cycling standards.
- Foundry-to-OSAT corridor clustering:Taiwan, South Korea, and mainland China concentrate advanced packaging capacity, creating localized equipment procurement pull for proximity-matched service and spare parts logistics.
Market Restraints
- Palladium and gold wire volatility:Precious metal price swings compress margin predictability for wire bonding equipment vendors locked into long-term consumables contracts with OSAT customers.
- Substrate supply concentration:ABF substrate fabrication concentrates among Japanese and Taiwanese suppliers, creating bottleneck risk for flip-chip ball grid array capacity expansion timelines.
- EU REACH substance restrictions:Brominated flame retardant bans in epoxy mold compounds force material requalification cycles that extend new package type introduction schedules by 12-18 months.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme subsidies for domestic packaging and test facilities create greenfield equipment demand as the country builds OSAT capacity for mature-node consumer and automotive chips.
- Photonics-electronics convergence:Co-packaged optics for AI training clusters integrates silicon photonics with electronic interposers, opening equipment specifications for optical I/O alignment and hybrid assembly.
- Equipment-as-a-service models:Pay-per-wafer pricing for test cell utilization shifts capital burden from OSAT balance sheets to equipment vendors, penetrating cost-constrained mid-tier packaging houses.
Industry Challenges
- Multiphysics simulation expertise scarcity:Package thermal, mechanical, and electrical co-design requires rare cross-functional engineering talent that equipment makers and OSATs compete to recruit.
- Automotive qualification timeline compression:AEC-Q100 and AEC-Q104 stress test protocols demand 1000+ hour validation cycles that conflict with customer pressure for faster new product introduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Equipment Packaging and Test Market |
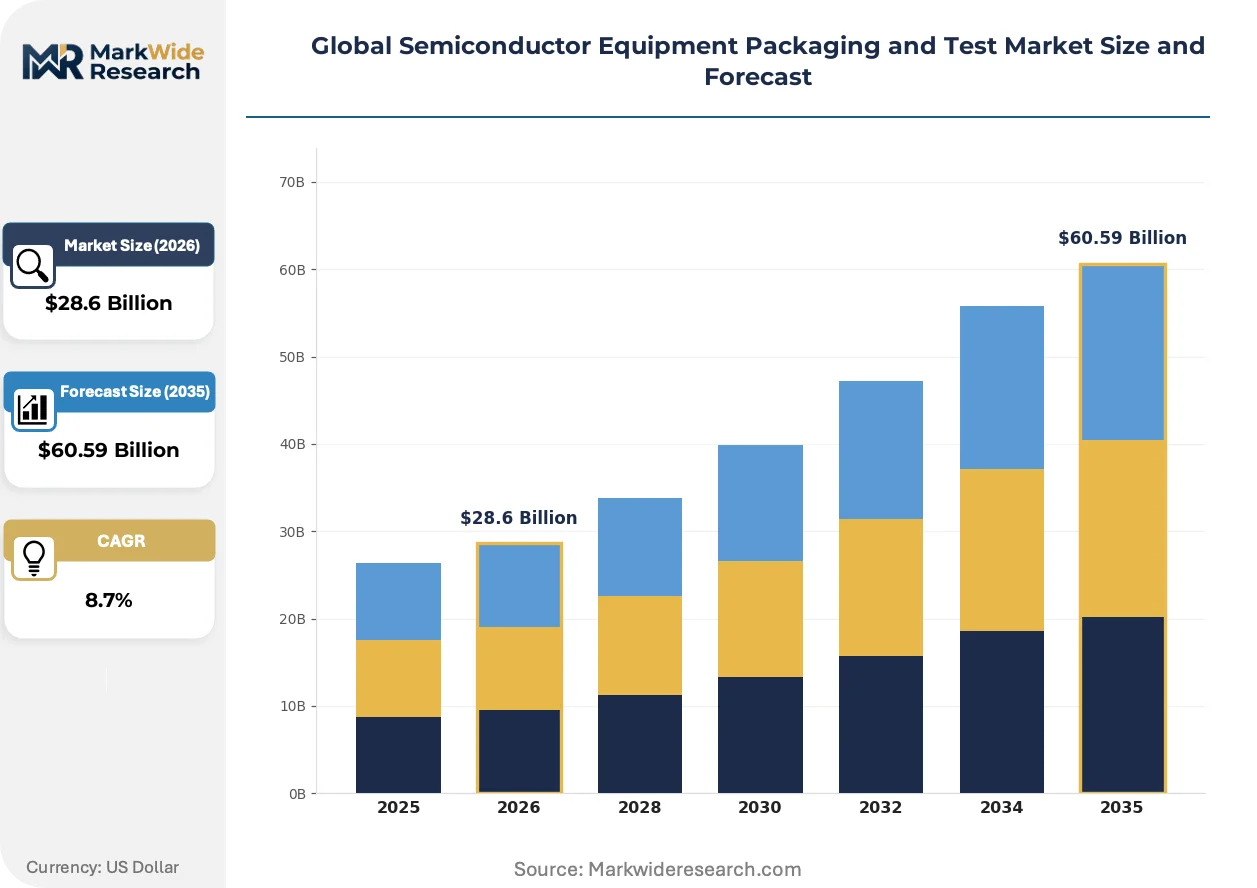
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
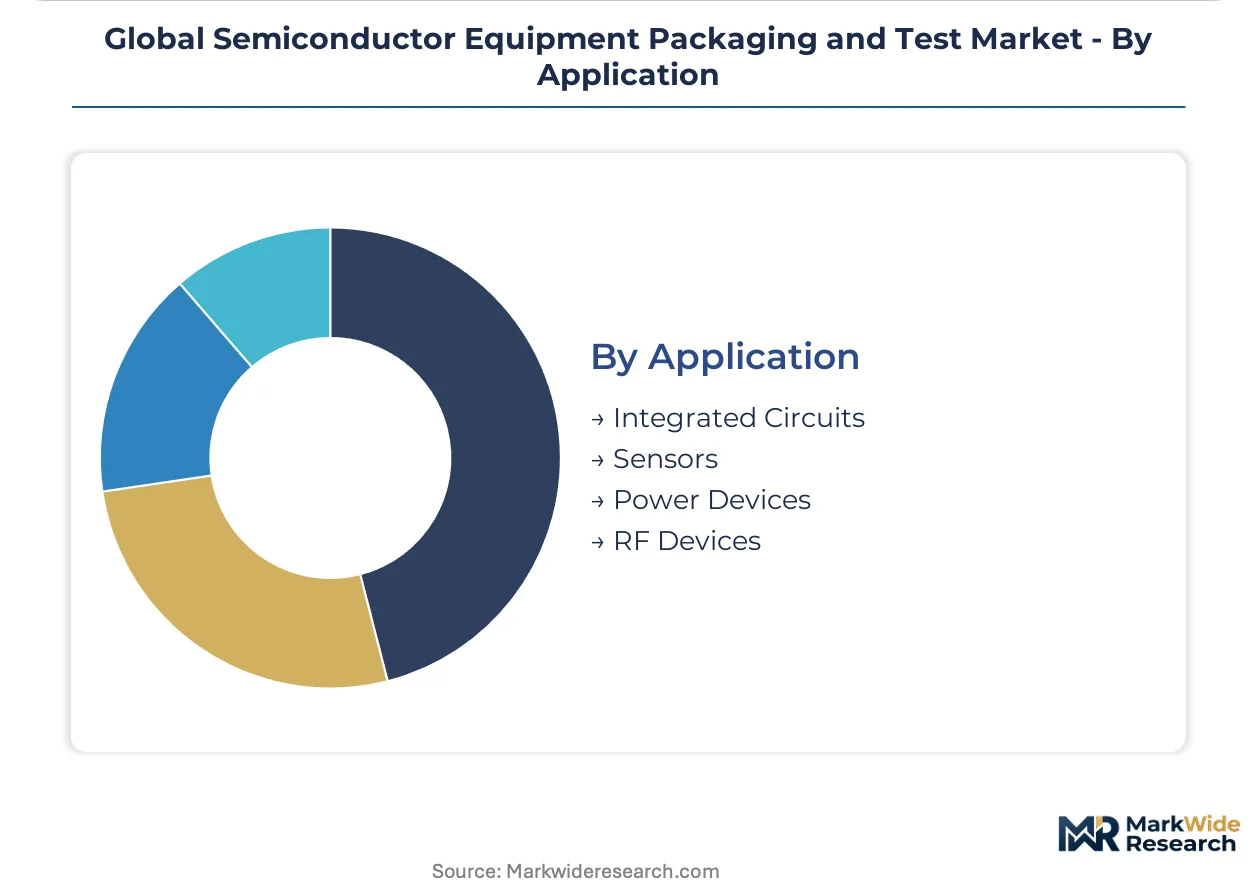
| Segmentation | Product Type: Assembly Equipment, Inspection Equipment, Packaging Materials, Test Equipment Technology: Wire Bonding, Flip Chip, Thru-Silicon Via, Die Attach End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Electronics Application: Integrated Circuits, Sensors, Power Devices, RF Devices |
| Companies Covered | Siliconware Precision Industries (SPIL), UTAC, Amkor Technology, JCET, ChipMos, ASE, STATS ChipPAC, Nepes, Powertech Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Equipment Packaging and Test Market Strategic Shifts
Equipment architectures are converging toward modular platforms that reconfigure between wire bonding, flip-chip, and fan-out processes without full line replacement. This flexibility imperative responds to SKU fragmentation as chiplet-based designs multiply package variants per device generation.
Hybrid bonding technology is electrifying permanent die-to-wafer interconnection by eliminating underfill and solder interfaces entirely. Memory manufacturers building high-bandwidth memory stacks adopt copper-to-copper direct bonding for sub-10 micrometer pitch interconnects. This process is electrifying capital allocation toward precision activation and alignment equipment that displaces traditional thermocompression bonders.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in test handler thermal conditioning systems. Equipment vendors must redesign chiller subsystems for lower global-warming-potential alternatives while maintaining -40°C to +150°C cycling performance. European automotive test facilities face the most compressed compliance timelines as the regulation tightens in three-year reduction steps.
Consolidated procurement consortia among tier-one OSATs are displacing individual equipment vendor relationships. ASE, Amkor, and JCET coordinate test handler and prober purchasing through shared technical specifications that narrow vendor qualification pools. This concentration is most visible in Taiwan and mainland China where capital expenditure coordination among the three companies shapes equipment roadmap priorities.
Global Semiconductor Equipment Packaging and Test Market Segmentation
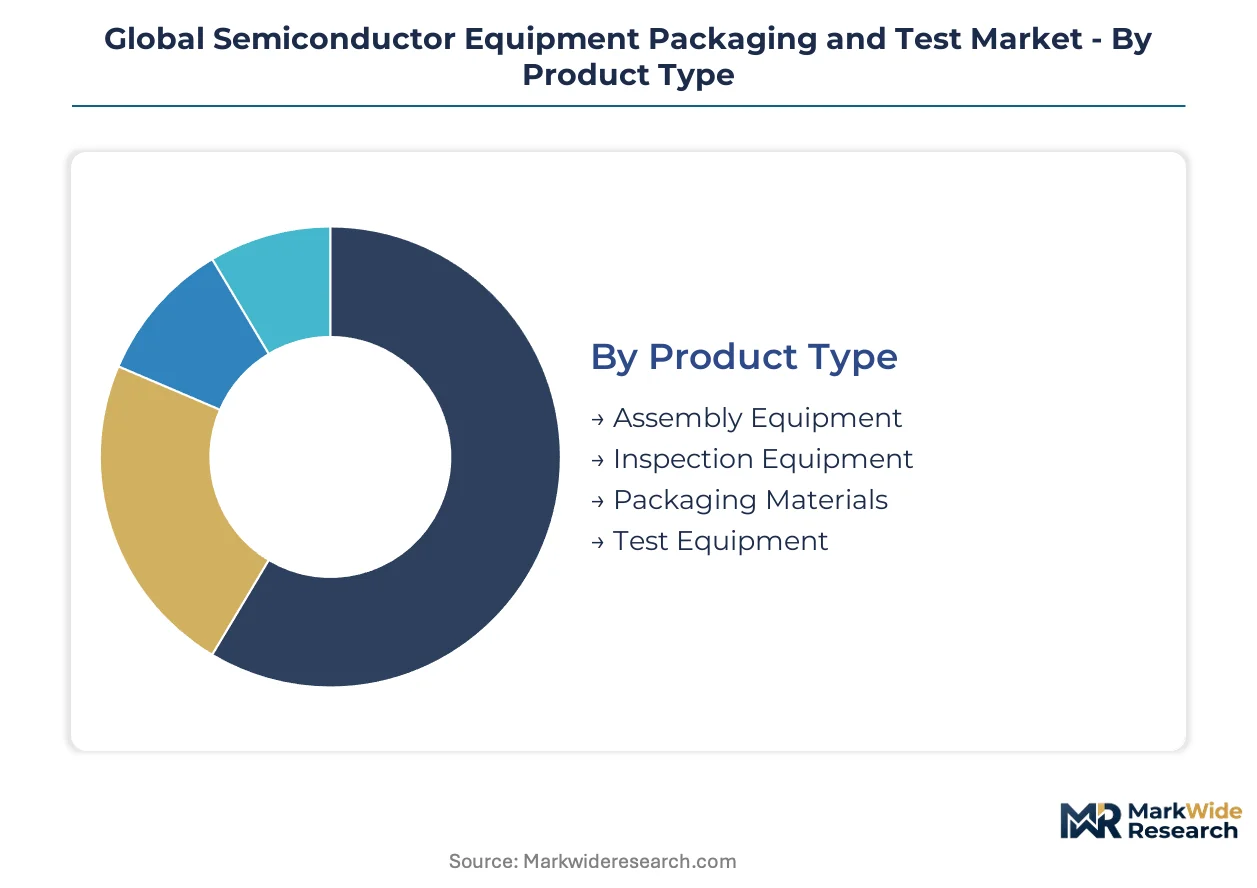
Equipment procurement patterns diverge sharply across process stages in semiconductor back-end manufacturing. Test handlers and bonders command distinct capital allocation cycles, while substrate materials and inspection systems follow separate supply chain rhythms. Understanding these segment boundaries clarifies where technology transitions create replacement demand versus incremental expansion.
Product Type:
Technology specifications define equipment selection criteria across assembly, inspection, and validation workflows. Thermal conditioning precision and alignment tolerances separate premium system tiers from standard configurations.
- Assembly Equipment:Die bonders, wire bonders, and flip-chip placers constitute the core capital base for OSAT facilities. Taiwan and mainland China concentrate procurement volumes for high-throughput systems serving mobile processor and networking chip packaging. EU Green Deal energy benchmarks are accelerating replacement cycles for legacy thermocompression platforms in European automotive-facing plants.
- Test Equipment:Test handlers, probe stations, and final test systems absorb disproportionate capital intensity as heterogeneous integration multiplies die-level validation steps. South Korean memory manufacturers drive demand for high-pin-count contactors and thermal cycling chambers qualified to automotive stress protocols.
- Inspection Equipment:Automated optical inspection and X-ray systems verify bond placement integrity and void-free underfill distribution.
- Packaging Materials:Leadframes, substrates, mold compounds, and die attach adhesives represent recurring consumable expenditure.
Mature deployment sits with Assembly Equipment. Newer deployment is concentrated in Test Equipment.
Technology:
Interconnect pitch density and thermal performance requirements stratify equipment architectures across bonding platforms.
- Flip Chip:Controlled collapse chip connection technology enables sub-100 micrometer bump pitch for processor and networking applications. Taiwan's foundry-to-OSAT corridors anchor volume demand, with ASE and Amkor qualifying advanced thermal compression bonders for high-bandwidth memory integration.
- Thru-Silicon Via:Vertical interconnect stacks replace lateral routing constraints in high-bandwidth memory and AI accelerator packages. South Korean DRAM manufacturers and TSMC's CoWoS lines in Taiwan drive capital allocation toward deep reactive ion etching and chemical-mechanical planarization equipment.
- Wire Bonding:Fine-pitch ball and wedge bonding persists in cost-optimized consumer and automotive microcontroller packaging.
- Die Attach:Epoxy, soft solder, and silver-sintering attach methods address thermal conductivity requirements across power device and RF module applications.
Wire Bonding retains the largest installed base. Thru-Silicon Via is expanding most quickly in memory stack integration.
End User:
Application reliability standards and volume scale create divergent equipment specification requirements across downstream industries.
- Automotive Electronics:AEC-Q100 and AEC-Q104 qualification protocols demand test handlers capable of -40°C to +150°C thermal cycling with 1000+ hour validation documentation. German automotive Tier-1 suppliers and Chinese EV platform builders are driving silver-sintering die attach adoption for traction inverter power modules.
- Consumer Electronics:Smartphone and wearable device packaging prioritizes miniaturization and cost-adjusted throughput over extended reliability testing. Mainland China OSATs concentrate wire bonding and fan-out wafer-level packaging capacity for mature-node consumer chips.
- Telecommunications:Base station and optical networking equipment requires hermetic sealing and RF shielding validation.
- Industrial Electronics:Factory automation and power conversion applications specify extended temperature range operation.
Consumer Electronics maintains the broadest equipment footprint. Automotive Electronics is gaining share fastest on electrification capex.
Application:
Device electrical complexity and thermal dissipation requirements determine packaging hierarchy selection and corresponding equipment procurement.
- Integrated Circuits:Logic processors, memory devices, and mixed-signal chips span the full packaging technology spectrum from wire bonding to 3D stacking. Taiwan and South Korea concentrate advanced flip-chip and 2.5D interposer capacity for high-performance computing applications.
- Power Devices:Silicon carbide and gallium nitride discretes require specialized die attach and clip bonding equipment for high-current, high-temperature operation. European automotive suppliers and Chinese EV manufacturers are expanding packaging capacity for traction inverter modules.
- Sensors:MEMS accelerometers, gyroscopes, and environmental sensors demand cavity packaging and controlled atmosphere sealing.
- RF Devices:5G millimeter-wave and Wi-Fi 6E front-end modules require precision passive integration and electromagnetic shielding.
Integrated Circuits dominate capital deployment. Power Devices show the steepest expansion trajectory on electrification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the densest concentration of semiconductor packaging and test capacity worldwide, with foundry-to-OSAT corridors generating localized equipment procurement pull across Taiwan, South Korea, and mainland China.
Taiwan
ASE and SPIL drive demand for high-throughput wire bonders and thermal compression bonders serving mobile processor packaging. Taiwan's Environmental Protection Administration enforces wastewater and air emissions protocols that elevate operating costs for back-end facilities in Hsinchu and Tainan Science Parks. Kaohsiung's emerging advanced packaging cluster is attracting capital equipment vendors for proximity-matched spare parts logistics.
South Korea
Samsung Electronics and SK Hynix are expanding high-bandwidth memory stack capacity, accelerating capital allocation toward deep reactive ion etching and chemical-mechanical planarization equipment. MFDS pharmaceutical-grade traceability requirements are extending to semiconductor packaging serving medical device clients. Seoul-Pyeongtaek corridor concentrates memory packaging capacity with concentrated equipment procurement coordination.
China
JCET and Hua Tian Technology are scaling mature-node packaging for consumer and automotive microcontroller demand. GB standards for electronic product pollution control reshape material selection and process documentation across multinational supply chains. Wuxi and Suzhou industrial parks cluster OSAT capacity with localized equipment vendor qualification programs.
United States
Texas Instruments and Intel are expanding domestic advanced packaging capacity for defense and automotive qualification requirements. EPA emissions standards and FDA device-quality traceability protocols extend validation documentation burdens for packaging facilities serving medical and aerospace clients. Arizona's Phoenix metro area is attracting test equipment vendors for new fab-to-OSAT corridors.
Germany
Infineon and Robert Bosch are driving silver-sintering die attach adoption for traction inverter power modules in electric vehicle platforms. EU REACH substance restrictions on brominated flame retardants force 12-18 month material requalification cycles for epoxy mold compounds. Dresden's Silicon Saxony cluster concentrates automotive-facing packaging capacity with compressed compliance timelines under EU F-Gas Regulation phase-down schedules.
Global Semiconductor Equipment Packaging and Test Market Competitive Environment
The competitive structure tilts toward scale-driven OSATs with captive substrate capabilities. Three to four vertically integrated packaging houses command disproportionate capital equipment procurement influence through consolidated purchasing consortia. Two strategic archetypes dominate: full-service OSATs with in-house substrate fabrication, and specialized memory packaging houses with deep foundry partnerships. Competitive moves center on capacity expansion in Southeast Asian manufacturing nodes and strategic partnerships for heterogeneous integration process development.
Among Taiwan-based OSATs, ASE and SPIL exemplify the full-service archetype with integrated substrate and assembly capabilities. Amkor Technology anchors the multinational tier with geographic diversification across Southeast Asian manufacturing nodes. JCET represents the cost-optimized scale player competing aggressively on throughput-adjusted pricing for mature-node consumer and industrial segments.
| Leading Market Players |
|---|
| Siliconware Precision Industries (SPIL) |
| UTAC |
| Amkor Technology |
| JCET |
| ChipMos |
| ASE |
| STATS ChipPAC |
| Nepes |
| Powertech Technology |
| Others |
Value Chain & Pricing Dynamics
Gold wire spot volatility cascades through OSAT procurement tiers, compressing margin pools for wire bonding equipment vendors locked into long-term consumables contracts while amplifying price differentiation between premium thermal compression platforms and standard wire bonders serving cost-optimized consumer segments.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for test handler fleets, with premium tiers commanding yield-optimized thermal cycling precision while economy configurations compete on cost-per-wafer metrics. Price differentiation hinges on AEC-Q100 certification grade and geographic proximity to foundry clusters. Pricing pressure stems from palladium and gold wire volatility eroding consumables margins. Mature-node consumer packaging houses exhibit highest price sensitivity, whereas automotive-facing facilities prioritize qualification documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from tier-one OSATs require equipment vendors to qualify secondary component suppliers for thermal conditioning subsystems and precision alignment modules. Geographic concentration centers on Taiwan, South Korea, and Japan for ABF substrate fabrication and high-purity mold compound feedstock. Raw material dependencies include brominated epoxy resins, palladium-coated bonding wire, and fluorinated refrigerants for test handler chillers. Single-source vulnerability concentrates in Japanese substrate suppliers. Distribution runs through consolidated procurement consortia coordinating specifications across ASE, Amkor, and JCET.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ABF substrate fabrication bottlenecks prop equipment pricing power, constraining flip-chip ball grid array capacity expansion timelines and sustaining premium tier valuations for thermal compression bonders qualified to high-bandwidth memory integration protocols.
For Market Incumbents: Deepen captive substrate capabilities to defend margin pools against emerging fan-out wafer-level packaging entrants. Expand Southeast Asian manufacturing nodes to mitigate Taiwan environmental compliance cost escalation. Prioritize silver-sintering die attach R&D to capture traction inverter power module demand from German automotive Tier-1 suppliers. For New Entrants and Emerging Players: Hybrid bonding equipment for sub-10 micrometer pitch copper-to-copper interconnection offers white-space entry into high-bandwidth memory stack integration serving South Korean DRAM manufacturers. Target India's PLI-subsidized packaging facilities for mature-node consumer and automotive microcontroller demand. Lead with equipment-as-a-service pricing to penetrate cost-constrained mid-tier OSATs. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular platform specialists with reconfigurable wire bonding-to-flip-chip architectures in Taiwan and mainland China corridors. Long-term viability hinges on heterogeneous integration process development partnerships with foundry ecosystem players. Watch EU F-Gas Regulation phase-down compliance timelines as inflection signal for test handler thermal subsystem replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Equipment Development | Copper-to-copper direct bonding displaces thermocompression platforms in HBM stacks at Samsung and SK Hynix. |
| India PLI Scheme Capacity Buildout | Greenfield OSAT facilities in Gujarat and Karnataka create localized equipment procurement corridors. |
| EU F-Gas Regulation Compliance Transition | Refrigerant redesign for test handler chillers opens replacement cycles at Infineon Dresden operations. |
| Equipment-as-a-Service Model Launch | Pay-per-wafer pricing shifts capital burden from JCET balance sheets to vendor financing structures. |
| Photonics-Electronics Convergence Partnership | Co-packaged optics alignment equipment addresses AI training cluster demand at TSMC CoWoS lines. |
Study Parameters
Multi-period observation of capital expenditure patterns, equipment utilization rates, and substrate lead time indicators anchored the trend analysis, supplemented by interviews with OSAT procurement directors, semiconductor test engineering managers, and thermal subsystem design leads. Secondary validation drew from SEC equipment vendor filings, Taiwan EPA emissions disclosure databases, and EU REACH substance restriction registries. Bottom-up segment sizing triangulated against top-down foundry capacity expansion announcements.
Segment-weighting across equipment type, interconnect technology, and end-user application dimensions structured the analytical framework over the projection horizon. CAGRs derived from equipment shipment volume trajectories, replacement cycle compression factors, and technology transition elasticity coefficients. Forecast inputs incorporated EU Green Deal energy benchmark compliance costs and heterogeneous integration die count proliferation.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, abrupt precious metal price dislocations, and unannounced foundry process node transitions. Deviation in ABF substrate supply concentration or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market