
 Visual Computing Market | 2026-2036
Visual Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Visual Computing Market Outlook
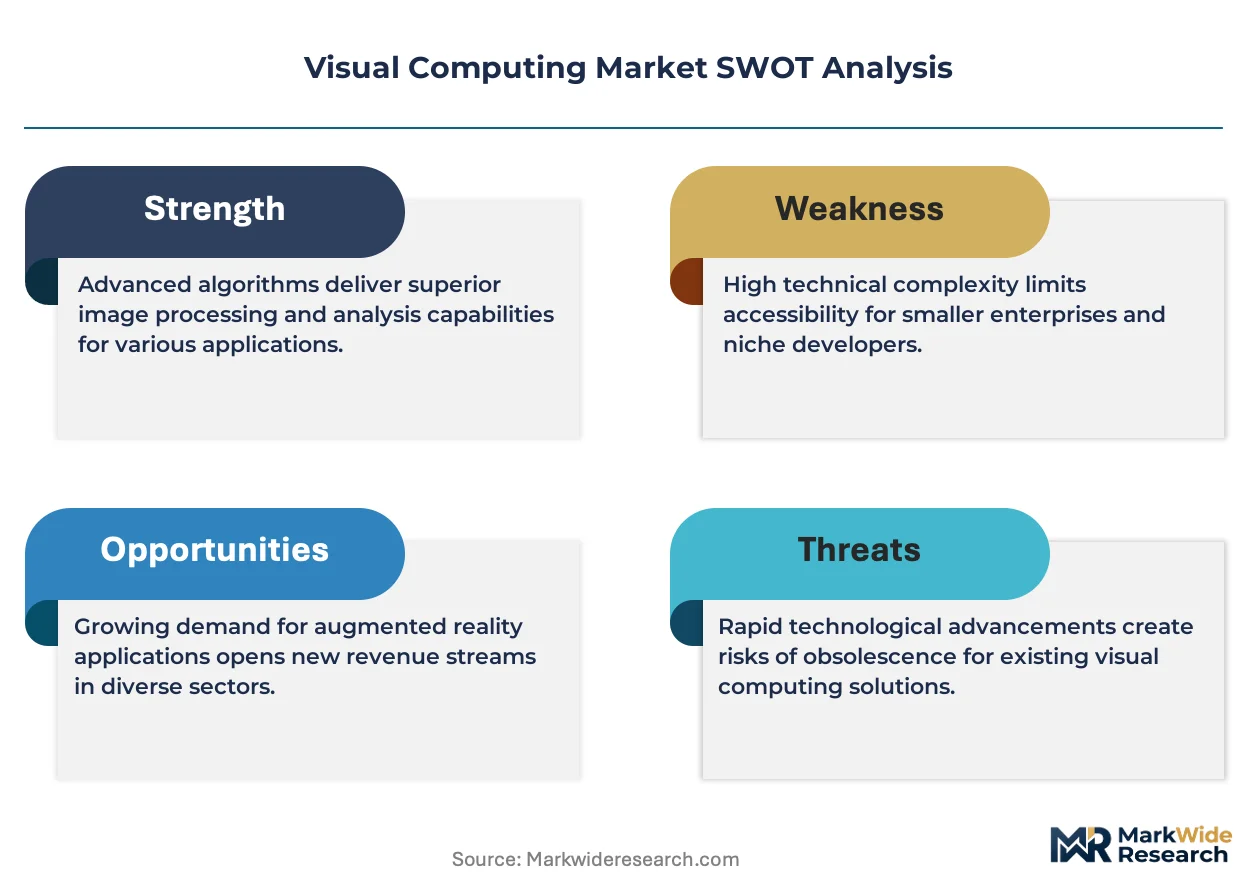
Medical imaging is restructuring demand patterns across the visual computing landscape as healthcare providers upgrade diagnostic visualization infrastructure. NVIDIA anchors the hardware layer through GPU architectures optimized for parallel image processing workloads. Cognex Corporation specializes in industrial machine vision systems, sustaining its position in factory automation quality control. Landing AI competes on data-centric AI platforms that reduce training data requirements for custom visual inspection models.
Visual computing encompasses the hardware, software, and algorithms that generate, process, analyze, and display visual information, typically operating on pixel throughput rates exceeding billions per second for real-time rendering pipelines. Its primary purpose spans interactive entertainment, scientific visualization, autonomous navigation, and computer-aided diagnostics where human or machine interpretation of visual data drives operational decisions. Graphics cards and rendering software capture the dominant margin pools, with ray tracing technology displacing rasterization in premium segments while machine learning accelerators represent the fastest-growing technology category as neural rendering techniques mature.
The FDA regulates medical imaging devices through premarket clearance pathways that mandate clinical validation of diagnostic visual outputs, while the FCC governs spectrum allocation for wireless AR/VR headsets and vehicle-to-infrastructure visual sensing links. The EU AI Act imposes conformity assessment obligations on high-risk biometric identification and emotion recognition systems, directly shaping product development roadmaps for European market access. Stakeholders must monitor evolving interoperability standards between proprietary rendering engines and open-source visualization frameworks to preserve deployment flexibility across regulated end-use environments.
Market Dynamics
Neural rendering techniques are compressing traditional rasterization pipelines as automotive OEMs and healthcare systems demand real-time photorealism from edge-deployed silicon. This architectural shift is redistributing value from discrete GPU vendors toward integrated AI accelerators.
Growth Catalysts
- EU AI Act biometric classification:Mandatory conformity assessments for emotion recognition and remote identification systems are creating certified-hardware procurement mandates across European industrial automation deployers.
- Autonomous vehicle perception hardware:German automotive OEMs are specifying multi-camera fusion architectures with dedicated neural processing units for Level 3+ highway automation.
- Ray tracing silicon maturation:Foundry capacity allocation toward 5nm and 3nm process nodes is enabling power-efficient real-time path tracing in mobile and embedded form factors.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and HBM interposer capacity constraints at Taiwanese foundries are throttling high-bandwidth memory integration for training-class accelerators.
- FDA premarket validation timelines:Diagnostic visualization devices face 18-36 month clearance pathways that compress commercialization windows for radiology AI startups.
- GaN and SiC power component costs:Wide-bandgap semiconductors essential for thermal management in dense compute clusters trade at 3-4x silicon MOSFET equivalents.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and testing are attracting visual computing module packaging investments.
- Neural radiance fields (NeRF) convergence:Scene reconstruction from sparse camera inputs is opening volumetric video applications in surgical planning and industrial digital twins.
- Japan METI carbon-neutral factory mandates:Energy-efficient visual inspection systems qualify for subsidies under the Green Transformation program.
Industry Challenges
- Compiler toolchain fragmentation:Proprietary kernel optimization layers across CUDA, ROCm, and oneAPI are fragmenting developer talent pools and extending model porting cycles.
- ISO/IEC 27001 certification for medical imaging cloud:Healthcare providers are demanding end-to-end information security management that delays SaaS visualization platform rollouts by 6-12 months.
- Legacy SCADA integration:Factory automation retrofits require protocol translation gateways between modern GigE Vision cameras and decades-old proprietary machine controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visual Computing Market |
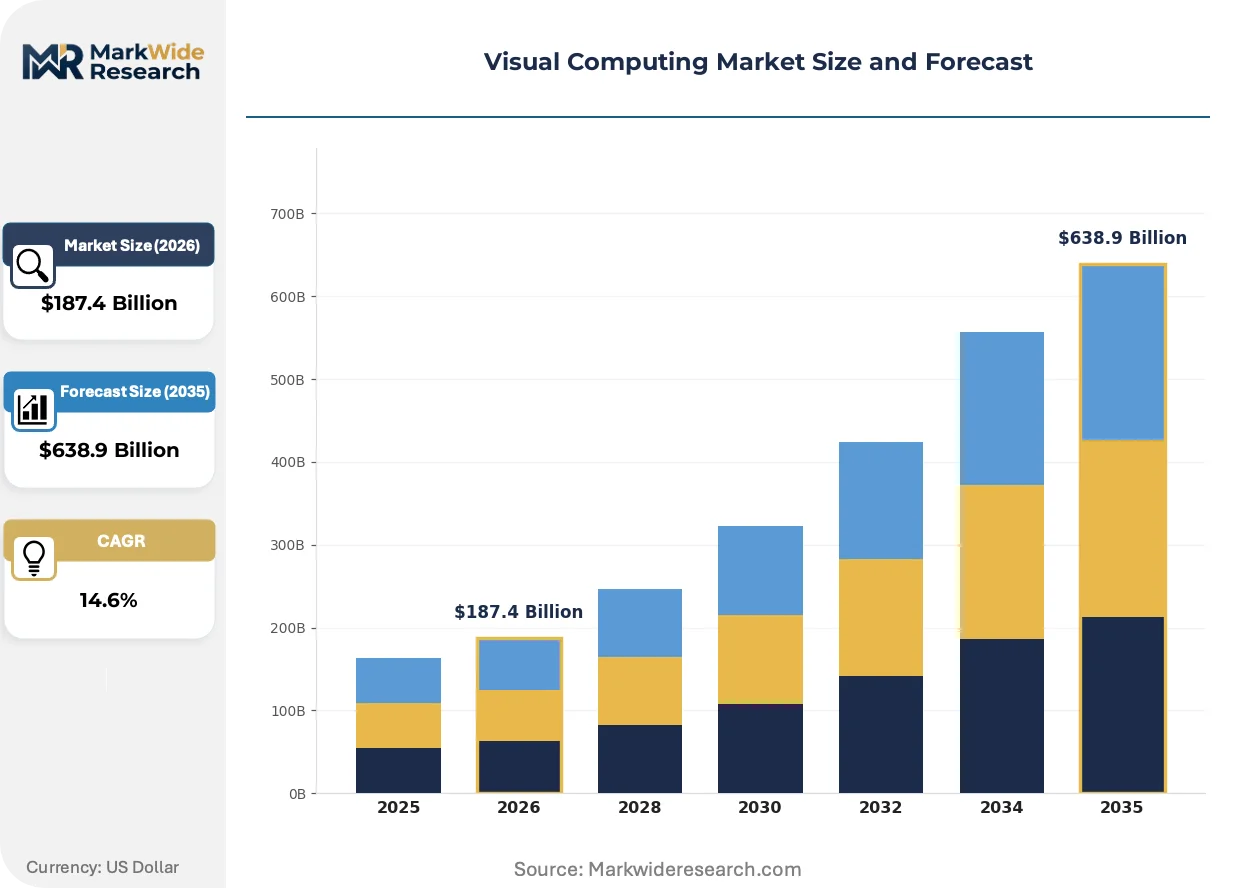
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Cards, Video Processors, Display Units, Rendering Software End User: Gaming, Film Production, Virtual Reality, Medical Imaging Technology: Ray Tracing, Rasterization, Machine Learning, Image Processing Application: 3D Modeling, Augmented Reality, Simulation, Animation |
| Companies Covered | Landing AI, Aurora Innovation, NVIDIA, Azumo, Vention, Cognex Corporation, Clarifai, Saritasa, Wildnet Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visual Computing Market Strategic Shifts
Real-time neural rendering is dissolving the boundary between precomputed graphics and interactive simulation. Three distinct vectors are reconfiguring how visual data is generated, governed, and consumed across industrial and consumer contexts.
Neural radiance fields are converging with light field displays to enable glasses-free 3D visualization for surgical planning and automotive HMI design. Medical device manufacturers in Germany and Japan are piloting NeRF-based preoperative modeling that reconstructs patient anatomy from standard CT stacks without specialized scanning hardware. This convergence is compressing the hardware requirements for immersive diagnostic review from dedicated VR headsets to conventional high-resolution panels.
The EU AI Act's risk-based classification for biometric identification is mandating conformity assessment bodies for computer vision systems deployed in public spaces. High-risk categorization for emotion recognition in workplace monitoring and educational settings is forcing vendors to rearchitect training data governance and model interpretability features. European industrial automation procurement specifications are now requiring CE-marked AI modules with documented technical file compliance.
Automotive Tier 1 suppliers are consolidating camera and lidar sensor procurement under single-source perception platform contracts that bundle silicon, software, and validation liability. This buying-pattern shift is displacing discrete component sourcing for German and Korean OEMs. Vertical integration into in-house neural network training is accelerating as manufacturers seek differentiation in object detection performance rather than hardware specifications alone.
Visual Computing Market Segmentation
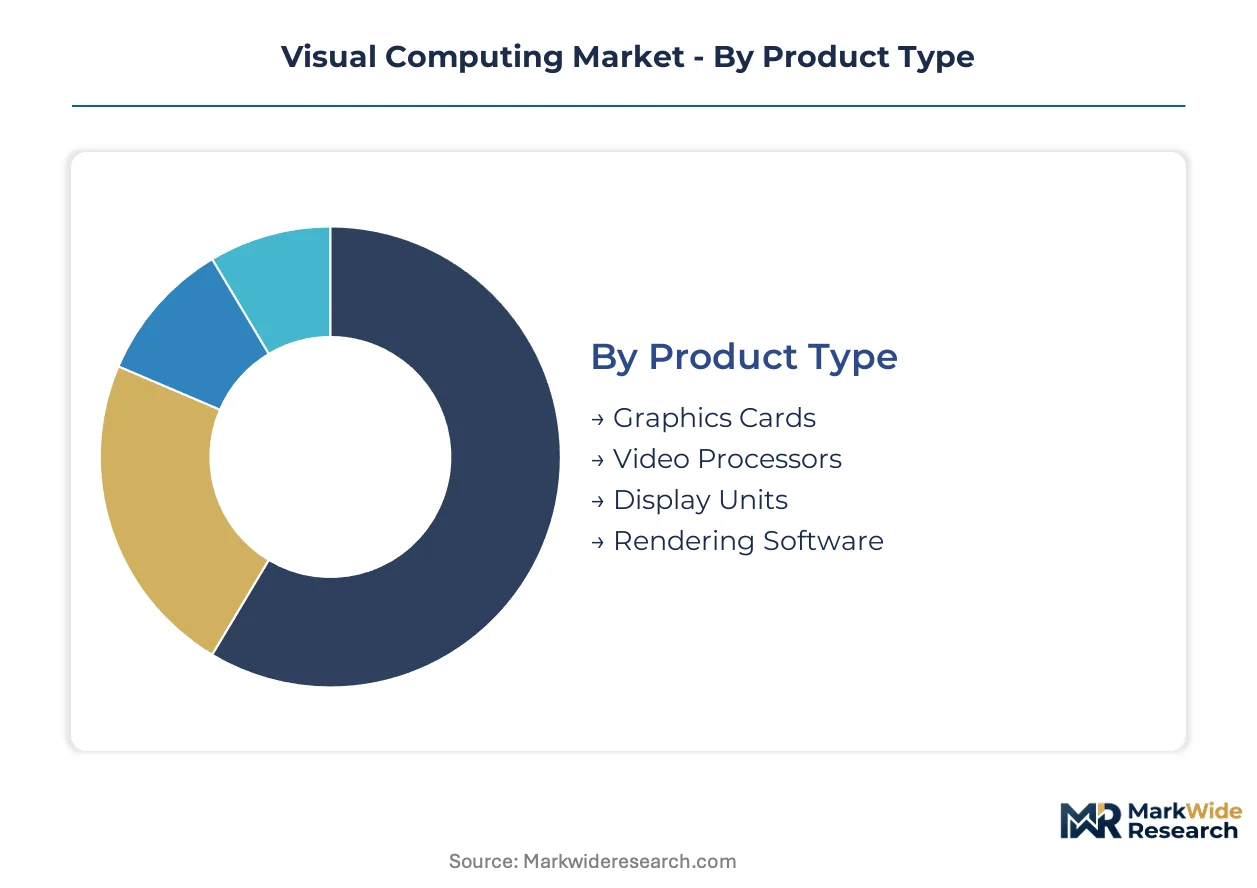
Visual computing segmentation maps directly to divergent margin structures across hardware and software layers. Product mix determines whether vendors capture recurring software revenue or compete on silicon bill-of-materials. End-use concentration in automotive and healthcare is reshaping which technology categories command procurement priority.
Product Type:
Graphics cards dominate unit volume while rendering software captures the premium margin tier. Hardware segments compete on memory bandwidth and thermal design power; software segments compete on licensing model and pipeline integration depth.
- Graphics Cards:Discrete GPU architectures with HBM3 memory stacks and 500W+ thermal envelopes. German automotive OEMs specify these for in-vehicle perception compute, though CoWoS packaging shortages constrain supply allocation.
- Rendering Software:Perpetual and subscription licensing for ray tracing and path tracing engines. Film production studios in Los Angeles and London drive demand for photorealistic batch rendering with USD pipeline compatibility.
- Video Processors:ASIC-based encode/decode silicon for streaming infrastructure. Content delivery networks deploy these at edge nodes for transcoding efficiency.
- Display Units:High-refresh-rate panels and projection systems for simulation environments. Military training contractors represent a concentrated procurement channel.
Today's leader: Graphics Cards. Tomorrow's challenger: Rendering Software.
End User:
Medical imaging commands the highest price per teraflop as FDA validation requirements filter out commodity competition. Gaming generates volume but compresses margins through annual refresh cycles and retail channel economics.
- Medical Imaging:Diagnostic visualization workstations with DICOM compliance and clinical workflow integration. FDA premarket clearance timelines of 18-36 months protect incumbents with validated installed bases.
- Virtual Reality:Enterprise training and surgical simulation systems with sub-20ms motion-to-photon latency. Healthcare providers in Germany and Japan are qualifying these for reimbursement under digital health pathways.
- Gaming:Consumer GPU procurement for real-time rasterization and emerging neural rendering. Mobile chipset integration is displacing discrete card attach rates in emerging markets.
- Film Production:Render farm infrastructure for visual effects and animated features. Cloud-based burst rendering is shifting capex to opex for mid-sized studios.
Medical imaging sustains pricing power; virtual reality is climbing the fastest.
Technology:
Machine learning accelerators are expanding most quickly as neural rendering displaces traditional pipelines. Ray tracing maturation is compressing the performance gap between offline and real-time production.
- Machine Learning:Tensor core architectures and dedicated inference silicon for neural denoising and super-resolution. Automotive perception stacks in Korea and Germany specify these for camera fusion workloads.
- Ray Tracing:Hardware-accelerated path tracing with bounding volume hierarchy traversal. Mobile SoC integration at 3nm process nodes is enabling handset-class real-time global illumination.
- Rasterization:Traditional z-buffer polygon rendering with shader programmability. Legacy game engine compatibility sustains demand despite architectural obsolescence.
- Image Processing:Computational photography pipelines and industrial inspection algorithms. Factory automation in Bavaria deploys these for defect detection at line speed.
Ray tracing owns the present narrative; machine learning owns the growth curve.
Application:
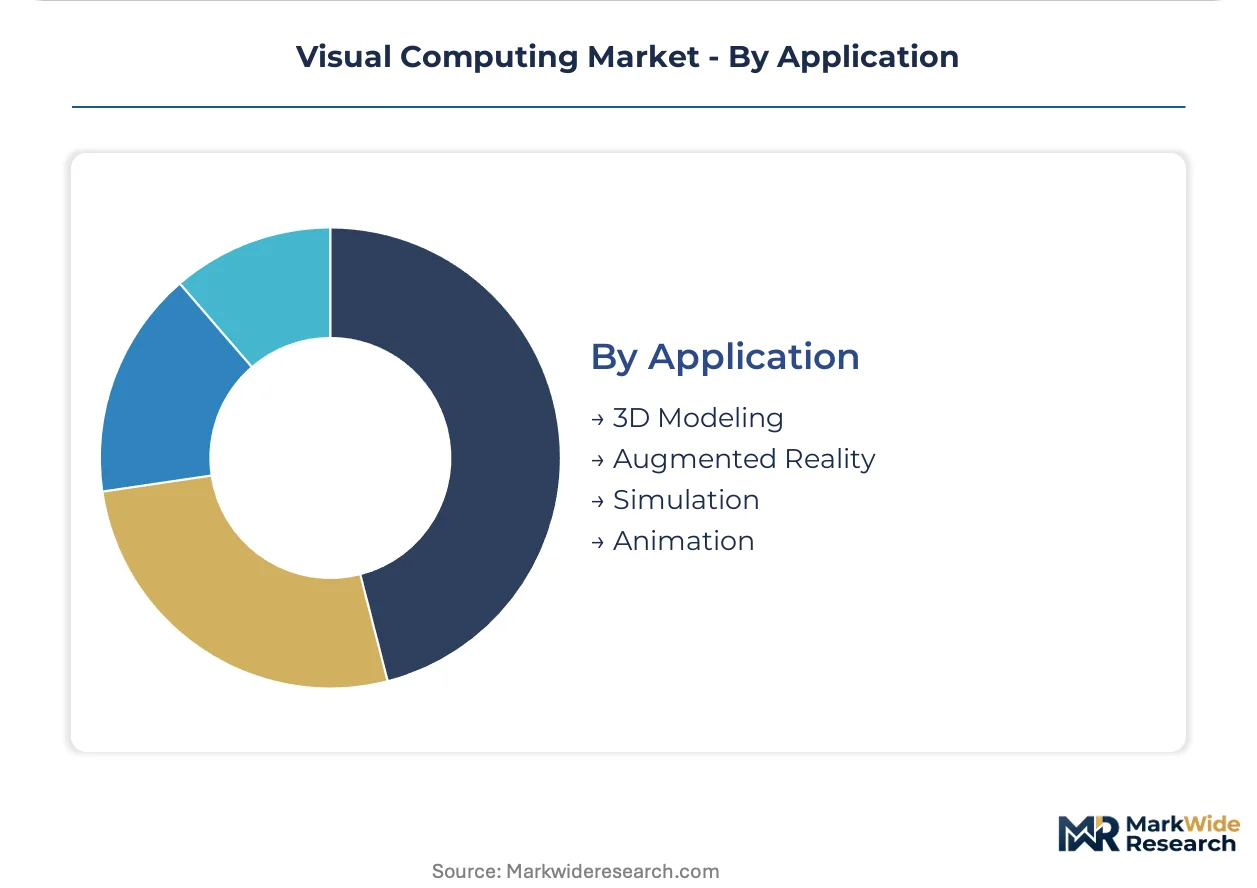
3D modeling anchors professional workstation procurement while augmented reality demands specialized optical and compute integration. Simulation applications are fragmenting across physics fidelity requirements and regulatory validation tiers.
- 3D Modeling:CAD and digital content creation tools with parametric surface manipulation. Industrial design studios in Milan and Detroit drive workstation GPU refresh cycles.
- Simulation:Physics-based digital twins for automotive crash testing and fluid dynamics. EU AI Act conformity assessments are adding compliance overhead for safety-critical visualization.
- Augmented Reality:See-through optics combined with spatial mapping compute. Enterprise maintenance applications in aviation are qualifying these for FAA operational approval.
- Animation:Character rigging and motion capture pipelines for entertainment production. Real-time engine adoption is collapsing traditional pre-rendered workflows.
3D modeling commands current share; augmented reality represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and industrial automation clusters anchor procurement intensity for specialized visual computing hardware across the analysis window.
United States
FDA premarket clearance pathways for diagnostic visualization devices filter out commodity competition in medical imaging. The FCC governs spectrum allocation for wireless AR/VR headsets and vehicle-to-infrastructure sensing links. Boston and Los Angeles clusters concentrate radiology AI startups and film production render farm infrastructure respectively.
Germany
Automotive OEMs specify multi-camera fusion architectures with dedicated neural processing units for Level 3+ highway automation. The EU AI Act imposes conformity assessment obligations on high-risk biometric identification systems deployed in industrial settings. Bavarian factory automation clusters deploy GigE Vision cameras for defect detection at line speed.
Japan
METI carbon-neutral factory mandates subsidize energy-efficient visual inspection systems under the Green Transformation program. PMDA regulatory timelines for medical device software validation protect incumbents with validated installed bases. Nagoya automotive suppliers consolidate perception platform procurement under single-source contracts.
South Korea
MFDS regulates diagnostic visualization workstations with clinical workflow integration requirements. Automotive Tier 1 suppliers specify camera and lidar sensor fusion for highway automation systems. Seoul-based electronics manufacturers drive demand for mobile SoC integration of real-time neural rendering.
India
The PLI scheme for electronics manufacturing attracts visual computing module packaging investments in semiconductor assembly and testing. BIS standards govern display unit safety certifications for industrial applications. Karnataka and Telangana clusters concentrate SaaS visualization platform development for healthcare providers.
Visual Computing Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bundle silicon, software, and validation liability under single-source contracts. The vendor base concentrates around three tiers: GPU architecture specialists, industrial machine vision incumbents, and data-centric AI platform challengers. Two archetypes define positioning: hardware-anchored incumbents with foundry relationships and software-native entrants with reduced training data value propositions. Competitive moves center on vertical integration into in-house neural network training and geographic expansion into subsidized manufacturing jurisdictions.
Within the hardware-anchored tier, NVIDIA and Cognex Corporation exemplify divergent specialization strategies. NVIDIA occupies a position spanning consumer graphics and automotive perception silicon. Cognex Corporation sits within the factory automation quality control segment. Landing AI represents the software-native archetype with data-centric platforms for custom visual inspection. Aurora Innovation and Clarifai anchor autonomous vehicle and general-purpose computer vision positioning respectively.
| Leading Market Players |
|---|
| Landing AI |
| Aurora Innovation |
| NVIDIA |
| Azumo |
| Vention |
| Cognex Corporation |
| Clarifai |
| Saritasa |
| Wildnet Edge |
| Others |
Value Chain & Pricing Dynamics
GPU compiler engineers concentrated in Santa Clara and Hsinchu command wage premiums that compress margin spreads between premium HBM3 stacks and standard GDDR6 configurations. Labor-cost differentials between Taiwan foundry zones and Indian assembly clusters translate directly into pricing-tier spreads across automotive perception modules and medical imaging workstations.
Pricing Analysis
Input-cost pass-through from CoWoS packaging shortages and HBM3 memory supply constraints is intensifying margin pressure at the premium tier. Pricing stratifies across FDA-cleared medical devices, CE-marked industrial automation modules, and uncertified consumer graphics cards. Cost compression in the mid-tier is accelerating because mobile SoC neural rendering is displacing discrete GPU attach rates. Healthcare providers in Germany and Japan exhibit the lowest price sensitivity due to reimbursement-protected procurement budgets, while Southeast Asian gaming distributors face acute margin compression from retail channel economics.
Supply Chain Analysis
Reverse-logistics flows for refurbished enterprise GPUs and remanufactured industrial cameras are creating secondary supply channels that discipline primary pricing. Geographic concentration centers on Taiwan for advanced packaging and foundry services, South Korea for HBM memory fabrication, and China for display panel and camera module assembly. Raw material dependencies include silicon wafers, rare-earth phosphors for display backlights, and high-purity copper for interconnect substrates. Single-source vulnerability at TSMC's CoWoS capacity represents the dominant structural risk. Distribution runs through direct OEM contracts for automotive Tier 1 suppliers and specialized industrial distributors for factory automation deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's biometric conformity assessment mandates compound procurement requirements, converting regulatory compliance into a sustained demand driver across European industrial automation.
For Market Incumbents: Lock in foundry allocation agreements for 3nm and 5nm process nodes before capacity constraints deepen. Secure FDA and CE marking for neural rendering pipelines ahead of diagnostic visualization standardization. The threat of data-centric AI platforms reducing training data requirements demands defensive certification investment in interpretability features. Backward integration into in-house compiler toolchains preserves optimization advantages against ROCm and oneAPI fragmentation. For New Entrants and Emerging Players: Launch via India PLI-subsidized assembly partnerships to bypass Taiwan packaging bottlenecks. Target surgical planning applications in German university hospitals where NeRF-based preoperative modeling lacks incumbent validation. White-space concentration exists in energy-efficient visual inspection systems qualifying for Japan METI Green Transformation subsidies. The most penetrable segment comprises mid-sized automotive Tier 2 suppliers seeking perception platform alternatives to single-source contracts. For Investors and Strategic Acquirers: German automotive OEMs are the most active acquirer in this space, consolidating camera-lidar fusion capabilities under captive silicon strategies. Long-term viability hinges on neural rendering patent portfolios and validated clinical installed bases. Acquisition target archetypes include industrial machine vision specialists with GigE Vision protocol expertise and radiology AI startups with FDA 510(k) clearances. Watch for EU AI Act enforcement actions against non-conforming biometric systems as an inflection indicator for certified-hardware procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU AI Act conformity assessments mandate documented technical files for biometric systems in Bavarian factories. |
| Neural Rendering Patent Acquisition | Intellectual property in NeRF reconstruction secures differentiation against rasterization incumbents in surgical planning. |
| India PLI Manufacturing Footprint | Production-linked incentives for semiconductor testing reduce dependency on Taiwan packaging capacity constraints. |
| FDA 510(k) Diagnostic Clearance | Premarket validation timelines protect radiology AI vendors from commodity competition in DICOM-compliant workstations. |
| Automotive Tier 1 Partnership | Single-source perception platform contracts bundle silicon, software, and liability for Korean highway automation systems. |
Study Parameters
Bottom-up automotive and healthcare demand modeling reconciled against top-down foundry capacity and silicon supply tracking forms the analytical core. Primary interviews with GPU architecture product managers, automotive Tier 1 procurement officers, FDA regulatory consultants, hospital biomedical engineers, and industrial automation plant engineers combined with secondary validation from SEC filings, EU AI Act implementation guidance, TSMC investor presentations, and PMDA medical device registration databases. Triangulation across these sources calibrated shipment forecasts against wafer allocation disclosures.
Input-output matrices map neural processing unit die sizes to automotive perception compute requirements, ray tracing core counts to film production render farm specifications, and ML accelerator TOPS to medical imaging inference latency targets. Segmentation dimensions span product type, end-use vertical, technology category, and application with geographic regulatory cluster overlays. CAGRs derive from installed base replacement cycles, OEM platform roadmaps, and reimbursement pathway approvals without year-specific milestone anchoring. Forecast inputs include CoWoS capacity expansion schedules and EU conformity assessment body accreditation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry geopolitical disruption or accelerated FDA breakthrough device designation pathways. Forecasts reflect assumptions regarding neural rendering adoption curves, automotive Level 3 automation regulatory approvals, and healthcare provider digital health reimbursement expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Medical Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Commercial Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
LCD Panel Market
Display Technologies
OLED Display Market
Display Technologies
Phosphor Screen Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Global Display Market
Display Technologies
Display Port Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Touch and Display Integration IC for Tablet Market