
 Global Portable Monitor Market | 2026-2036
Global Portable Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Monitor Market Outlook
OLED panel substrates is hardening cost structures for premium portable monitors as manufacturers shift from traditional LED backlights. Dell leverages in-house display engineering to sustain pricing power across corporate channels. AsusTek Computer Inc. anchors its position through R&D intensity in gaming-oriented high-refresh panels. Samsung Electronics Co., Ltd. dominates OLED supply chains through captive production of mobile-grade substrates.
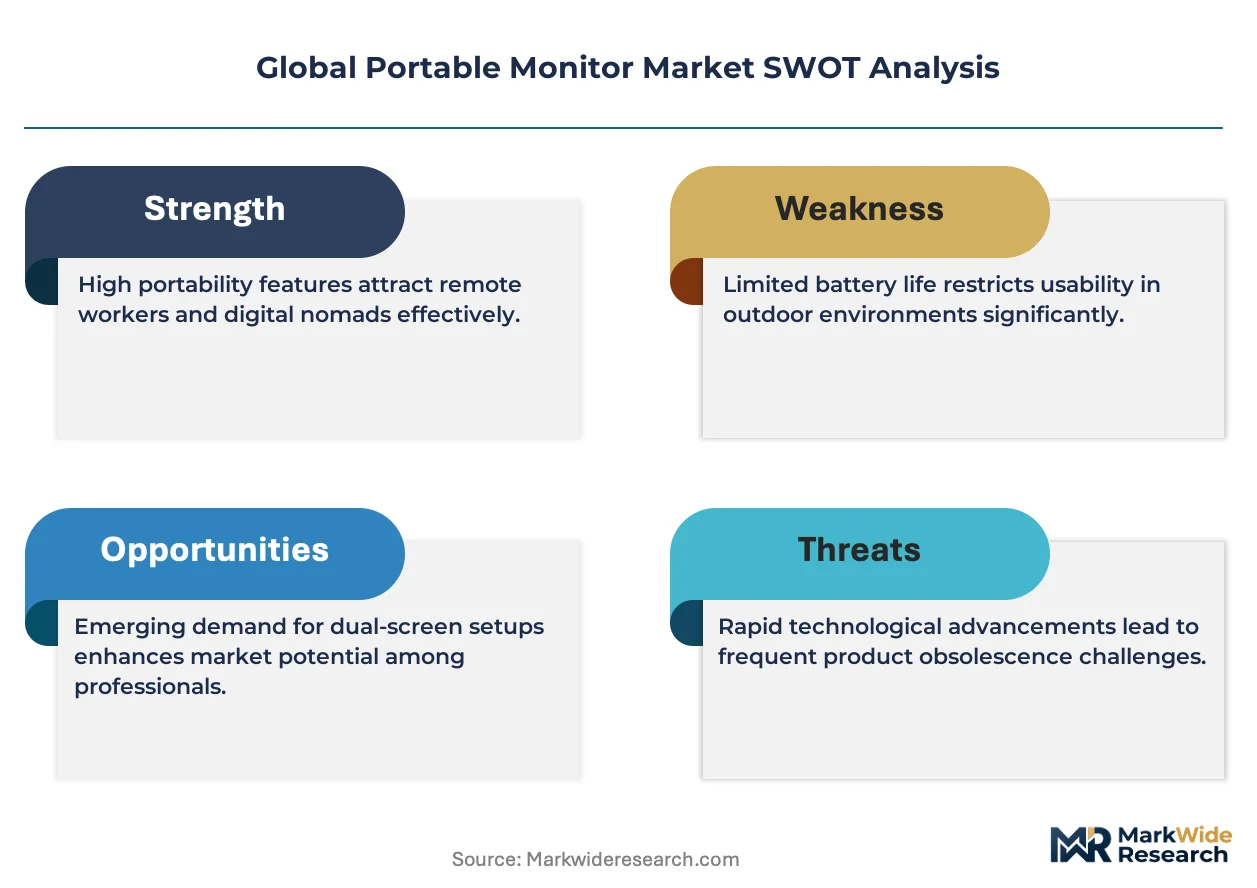
A portable monitor is a lightweight, externally powered display unit typically measuring 13 to 17 inches diagonally, employing LCD, LED, or OLED pixel technologies and connecting via USB-C, wireless protocols, or HDMI to extend screen real estate for laptops and mobile devices. IPS configurations lead volume shipments due to color accuracy requirements from creative professionals, while OLED commands margin pools in the premium tier where gamers and business professionals prioritize contrast ratios. USB-C technology is displacing proprietary docking solutions as single-cable video and power convergence simplifies mobile workstation setups.
FCC electromagnetic emissions standards in the US, CE marking requirements under EU RoHS and REACH frameworks, and China's GB standards enforced by SAMR collectively govern display safety, material composition, and wireless transmission protocols across major demand centers. These frameworks elevate compliance costs for entrants but protect established OEMs with certified supply chains. Stakeholders must monitor evolving USB-C power delivery certifications and regional e-waste directives as determinants of product refresh viability and market access continuity.
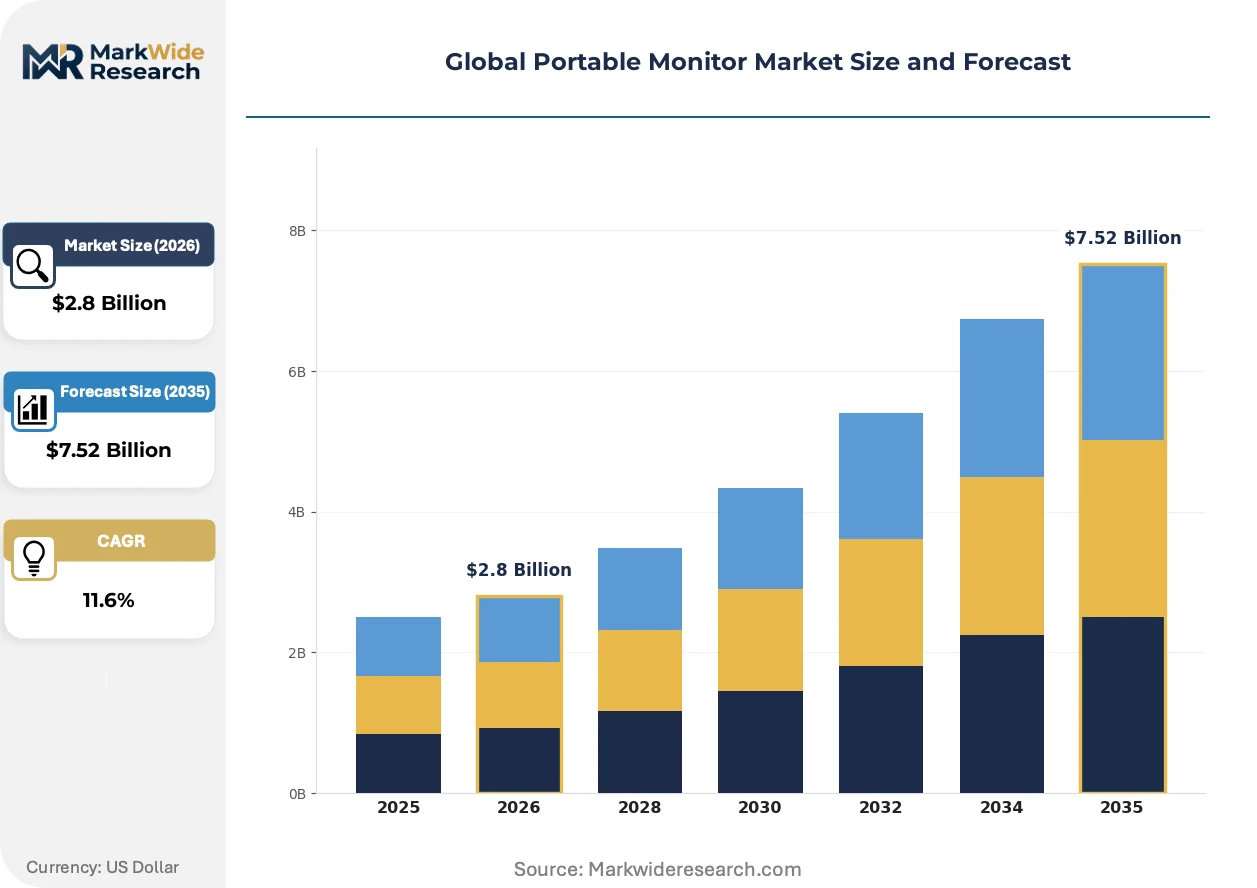
Market Dynamics
USB-C power delivery standardization from the IEC is compressing proprietary docking ecosystems while Shenzhen-based panel sourcing clusters concentrate supply-side leverage among contract manufacturers.
Growth Catalysts
- Remote freelance workforce expansion:Hardware refresh cycles accelerate as distributed professionals invest in mobile workstation setups requiring secondary displays.
- IEC 62680 USB-C certification:Universal compatibility mandates reduce interoperability friction and expand addressable device pairings across laptop and tablet ecosystems.
- OLED substrate maturation:Mobile-grade OLED production scaling enables premium tier expansion with contrast ratios exceeding IPS alternatives.
Market Restraints
- OLED input cost volatility:Organic emitter material pricing fluctuates with rare earth supply constraints from concentrated mining jurisdictions.
- Shenzhen supply cluster concentration:Panel sourcing and final assembly dependence on single metropolitan manufacturing basin creates geopolitical exposure.
- FCC electromagnetic emissions compliance:Certification timelines and testing costs erect barriers for unestablished entrants lacking certified supply chain partnerships.
Strategic Opportunities
- India underpenetrated demand:BIS certification alignment with IEC standards enables market entry as remote work adoption spreads among IT services professionals.
- Gaming-optimized high-refresh panels:Esports and mobile gaming segments seek 120Hz+ refresh rates currently underserved by standard productivity-focused offerings.
- EU e-waste directive alignment:CSRD reporting requirements and REACH material compliance create preference for modular, repairable designs with standardized component interfaces.
Industry Challenges
- Display calibration talent scarcity:Factory color accuracy tuning for creative professional segments requires specialized expertise concentrated among veteran panel engineers.
- USB-IF certification backlog:Power delivery and alternate mode verification queues delay product launch windows for manufacturers without existing certification relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Monitor Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, IPS Technology: Touchscreen, Non-Touchscreen, Wireless, USB-C End User: Freelancers, Gamers, Business Professionals, Students Size: 13-inch, 15-inch, 17-inch, 19-inch |
| Companies Covered | Lenovo Group Limited, Dell, AsusTek Computer Inc., HP Inc., Acer Inc., LG Electronics, ViewSonic Corporation, Samsung Electronics Co., Ltd., AOC Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Monitor Market Strategic Shifts
Display interface architectures and power management protocols are undergoing rapid consolidation, with single-cable solutions displacing multi-connector legacy configurations across professional and consumer segments.
USB-C DisplayPort alternate mode is converging with 100W power delivery to enable true single-cable monitor operation. Corporate procurement teams now mandate this configuration for mobile workstation deployments. The technology is converging with wireless casting protocols to create hybrid wired-wireless ecosystems that reduce desk clutter while maintaining latency performance.
EU REACH substance restrictions and RoHS material mandates are forcing reformulation of solder alloys and PCB substrates. Manufacturers must requalify supply chains for cadmium and lead-free compliance. Premium tier products targeting creative professionals face the strictest enforcement timelines under ECHA substance evaluation protocols.
Direct-to-consumer channel expansion is compressing traditional electronics retail margins. Shenzhen OEMs now sell branded portable monitors through proprietary storefronts, bypassing distributor markups. This pattern is most visible in North American and Western European markets where Amazon Marketplace saturation enables rapid brand building without physical retail presence.
Global Portable Monitor Market Segmentation
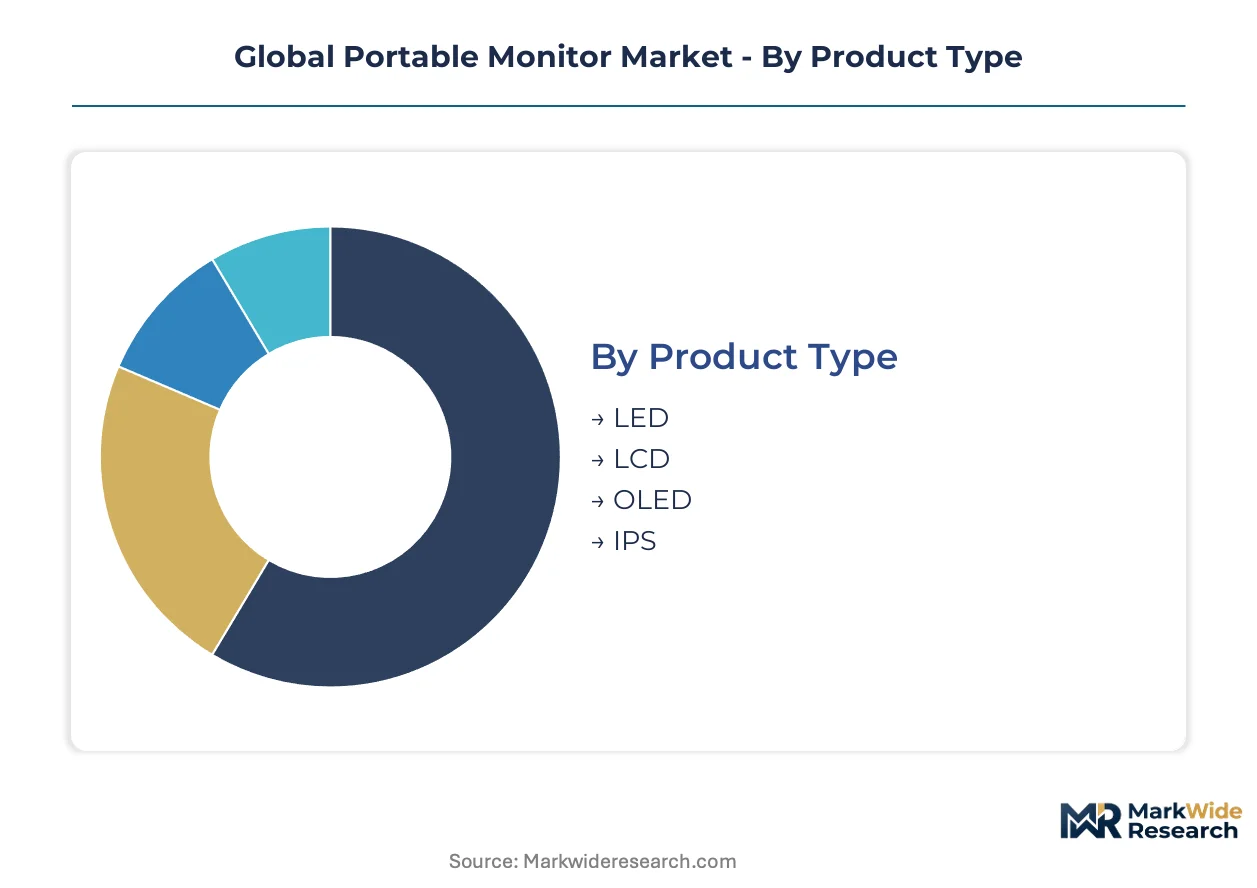
Portable monitor purchasing patterns diverge sharply across display technologies, connectivity protocols, and professional use cases. Upgrade cycles vary from eighteen months for gaming enthusiasts to four-plus years for enterprise procurement teams. Understanding these segment boundaries clarifies where product development investments yield disproportionate returns.
Product Type:
Upgrade cycles for display panels correlate directly with backlight technology maturity and manufacturing yield improvements.
- LED:Edge-lit LED configurations dominate volume shipments through cost efficiency in 15-inch and 17-inch form factors. Procurement from Shenzhen contract manufacturers sustains pricing accessibility for student and entry-level freelancer segments.
- LCD:Traditional cold cathode fluorescent lamp backlights persist in ultra-budget tiers where panel longevity outweighs color gamut requirements. Demand concentrates in emerging markets with limited IEC 62680 USB-C device penetration.
- OLED:Mobile-grade organic substrates deliver contrast ratios exceeding 1,000,000:1 through self-emissive pixel architecture. Premium tier expansion accelerates among gamers and creative professionals in Germany and South Korea where ECHA REACH compliance certifies material safety.
- IPS:In-plane switching liquid crystal alignment maintains 178-degree viewing angles essential for collaborative workflows. Color accuracy requirements from US-based video editors and Japanese content creators sustain volume leadership.
Volume placements concentrate in IPS configurations; the faster expansion belongs to OLED substrates.
Technology:
Connectivity protocol selection determines compatibility breadth and power delivery integration depth.
- Touchscreen:Projected capacitive digitizers enable stylus input for annotation workflows. US and UK graphic designers drive adoption where FCC electromagnetic emissions certification validates interference resilience.
- Non-Touchscreen:Passive display architectures minimize cost and weight for pure screen extension use cases. Enterprise procurement in France and Italy under EU Green Deal sustainability mandates favors repairable non-touch designs.
- Wireless:Wi-Fi Display and Miracast protocols eliminate cable clutter for hybrid meeting room deployments. Latency constraints limit penetration to presentation-centric business professionals rather than gaming segments.
- USB-C:Single-cable video, data, and 100W power convergence simplifies mobile workstation logistics. IEC 62680 certification alignment accelerates replacement of proprietary docking ecosystems across corporate IT refresh cycles.
Shipment volumes cluster in USB-C implementations; wireless connectivity claims the steepest expansion trajectory.
End User:
Professional identity shapes performance requirements, portability priorities, and budget authorization levels.
- Freelancers:Distributed knowledge workers operating from co-working spaces and home offices require lightweight 15-inch panels with universal laptop compatibility. Hardware refresh cycles compress to twenty-four months as USB-C standardization enables seamless device transitions.
- Gamers:Esports participants and mobile gaming enthusiasts prioritize 120Hz+ refresh rates and sub-5ms response times. Premium pricing tolerance supports OLED adoption where contrast performance enhances competitive visibility.
- Business Professionals:Corporate road warriors demand single-cable simplicity and aircraft-carry-on dimensions. Procurement departments in Japan and Singapore mandate three-year warranty terms and METI-aligned energy efficiency ratings.
- Students:Price-sensitive academic users accept 13-inch form factors and 60Hz limitations for secondary screen functionality. Back-to-school seasonal demand concentrates in India and Brazil where BIS and ANVISA certifications govern market access.
Freelancers generate the highest absolute unit demand; gamers exhibit the fastest adoption velocity for premium specifications.
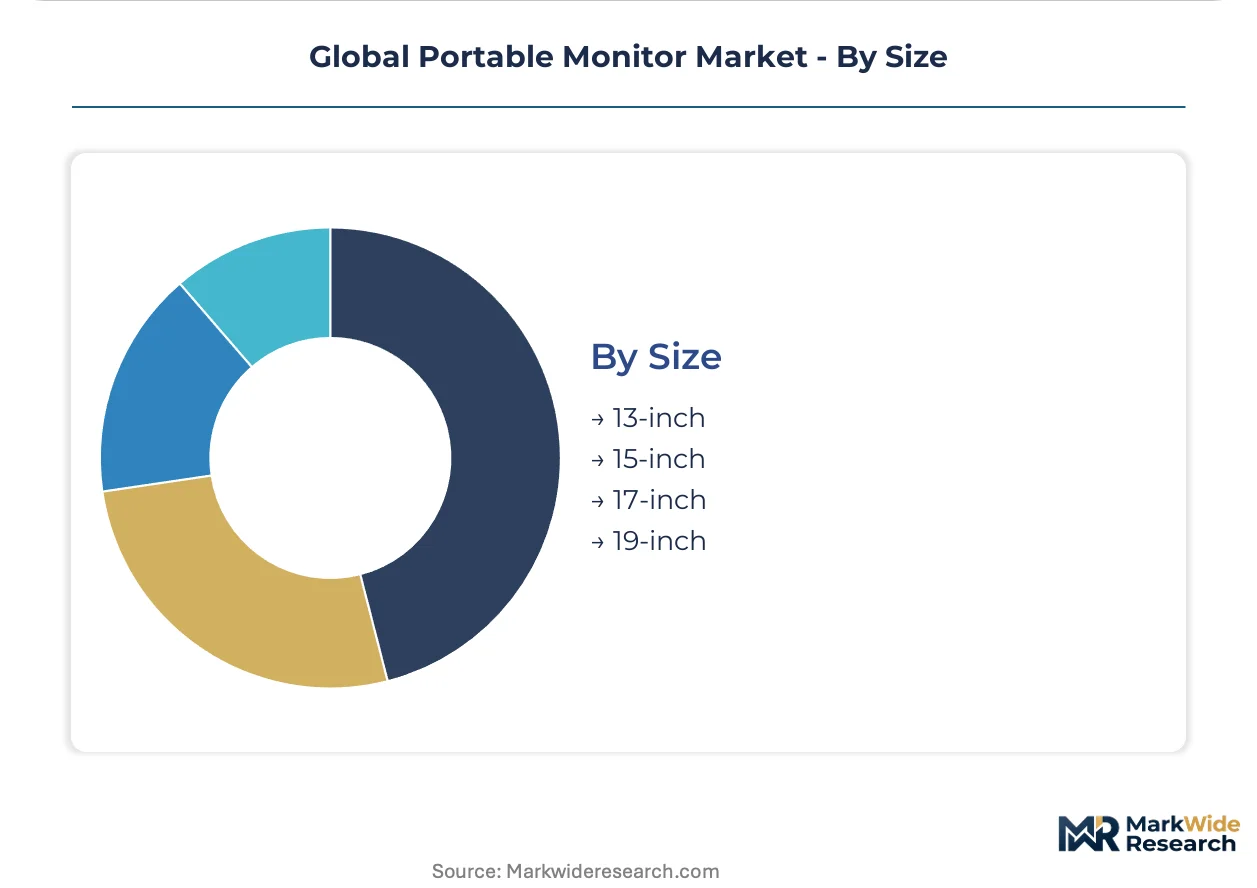
Size:
Diagonal dimension selection balances screen real estate against travel weight constraints and power draw limitations.
- 13-inch:Ultra-portable dimensions under 800 grams suit tablet companion use and airline tray table deployment. Student and mobile professional segments in compact urban environments favor this footprint.
- 15-inch:The volume anchor matches standard laptop dimensions for symmetrical dual-screen arrangements. Freelancers and business professionals across Germany, UK, and US standardize procurement on this form factor.
- 17-inch:Desktop replacement scale enables spreadsheet and timeline workflows without external monitor dependency. Creative professionals and financial analysts accept the 1.2kg weight penalty for productivity gains.
- 19-inch:Niche desktop extension panels target semi-permanent home office installations rather than true mobility. Limited USB-C power delivery compatibility constrains addressable device pairings.
Manufacturing output centers on 15-inch panels; 17-inch configurations gain share fastest among remote work infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the highest absolute demand for portable monitors, with Shenzhen-based OEMs controlling panel sourcing and final assembly. Remote work infrastructure investments across Germany, the United States, Japan, and India generate differentiated growth vectors shaped by local certification requirements and professional segment priorities.
China
Domestic demand from freelancers and mobile professionals accelerates hardware refresh cycles in tier-one cities. SAMR enforces GB standards for display safety and electromagnetic compatibility, elevating compliance costs for entrants. Shenzhen manufacturing clusters dominate OLED panel sourcing and USB-C assembly, with contract manufacturers consolidating leverage over global supply chains.
Germany
Creative professionals and business road warriors drive premium-tier adoption of IPS and OLED configurations. ECHA REACH substance restrictions and RoHS material mandates force reformulation of solder alloys and PCB substrates. Industrial concentration in Bavaria and Baden-Württemberg hosts corporate procurement teams mandating three-year warranty terms and modular repairable designs.
United States
Freelance workforce expansion and hybrid office deployments sustain demand for 15-inch USB-C panels. FCC electromagnetic emissions certification creates barriers for unestablished players lacking tested supply chain partnerships. Seattle and Austin metropolitan areas concentrate remote technology workers prioritizing single-cable mobile workstation setups.
Japan
Corporate procurement teams in Tokyo and Osaka standardize on lightweight 15-inch form factors with METI-aligned energy efficiency ratings. Technical standards for wireless transmission protocols govern Miracast and Wi-Fi Display implementations in business meeting room deployments. Kanto region electronics distributors maintain stringent three-year warranty requirements for enterprise channel access.
India
IT services professionals and student segments generate underpenetrated demand for entry-level 13-inch and 15-inch panels. BIS certification alignment with IEC 62680 USB-C standards enables market entry for international manufacturers. Bengaluru and Hyderabad technology corridors concentrate remote work adoption among software developers seeking secondary display solutions.
Global Portable Monitor Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium tiers consolidating around display engineering capabilities and volume tiers fragmenting among Shenzhen-based OEMs. Three archetypes dominate: multinational electronics conglomerates with captive panel supply, dedicated display peripheral specialists, and direct-to-consumer contract manufacturers bypassing traditional distribution. Competitive moves center on backward integration into OLED substrate sourcing and geographic expansion through India BIS certification alignment.
Among multinational electronics conglomerates, Lenovo Group Limited and Dell exemplify the corporate channel archetype through in-house display engineering and enterprise procurement relationships. Samsung Electronics Co., Ltd. anchors the premium tier through captive production of mobile-grade OLED substrates. AsusTek Computer Inc. occupies a position within the gaming-oriented specialist tier, with R&D intensity in high-refresh panel configurations distinguishing its competitive posture.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| Dell |
| AsusTek Computer Inc. |
| HP Inc. |
| Acer Inc. |
| LG Electronics |
| ViewSonic Corporation |
| Samsung Electronics Co., Ltd. |
| AOC Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
OLED-IPS divergence in panel performance hardens a bifurcated cost structure where premium substrates command margin pools while Shenzhen-sourced LED configurations compete on unit economics. This tier split manifests in procurement patterns: corporate buyers absorb OLED premiums for color accuracy, while student and entry-level freelancer segments concentrate demand in 15-inch LED panels where contract manufacturing scale compresses landed costs.
Pricing Analysis
Volume shipments cluster in IPS and LED configurations where Shenzhen contract manufacturing sustains accessible price points for 15-inch student and freelancer segments. Premium-mid-economy pricing differentiation rests on panel substrate technology and IEC 62680 USB-C certification alignment. Cost compression in LED tiers is intensifying because panel oversupply from Chinese OLED conversion investments spills into legacy backlight categories. Students exhibit the highest price sensitivity, while gamers and creative professionals tolerate OLED premiums for contrast performance.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions and transpacific rate spikes feeds directly into landed cost calculations for North American and European distributors. Panel sourcing draws from China, South Korea, and Taiwan, with mobile-grade OLED substrates anchored in Samsung and LG captive production. Rare earth supply constraints for organic emitter materials create single-source vulnerability for premium tier manufacturers. Distribution runs through Amazon Marketplace direct-to-consumer storefronts and enterprise IT procurement channels, bypassing traditional electronics retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable monitor competition is converging into a vertical-integration race where captive OLED substrate supply and certified USB-C power delivery integration determine margin sustainability. Players lacking upstream panel relationships or downstream certification velocity face displacement.
For Market Incumbents: Deepen backward integration into mobile-grade OLED substrate sourcing to defend margin pools against Samsung and LG captive supply advantages. Fortify IEC 62680 certification relationships with USB-IF to compress launch windows, as certification backlog delays threaten product cycle alignment with corporate IT refresh timelines. For New Entrants and Emerging Players: Begin with India BIS certification alignment for 13-inch and 15-inch USB-C panels targeting Bengaluru and Hyderabad IT services corridors. White-space concentration exists in gaming-optimized 120Hz+ refresh rate segments where AsusTek R&D intensity has not fully saturated demand. Direct-to-consumer Amazon storefront launch bypasses distributor margin extraction. For Investors and Strategic Acquirers: Re-rating potential sits with display peripheral specialists possessing USB-IF certification relationships and Shenzhen assembly partnerships given IEC standardization catalysts compressing proprietary ecosystem viability. Long-term viability over a multi-year window favors targets with modular repairable design capabilities aligned to EU e-waste directives. Monitor USB-IF certification queue lengths as inflection indicator for product launch velocity disparities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OLED Substrates | Captive mobile-grade panel supply secures contrast performance differentiation against IPS alternatives. |
| IEC 62680 USB-C Certification Investment | Single-cable power and video convergence mandates displace proprietary docking ecosystems in corporate procurement. |
| Direct-to-Consumer Channel Expansion | Amazon Marketplace storefronts bypass distributor markups and compress customer acquisition costs in North America. |
| Gaming-Optimized High-Refresh Panel R&D | 120Hz+ configurations capture esports segment pricing tolerance currently underserved by productivity-focused offerings. |
| EU E-Waste Directive Alignment | Modular repairable designs with standardized component interfaces secure preference under CSRD reporting requirements. |
Study Parameters
Multi-period observation of panel substrate pricing, USB-C certification timelines, and OEM shipment patterns anchored the trend analysis, supplemented by interviews with display engineering directors, contract manufacturing procurement leads, corporate IT refresh managers, and Amazon Marketplace vendor operations heads. Secondary validation drew from SEC 10-K filings of listed electronics conglomerates, USB-IF certification databases, IEC standards documentation, and customs trade data from major demand centers. Bottom-up shipment estimates by panel technology and connectivity protocol triangulated against top-down market sizing from OEM revenue disclosures.
Segment-weighting approaches applied differential growth assumptions across OLED, IPS, and LED technology tiers, USB-C versus wireless connectivity implementations, and freelancer versus gamer versus business professional end-use categories. CAGRs were derived from installed base replacement cycles, remote work infrastructure investment trajectories, and panel cost curve projections across the analysis window. Forecast inputs incorporated OLED substrate yield improvements, IEC 62680 adoption curves, and regional certification timeline differentials.
Underlying measurement precision varies by segment; USB-C shipment volumes carry tighter precision than wireless connectivity estimates due to certification database transparency. Forecasts reflect documented assumptions regarding remote work permanence, USB-C standardization velocity, and OLED cost curve trajectories. Panel supply disruptions, geopolitical trade restrictions, or regulatory timeline accelerations could materially revise trajectory outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Portable Projector Market
Display Technologies
North America Head-Up Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Phosphor Screen Market
Display Technologies
Flexible Screens Market
Display Technologies
Touch Screen Film Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Global Display Controllers Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Microdisplay Market
Display Technologies
Display Glass Substrate Market
Display Technologies
OLED Panel Market