

In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market Size, Share, and Industry Trends Forecast 2026-2036
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market Insights
Sub-angstrom measurement precision is redrawing competitive boundaries in semiconductor metrology. KLA Corporation leverages its installed base of optical critical dimension platforms to sustain dominance in high-volume manufacturing environments. Applied Materials anchors its position through integrated process control solutions that bridge deposition and metrology workflows. Onto Innovation differentiates via specialized overlay systems designed for EUV double-patterning regimes.
In-line overlay and critical dimension metrology for sub-3nm nodes encompasses real-time measurement of pattern placement accuracy and feature dimensions at atomic scales, employing electron beam and scatterometry techniques with sub-nanometer resolution to ensure lithographic fidelity in advanced semiconductor fabrication. Scatterometry systems lead the product type landscape due to their throughput advantages in production environments, while electron beam metrology captures the fastest growth trajectory driven by resolution requirements for gate-all-around transistor architectures. Foundries represent the most concentrated end user segment, with memory producers expanding capacity fastest as 3D NAND layer counts multiply.
ISO standards for measurement traceability, FDA oversight of semiconductor-based medical device components, and EPA hazardous substance regulations collectively shape equipment qualification protocols and facility certification requirements. The EU AI Act introduces emerging compliance dimensions for machine learning-enhanced defect classification systems. Stakeholders must monitor evolving export control frameworks governing extreme ultraviolet source technologies and their metrology dependencies.
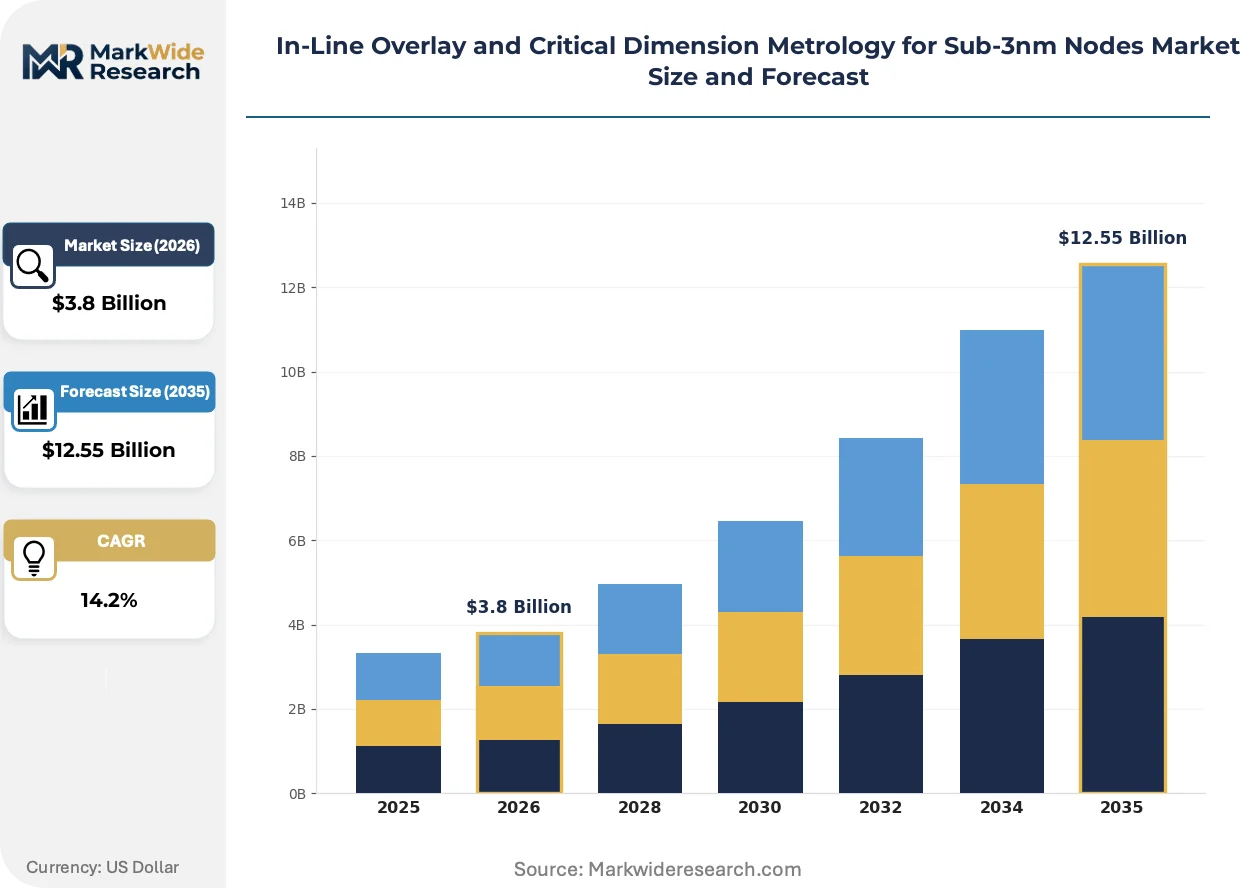
Market Dynamics
Gate-all-around transistor architectures are forcing metrology systems to resolve atomic-scale variations in three-dimensional structures, compressing tolerance windows below 0.5 nanometers and demanding simultaneous throughput gains that strain existing electron beam and optical scatterometry platforms.
Growth Catalysts
- EU Green Deal F-Gas Regulation:Mandates for EUV lithography deployment in European fabs are tightening process control requirements and accelerating metrology tool qualification timelines.
- 3D NAND Layer Multiplication:Memory producers scaling beyond 300 active layers require overlay precision at wafer edges where thermal expansion effects concentrate.
- Hsinchu Science Park Concentration:TSMC and allied foundries anchor the world's most advanced node production, creating concentrated demand pull for sub-angstrom measurement systems.
Market Restraints
- Helium Supply Volatility:Cryogenic cooling systems in electron beam columns depend on helium, with price spikes and allocation constraints disrupting tool delivery schedules.
- Zeiss Optical Component Bottleneck:Extreme ultraviolet projection optics manufacturing concentrates in a single German supplier, creating single-source vulnerability for overlay system producers.
- Throughput-Resolution Tradeoff:Electron beam metrology achieves sub-nanometer precision at speeds insufficient for high-volume manufacturing, forcing parallel tool deployment.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction create greenfield metrology demand as first advanced nodes enter planning.
- Machine Learning Defect Classification:EU AI Act compliance frameworks are accelerating adoption of neural network-enhanced measurement interpretation in European facilities.
- Hybrid Metrology Convergence:Integration of scatterometry throughput with electron beam precision enables single-platform solutions for gate-all-around process control.
Industry Challenges
- Atomic-Scale Calibration Expertise:Tool operators require physics-level understanding of electron-specimen interactions, with training pipelines failing to match deployment rates.
- ISO 17025 Accreditation Timelines:Measurement traceability certification for sub-angstrom systems extends 18-24 months, delaying revenue recognition on new installations.
- Legacy 193nm Tool Integration:Hybrid fabs running multiple lithography generations require overlay systems capable of correlating measurements across incompatible optical platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market Trends and Innovations
Computational metrology and artificial intelligence are compressing measurement cycles while extending resolution limits, enabling real-time process control feedback loops that were previously confined to offline characterization labs.
Multi-beam electron microscopy is displacing single-column architectures in critical dimension applications. Foundries in Taiwan and South Korea are piloting 25-beam systems for gate-all-around transistor characterization. This parallelization is displacing the throughput ceiling that has constrained electron beam adoption in high-volume environments.
The EU AI Act introduces mandatory conformity assessments for machine learning systems deployed in semiconductor manufacturing. Equipment suppliers must document algorithmic decision pathways for defect classification models. European fabs in Dresden and Leuven are restructuring procurement specifications to prioritize vendors with established AI governance frameworks.
Consolidated procurement consortia are replacing individual tool purchases among second-tier foundries. Buyers in Singapore and Israel are pooling metrology capital expenditure to secure volume pricing and shared service contracts. This collective purchasing is most visible among specialty foundries serving automotive and aerospace chip demand, where individual volumes cannot justify dedicated tool installations.
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market Segmentation
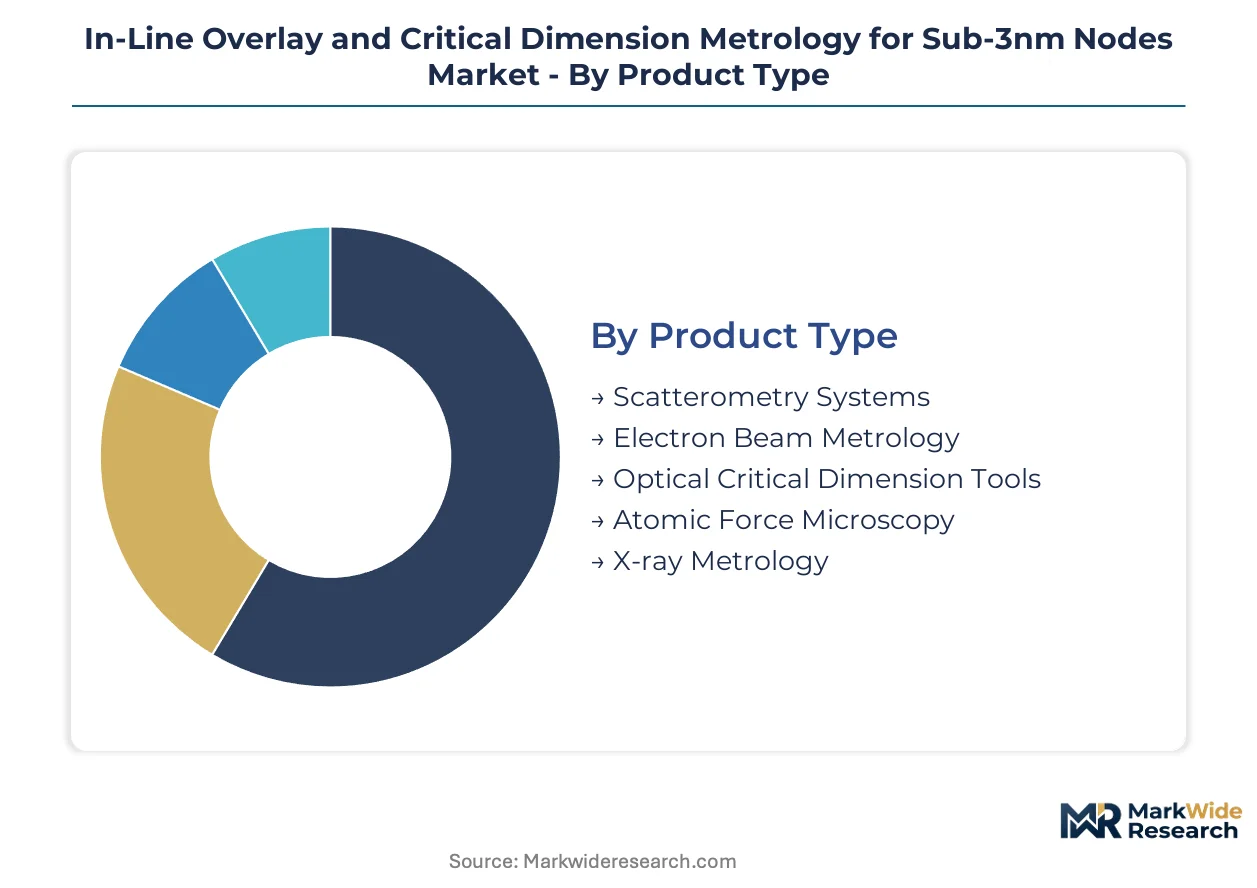
Segmentation in sub-3nm metrology reveals how tool selection splits between throughput-hungry high-volume lines and precision-starved development fabs. Each dimension exposes different procurement hierarchies and technical substitution risks that reshape vendor positioning.
Product Type:
Scatterometry systems face mounting substitution pressure from multi-beam electron platforms as gate-all-around architectures demand atomic-scale resolution that optical diffraction limits cannot satisfy.
- Scatterometry Systems:These optical diffraction-based platforms measure periodic structures through reflected light analysis, achieving sub-nanometer precision at wafer-level throughput. Foundries in Taiwan's Hsinchu Science Park deploy these for line monitoring where speed dominates absolute accuracy requirements. EUV double-patterning regimes are stretching their resolution limits toward obsolescence.
- Electron Beam Metrology:Scanning electron microscopy platforms resolve individual atomic layers in three-dimensional transistor architectures. South Korean memory producers pilot 25-beam parallel systems to overcome traditional throughput constraints. Gate-all-around process control mandates are accelerating foundry adoption despite capital intensity.
- Optical Critical Dimension Tools:Broadband reflectometry systems bridge 193nm and EUV lithography generations in hybrid fabs.
- Atomic Force Microscopy:Mechanical probe platforms quantify surface roughness and sidewall angles in development environments.
- X-ray Metrology:Grazing-incidence diffraction penetrates buried structures for 3D NAND string characterization.
Scatterometry Systems retain volume leadership; Electron Beam Metrology holds the steepest expansion curve.
Technology:
Cost tiering separates mature automation layers from emerging AI inference stacks that command premium pricing and extended qualification timelines.
- Advanced Process Control:Run-to-run feedback loops adjust lithography parameters based on real-time overlay measurements. Dresden fabs under EU AI Act compliance are restructuring procurement to prioritize vendors with documented algorithmic governance frameworks.
- Machine Learning Algorithms:Neural networks classify defect signatures and predict process drift before dimensional excursions occur. European facilities in Leuven mandate conformity assessments for these systems under emerging AI liability regulations.
- Real-Time Data Analytics:Edge computing architectures compress measurement-to-correction latency below single-wafer cycle times.
- High-Resolution Imaging:Computational enhancement techniques extract sub-pixel information from noisy sensor outputs.
- Automated Defect Detection:Rule-based classification systems remain dominant in legacy 193nm process lines.
Advanced Process Control dominates current installations; Machine Learning Algorithms are climbing the fastest as regulatory frameworks mature.
Application:
Customer type fragmentation splits procurement between captive fabs optimizing yield and merchant foundries competing on cycle time guarantees.
- Semiconductor Fabrication:In-line metrology stations monitor every lithography layer in sub-3nm logic production. TSMC's N2 node ramp is concentrating demand for combined overlay and critical dimension platforms that correlate measurements across 500+ process steps.
- Wafer Inspection:Macro-defect detection precedes patterning to prevent costly tool contamination events. Memory producers scaling beyond 300 3D NAND layers require edge-specific overlay compensation where thermal gradients concentrate.
- Lithography Process Control:Scanner feedback systems minimize overlay error through predictive reticle heating models.
- Yield Enhancement:Offline characterization laboratories trace systematic failure modes to specific process excursions.
- Process Integration:Cross-functional teams reconcile metrology data across deposition, etch, and planarization modules.
Semiconductor Fabrication commands the largest installed base; Wafer Inspection is gaining share fastest as layer counts multiply in memory architectures.
End User:
Supply concentration among leading-edge foundries creates asymmetric pricing power that compresses margins for metrology vendors serving fragmented specialty segments.
- Logic Chip Manufacturers:Sub-3nm node development requires atomic-scale calibration of gate-all-around transistor dimensions. Intel's Ohio and Arizona fabs are qualifying multi-platform metrology suites that bridge internal development and external foundry service models.
- Foundries:Merchant manufacturers compete on guaranteed overlay specifications that constrain customer design rules. Singapore-based specialty foundries are forming procurement consortia to secure volume pricing for sub-angstrom measurement systems.
- Integrated Device Manufacturers:Captive production for automotive and aerospace applications prioritizes traceability over throughput.
- Memory Producers:3D NAND scaling drives demand for high-aspect-ratio hole metrology in string stacking processes.
- Photonics Developers:Silicon photonics integration requires overlay precision for passive waveguide alignment.
Foundries anchor current demand concentration; Memory Producers are expanding capacity most aggressively as layer multiplication accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metrology tool trade flows tilt heavily toward export-dependent manufacturing economies, with import demand concentrated in emerging fabrication hubs building domestic capacity. Equipment shipments track lithography scanner deployments, creating geographic lag patterns between tool orders and revenue recognition.
Taiwan
Hsinchu Science Park foundries consume the densest concentration of sub-angstrom measurement systems worldwide, with TSMC's N2 node ramp pulling multi-platform overlay suites. The National Development Council's Advanced Semiconductor Research Program subsidizes domestic metrology qualification labs. Taichung's Central Taiwan Science Park is expanding specialty foundry capacity requiring edge-specific overlay compensation systems.
South Korea
Memory producers in Pyeongtaek and Yongin are piloting 25-beam electron systems for 300-layer 3D NAND characterization, outpacing logic foundry adoption curves. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative funds metrology infrastructure for non-memory chip production. Samsung's Pyeongtaek complex anchors the steepest capacity expansion trajectory for high-aspect-ratio hole metrology.
United States
Intel's Ohio and Arizona fabs are qualifying hybrid metrology suites bridging internal development and external foundry service models, creating dual-use equipment specifications. The CHIPS and Science Act's domestic content requirements are restructuring supplier qualification timelines for federal funding recipients. Phoenix's semiconductor corridor is attracting overlay tool service centers to support simultaneous fab construction projects.
China
Domestic foundries in Shanghai and Beijing are accelerating import substitution programs for optical critical dimension platforms amid export control tightening. MIIT's Guidelines on the Development of the Integrated Circuit Industry mandate localization timelines for process control equipment. Zhangjiang Hi-Tech Park in Shanghai hosts the most advanced indigenous metrology development clusters.
Germany
Dresden's European Semiconductor Manufacturing Company consortium is restructuring procurement specifications to prioritize vendors with documented AI governance frameworks under EU AI Act conformity assessments. The EU Green Deal F-Gas Regulation accelerates metrology tool qualification for EUV lithography deployment. Zeiss's Oberkochen facility maintains single-source dominance in extreme ultraviolet projection optics for overlay systems.
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with public companies leveraging balance sheet capacity for multi-beam platform development while private entities concentrate on niche optical subsystems. The vendor base stratifies between integrated process control conglomerates and standalone metrology pure-plays. Three archetypes dominate: full-stack lithography-metrology integrators, precision optics specialists, and AI-enhanced measurement software vendors. Consolidation is accelerating through strategic technology licensing agreements and captive supply arrangements for critical optical components.
Within the precision optics tier, KLA Corporation and Applied Materials exemplify scale-driven platform consolidation, while Onto Innovation occupies a specialized position in overlay systems for EUV double-patterning regimes. These three entities anchor the competitive structure through contrasting strategic postures—KLA leveraging installed base density, Applied Materials bridging deposition and metrology workflows, and Onto Innovation concentrating on pattern placement accuracy at sub-nanometer tolerances.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials |
| ASML |
| Onto Innovation |
| Nova |
| Hitachi High-Tech |
| Thermo Fisher Scientific |
| SCREEN Holdings |
| Advantest |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month qualification timelines for sub-angstrom metrology systems compress inventory buffers to 45-60 days for critical optical subsystems, concentrating pricing power with Zeiss's single-source EUV projection optics while forcing foundries to absorb premium markups for expedited helium-cooled electron beam columns.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where multi-year service agreements bundle hardware, calibration, and software updates. Price differentiation separates ISO 17025-accredited systems from standard-tier platforms lacking measurement traceability certification. Cost compression in entry-level scatterometry tiers is intensifying because memory producers are consolidating procurement through Singapore-based purchasing consortia. Merchant foundries exhibit highest price sensitivity due to margin pressure from guaranteed overlay specification contracts, while captive IDM fabs prioritize traceability premiums over unit economics.
Supply Chain Analysis
Strategic stockpiling of helium reserves dominates inventory strategy given cryogenic cooling dependencies in electron beam columns, contrasting with just-in-time component flows for optical subsystems. Geographic supply concentration centers on Germany for EUV projection optics, Taiwan for precision motion stages, and Japan for electron source emitters. Raw material dependencies include high-purity helium, synthetic fused silica, and rare-earth magnetic alloys. Single-source vulnerability in Zeiss's Oberkochen facility creates structural supply chain risk. Distribution runs through direct vendor-fab relationships with embedded service engineering teams rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-beam electron platforms threaten to displace optical scatterometry in gate-all-around process control, forcing incumbents to defend installed base density through accelerated platform refresh cycles.
For Market Incumbents: Consolidate captive supply arrangements for EUV projection optics to mitigate Zeiss bottleneck exposure, while embedding machine learning defect classification modules ahead of EU AI Act conformity assessment deadlines. Backward integration into helium recycling systems addresses supply volatility threatening electron beam delivery schedules. For New Entrants and Emerging Players: ISO 17025 accreditation fast-tracks market access through metrology qualification labs in Taiwan's Hsinchu Science Park, where domestic subsidy programs reduce certification cost barriers. White-space targets include hybrid metrology platforms bridging scatterometry throughput with electron beam precision, and AI governance documentation services for European fabs in Dresden. The most penetrable segment is specialty foundries in Singapore and Israel lacking volume scale for dedicated tool installations. For Investors and Strategic Acquirers: Long-term, this sits as a process control infrastructure play because lithography scanner deployment mandates create inelastic demand for overlay and critical dimension metrology regardless of semiconductor cycle timing. Acquisition targets should concentrate on multi-beam electron microscopy specialists with 25-beam pilot validation. The signal to watch is TSMC's N2 node ramp cadence, which dictates capital expenditure intensity across the supplier ecosystem.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Platform Development | 25-beam parallelization overcomes throughput constraints that limited electron beam adoption in high-volume manufacturing environments. |
| AI Governance Framework Certification | EU AI Act conformity assessments in Dresden and Leuven restructure procurement specifications toward documented algorithmic decision pathways. |
| Helium Supply Security Agreements | Long-term offtake contracts with Qatar and Algeria stabilize cryogenic cooling costs for electron beam column operations. |
| Hybrid Metrology Integration | Single-platform solutions combining scatterometry speed with electron beam precision address gate-all-around process control requirements. |
| Procurement Consortium Participation | Shared service contracts among Singapore specialty foundries secure volume pricing for sub-angstrom measurement systems. |
Research Methodology
The analysis maps scatterometry systems, electron beam metrology, optical critical dimension tools, and hybrid platforms, each validated through process integration engineers, metrology tool operators, fab procurement managers, and lithography scanner specialists. Primary interviews with these stakeholders combined with secondary validation from SEMI equipment market data, SEC filings of listed metrology vendors, EUV lithography deployment disclosures, and ISO accreditation registries. Bottom-up installation base counts and top-down equipment spending forecasts triangulate market sizing.
Consistency checks against SEMI capital expenditure surveys and foundry equipment procurement disclosures validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology layer, application stage, and end-user archetype. CAGRs derive from equipment shipment trajectories correlated with lithography scanner order backlogs. Industry-specific forecast inputs incorporate gate-all-around transistor ramp schedules and 3D NAND layer multiplication roadmaps.
Underlying assumptions cover EUV lithography deployment timelines, helium supply stabilization, and multi-beam electron platform qualification rates, with deviation risk concentrated in export control tightening for extreme ultraviolet source technologies. Revision becomes warranted when TSMC or Samsung node transition schedules shift beyond ±6 quarters from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.