
 Stability Test Chamber Market | 2026-2036
Stability Test Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Stability Test Chamber Market Analytics
Pharmaceutical-grade chamber specifications is rotating demand toward ICH-validated walk-in systems with tighter uniformity tolerances. ESPEC leverages its Japanese manufacturing scale to dominate high-precision humidity control segments across Asia-Pacific installations. Weiss Technik anchors European demand through captive refrigeration technology and deep integration with German automotive testing protocols. Thermotron competes in North American defense and aerospace qualification markets where MIL-STD environmental cycling requirements sustain premium pricing.
A stability test chamber is an enclosed, climate-controlled apparatus engineered to maintain precise temperature, humidity, and sometimes light conditions within tight tolerances—typically ±0.5°C and ±3% RH—using cascaded refrigeration loops, desiccant or steam-injection humidity systems, and programmable PID controllers. Its primary purpose is to accelerate aging, validate shelf-life claims, and certify product integrity under stressed environmental conditions for regulated industries. Walk-in chambers command the largest revenue pool due to pharmaceutical batch-testing volumes, while benchtop units represent the fastest-expanding segment as cosmetics and biotech startups outsource stability programs to contract testing services. Refrigeration technology remains the most mature subsystem with compressed margin pools, whereas programmable controllers and integrated data logging architectures capture expanding value as 21 CFR Part 11 compliance requirements harden.
FDA 21 CFR Part 11, ICH Q1A(R2), and EMA stability testing guidelines collectively shape chamber validation protocols, calibration frequencies, and documentation standards that manufacturers must embed to serve regulated pharmaceutical clients. EPA energy efficiency regulations and EU F-Gas refrigerant phase-down rules are forcing compressor redesigns and alternative cooling chemistry investments across equipment portfolios. Stakeholders should monitor evolving WHO prequalification standards for temperature-controlled storage as emerging market pharmaceutical manufacturing scales.
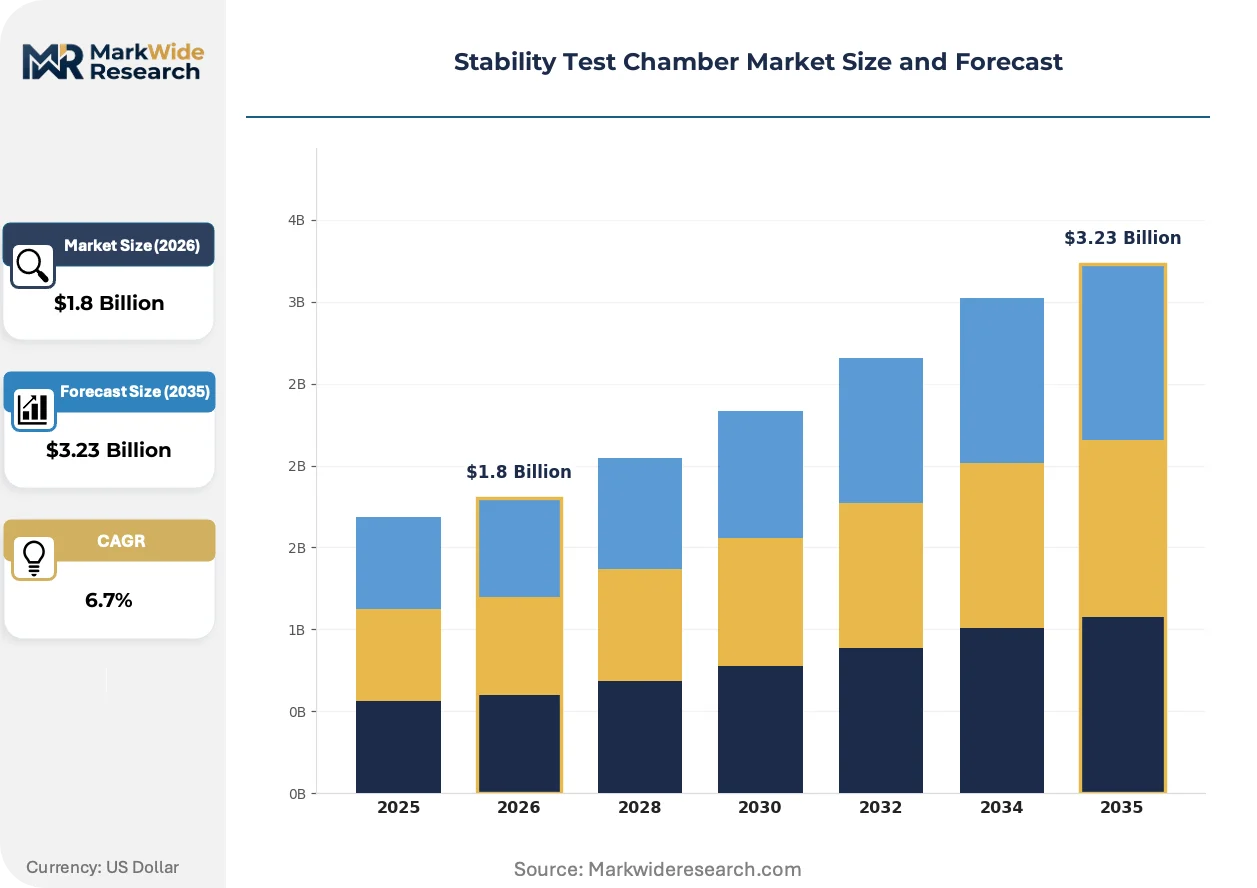
Market Dynamics
Pharmaceutical manufacturers now demand programmable environmental chambers with tighter uniformity tolerances as ICH Q1A validation protocols harden across regulated markets, compressing margins for legacy refrigeration-only suppliers while elevating controller and data-logging architectures.
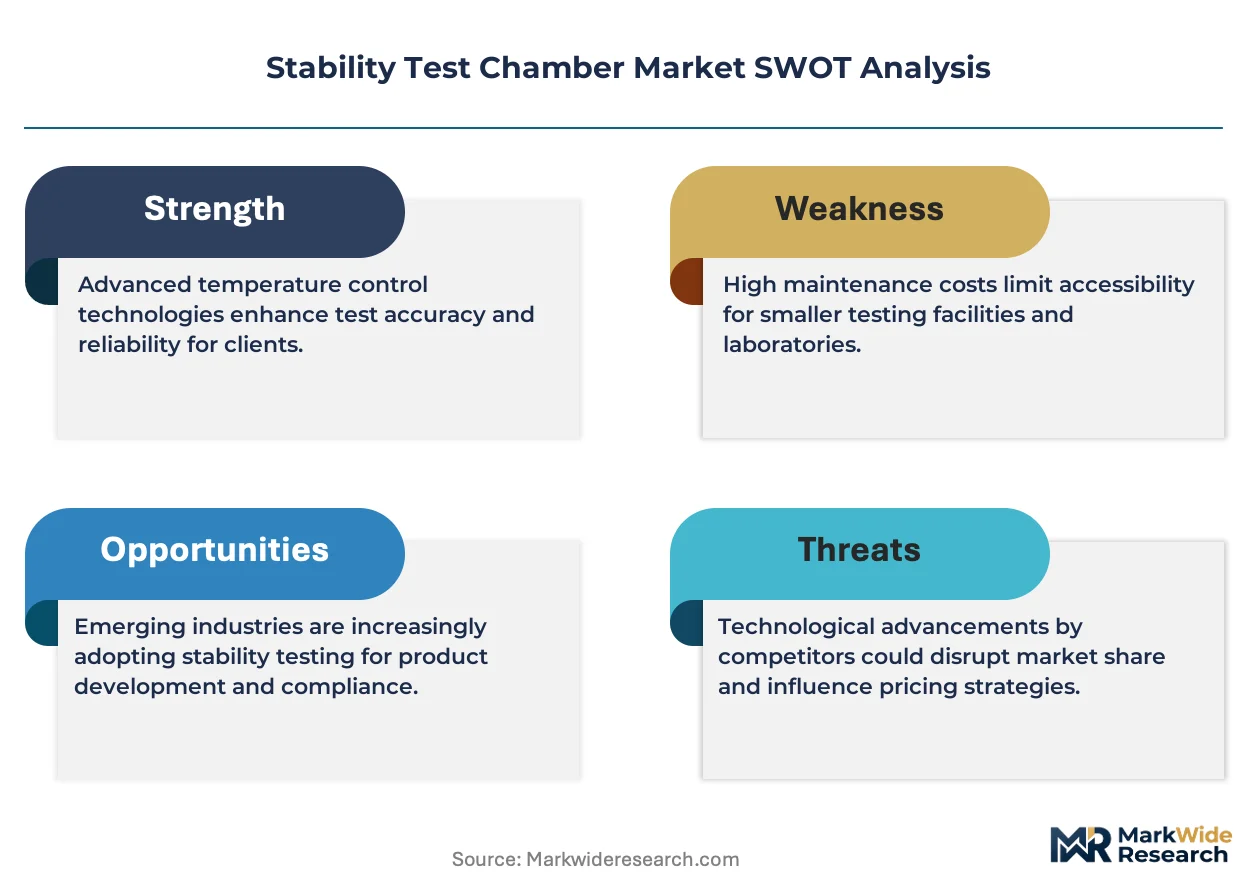
Growth Catalysts
- ICH Q1A(R2) stability guidelines:Tightened shelf-life validation requirements across EMA-aligned markets are forcing pharmaceutical manufacturers to upgrade aging batch-testing infrastructure.
- Contract research laboratory clusters:Dense concentrations of outsourced stability testing services in Germany and Switzerland are driving walk-in chamber procurement volumes.
- Benchtop unit miniaturization:Cosmetics and biotech startups are deploying compact environmental chambers for accelerated aging studies previously reserved for large-scale facilities.
Market Restraints
- Refrigerant chemistry constraints:EU F-Gas phase-down rules are forcing compressor redesigns and alternative cooling chemistry investments that extend R&D cycles.
- Controller subsystem supply concentration:Precision PID programming and integrated data-logging architectures depend on specialized semiconductor supply chains concentrated in East Asian fabrication facilities.
- Validation documentation burden:FDA 21 CFR Part 11 compliance requirements extend sales cycles and inflate field service costs for chamber manufacturers serving regulated clients.
Strategic Opportunities
- Indian pharmaceutical manufacturing scale:CDSCO-aligned stability testing adoption among domestic generic producers creates demand for ICH-validated walk-in systems.
- WHO prequalification standards:Emerging market temperature-controlled storage requirements are expanding addressable market for validated environmental chambers beyond OECD jurisdictions.
- Cloud-integrated data logging:Convergence of chamber telemetry with enterprise quality management systems enables subscription-based validation monitoring services.
Industry Challenges
- Metrology technician scarcity:Calibration and validation of ±0.5°C uniformity tolerances requires specialized thermal mapping expertise that outpaces vocational training pipeline output.
- Legacy system integration friction:Pharmaceutical facilities with decades-old batch records infrastructure face protocol translation costs when connecting modern programmable controllers to existing LIMS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stability Test Chamber Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Chamber, Walk-In Chamber, Benchtop Chamber, Environmental Chamber Application: Pharmaceuticals, Food & Beverages, Cosmetics, Electronics End User: Manufacturers, Research Institutions, Quality Control Laboratories, Contract Testing Services Technology: Refrigeration Technology, Humidity Control, Programmable Controllers, Data Logging |
| Companies Covered | ESPEC, Weiss Technik, Thermotron, Binder, Memmert, Thermo Fisher Scientific, Angelantoni, CTS, Russells Technical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stability Test Chamber Market Evolving Landscape
Stability test chamber architecture is pivoting from standalone hardware toward integrated validation ecosystems, with controller intelligence and data integrity features capturing disproportionate value as regulatory documentation requirements intensify.
Cascaded refrigeration loops with variable-speed compressor drives are fragmenting the traditional single-stage cooling paradigm. Mid-tier pharmaceutical manufacturers are adopting these systems to achieve ICH-validated uniformity without walk-in chamber capex. The technology is fragmenting procurement patterns by enabling smaller facilities to perform batch-scale stability studies previously requiring centralized contract laboratory capacity.
EMA stability testing guidelines and EU F-Gas refrigerant regulations are jointly accelerating alternative cooling chemistry adoption. Equipment manufacturers must now validate thermal performance across hydrofluoroolefin and natural refrigerant portfolios. German automotive testing protocols are extending this pressure beyond pharmaceutical applications, compressing timeline advantages for suppliers with captive refrigeration technology.
Service unbundling is reshaping how pharmaceutical buyers contract for chamber validation and calibration. Equipment vendors are disaggregating hardware sales from ongoing metrology support, with third-party ISO 17025-accredited laboratories capturing recurring revenue streams. This pattern is most visible in Swiss and German contract research clusters where multi-vendor chamber fleets favor independent calibration providers over manufacturer-captive service networks.
Stability Test Chamber Market Segmentation
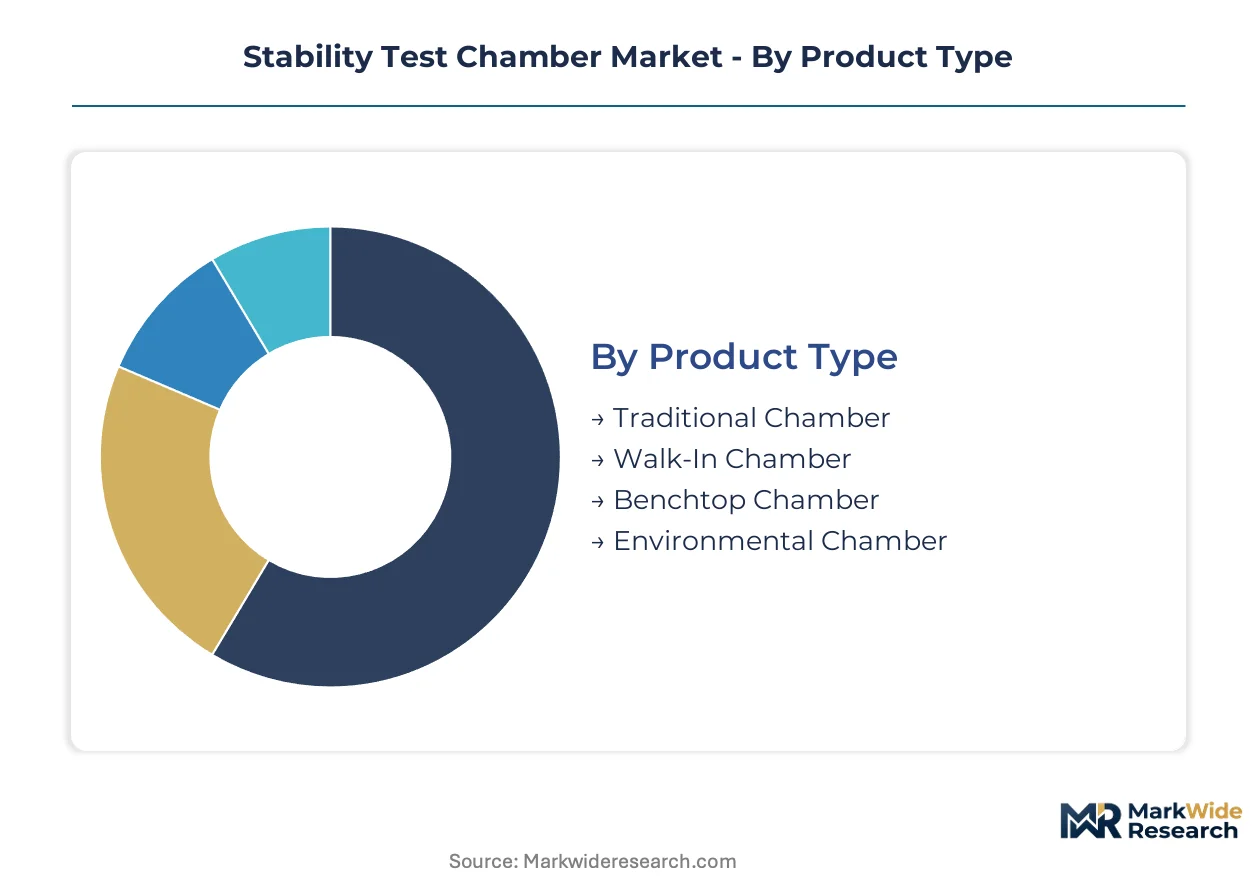
Stability test chamber procurement patterns fragment sharply across product scale, regulatory exposure, and validation intensity. Pharmaceutical manufacturers prioritize ICH-validated walk-in systems for batch testing, while cosmetics and electronics sectors drive benchtop miniaturization.
Product Type:
Margin pools concentrate in programmable walk-in systems where validation documentation and field service attach rates sustain premium pricing.
- Walk-In Chamber:These climate-controlled rooms maintain ±0.5°C uniformity across pallet-scale pharmaceutical batches using cascaded refrigeration and distributed sensor networks. German contract research clusters in Munich and Hamburg anchor procurement volumes as EMA-aligned stability protocols tighten shelf-life validation requirements.
- Benchtop Chamber:Compact units deploy desiccant-based humidity control and PID programming for accelerated aging studies in limited footprint facilities. Biotech startups in Basel and cosmetics formulators in Paris are rotating demand toward these systems as outsourced stability programs fragment testing volumes across smaller facilities.
- Traditional Chamber:Standalone reach-in cabinets with basic temperature cycling dominate legacy pharmaceutical installations in mature markets.
- Environmental Chamber:Multi-stress systems combining thermal, humidity, and vibration profiles serve automotive and aerospace qualification protocols.
Walk-in chambers hold installed capacity. Benchtop chambers are rotating up the share rankings.
Application:
Volume concentrates in pharmaceutical shelf-life validation where FDA 21 CFR Part 11 documentation requirements harden specification thresholds.
- Pharmaceuticals:ICH Q1A(R2) stability studies demand continuous temperature and humidity logging with audit-trail integrity for New Drug Application submissions. Swissmedic-aligned facilities in Basel and FDA-regulated manufacturers in New Jersey are upgrading aging infrastructure to meet tightened uniformity tolerances.
- Cosmetics:Accelerated aging protocols for emulsion stability and packaging integrity require compact chambers with rapid cycle capability. Formulation laboratories in France and contract testing services in Switzerland are deploying benchtop units for preservative efficacy studies previously centralized in walk-in facilities.
- Food & Beverages:Shelf-life prediction for packaged goods relies on temperature-abuse simulation rather than pharmaceutical-grade precision.
- Electronics:MIL-STD environmental cycling for semiconductor reliability demands rapid thermal transition rates.
Pharmaceuticals command the revenue concentration. Cosmetics is climbing the fastest as miniaturization enables distributed testing.
End User:
Procurement authority is fragmenting as quality control laboratories and contract testing services disaggregate from captive manufacturer fleets.
- Contract Testing Services:Multi-client stability programs in Germany and Switzerland require flexible chamber configurations with rapid protocol switching and ISO 17025-accredited calibration documentation. These providers favor vendor-agnostic service contracts over manufacturer-captive validation networks.
- Quality Control Laboratories:In-house pharmaceutical testing facilities demand integrated data logging architectures that map directly to LIMS infrastructures. CDSCO-aligned generic manufacturers in India are building captive QC capacity as domestic production scales for WHO prequalification.
- Manufacturers:Captive stability infrastructure remains concentrated among large pharmaceutical and automotive producers.
- Research Institutions:Academic and government laboratories prioritize capital cost containment over validation intensity.
Manufacturers retain the installed base. Contract testing services are gaining share fastest as outsourcing consolidates testing volumes.
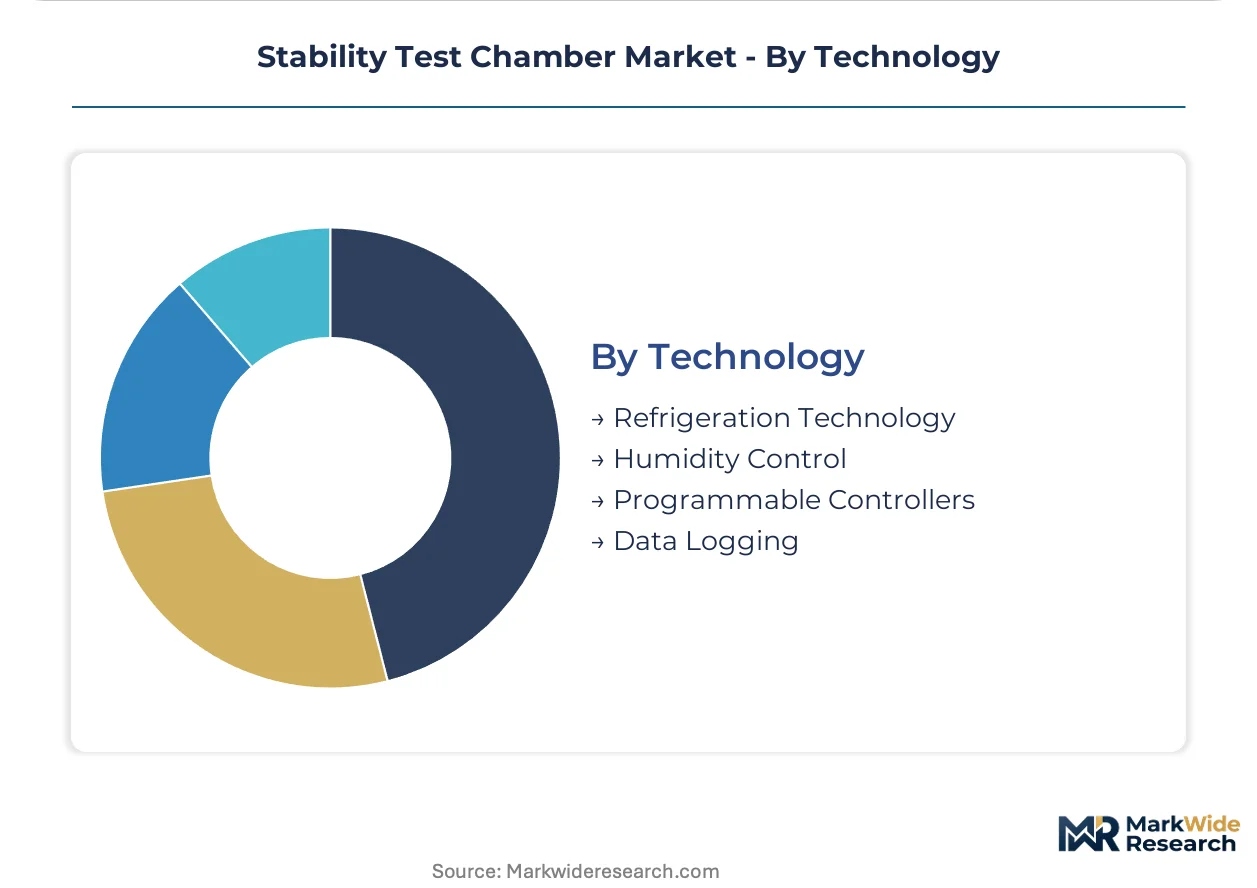
Technology:
Value capture is rotating toward controller intelligence and data integrity subsystems as hardware commoditization compresses refrigeration margins.
- Programmable Controllers:PID-based systems with 21 CFR Part 11-compliant audit trails and remote telemetry integration command expanding value pools. Pharmaceutical buyers in regulated markets now require Ethernet-connected controllers that synchronize with enterprise quality management systems.
- Data Logging:Continuous temperature and humidity recording with cryptographic integrity verification supports regulatory inspection readiness. Cloud-integrated architectures enabling subscription-based validation monitoring are emerging in Swiss and German contract research clusters.
- Refrigeration Technology:Cascaded and variable-speed compressor systems face margin pressure from EU F-Gas refrigerant phase-down compliance costs.
- Humidity Control:Steam-injection and desiccant-based systems compete on precision and maintenance intensity across application segments.
Refrigeration technology holds the installed capacity. Programmable controllers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research buyers in Switzerland and Germany exhibit minimal price elasticity for ICH-validated walk-in systems, while Indian generic manufacturers prioritize capital efficiency over precision tolerances in benchtop procurement decisions.
Germany
EMA-aligned stability protocols and dense contract laboratory clusters in Munich and Hamburg anchor European demand for programmable walk-in chambers. The EU F-Gas Regulation forces compressor redesign investments across equipment portfolios. Bavaria's automotive testing corridor extends chamber specifications beyond pharmaceutical applications into multi-stress environmental cycling.
United States
FDA 21 CFR Part 11 compliance requirements harden specification thresholds for New Drug Application submissions, elevating controller and data-logging architectures. EPA energy efficiency regulations reshape refrigeration subsystem investments. New Jersey's FDA-regulated pharmaceutical corridor and California's biotech startup ecosystem fragment procurement across walk-in and benchtop segments.
Switzerland
Swissmedic-aligned facilities in Basel demand integrated data logging architectures with cryptographic integrity verification for inspection readiness. ISO 17025-accredited calibration documentation requirements favor vendor-agnostic service contracts over manufacturer-captive networks. The country's contract research clusters drive premium pricing for rapid protocol switching capabilities.
India
CDSCO-aligned stability testing adoption among domestic generic producers creates demand for ICH-validated systems at compressed price points. WHO prequalification standards for temperature-controlled storage expand addressable market beyond OECD jurisdictions. Maharashtra and Gujarat pharmaceutical manufacturing belts are building captive quality control capacity as export scale accelerates.
China
NMPA regulatory harmonization with ICH guidelines elevates validation documentation requirements for domestic pharmaceutical exporters. The country's dual carbon goals accelerate alternative cooling chemistry adoption in refrigeration subsystems. Yangtze River Delta pharmaceutical clusters are upgrading aging batch-testing infrastructure to meet tightened uniformity tolerances for international market access.
Stability Test Chamber Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where precision controller specialists command premium attach rates while scale fabricators compete on refrigeration subsystem efficiency. The vendor base separates into three strategic archetypes: Japanese and German precision specialists with captive humidity control technology, North American defense-aerospace qualification providers, and emerging Asian scale manufacturers. Competitive moves concentrate on M&A for controller subsystem capabilities and geographic expansion into Indian and Southeast Asian pharmaceutical manufacturing corridors.
Among Japanese precision specialists, ESPEC Corp. exemplifies technology leadership through manufacturing scale advantages in high-precision humidity control segments. German captive refrigeration technology is represented by Weiss Technik GmbH, which anchors European demand through deep integration with automotive testing protocols. Thermotron Industries occupies a position in North American defense and aerospace qualification markets where MIL-STD environmental cycling requirements sustain differentiated pricing power. These three companies represent the dominant geographic-technological archetypes shaping competitive positioning across regulated pharmaceutical and industrial testing applications.
| Leading Market Players |
|---|
| ESPEC |
| Weiss Technik |
| Thermotron |
| Binder |
| Memmert |
| Thermo Fisher Scientific |
| Angelantoni |
| CTS |
| Russells Technical Products |
| Others |
Value Network & Pricing Analysis
Hydrofluoroolefin refrigerant substitution for legacy F-Gas chemistries is simultaneously redrawing compressor sourcing maps from Germany and Japan toward Chinese alternative-cooling R&D clusters and inflating validation costs that chamber manufacturers pass to pharmaceutical buyers through extended service contracts.
Pricing Analysis
Validation and calibration service contracts now drive lifetime value capture, with pharmaceutical-grade walk-in systems commanding three-tier pricing structure across premium, standard, and economy levels differentiated by ICH certification tier and 21 CFR Part 11 audit-trail sophistication. Price differentiation hinges on uniformity tolerance guarantees and geographic proximity to EMA-aligned metrology laboratories. Margins are tightening due to EU F-Gas compliance investments in compressor redesigns. Indian generic manufacturers exhibit highest price sensitivity, while Swiss contract research laboratories show minimal elasticity for rapid protocol-switching capabilities.
Supply Chain Analysis
Japan and Germany anchor precision humidity control and captive refrigeration technology production, while China concentrates benchtop controller assembly and semiconductor fabrication for PID programming architectures. Cascaded compressor systems draw from specialized copper tubing and rare-earth magnet feedstocks concentrated in East Asian processing facilities. Single-source vulnerability runs through Taiwanese foundries supplying precision sensor arrays. Distribution runs through manufacturer-direct channels for pharmaceutical validation segments and third-party laboratory service networks for contract research clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stability test chamber demand sits in early-cycle expansion as WHO prequalification standards penetrate Indian and Southeast Asian pharmaceutical manufacturing corridors previously outside OECD regulatory orbits.
For Market Incumbents: Secure controller subsystem capabilities through targeted acquisition of PID programming specialists in Taiwan and South Korea, insulating against semiconductor supply concentration risk. Defend margin position by embedding cloud-integrated data logging architectures that pharmaceutical buyers cannot easily disaggregate from hardware procurement. Counter emerging Asian scale manufacturers by deepening captive refrigeration technology moats around EU F-Gas-compliant alternative cooling chemistries. For New Entrants and Emerging Players: CDSCO fast-track certification for ICH-validated benchtop systems opens immediate white-space access in Maharashtra and Gujarat pharmaceutical manufacturing belts. Target cosmetics formulators in Paris and Basel with compact desiccant-based humidity control units priced below German incumbent tiers. Accelerated aging protocols for preservative efficacy studies represent the most penetrable application segment for capital-constrained biotech startups outsourcing stability programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision controller specialists in East Asian semiconductor corridors seeking exit liquidity before next-generation telemetry integration capex requirements intensify. Five-to-ten year viability favors vendors with installed base density in German and Swiss contract research clusters where ISO 17025-accredited calibration documentation creates switching costs. Monitor NMPA regulatory harmonization progress with ICH guidelines as inflection signal for Chinese pharmaceutical exporter upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Subsystem Acquisition | Captures PID programming expertise concentrated in Taiwanese semiconductor corridors for pharmaceutical telemetry integration. |
| WHO Prequalification Certification | Unlocks Indian generic manufacturer procurement previously restricted to OECD-validated equipment suppliers. |
| Cloud-Integrated Data Logging Launch | Enables subscription-based validation monitoring services in Swiss and German contract research clusters. |
| Alternative Cooling Chemistry Partnership | Accelerates EU F-Gas-compliant hydrofluoroolefin compressor validation for EMA-aligned stability protocols. |
| Benchtop Miniaturization Scale-Up | Addresses cosmetics and biotech startup demand for distributed accelerated aging studies in limited-footprint facilities. |
Research Methodology
Cross-validation between primary interviews with chamber validation engineers, contract laboratory procurement directors, pharmaceutical quality control managers, and refrigeration subsystem suppliers anchors the qualitative findings against secondary sources including FDA 483 inspection observations, EMA GMP inspection reports, and EU F-Gas Regulation compliance disclosures. Bottom-up triangulation of installed base estimates with top-down pharmaceutical capital expenditure patterns validates volume assumptions across product type and regional segments.
Sensitivity analysis stress-tests demand projections against regulatory timeline slippage and refrigerant chemistry transition costs throughout the forecast period. Segmentation modeling incorporates chamber scale, application intensity, end-user procurement authority, and technology subsystem value capture. CAGRs derive from pharmaceutical manufacturing capacity expansion pipelines and contract research laboratory cluster formation patterns. Forecast inputs include CDSCO regulatory harmonization milestones and WHO prequalification adoption curves in emerging market pharmaceutical corridors.
Underlying assumptions cover EMA stability guideline enforcement continuity and EU F-Gas phase-down schedule adherence, with deviation risk concentrated in NMPA regulatory alignment delays and East Asian semiconductor supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Crock Meter Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Tensile Testers Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Hour Meter Market
Test and Measurement
Digital Inspection Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Global Source Measure Unit Market