
 LTE Testing Equipment Market | 2026-2036
LTE Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
LTE Testing Equipment Market Outlook
3GPP Release 17 conformance certification is bifurcating the vendor landscape into qualified incumbents and excluded challengers. Keysight Technologies leverages deep calibration IP to sustain dominance in protocol validation suites. Rohde & Schwarz anchors European demand through integrated signal generator and network analyzer portfolios.
LTE testing equipment comprises instruments that validate radio frequency performance, protocol stack behavior, and network interoperability across licensed cellular bands from 700 MHz to 2.6 GHz, employing vector signal analysis and over-the-air measurement techniques to ensure base station and user equipment compliance with 3GPP specifications. RF test equipment occupies the largest installed base due to carrier aggregation complexity, while protocol testers capture expanding margins as operators validate VoLTE handover reliability. Cloud-based deployment segments are gaining traction among testing laboratories seeking elastic capacity for sporadic certification cycles.
FCC Part 27 equipment authorization and 3GPP TS 36.521 conformance frameworks mandate iterative retesting as carriers refarm spectrum, directly shaping replacement demand for aging bench instruments. ETSI harmonized standards in Europe add CE marking validation layers that extend procurement lead times for non-EU suppliers. Stakeholders must monitor spectrum auction schedules and 3GPP release cadence to time capital deployment against certification deadline clusters.
Market Dynamics
Carrier aggregation complexity and VoLTE interoperability mandates are compressing replacement cycles for bench instruments as operators refarm spectrum ahead of 5G standalone deployments.
Growth Catalysts
- 3GPP Release 17 conformance frameworks:Mandatory protocol stack validation for LTE-Advanced Pro devices is pulling demand for multi-band signal analyzers into certification laboratories.
- VoLTE handover reliability mandates:North American operators are expanding test lab capacity to validate voice continuity across heterogeneous network boundaries.
- Spectrum refarming cycles:FCC Part 27 equipment authorization rules require iterative retesting when carriers reallocate 700 MHz and AWS-3 bands.
Market Restraints
- Precision oscillator input volatility:Temperature-compensated crystal oscillator supply concentrates among Japanese and German component specialists, creating procurement bottlenecks.
- Calibration IP concentration:Protocol validation suites depend on proprietary waveform libraries concentrated among incumbent instrumentation vendors.
- ETSI CE marking friction:Harmonized standards add validation layers that extend lead times for non-EU suppliers seeking European laboratory procurement.
Strategic Opportunities
- Cloud-native test orchestration:Elastic capacity models enable testing laboratories to scale conformance cycles without capital-intensive bench instrument purchases.
- India's telecom manufacturing zones:PLI scheme incentives for domestic 4G device production are creating demand for localized RF validation infrastructure.
- Automotive C-V2X convergence:LTE-V2X protocol testing requirements for connected vehicle certification are opening adjacent demand from automotive Tier-1 suppliers.
Industry Challenges
- Millimeter-wave calibration expertise scarcity:Vector signal analysis above 6 GHz requires specialized technician training that outpaces current vocational pipeline output.
- Multi-release protocol stack integration:Simultaneous support for 3GPP Releases 15 through 17 is forcing firmware architecture rewrites that delay product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTE Testing Equipment Market |
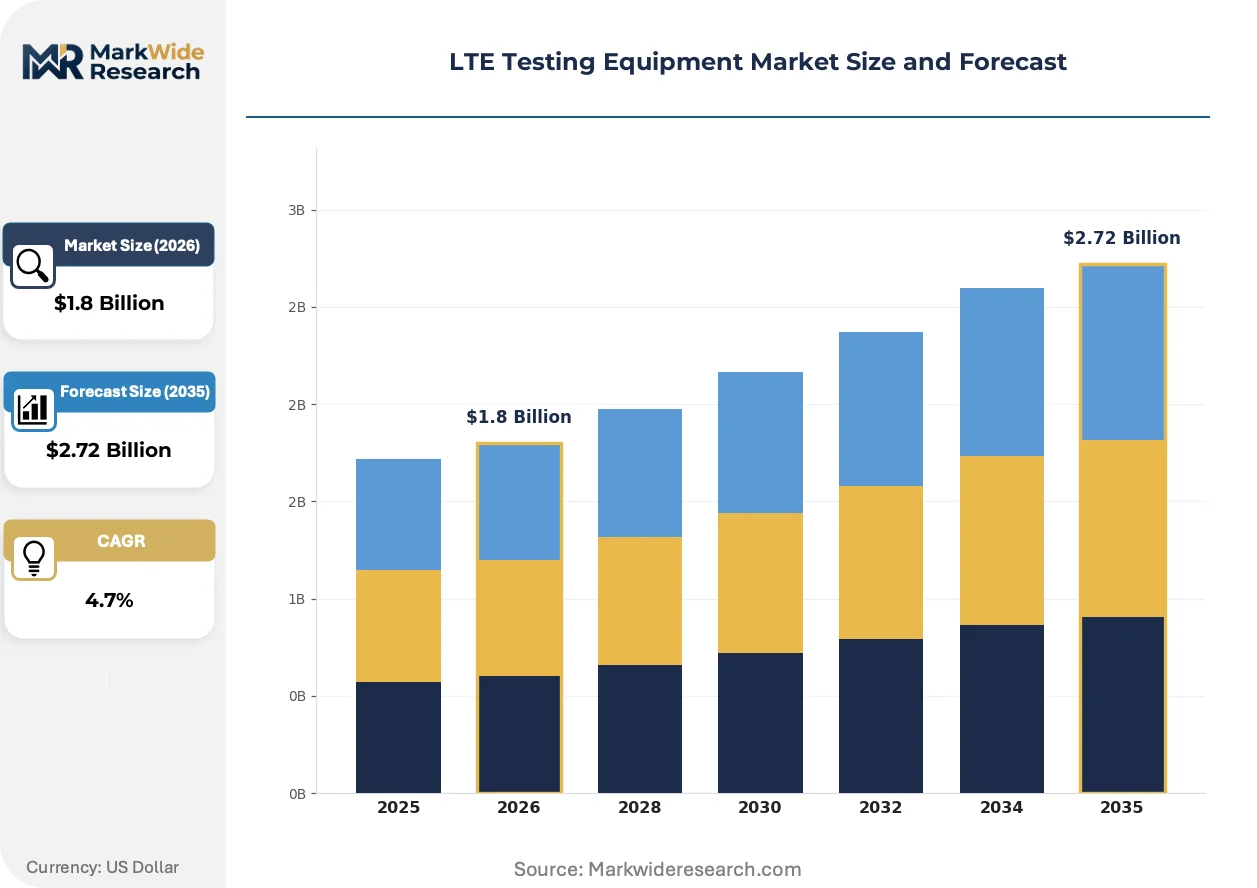
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Generators, Network Analyzers, Protocol Testers, RF Test Equipment End User: Telecom Operators, Equipment Manufacturers, R&D Institutions, Testing Laboratories Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Technology: LTE, LTE-Advanced, 5G NR, VoLTE |
| Companies Covered | Spirent Communications, EXFO, Keysight Technologies, Agilent Technologies, Fluke Corporation, Rohde & Schwarz, Tektronix, Zhejiang Dingli Machinery, Anritsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE Testing Equipment Market Strategic Shifts
Instrumentation architectures are fragmenting between hardware-centric bench systems and software-defined validation platforms, reshaping how laboratories provision sporadic certification capacity.
Software-defined radio testbeds are decomposing traditional vector signal generator hardware stacks into modular FPGA-based processing layers. Tier-1 equipment manufacturers are adopting these platforms for rapid waveform prototyping. The shift is decomposing capital expenditure models from perpetual instrument ownership toward subscription-based license structures.
ETSI harmonized standards for RED 2014/53/EU compliance are mandating enhanced spurious emission testing for carrier aggregation configurations. The framework compresses certification timelines for devices operating across non-contiguous spectrum blocks. German and French notified bodies are expanding laboratory accreditation scope to capture these multi-band validation requirements.
Testing service unbundling is separating conformance validation from equipment procurement decisions. Network equipment manufacturers are outsourcing 3GPP TS 36.521 certification to specialized third-party laboratories rather than maintaining captive test benches. This pattern is most visible in South Korea and Taiwan, where semiconductor foundries co-locate validation facilities near device assembly operations.
LTE Testing Equipment Market Segmentation
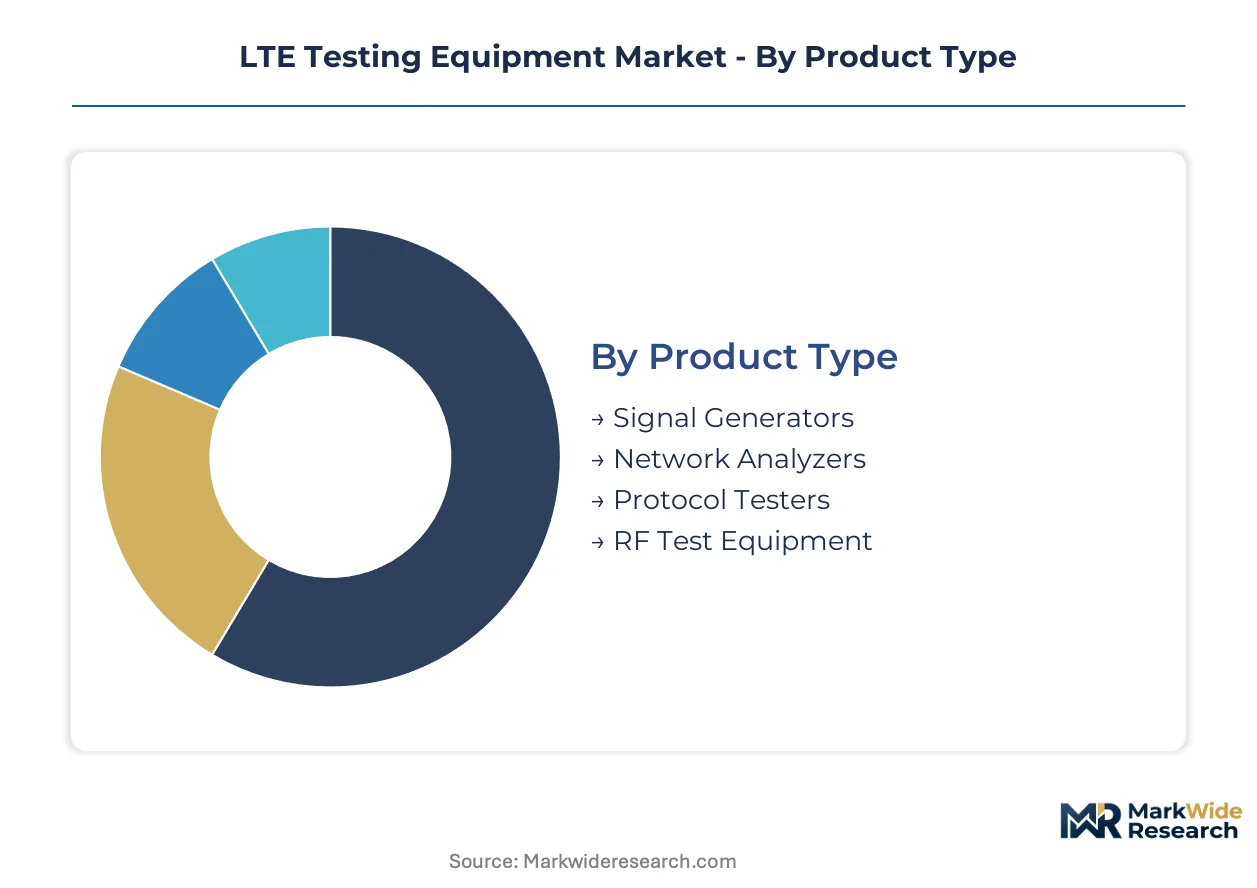
LTE testing equipment segmentation reveals how procurement priorities diverge across validation workflows. Equipment manufacturers prioritize protocol stack verification while telecom operators concentrate investment on RF conformance for live network deployment.
Product Type:
Substitution pressure from software-defined alternatives is reshaping instrument procurement, with modular FPGA platforms displacing traditional hardware stacks in mid-tier laboratories.
- Signal Generators:Vector signal generators synthesize complex LTE waveforms with carrier aggregation configurations up to five component carriers. Demand concentrates in Germany and the United States where 3GPP Release 17 certification laboratories require precision modulation for inter-band contiguous testing.
- Network Analyzers:Scalar and vector network analyzers characterize base station antenna impedance and filter response across 700 MHz to 2.6 GHz bands. Testing laboratories in South Korea and Taiwan are expanding installed base to support device manufacturing clusters co-located with semiconductor foundries.
- Protocol Testers:Stack validation systems for NAS and RRC layer compliance.
- RF Test Equipment:Spectrum analyzers and power meters for spurious emission verification.
RF Test Equipment anchors the volume base while Protocol Testers gain share at the steepest rate.
End User:
Customer procurement sophistication separates captive R&D investment from outsourced validation services, with margin structures diverging sharply across these institutional types.
- Telecom Operators:AT&T, Verizon, and Deutsche Telekom maintain internal test beds for live network interoperability validation. North American operators are expanding VoLTE handover test capacity ahead of 5G standalone core migrations, compressing procurement timelines for multi-band signal analyzers.
- Equipment Manufacturers:Ericsson, Nokia, and Samsung Networks invest in pre-conformance testing to reduce third-party laboratory dependency. These stakeholders face FCC Part 27 equipment authorization deadlines that mandate iterative retesting when spectrum refarming occurs.
- R&D Institutions:University laboratories and government research centers with limited capital budgets.
- Testing Laboratories:Third-party conformance facilities accredited under ETSI and FCC frameworks.
Equipment Manufacturers dominate capital expenditure while Testing Laboratories expand most quickly through service unbundling trends.
Deployment:
Elastic capacity requirements are fragmenting procurement between perpetual instrument ownership and subscription-based access models.
- On-Premises:Permanent bench installations with calibrated reference standards for high-throughput certification cycles. German automotive Tier-1 suppliers favor this model for C-V2X protocol validation where test repeatability is critical.
- Cloud-Based:Remote instrument access with FPGA virtualization for sporadic waveform prototyping. India's PLI scheme beneficiaries are adopting these platforms to avoid capital-intensive infrastructure buildout in nascent manufacturing zones.
- Hybrid:Mixed ownership combining captive hardware for routine testing with cloud burst capacity.
- Mobile:Portable field test sets for drive testing and over-the-air measurement campaigns.
On-Premises retains the largest installed base while Cloud-Based deployment climbs the fastest among new laboratory entrants.
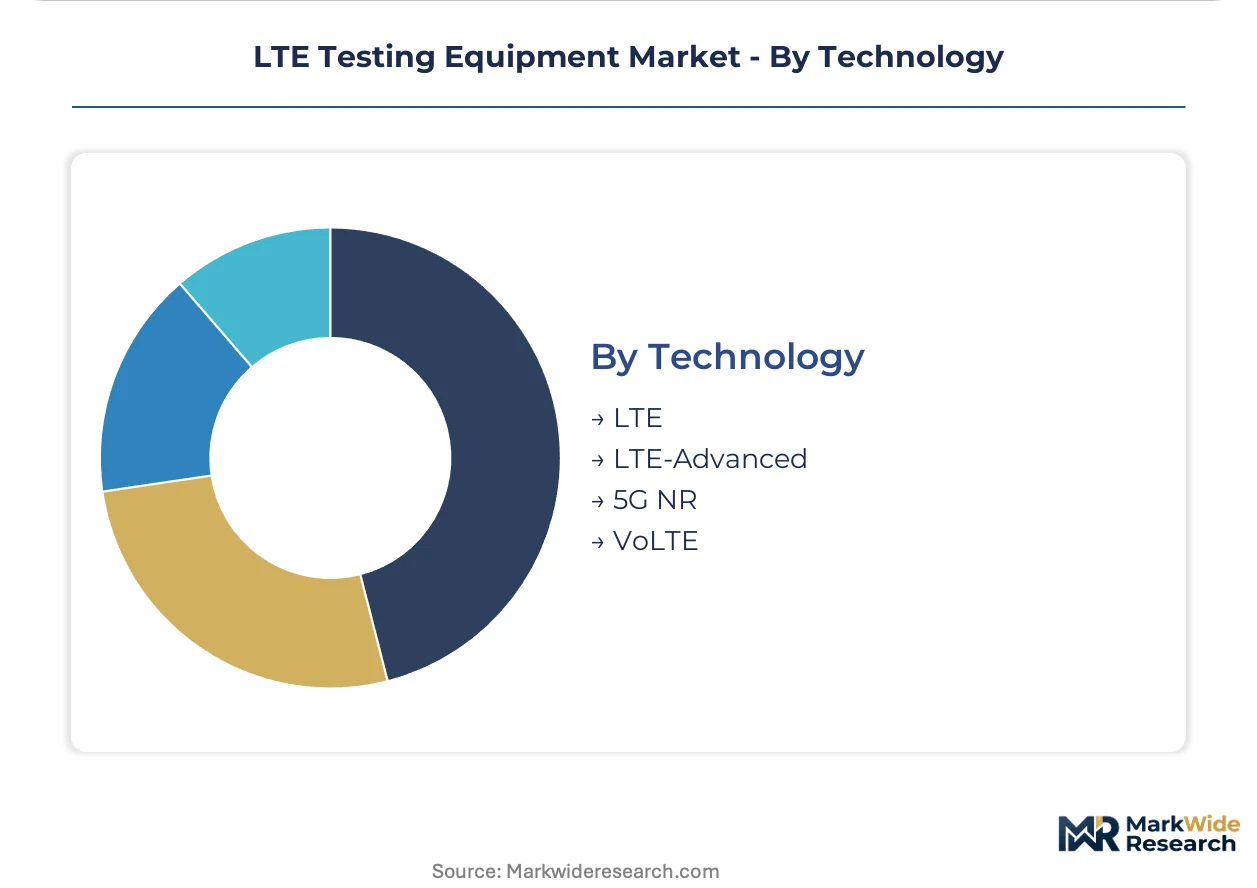
Technology:
Multi-release protocol support is forcing firmware architecture complexity that favors incumbents with deep calibration IP libraries.
- LTE:Baseline FDD and TDD conformance testing for legacy device certification. Demand persists in India and Southeast Asia where 4G network buildout continues alongside 5G overlay deployment.
- LTE-Advanced:Carrier aggregation and enhanced MIMO validation for Category 6 through 12 devices. United States and Japanese operators require this capability for AWS-3 and 2.5 GHz band certification under FCC and ARIB frameworks.
- 5G NR:Non-standalone and standalone protocol testing with LTE anchor requirements.
- VoLTE:IMS-based voice continuity and SRVCC handover verification.
LTE-Advanced captures the highest replacement cycle velocity while VoLTE shows the steepest expansion trajectory among technology segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for telecom manufacturing is accelerating RF validation infrastructure buildout in emerging production zones. FCC equipment authorization rules in the United States compress procurement timelines for conformance testers. Germany anchors European demand through integrated signal generator and network analyzer portfolios.
United States
AT&T and Verizon are expanding VoLTE handover test capacity ahead of 5G standalone core migrations. FCC Part 27 equipment authorization mandates iterative retesting when carriers refarm 700 MHz and AWS-3 bands. Testing laboratories in California and Texas are scaling multi-band signal analyzer procurement to meet compressed certification deadlines.
Germany
Automotive Tier-1 suppliers favor on-premises bench installations for C-V2X protocol validation where test repeatability is critical. ETSI harmonized standards for RED 2014/53/EU compliance mandate enhanced spurious emission testing for carrier aggregation configurations. Munich and Stuttgart clusters concentrate R&D investment from Rohde & Schwarz and Keysight Technologies regional operations.
India
PLI scheme beneficiaries are adopting cloud-based platforms to avoid capital-intensive infrastructure buildout in nascent manufacturing zones. TRAI spectrum allocation frameworks drive iterative device recertification as bands refarm between operators. Bengaluru and Hyderabad testing facilities are expanding to support domestic 4G device production clusters.
South Korea
Samsung Networks and semiconductor foundries co-locate validation facilities near device assembly operations. ARIB certification frameworks for 2.5 GHz band testing compress procurement timelines for LTE-Advanced conformance equipment. Seoul and Suwon corridors concentrate outsourced 3GPP TS 36.521 certification to specialized third-party laboratories.
Japan
NTT Docomo maintains internal test beds for live network interoperability validation ahead of 5G migrations. METI industrial standards coordination shapes domestic procurement specifications for protocol stack verification. Tokyo and Osaka metropolitan areas anchor demand for precision temperature-compensated crystal oscillator supply chains.
LTE Testing Equipment Market Competitive Environment
Player mix skews toward diversified instrumentation conglomerates with deep calibration IP libraries. Market structure concentrates around incumbent vendors sustaining dominance through protocol validation suite ownership. Two strategic archetypes emerge: integrated hardware-software platform providers and specialized RF component suppliers. Competitive moves center on cloud-native test orchestration partnerships and modular FPGA-based platform diversification.
Within the diversified instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify integrated platform providers with extensive geographic footprints. Spirent Communications occupies a position among protocol validation specialists. Zhejiang Dingli Machinery represents Chinese manufacturing-scale entrants. Anritsu and EXFO sit within the RF test equipment specialization vector. Tektronix and Fluke Corporation anchor mid-tier laboratory instrumentation supply. Agilent Technologies, through its historical instrumentation lineage, exemplifies legacy calibration IP concentration.
| Leading Market Players |
|---|
| Spirent Communications |
| EXFO |
| Keysight Technologies |
| Agilent Technologies |
| Fluke Corporation |
| Rohde & Schwarz |
| Tektronix |
| Zhejiang Dingli Machinery |
| Anritsu |
| Others |
Value Chain & Pricing Dynamics
Calibration-laboratory utilization rates above 80 percent in Germany and the United States create scale economies that compress unit testing costs while concentrating procurement power among multi-site certification facilities. This capacity concentration simultaneously elevates price floors for precision oscillator components and fragments margin structures across instrument tiers.
Pricing Analysis
Certification level (CE marking under RED 2014/53/EU versus non-harmonized laboratory validation) creates the primary spread across pricing tiers. Three-tier pricing structure across premium, standard, and economy levels segments procurement: premium tiers bundle 3GPP Release 17 protocol libraries with multi-year calibration contracts, while economy tiers target single-band RF validation. Pricing pressure stems from cloud-native test orchestration platforms that displace perpetual instrument ownership with subscription models. Equipment manufacturers exhibit lowest price sensitivity due to captive R&D mandates, whereas third-party testing laboratories in India and Southeast Asia prioritize capital efficiency.
Supply Chain Analysis
Temperature-compensated crystal oscillator fabrication concentrates in Japan and Germany, creating input chokepoints for precision signal generation hardware. Vector signal processing chipsets draw from Taiwan and South Korea foundries, while FPGA modules for software-defined platforms source from United States and Chinese suppliers. Single-source vulnerability in Japanese oscillator supply exposes lead time volatility when automotive C-V2X certification cycles spike. Distribution runs through direct OEM relationships for tier-1 instrumentation vendors, with regional distributors serving mid-tier laboratory procurement in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millimeter-wave calibration expertise scarcity above 6 GHz constrains laboratory expansion velocity and elevates technician training costs across certification facilities. This capability gap separates incumbent vendors with established training pipelines from challengers dependent on external vocational partnerships.
For Market Incumbents: Consolidate protocol validation suite ownership through exclusive 3GPP waveform library licensing to defend against modular FPGA platform substitution. Expand captive calibration service networks in India to capture PLI scheme infrastructure buildout. Vertical integration into temperature-compensated crystal oscillator supply hedges against Japanese component bottlenecks during automotive C-V2X demand surges. For New Entrants and Emerging Players: Differentiate on cloud-native test orchestration with elastic capacity models targeting India's nascent manufacturing zones. White-space concentration exists in automotive Tier-1 C-V2X protocol validation where German suppliers demand on-premises repeatability. Target South Korean semiconductor foundry co-location corridors with outsourced 3GPP TS 36.521 certification services. Go-to-market through testing laboratory accreditation partnerships accelerates regulatory credibility without captive hardware investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among protocol validation specialists with subscription-based waveform library access. Long-term viability hinges on multi-release firmware architecture supporting simultaneous 3GPP Releases 15 through 17 compliance. Acquisition candidates with deep calibration IP and established FCC Part 27 laboratory relationships offer defensive positioning. Signal to watch: spectrum auction schedules in the United States and India that cluster certification deadline windows and spike demand volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Test Orchestration Platform | Enables Indian PLI beneficiaries to avoid capital-intensive bench instrument procurement. |
| Multi-Release Firmware Architecture | Supports simultaneous 3GPP Releases 15-17 compliance for LTE-Advanced Pro certification. |
| Automotive C-V2X Validation Partnership | Captures adjacent demand from German Tier-1 suppliers requiring test repeatability. |
| Calibration Service Network Expansion | Addresses millimeter-wave expertise scarcity constraining laboratory capacity growth. |
| Protocol Validation Suite Licensing | Defends incumbent margin position against modular FPGA platform substitution pressure. |
Study Parameters
Desk research of 3GPP release documentation, FCC equipment authorization databases, and ETSI harmonized standards preceded structured interviews with testing laboratory directors, RF instrumentation procurement managers, and automotive Tier-1 validation engineers. Secondary triangulation incorporated SEC filings from diversified instrumentation conglomerates, customs records for temperature-compensated crystal oscillator trade flows, and TRAI spectrum allocation notifications. Bottom-up demand modeling across certification laboratory capacity expansion combined with top-down market sizing from instrument shipment data.
Variance decomposition across technology segments, deployment models, and end-user archetypes shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include product type, end-user institutional category, deployment architecture, and protocol release tier. CAGRs derived from instrument replacement cycle compression analysis and spectrum refarming schedule clustering. Industry-specific forecast inputs encompassed VoLTE handover mandate timelines and automotive C-V2X certification pathway adoption curves.
Material uncertainties — 3GPP release cadence acceleration, FCC Part 27 rule modifications, and temperature-compensated crystal oscillator supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding carrier aggregation complexity persistence and cloud-based deployment adoption velocity among emerging market laboratories. Practitioners should keep alternative scenarios live as 5G standalone migration timelines and spectrum auction clustering patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
United States Signal Generator Market
Test and Measurement
Battery Testing Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Distortion Meter Market