
 Printed Circuit Board Inspection Equipment Market | 2026-2036
Printed Circuit Board Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Circuit Board Inspection Equipment Market Analytics
IPC-A-610 qualification cycles for electronics assembly is reorganizing competitive tiers among inspection equipment vendors. Koh Young Technology leverages its 3D solder paste inspection leadership to anchor premium positioning in East Asian fabs. Mirtec competes through integrated machine vision architectures that span optical and X-ray modalities. Nordson controls material dispensing and inspection convergence through upstream process integration.
Printed circuit board inspection equipment comprises automated systems that evaluate conductor traces, solder joints, and component placement against geometric tolerances, typically resolving defects below 10 microns using structured light or transmission imaging. These systems prevent field failures in high-reliability electronics by intercepting process deviations before downstream assembly. Automated optical inspection leads installed base volumes while X-ray inspection captures the fastest expansion, driven by hidden solder joint verification in multilayer boards and automotive power modules. Machine vision technology concentrates margin pools where deep learning classification reduces false-call rates below legacy rule-based thresholds.
FDA device manufacturing regulations, EU RoHS substance restrictions, and China's GB standards for electronic product quality collectively elevate inspection stringency across export-oriented supply chains. REACH compliance in Europe and EPA hazardous substance rules in the United States force equipment vendors to certify contaminant-free construction and validate traceability protocols. Stakeholders must weigh capital deployment timing against the transition from 2D to 3D inspection architectures as miniaturization thresholds compress acceptable defect margins.
Market Dynamics
The transition from 2D to 3D inspection architectures is compressing acceptable defect margins below 10 microns and forcing capital redeployment across automotive and consumer electronics fabs.
Growth Catalysts
- Automotive Power Module Verification:Hidden solder joint inspection in multilayer boards is accelerating X-ray system deployment as electric vehicle inverters demand zero-defect reliability.
- EU F-Gas Regulation:Refrigerant phase-down mandates are tightening material compliance requirements for inspection equipment cooling systems, elevating certified vendor status.
- China's Semiconductor Self-Sufficiency:Government-backed domestic PCB fabrication capacity expansion is concentrating equipment demand in East Asian supply chains.
Market Restraints
- Deep Learning Hardware Costs:GPU-accelerated classification engines require specialized compute infrastructure that inflates system price points beyond mid-tier fab budgets.
- Optical Component Supply Concentration:Structured light source modules depend on concentrated East Asian photonics suppliers exposed to trade friction.
- RoHS Substance Substitution Limits:Lead-free solder alloys introduce inspection artifacts that degrade false-call performance versus legacy tin-lead benchmarks.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are creating greenfield inspection demand without legacy 2D system write-off constraints.
- Machine Vision-AI Convergence:Deep learning classification integrated with optical and X-ray modalities enables unified defect taxonomy across process steps.
- EPA Hazardous Substance Rules:Traceability protocol mandates for contaminant-free construction validate premium equipment positioning in US medical device supply chains.
Industry Challenges
- IPC-A-610 Certification Velocity:Qualification cycle compression for electronics assembly standards strains vendor technical support bandwidth.
- Legacy System Integration Friction:Retrofitting 3D SPI and AOI architectures into existing SMT lines requires custom mechanical interfaces and software middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Circuit Board Inspection Equipment Market |
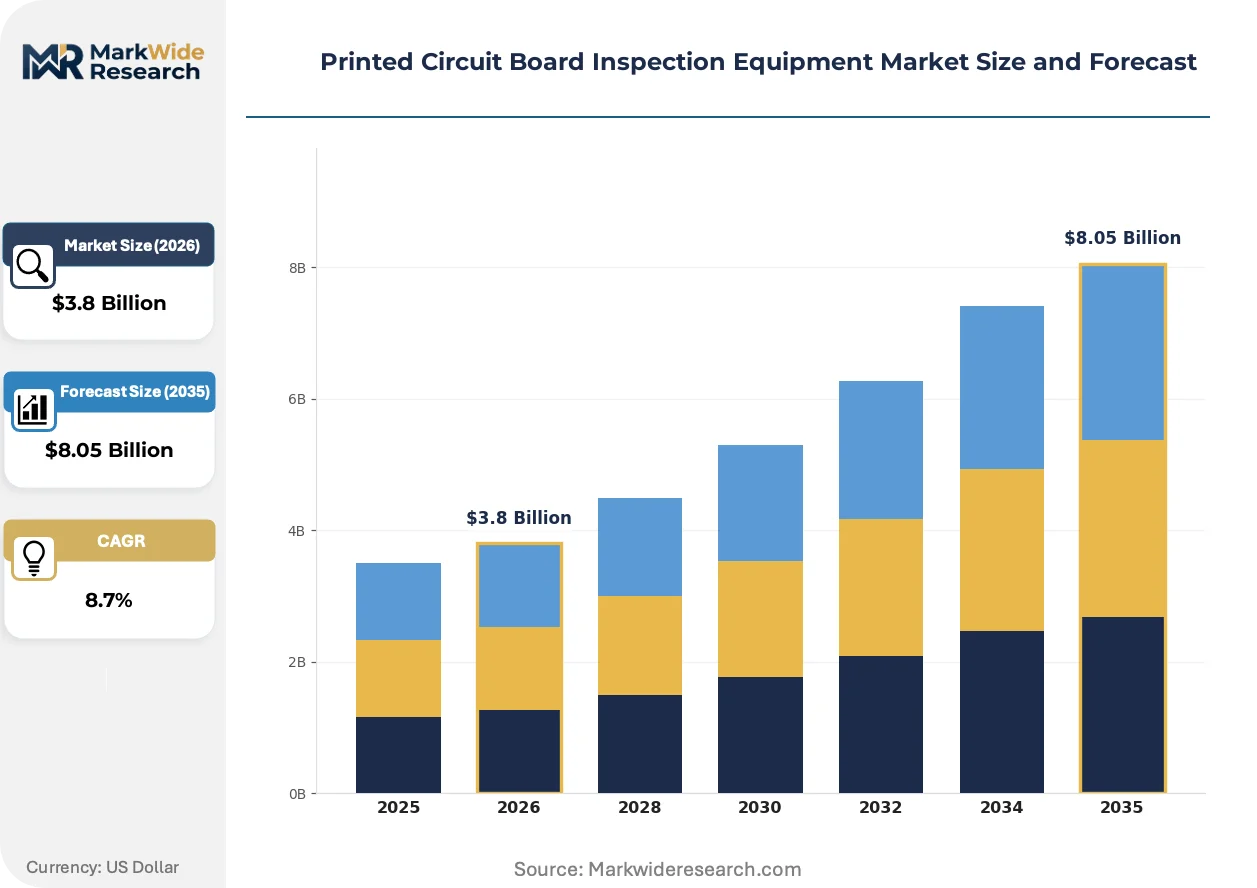
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Optical Inspection, X-Ray Inspection, Digital Multimeters, In-Circuit Testers Technology: 2D Imaging, 3D Imaging, Laser Inspection, Machine Vision End User: Consumer Electronics, Telecommunications, Aerospace, Automotive Components Application: Quality Control, Fault Detection, Process Improvement, Compliance Verification |
| Companies Covered | Mirtec, Viscom AG, Koh Young Technology, Cognex Corporation, Saki Corporation, Omron Corporation, ViTrox, Test Research, Nordson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Circuit Board Inspection Equipment Market Evolving Landscape
Deep learning classification is compressing false-call rates below rule-based thresholds while regulatory substance restrictions and procurement centralization reshape equipment specification workflows.
Structured light 3D measurement is fragmenting inspection task allocation between optical and X-ray modalities. Automotive electronics manufacturers in Germany and Japan are adopting hybrid architectures that route high-aspect-ratio joints to transmission imaging while delegating surface defects to structured light systems. This fragmentation is compressing standalone 2D AOI system margins and forcing vendors to bundle multi-modal platforms.
EU RoHS directive revisions are tightening cadmium and hexavalent chromium thresholds in electronic product quality standards. Equipment vendors must now certify contaminant-free construction and validate material traceability protocols through REACH-registered supply chains. Medical device manufacturers in Ireland and the Netherlands face the steepest compliance ramps as notified bodies integrate substance screening into CE marking audits.
Centralized procurement through EMS consolidators is displacing individual OEM equipment specification. Foxconn, Jabil, and Pegatron are standardizing inspection platforms across their global facility networks, compressing vendor count and extending pay-for-performance service terms. This concentration is most visible in Mexico and Vietnam, where greenfield electronics manufacturing zones favor single-source inspection contracts with outcome-based uptime guarantees.
Printed Circuit Board Inspection Equipment Market Segmentation
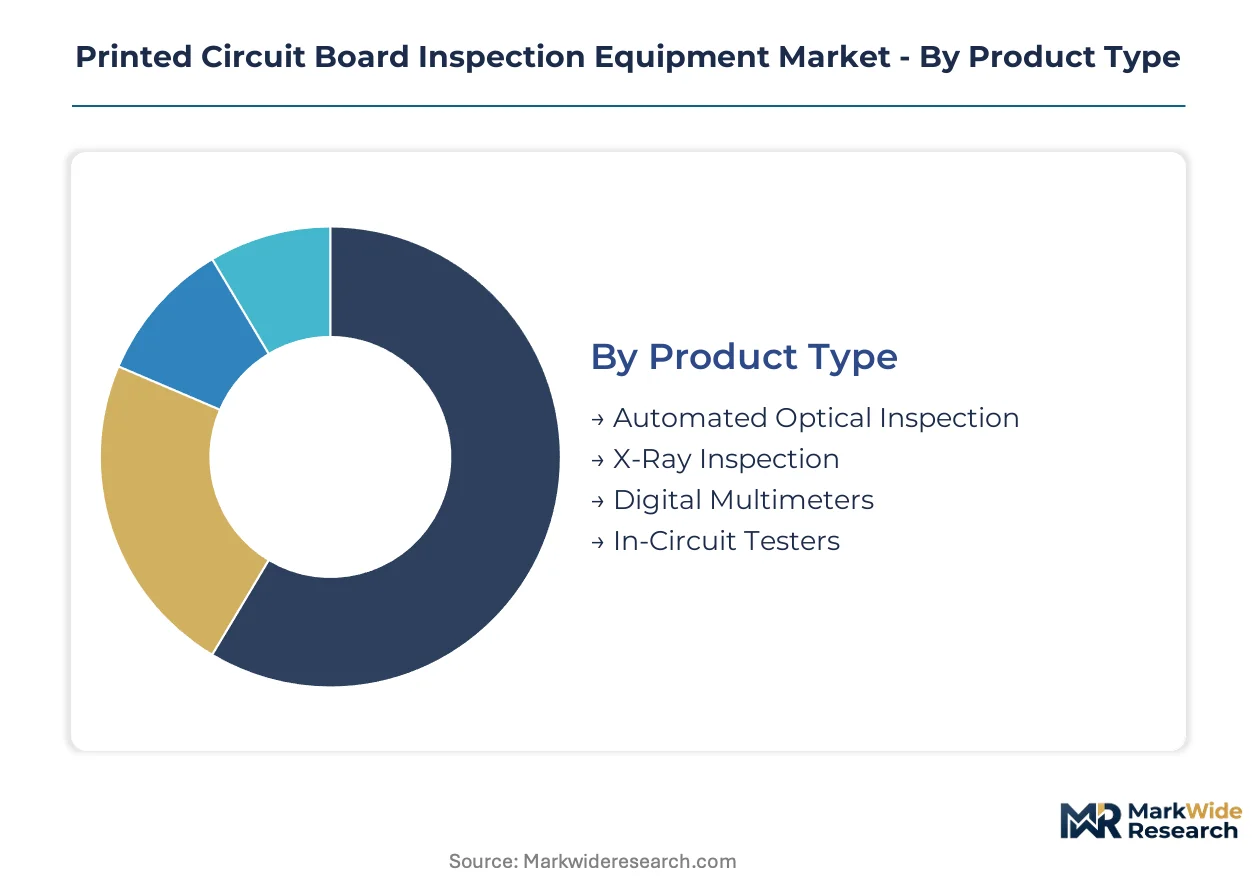
Segmentation in PCB inspection equipment reveals divergent technology maturities and geographic demand patterns. Equipment vendors configure product portfolios around inspection depth requirements and end-use reliability thresholds.
Product Type:
Domestic demand in China and Taiwan concentrates in high-throughput optical systems, while European and North American buyers prioritize X-ray modalities for automotive and medical applications.
- Automated Optical Inspection:Structured light and camera-array systems evaluate solder joint geometry, component placement, and trace integrity at production line speeds. Consumer electronics fabs in Shenzhen and Dongguan deploy these systems in high-density configurations to match smartphone PCB output volumes.
- X-Ray Inspection:Transmission imaging penetrates multilayer boards and flip-chip packages to verify hidden solder joints and void ratios. German automotive electronics manufacturers mandate these systems for electric vehicle inverter modules where field failure carries liability exposure.
- Digital Multimeters:Handheld and benchtop units provide parametric verification of resistance, capacitance, and voltage during prototype validation and repair operations.
- In-Circuit Testers:Bed-of-nails and flying-probe architectures isolate manufacturing defects through electrical stimulus-response testing before functional assembly.
Automated optical inspection commands the established base. The steepest expansion runs through X-ray inspection.
Technology:
Cost tiers separate legacy 2D implementations from premium 3D architectures, with mid-tier fabs facing forced upgrade cycles as miniaturization thresholds tighten.
- 2D Imaging:Planar camera systems capture top-down views of PCB surfaces for defect classification against geometric templates. These systems retain installed base presence in cost-sensitive consumer electronics operations across Vietnam and Mexico where legacy SMT lines limit capital replacement velocity.
- 3D Imaging:Structured light projection and multi-angle triangulation reconstruct volumetric solder joint profiles with sub-10-micron resolution. Japanese automotive suppliers in Nagoya and Toyota City require these systems for advanced driver-assistance module verification.
- Laser Inspection:Confocal and triangulation laser scanning measures coplanarity and height variation on component leads and BGA spheres.
- Machine Vision:Deep learning classification pipelines reduce false-call rates through trained neural networks that generalize across defect morphologies.
2D imaging retains volume leadership in installed base. 3D imaging gains share fastest as geometric tolerance requirements compress.
End User:
Application maturity varies sharply, with aerospace and automotive imposing qualification burdens that consumer electronics bypass.
- Consumer Electronics:Smartphone, tablet, and wearable manufacturers drive throughput-optimized inspection configurations with minimized cycle times. Foxconn and Pegatron facilities in Zhengzhou and Chennai prioritize optical inspection speed over absolute defect resolution depth.
- Automotive Components:Power module, sensor, and control unit suppliers face zero-defect reliability mandates under functional safety standards. Bosch and Continental operations in Reutlingen and Regensburg deploy hybrid optical-X-ray architectures for inverter PCB verification.
- Telecommunications:Base station and optical networking equipment manufacturers balance reliability requirements against capital efficiency in 5G infrastructure rollout.
- Aerospace:Avionics and satellite electronics suppliers under FAA and EASA oversight enforce IPC-A-610 Class 3 inspection protocols with full traceability documentation.
Consumer electronics commands the established base. Automotive components exhibit the steepest expansion trajectory as electrification multiplies PCB content per vehicle.
Application:
Customer type bifurcation separates OEM in-house operations from EMS provider networks with divergent specification authority and procurement centralization.
- Quality Control:Statistical process control integration captures defect trends for upstream feedback to solder paste printing and component placement operations. EMS consolidators in Guadalajara and Bac Ninh standardize these systems across multi-customer lines.
- Fault Detection:Inline screening intercepts process deviations before downstream value-add operations compound rework costs. Medical device manufacturers in Galway and Minneapolis face FDA 21 CFR Part 820 traceability requirements that elevate inspection documentation stringency.
- Process Improvement:Inspection data analytics identify systematic variation in printing, placement, and reflow parameters for continuous improvement programs.
- Compliance Verification:Audit-ready inspection records support CE marking, UL listing, and customer quality system certifications with timestamped defect evidence.
Quality control commands the established base. Compliance verification climbs fastest as regulatory substance restrictions and medical device traceability mandates expand documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates among automotive electronics manufacturers in Germany, EMS consolidators in Mexico, and semiconductor packaging fabs in China. Each geography imposes distinct qualification burdens and cooling system compliance requirements. Domestic fabrication capacity expansion in East Asia continues redirecting capital flows.
Germany
Bosch and Continental operations in Reutlingen and Regensburg drive X-ray system deployment for electric vehicle inverter verification. EU F-Gas Regulation refrigerant phase-down mandates elevate certified vendor status for equipment cooling systems. The Baden-Württemberg automotive cluster anchors hybrid optical-X-ray architecture adoption.
China
Domestic PCB fabrication capacity expansion concentrates equipment demand in Shenzhen and Dongguan smartphone manufacturing zones. Government-backed semiconductor self-sufficiency programs accelerate capital deployment for advanced packaging inspection. Yangtze River Delta fabs prioritize high-throughput optical configurations.
Mexico
Foxconn and Jabil facilities in Guadalajara standardize inspection platforms across multi-customer EMS lines. Greenfield electronics manufacturing zones favor single-source contracts with outcome-based uptime guarantees. The Bajío Region attracts automotive electronics suppliers seeking NAFTA-adjacent production.
Japan
Toyota City and Nagoya automotive suppliers require 3D structured light systems for advanced driver-assistance module verification. METI industrial standards enforce traceability protocols that elevate documentation stringency. Chubu region fabs lead sub-10-micron resolution adoption.
United States
Medical device manufacturers in Minneapolis face FDA 21 CFR Part 820 traceability requirements that compress inspection documentation cycles. EPA hazardous substance rules validate premium equipment positioning in contaminant-free construction certification. Pacific Northwest telecommunications equipment suppliers balance 5G infrastructure reliability against capital efficiency.
Printed Circuit Board Inspection Equipment Market Competitive Landscape
Player mix skews toward East Asian precision equipment specialists and European industrial automation conglomerates. Market structure exhibits tiered concentration where 3D inspection capability separates premium positioning from mid-tier alternatives. Strategic archetypes include optical modality pure-plays, multi-modal platform bundlers, and upstream process integrators. Dominant competitive moves encompass technology licensing for deep learning classification engines and geographic expansion through EMS consolidator framework agreements.
Within the multi-modal platform tier, Koh Young Technology and Mirtec exemplify divergent architectural approaches to 3D solder paste inspection and integrated machine vision. Viscom AG occupies a position among German precision equipment fabricators serving automotive reliability mandates. These three anchors illustrate how vendor specialization around optical depth, X-ray penetration, or hybrid convergence shapes competitive differentiation without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Mirtec |
| Viscom AG |
| Koh Young Technology |
| Cognex Corporation |
| Saki Corporation |
| Omron Corporation |
| ViTrox |
| Test Research |
| Nordson |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation refrigerant phase-down mandates and IPC-A-610 certification cycles simultaneously gate vendor qualification and stratify price tiers, compressing margins for uncertified suppliers while elevating premium positioning for compliant equipment manufacturers serving automotive and medical device fabs.
Pricing Analysis
Cost-plus contracts with semiconductor capital expenditure indexation dominate equipment procurement between EMS consolidators and tier-one vendors. Three-tier pricing structure across premium 3D optical, standard 2D AOI, and economy refurbished systems separates Bosch and Continental automotive mandates from Foxconn consumer electronics volume buys. Pricing pressure stems from GPU-accelerated deep learning hardware inflating system costs beyond mid-tier fab budgets. Consumer electronics EMS providers exhibit highest price sensitivity; medical device manufacturers under FDA 21 CFR Part 820 show lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German automotive electronics manufacturers, while Chinese domestic PCB fabs maintain strategic stockpiles of structured light source modules against photonics supplier concentration risk. East Asian photonics suppliers in Taiwan and South Korea dominate structured light source modules; German precision mechanics fabricators anchor motion control subsystems. Single-source vulnerability concentrates in high-resolution camera sensors from Sony and ON Semiconductor. Distribution runs through EMS consolidator framework agreements with outcome-based uptime guarantees rather than discrete equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as automotive electrification multiplies PCB inspection points per vehicle, with X-ray modality penetration in power module verification still below saturation thresholds across European and North American supply chains.
For Market Incumbents: Compound 3D SPI-AOI architecture leadership through backward integration into structured light source manufacturing, neutralizing East Asian photonics supplier concentration risk. Accelerate IPC-A-610 Class 3 certification velocity to defend against emerging machine vision-AI pure-plays. Lock in EMS consolidator framework agreements in Mexico and Vietnam before greenfield capacity absorbs competitor share.
For New Entrants and Emerging Players: FDA 510(k) fast-track for medical device inspection documentation systems opens white-space in Minneapolis and Galway manufacturing clusters. Target India's PLI scheme semiconductor packaging greenfields, where legacy 2D system write-off constraints do not exist. Lead with deep learning false-call reduction as differentiated go-to-market pitch against rule-based incumbent architectures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across X-ray inspection sub-segments as transmission imaging complexity demands specialized GPU compute infrastructure. Five-to-ten-year viability favors multi-modal platform bundlers with optical-X-ray convergence capability over pure-play optical vendors. Watch for inflection when automotive power module X-ray penetration crosses critical mass in German and Japanese supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Integration | Bosch and Continental mandates hybrid optical-X-ray architectures for EV inverter verification. |
| Deep Learning Classification Engine Development | GPU-accelerated neural networks reduce false-call rates below legacy rule-based thresholds. |
| EMS Consolidator Framework Agreements | Foxconn and Jabil standardize platforms across Guadalajara and Bac Ninh facilities. |
| EU F-Gas Cooling System Certification | Refrigerant phase-down mandates elevate certified vendor status in German automotive clusters. |
| India PLI Scheme Geographic Expansion | Greenfield semiconductor packaging demand avoids legacy 2D system replacement friction. |
Research Methodology
Desk research of SEC equipment vendor filings, ECHA REACH substance databases, and EMS consolidator procurement disclosures preceded structured interviews with SMT line engineers, automotive electronics quality directors, medical device regulatory affairs leads, and photonics component procurement managers. Primary fieldwork captured capital deployment timing, 2D-to-3D transition friction, and cooling system compliance verification workflows. Secondary validation drew from FDA 510(k) device listings, EU F-Gas Regulation implementation guidance, and China MIIT semiconductor self-sufficiency program announcements. Bottom-up equipment shipment modeling triangulated against top-down PCB fabrication capacity expansion forecasts.
Variance decomposition across technology adoption curves, regulatory compliance ramps, and geographic demand concentration shaped analytical framework construction over the projection horizon. Segmentation dimensions spanned inspection modality depth, end-use reliability tier, and customer type bifurcation between OEM in-house operations and EMS provider networks. CAGRs derived from equipment shipment elasticities against PCB output volumes and miniaturization threshold compression rates. Industry-specific inputs included automotive power module content-per-vehicle trajectories and medical device traceability mandate expansion timelines.
Underlying assumptions cover sustained automotive electrification capital deployment, continued East Asian photonics supplier dominance, and stable EU F-Gas Regulation implementation pace, with deviation risk concentrated in trade friction disrupting structured light source module availability and RoHS substance substitution limits degrading inspection algorithm performance. Revision becomes warranted when X-ray inspection cost curves intersect 3D optical system price points or when India PLI scheme incentives trigger accelerated greenfield capacity absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Sound Meter Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Density Meter Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Electrical and Electronic Test Equipment Market