
 Continuous Methane Monitoring and Leak Detection Test Equipment Market | 2026-2036
Continuous Methane Monitoring and Leak Detection Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Methane Monitoring and Leak Detection Test Equipment Market Insights
Quartz-enhanced photoacoustic spectroscopy is consolidating as the preferred sensing modality for sub-ppm methane detection in harsh field conditions. Honeywell International leverages its distributed control systems heritage to bundle fixed sensors with plant-wide analytics platforms. Teledyne FLIR competes through thermal imaging integration that visualizes invisible plumes for rapid leak localization. MSA Safety anchors its position in worker-wearable portable detectors for confined-space entry protocols.
Continuous methane monitoring and leak detection test equipment encompasses permanently installed and mobile instrumentation that quantifies CH4 concentrations through optical absorption, electrochemical reaction, or acoustic signature analysis, typically achieving detection thresholds below one part per million with response times under ten seconds. These systems serve to prevent explosive atmosphere formation, quantify greenhouse gas inventories, and trigger automated shutdown sequences in hydrocarbon handling facilities. Optical imaging systems command premium pricing due to semiconductor laser component costs yet deliver the fastest return on investment in compressor station applications where fugitive emissions cluster. Fixed sensors dominate unit volume as pipeline integrity mandates from the PHMSA drive blanket deployment across interstate transmission corridors. Portable detectors sustain steady replacement demand from environmental agencies conducting spot inspections and enforcement actions.
The EPA enforces quad-Oa standards that compel quarterly optical gas imaging surveys at oil and gas production sites, while the Inflation Reduction Act methane fee creates direct financial exposure for uncaptured emissions above reporting thresholds. OSHA maintains confined-space entry regulations that sustain baseline demand for personal gas detection across chemical processing and landfill gas operations. Buyers must evaluate whether laser absorption technology investments align with forthcoming federal certification requirements for continuous monitoring equivalence.
Market Dynamics
The EPA's quad-Oa methane standards are compressing deployment timelines for optical gas imaging systems, forcing operators to abandon periodic surveys in favor of continuous monitoring architectures that satisfy quarterly compliance mandates while eliminating fugitive emission blind spots between inspections.
Growth Catalysts
- Inflation Reduction Act methane fee:Direct financial exposure for uncaptured emissions above reporting thresholds compels investment in sub-ppm detection sensitivity across Permian Basin production facilities.
- PHMSA pipeline integrity mandates:Blanket deployment requirements across interstate transmission corridors sustain unit volume demand for fixed sensor networks with automated alarm integration.
- Certification of responsibly sourced natural gas:Investor pressure and offtake contract specifications in Gulf Coast export terminals drive adoption of continuous monitoring as a condition of supply chain eligibility.
Market Restraints
- Semiconductor laser component costs:Optical imaging systems command premium pricing due to distributed feedback laser diode supply concentration in East Asian foundries.
- Technical limitation in high-humidity environments:Tunable diode laser absorption spectroscopy suffers interference from water vapor cross-sensitivity, degrading detection reliability in coastal petrochemical corridors.
- Substitution threat from satellite-based monitoring:MethaneSAT and other orbital platforms offer basin-scale emissions quantification that competes with ground-based continuous monitoring for inventory verification purposes.
Strategic Opportunities
- Underpenetrated landfill gas operations:OSHA confined-space entry regulations sustain baseline demand for portable detectors, yet continuous perimeter monitoring remains nascent across municipal waste facilities in secondary markets.
- Technology convergence of thermal imaging and machine vision:Integration of FLIR thermal cores with edge-computing analytics enables automated plume detection without human operator interpretation.
- EU F-Gas Regulation extension:Proposed amendments to phase down hydrofluorocarbon use in refrigeration create adjacent demand for methane leak detection in cold chain infrastructure retrofits.
Industry Challenges
- Certification timeline compression:EPA continuous monitoring equivalence determinations lag hardware development cycles, creating uncertainty for operators seeking to substitute fixed sensors for quarterly OGI surveys.
- Integration complexity with legacy SCADA architectures:Brownfield compressor stations require protocol translation layers to incorporate methane concentration data into existing distributed control system alarm management hierarchies.
- Field calibration skill scarcity:Zero-span verification of quartz-enhanced photoacoustic sensors demands specialized technicians that pipeline operators struggle to retain in remote Permian and Bakken field locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Methane Monitoring and Leak Detection Test Equipment Market |
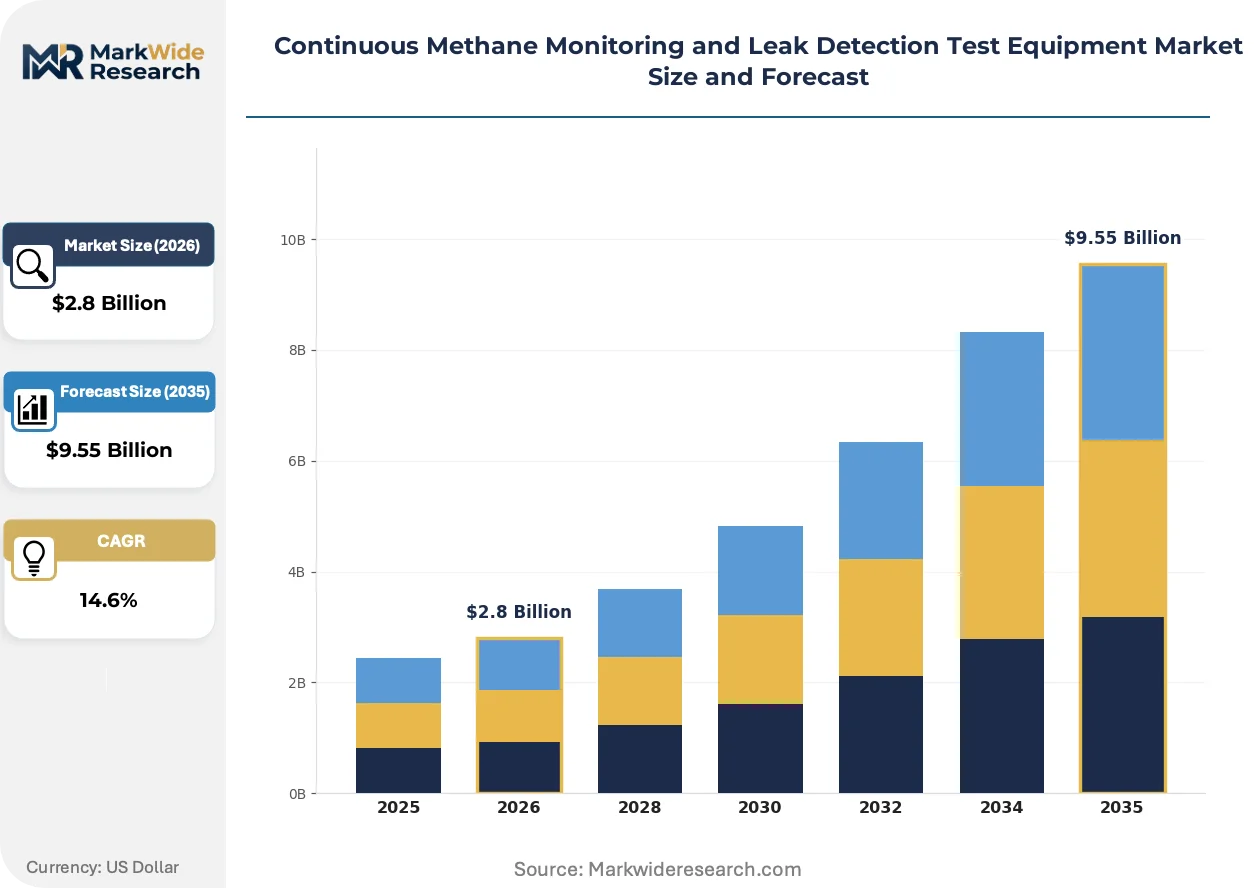
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Portable Detectors, Fixed Sensors, Optical Imaging Systems, Ultrasonic Detectors Technology: Infrared, Catalytic Bead, Photoionization, Semiconductor, Laser Absorption Application: Pipeline Integrity, Compressor Stations, Landfill Gas, Agricultural Emissions, Chemical Processing End User: Oil & Gas Operators, Landfill Managers, Farming Enterprises, Chemical Plants, Environmental Agencies |
| Companies Covered | Honeywell International, Teledyne FLIR, SLB, MSA Safety, Drägerwerk, Emerson, Qube Technologies, Project Canary, Sensirion Connected Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Methane Monitoring and Leak Detection Test Equipment Market Trends and Innovations
Detection modality preferences are fragmenting across end-use verticals as regulatory stringency diverges between production, transmission, and storage segments, with hardware vendors responding through platform architectures that accommodate multiple sensing technologies within unified analytics frameworks.
Quartz-enhanced photoacoustic spectroscopy is overtaking electrochemical and catalytic bead methods for sub-ppm methane detection in harsh field conditions. Permian Basin operators are adopting this solid-state modality at accelerating pace to satisfy EPA quarterly monitoring mandates without consumable sensor replacement. The technology is overtaking legacy infrared point detectors in compressor station applications where vibration and temperature cycling degrade conventional optical benches.
The EPA's updated methane emissions standards under the Inflation Reduction Act mandate quarterly optical gas imaging surveys with documented leak quantification. This regulatory architecture compels operators to deploy continuous monitoring systems that achieve equivalence certification, shifting capital allocation from mobile survey crews toward permanently installed sensor networks. Production facilities in Texas and New Mexico face the most compressed compliance deadlines and have responded with fastest deployment velocity.
Service unbundling is fragmenting traditional procurement relationships between operators and detection equipment vendors. Mid-size exploration companies now source sensors, telemetry hardware, and analytics software from separate suppliers, compressing switching cycles and eroding vendor lock-in. This pattern is most visible in the Denver-Julesburg Basin, where private equity-backed operators prioritize operational flexibility over integrated platform commitments.
Continuous Methane Monitoring and Leak Detection Test Equipment Market Segmentation
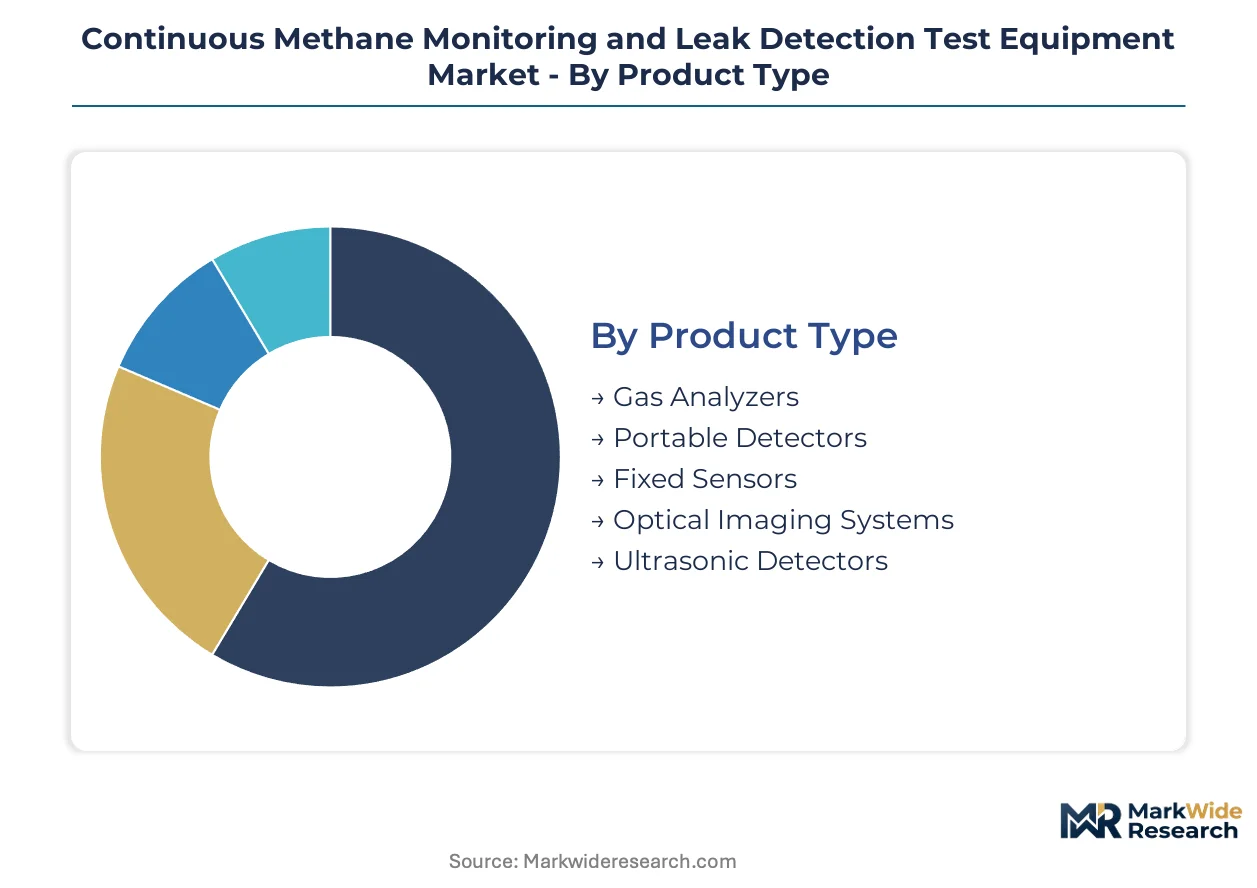
Segmentation in methane detection equipment reveals how hardware specifications align with regulatory exposure levels and operational risk profiles across hydrocarbon handling facilities. Procurement patterns diverge sharply between operators seeking standalone compliance instruments and those embedding sensors within plant-wide automation architectures.
Product Type:
Integration depth varies dramatically across product categories, with permanently installed networks demanding SCADA compatibility while portable units operate in isolation for spot-check protocols.
- Gas Analyzers:Laboratory-grade benchtop instruments quantify methane concentrations through gas chromatography or non-dispersive infrared methods with ppb-level precision. Demand clusters at environmental agency calibration laboratories and research facilities developing emission factors for the EPA greenhouse gas reporting program.
- Portable Detectors:Handheld or wearable units provide personal protection and spot measurement capabilities for confined-space entry and leak survey crews. OSHA mandates sustain replacement cycles across Texas and New Mexico oilfield services contractors facing compressed turnaround schedules.
- Fixed Sensors:Permanently mounted point detectors integrate with distributed control systems for automated alarm and shutdown sequences. Permian Basin pipeline operators deploy these in dense arrays along interstate transmission corridors to satisfy PHMSA integrity management deadlines.
- Optical Imaging Systems:Thermal cameras visualize invisible methane plumes through filtered infrared detection, enabling rapid leak localization without physical contact. Premium pricing reflects semiconductor laser component costs, yet compressor station operators recover investment through eliminated fugitive emission blind spots.
- Ultrasonic Detectors:Acoustic emission sensors identify turbulent gas releases through high-frequency sound signature analysis. These complement optical methods in fog-prone coastal corridors where thermal imaging suffers atmospheric attenuation.
Fixed sensors lead volumes today; optical imaging systems are gaining share fastest.
Technology:
Cost tiering separates mature electrochemical methods from emerging solid-state modalities commanding hardware premiums for sub-ppm sensitivity.
- Infrared:Non-dispersive infrared benches measure methane absorption at specific wavelengths using thermal or photonic detectors. These dominate budget-constrained municipal landfill operations where baseline leak detection satisfies regulatory minimums without performance overhead.
- Catalytic Bead:Pellistor-based sensors detect combustible gas through catalytic oxidation heat measurement. OSHA-confined space applications sustain steady demand despite cross-sensitivity limitations that disqualify these from EPA continuous monitoring equivalence certification.
- Photoionization:High-energy ultraviolet lamps ionize methane molecules for quantitative detection, offering rapid response times for emergency response scenarios. Fire departments and hazmat teams specify these for post-incident perimeter establishment.
- Semiconductor:Metal oxide sensors alter electrical resistance upon methane exposure, delivering low-cost detection for residential and light commercial applications. Sensitivity drift limits deployment in precision-critical oil and gas production environments.
- Laser Absorption:Tunable diode laser spectroscopy achieves part-per-billion detection thresholds through wavelength-modulated absorption measurement. Permian Basin operators prioritize this technology for Inflation Reduction Act compliance where uncaptured emissions trigger direct financial penalties.
Laser absorption commands the steepest expansion trajectory as EPA equivalence determinations elevate performance requirements.
Application:
Customer type fragmentation separates asset-intensive infrastructure operators from fragmented agricultural and waste management sectors with divergent procurement sophistication.
- Pipeline Integrity:Continuous monitoring along interstate transmission corridors prevents catastrophic releases and satisfies PHMSA integrity management regulations. Deployment concentrates in the Permian and Bakken formations where gathering line density creates concentrated emission profiles.
- Compressor Stations:Fugitive emissions cluster at compression equipment seals, vents, and pneumatic devices. Operators here prioritize optical gas imaging integration with machine vision analytics for automated plume detection without human operator interpretation.
- Landfill Gas:Municipal waste facilities capture methane for energy recovery while managing surface emission compliance. Underpenetrated continuous monitoring opportunities exist across secondary markets where periodic surface emission monitoring remains standard practice.
- Agricultural Emissions:Livestock operations and manure management systems face emerging measurement requirements for carbon accounting protocols. Dairy cooperatives in California and Wisconsin pilot sensor networks to certify low-carbon intensity milk production.
- Chemical Processing:Petrochemical crackers and syngas facilities monitor methane as both product loss indicator and explosion prevention measure. Gulf Coast integrated operators bundle detection systems with plant-wide safety instrumented systems.
Pipeline integrity leads volumes today; agricultural emissions is climbing the fastest as carbon accounting protocols mature.
End User:
Volume concentration sits with oil and gas operators, while margin opportunity concentrates in specialized environmental enforcement and certification segments.
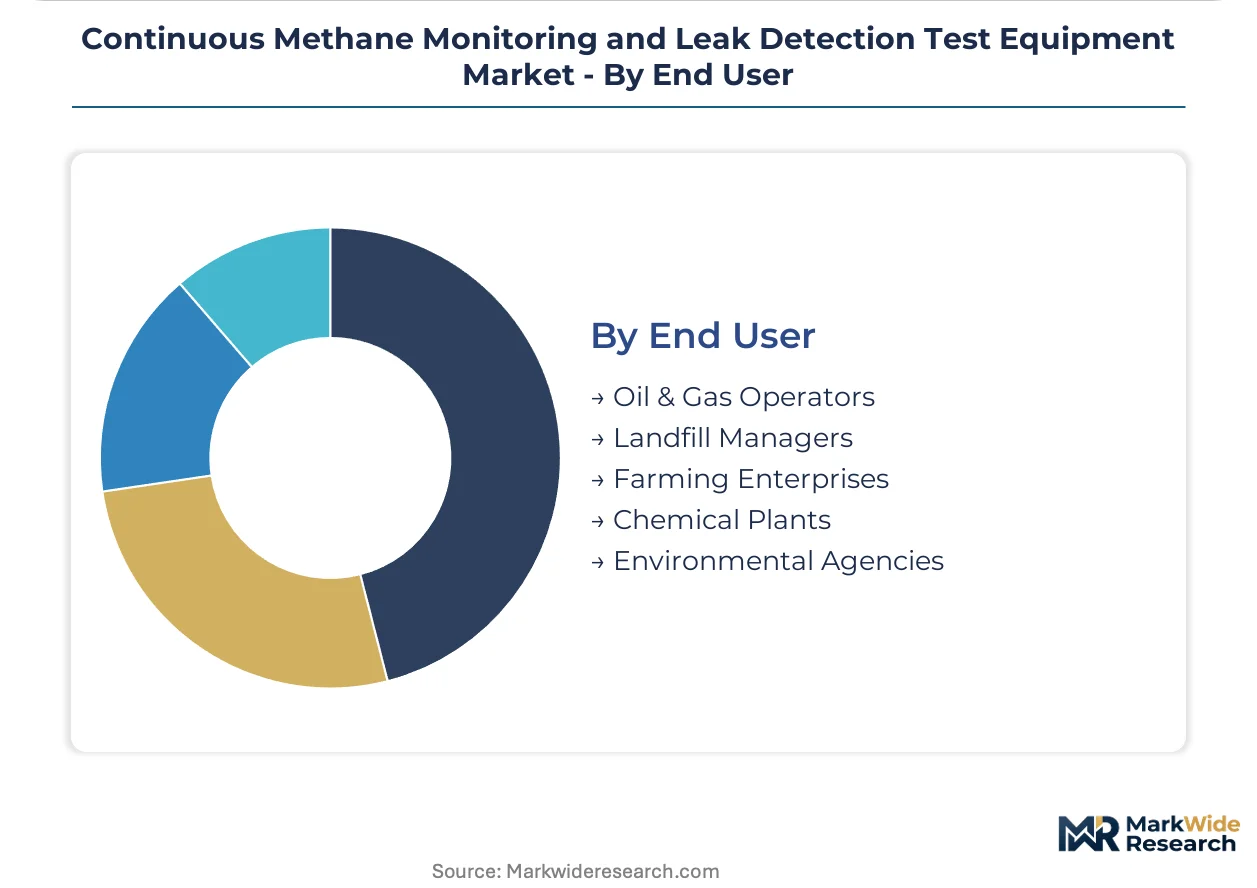
- Oil & Gas Operators:Upstream, midstream, and downstream asset holders face the most stringent methane monitoring mandates under EPA quad-Oa standards. Integrated majors and independent producers in Texas, New Mexico, and Louisiana drive capital allocation toward continuous monitoring equivalence certification.
- Landfill Managers:Municipal and private waste facility operators balance energy recovery optimization with surface emission compliance. Procurement patterns favor portable detectors for OSHA confined-space protocols over perimeter monitoring networks.
- Farming Enterprises:Livestock operations and agricultural cooperatives adopt detection equipment for carbon intensity certification and biogas project development. Equipment specifications prioritize ruggedization for barn and lagoon environments over laboratory precision.
- Chemical Plants:Petrochemical and specialty chemical manufacturers integrate methane detection within broader process safety management systems. Procurement emphasizes SIL-rated instrument reliability for safety instrumented function loops.
- Environmental Agencies:Federal, state, and local enforcement bodies specify reference-grade instrumentation for compliance verification and penalty documentation. EPA regional offices and state environmental agencies sustain replacement demand for field audit capabilities.
Oil and gas operators anchor volume demand today; environmental agencies represent the fastest-growing procurement segment as enforcement staffing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors deployment velocity as operators confront compressed compliance deadlines and investor certification requirements. Regulatory divergence across major hydrocarbon-producing economies is fragmenting equipment specifications and procurement patterns.
United States
EPA quad-Oa standards and Inflation Reduction Act methane fees compel quarterly monitoring equivalence certification at production facilities. The Permian Basin spanning Texas and New Mexico concentrates fastest fixed sensor network deployment. Compressor station operators in West Texas prioritize optical gas imaging integration with automated alarm systems.
Canada
Federal methane regulations under the Pan-Canadian Framework impose facility-level emission intensity caps on upstream oil and gas. Alberta's Energy Regulator enforces venting limits that drive continuous monitoring adoption across oil sands and conventional production. Calgary-based operators pilot satellite-ground hybrid verification systems in the Athabasca region.
Norway
Environmental Agency methane intensity requirements for offshore production platforms exceed EU minimums. Johan Sverdrup and other North Sea developments mandate sub-ppm detection sensitivity at all hydrocarbon handling nodes. Stavanger-clustered engineering firms specify Norwegian-fabricated sensor housings for North Atlantic harsh environment durability.
Saudi Arabia
Saudi Aramco's net-zero 2050 commitment accelerates leak detection deployment across Ghawar and Shaybah super-giant fields. The national oil company's In-Kingdom Total Value Add program prioritizes localized sensor assembly and calibration services. Eastern Province gas processing facilities adopt continuous perimeter monitoring for flare minimization compliance.
Australia
Clean Energy Regulator Safeguard Mechanism reforms impose declining baselines on LNG export facilities. Queensland coal seam gas operators deploy dense sensor arrays across Surat Basin gathering networks to quantify fugitive emissions for carbon credit eligibility. Perth-based engineering contractors integrate methane data into offshore platform safety instrumented systems.
Continuous Methane Monitoring and Leak Detection Test Equipment Market Competitive Landscape
Global majors compete with regional champions across technology platform breadth versus application-specific depth. The vendor base stratifies into three tiers: integrated automation conglomerates bundling detection with control systems, specialized sensor manufacturers advancing solid-state modalities, and software-centric analytics providers unbundling data layers from hardware. Competitive positioning depends on EPA equivalence certification speed, SCADA protocol compatibility breadth, and field service network density in Permian-type basins. M&A activity concentrates on analytics software acquisitions and regional calibration service roll-ups.
Among diversified industrial technology conglomerates, Honeywell International and Emerson exemplify platform-integration archetypes that leverage distributed control system installed bases to embed methane detection within plant-wide automation architectures. Specialized imaging and sensing pure-plays occupy adjacent positions: Teledyne FLIR represents thermal imaging modality leadership, while MSA Safety anchors personal protective equipment integration for confined-space safety protocols. Qube Technologies and Project Canary exemplify the emerging unbundled analytics tier that decouples data interpretation from sensor hardware procurement.
| Leading Market Players |
|---|
| Honeywell International |
| Teledyne FLIR |
| SLB |
| MSA Safety |
| Drägerwerk |
| Emerson |
| Qube Technologies |
| Project Canary |
| Sensirion Connected Solutions |
| Others |
Pricing and Supply Chain Analysis
EPA equivalence certification timelines compressing procurement cycles force buyers toward pre-certified hardware bundles that concentrate supplier power among established vendors with regulatory track records. Semiconductor laser diode foundry concentration in East Asian manufacturing clusters amplifies cost pass-through volatility for optical imaging systems.
Pricing Analysis
Distributed feedback laser diode costs transmit directly into optical imaging system price tiers, with tunable diode laser spectroscopy platforms commanding hardware premiums over electrochemical alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified continuous monitoring equivalence from periodic survey instruments and baseline confined-space detectors. Cost compression in portable detector segments intensifies as MSA Safety and Drägerwerk compete on replacement cycle contracts with oilfield services contractors. Environmental agencies exhibit lowest price sensitivity due to reference-grade precision requirements, while municipal landfill operators prioritize economy-tier procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Permian Basin integrated operators, while distributor networks serve fragmented mid-size exploration companies in secondary basins. Semiconductor laser component manufacturing concentrates in Taiwan, South Korea, and Japan, with quartz tuning fork resonators sourcing primarily from Swiss and German precision fabrication facilities. The supply chain draws from rare earth element processing for photonic detectors and specialty gas mixtures for calibration standard production. Single-source vulnerability in distributed feedback laser diode supply creates exposure to export control fluctuations. Distribution runs through authorized instrumentation distributors with EPA protocol certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA quad-Oa quarterly monitoring mandates and less stringent Canadian provincial enforcement creates cost-advantaged positioning for operators with cross-border asset portfolios.
For Market Incumbents: Hedge against satellite-based monitoring substitution by accelerating machine vision analytics integration that delivers plume localization precision orbital platforms cannot replicate. Backward integration into quartz-enhanced photoacoustic sensor calibration services locks in recurring revenue streams and raises switching costs for Permian Basin pipeline operators facing technician retention challenges. For New Entrants and Emerging Players: Begin with underpenetrated landfill gas perimeter monitoring in secondary US markets where periodic surface emission surveys remain standard practice. Target municipal waste facilities in the Southeast and Midwest with subscription-based continuous monitoring offerings that convert capital expenditure to operational expenditure. Lead with EPA equivalence certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with analytics software providers that decouple data interpretation from sensor hardware procurement. Long-term viability centers on platforms achieving SCADA protocol ubiquity across brownfield compressor station retrofits. Watch for EPA continuous monitoring equivalence determination acceleration as the inflection signal that validates fixed sensor network deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Equivalence Certification Investment | Accelerates fixed sensor substitution for quarterly OGI surveys at Permian production facilities. |
| Machine Vision Analytics Integration | Enables automated plume detection without human operator interpretation at compressor stations. |
| Calibration Service Network Expansion | Addresses field technician scarcity in remote Bakken and Permian field locations. |
| SCADA Protocol Compatibility Development | Reduces integration friction with legacy distributed control system architectures. |
| Landfill Gas Perimeter Monitoring Launch | Captures underpenetrated municipal waste facility demand in secondary US markets. |
Research Methodology
Bottom-up oil and gas operator deployment modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with environmental compliance officers, pipeline integrity managers, SCADA systems integrators, and field calibration technicians combined with secondary validation from EPA enforcement action databases, PHMSA incident reports, and SEC equipment vendor filings. Trade data from USITC harmonized tariff schedules and oil and gas production facility greenhouse gas reporting records provided supply-side triangulation.
Input-output matrices across the analysis window map fixed sensor network density, portable detector replacement cycles, and optical imaging system deployment velocity against regulatory deadline schedules and methane fee exposure thresholds. Segmentation dimensions include product type, detection technology modality, application vertical, and end-user procurement sophistication. CAGRs derive from regression analysis of historical deployment patterns against regulatory stringency indices and capital expenditure survey responses from upstream and midstream operators.
Several conditions sit outside the modeled scope, including potential EPA equivalence determination delays, breakthrough advances in satellite-based quantification accuracy, and trade policy disruptions affecting semiconductor laser component supply. Forecasts reflect assumptions regarding regulatory enforcement staffing levels and natural gas certification program adoption rates. Periodic stress-testing of base assumptions against actual deployment data and enforcement action frequency is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Surface Inspection Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
E-Axle and Inverter Efficiency and Reliability Test Platforms Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market