
 Flash Point Tester Market | 2026-2036
Flash Point Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Point Tester Market Analysis
The capital-intensity divergence between automated and manual flash point testing platforms is bifurcating competitive dynamics across the industry. Anton Paar leverages its precision instrumentation heritage to dominate high-throughput laboratory segments, while Koehler Instrument Company anchors its position through deep vertical integration into ASTM-standard reference materials. Grabner Instruments differentiates via portable field-deployable units that compete directly with benchtop systems in remote refining environments.
A flash point tester measures the lowest temperature at which a liquid generates sufficient vapor to ignite momentarily under standardized conditions, typically employing Pensky-Martens or Abel apparatus with automated ignition detection to achieve repeatability within 0.5°C. The instrument serves primarily to classify flammable liquids for safe transport, storage, and processing across hazardous material supply chains. Closed-cup technology leads product-type revenue due to its regulatory acceptance for precise flash point determination under ASTM D93 and IP 34 protocols, while automated systems are displacing manual units as laboratories face staffing constraints and seek ISO 17025 compliance. The petrochemical application segment sustains the largest installed base, though pharmaceuticals represents the fastest-growing demand pool driven by solvent safety documentation requirements.
OSHA Process Safety Management standards and EPA Risk Management Plan regulations mandate flash point documentation for chemical handling facilities across the United States, directly shaping instrument procurement specifications and calibration frequencies. ASTM International and ISO 2719 provide the harmonized test protocols that determine product eligibility for cross-border chemical trade, creating compliance-driven replacement demand even in mature markets. Stakeholders must monitor evolving UN Globally Harmonized System classification thresholds and regional laboratory accreditation mandates to anticipate the next wave of instrument upgrade cycles.
Market Dynamics
Automated closed-cup flash point testers are displacing manual Pensky-Martens apparatus across petrochemical laboratories as OSHA Process Safety Management audits intensify and ISO 17025 accreditation mandates accelerate instrument replacement cycles in hazardous material handling facilities.
Growth Catalysts
- EPA Risk Management Plan enforcement:Chemical processing facilities in the United States must document flash point data for regulated substances, forcing systematic upgrades to compliant testing infrastructure.
- Petrochemical capacity expansion:New refinery construction in China and India generates immediate demand for high-throughput automated systems capable of continuous batch testing.
- Solvent safety documentation in pharmaceuticals:Drug manufacturers face tightened excipient flammability reporting requirements under ICH Q3C guidelines, expanding laboratory instrument procurement.
Market Restraints
- Platinum-iridium thermocouple dependency:Sensor element supply concentrates with specialized German and Japanese metallurgical suppliers, exposing instrument manufacturers to input cost volatility.
- ASTM D93 calibration complexity:Reference material certification requires accredited third-party verification, extending sales-to-revenue recognition timelines for equipment vendors.
- Portable Raman spectroscopy substitution:Field-deployable optical analyzers now deliver vapor pressure estimates sufficient for preliminary hazard classification in logistics applications.
Strategic Opportunities
- Brazilian biofuel blending mandate expansion:ANVISA and INMETRO alignment on ethanol-gasoline flash point protocols creates replacement demand at sugarcane processing cooperatives and fuel terminals.
- Cloud-connected calibration services:Remote diagnostic platforms enable predictive maintenance contracts, shifting revenue from hardware sales to recurring service streams.
- Electric vehicle battery electrolyte testing:Lithium-ion cell manufacturers require flash point characterization for carbonate solvent mixtures, opening a specialized application segment.
Industry Challenges
- Cross-trained technician scarcity:Laboratories struggle to hire personnel proficient in both classical ASTM methods and automated system programming, delaying ISO 17025 audit readiness.
- Legacy LIMS integration friction:New automated testers must interface with decade-old laboratory information management systems, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Point Tester Market |
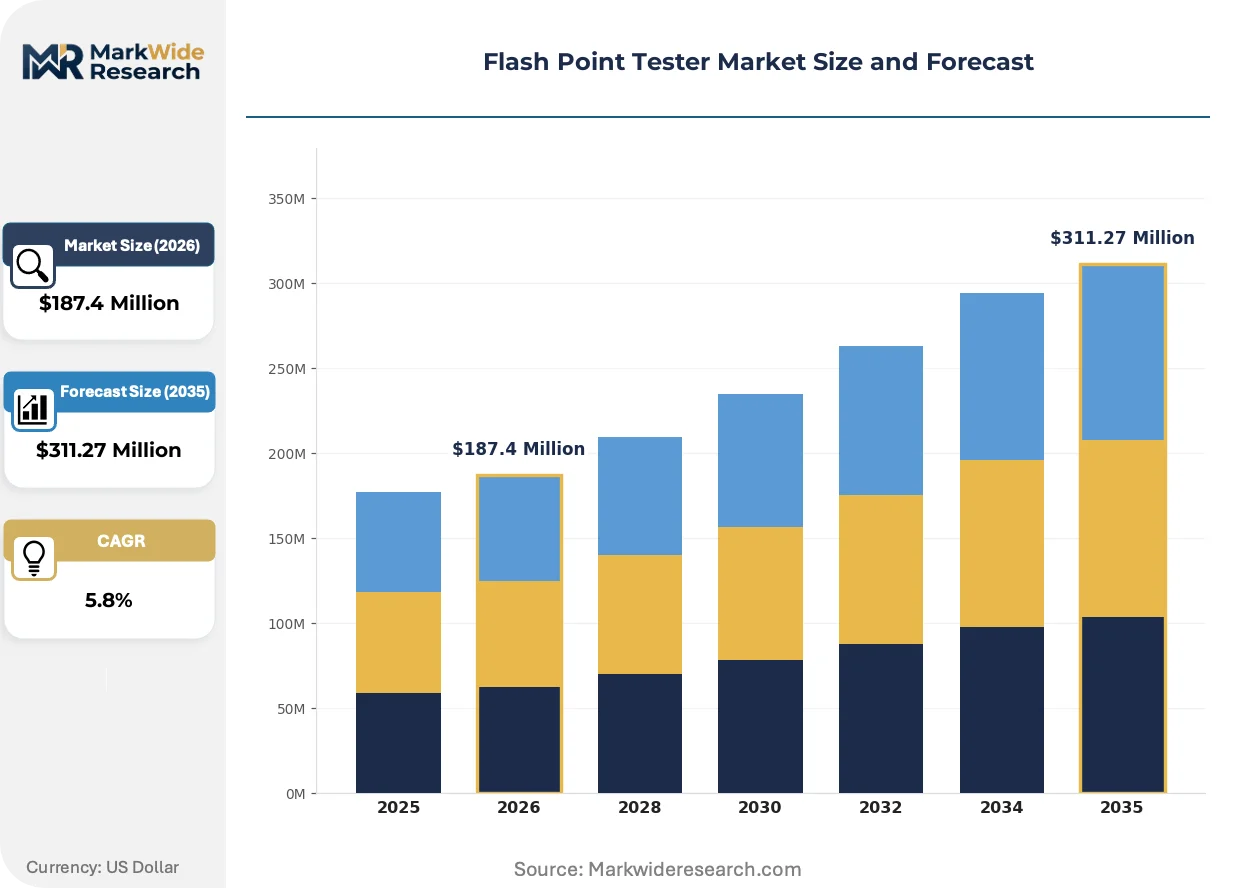
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cup, Closed Cup, Pensky-Martens, Abel Application: Petrochemical, Food Processing, Paints & Coatings, Pharmaceuticals End User: Chemical Manufacturers, Oil Refineries, Research Labs, Automotive Technology: Infrared, Electrical, Manual, Automated |
| Companies Covered | Anton Paar, ERALYTICS, Grabner Instruments, Koehler Instrument Company, Cannon Instrument Company, NORMALAB, Stanhope-Seta, PAC, Labtron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Point Tester Market Emerging Trajectories
Microprocessor-controlled ignition detection and thermal ramp algorithms are compressing test cycle times while improving repeatability margins, fundamentally altering how hazardous material classifications are generated and validated across industrial supply chains.
Automated Pensky-Martens systems equipped with precision thermoelectric cooling are displacing traditional water-bath temperature control in high-volume refinery laboratories. Marathon Petroleum and Valero have standardized on these platforms for crude assay workflows. The shift eliminates operator variability in ignition observation while reducing per-sample labor allocation by half.
REACH Annex XVII restrictions on flammable substance thresholds are compelling European chemical distributors to implement flash point verification at receiving terminals rather than relying on supplier certificates. ECHA guidance on substance identification requires test data traceable to EN ISO 2719. German and Dutch logistics hubs now specify closed-cup testers with integrated barcode scanning for chain-of-custody documentation.
Third-party calibration and certification services are unbundling from original equipment sales as independent metrology laboratories achieve ISO/IEC 17043 proficiency. Procurement teams at ExxonMobil and Shell now separate instrument acquisition from ongoing compliance verification, pressuring manufacturers to defend hardware margins without captive service revenue. This pattern is most pronounced in Texas and Rotterdam refining clusters where centralized maintenance contracts cover multi-vendor instrument fleets.
Flash Point Tester Market Segmentation
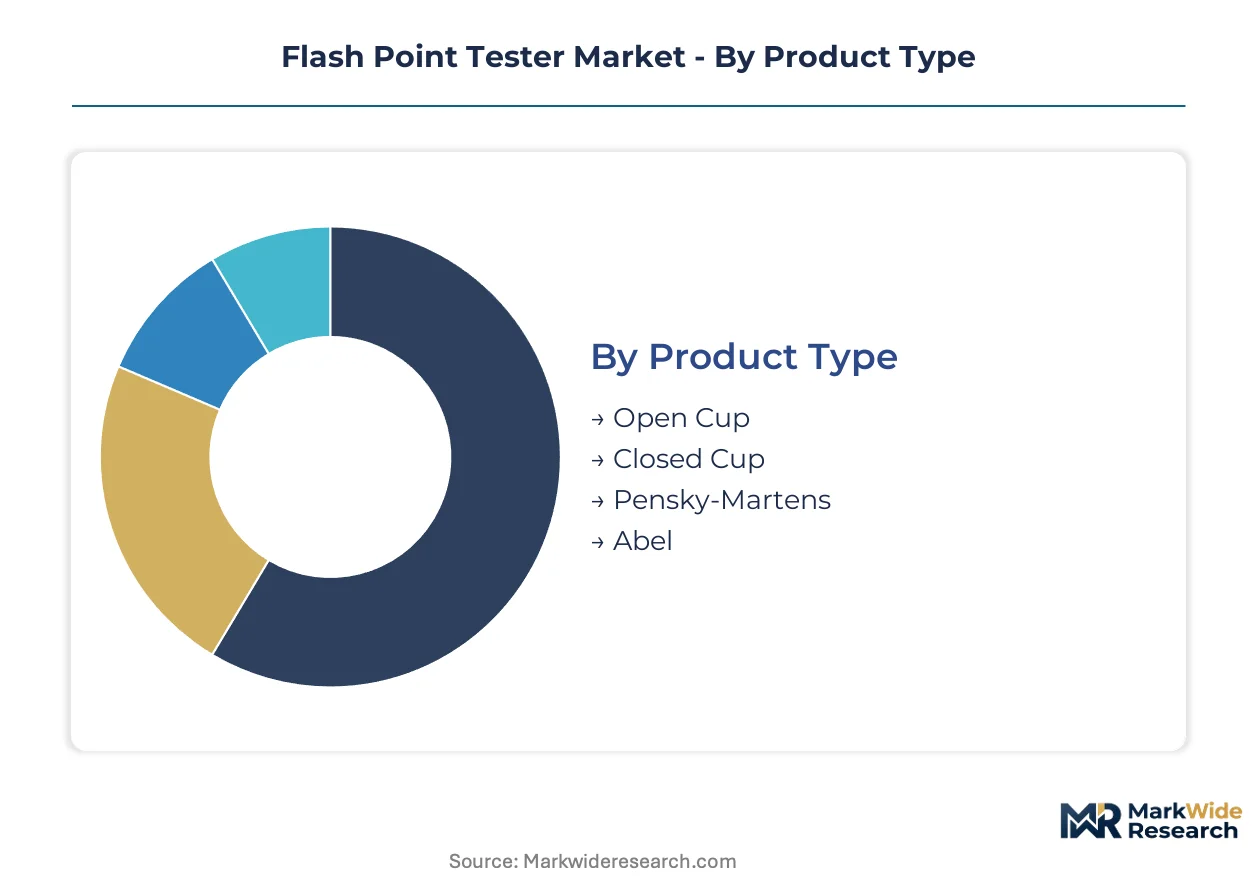
Flash point tester procurement patterns diverge sharply across product configurations and end-use environments. Channel mix varies from direct OEM sales for high-volume refinery deployments to distributor networks serving smaller pharmaceutical laboratories.
Product Type:
Closed-cup systems move primarily through direct manufacturer channels into petrochemical facilities, while portable open-cup units reach field operators via specialized safety equipment distributors.
- Closed Cup:Sealed vessel design prevents vapor loss during heating, delivering precise ignition temperature measurement under ASTM D93 protocols. Demand concentrates in United States Gulf Coast refineries where OSHA Process Safety Management audits mandate documented flash point verification for process streams. EPA Risk Management Plan enforcement accelerates replacement of aging manual apparatus.
- Automated Pensky-Martens:Microprocessor-controlled thermal ramp and ignition detection compress test cycles while eliminating operator observation variability. German chemical manufacturers and Rotterdam terminal operators specify these platforms for high-throughput solvent classification workflows. ISO 17025 accreditation requirements drive displacement of water-bath controlled manual systems.
- Open Cup:Exposed liquid surface design suits rapid field screening of crude oil and fuel shipments. Brazilian biofuel terminals and Indian refinery laboratories deploy these for preliminary hazard classification.
- Abel:Low-temperature closed-cup apparatus optimized for volatile solvents and aviation fuels. Aviation fuel testing laboratories in France and the United Kingdom maintain installed bases for Jet A-1 certification.
Closed Cup dominates installed base. Automated Pensky-Martens is where expansion concentrates.
Application:
Cost tier segmentation separates high-capital refinery installations from mid-range pharmaceutical laboratory deployments and economy-tier food processing quality control stations.
- Petrochemical:Crude assay laboratories and process control facilities require continuous batch testing capability with automated sample handling. Marathon Petroleum and Valero operations in Texas and California standardize on thermoelectric-cooled platforms. Tightened safety documentation under EPA Risk Management Plan forces systematic infrastructure upgrades.
- Pharmaceuticals:Solvent safety characterization for drug formulation and excipient qualification demands ISO 17025 traceability. ICH Q3C guideline compliance expands instrument procurement at Merck KGaA and Roche facilities in Germany and Switzerland.
- Paints & Coatings:VOC regulatory thresholds under EPA 40 CFR 59 and ECHA REACH restrictions require flash point verification for coating formulations. Sherwin-Williams and AkzoNobel quality laboratories drive replacement demand.
- Food Processing:Edible oil and flavoring solvent testing for transport classification employs economy-tier manual or semi-automated systems. Brazilian soybean oil exporters and Malaysian palm oil processors represent concentrated demand pockets.
Petrochemical commands the largest revenue pool. Pharmaceuticals is climbing the fastest.
End User:
Customer type determines procurement authority structure — centralized capital committees at integrated oil companies versus decentralized laboratory managers at contract research organizations.
- Oil Refineries:Integrated operators like ExxonMobil and Shell deploy enterprise-wide instrument standardization programs. Texas and Rotterdam refining clusters separate hardware acquisition from third-party calibration services, pressuring OEMs to defend equipment margins without captive service revenue.
- Chemical Manufacturers:BASF and Dow facilities require flash point documentation for REACH registration and OSHA hazard communication. Multi-site corporations negotiate framework agreements covering automated system fleets.
- Research Labs:University and government research institutions prioritize ASTM-standard reference materials and ISO/IEC 17043 proficiency testing. Funding constraints sustain demand for refurbished manual apparatus.
- Automotive:Battery electrolyte testing for lithium-ion cell manufacturing creates specialized demand at CATL and LG Energy Solution facilities. Carbonate solvent mixture characterization requires modified closed-cup protocols.
Oil Refineries anchor volume demand. Automotive is gaining share fastest.
Technology:
Supply concentration in sensor metallurgy and software architecture creates divergent margin profiles across technology tiers.
- Automated:Precision thermocouple arrays and algorithmic ignition detection enable unattended operation with 0.5°C repeatability. German and Japanese platinum-iridium sensor suppliers concentrate input cost exposure for instrument manufacturers.
- Manual:Operator-dependent observation of flame application persists in budget-constrained environments and regulatory jurisdictions with less stringent accreditation mandates.
- Infrared:Non-contact temperature monitoring reduces thermocouple drift errors in high-throughput environments. Adoption concentrates in European laboratories seeking EN ISO 2719 compliance with reduced calibration frequency.
- Electrical:Spark ignition sources replace gas flame applicators in safety-critical hydrogen-rich sample testing. Specialized petrochemical research applications sustain niche demand.
Automated systems dominate new capital deployment. Infrared is where technology substitution concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany demonstrate low price elasticity due to regulatory compliance mandates, while Indian and Brazilian procurement teams prioritize capital efficiency over precision specifications.
United States
OSHA Process Safety Management audits and EPA Risk Management Plan enforcement compel Gulf Coast refineries to replace manual Pensky-Martens apparatus with automated closed-cup systems. Texas refining clusters in Houston and Beaumont separate instrument acquisition from third-party calibration contracts, pressuring OEMs to defend hardware margins without captive service revenue.
Germany
Chemical manufacturers at BASF and Dow facilities require flash point documentation for REACH registration and hazard communication compliance. The Rhine-Ruhr industrial corridor and Bavarian chemical parks standardize on ISO 17025-accredited platforms, with ECHA guidance on substance identification driving test data traceability requirements.
China
Petrochemical capacity expansion in Zhejiang and Shandong provinces generates immediate demand for high-throughput automated systems capable of continuous batch testing. GB standards alignment with ASTM D93 protocols accelerates instrument replacement cycles at Sinopec and PetroChina crude assay laboratories.
India
Reliance Industries and Indian Oil Corporation expand refinery laboratory infrastructure to meet BIS certification requirements for petroleum product classification. The Gujarat refining hub and Maharashtra chemical belt prioritize economy-tier manual systems for preliminary hazard screening, deferring automated platform investments.
Brazil
ANVISA and INMETRO alignment on ethanol-gasoline flash point protocols creates replacement demand at sugarcane processing cooperatives and fuel terminals. São Paulo state biofuel distributors implement closed-cup verification at receiving terminals rather than relying on supplier certificates, expanding instrument procurement.
Flash Point Tester Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the flash point tester market. Precision instrumentation heritage distinguishes laboratory-focused suppliers, while vertical integration into ASTM-standard reference materials anchors mid-market positions. The competitive structure fragments across three strategic archetypes: automated system specialists, portable field-deployable fabricators, and calibration service integrators. Dominant competitive moves include cloud-connected diagnostic platforms shifting revenue toward recurring service streams, and third-party metrology laboratories achieving ISO/IEC 17043 proficiency to unbundle calibration from original equipment sales.
Among Austrian and German precision instrumentation specialists, Anton Paar GmbH and ERALYTICS GmbH exemplify technology leadership archetypes with heritage in laboratory automation. Koehler Instrument Company anchors the reference materials-integrated tier through its United States-based vertical structure. Grabner Instruments occupies a distinct position within portable field-deployable specialists, competing directly with benchtop configurations in remote refining environments where logistics constraints favor mobile units.
| Leading Market Players |
|---|
| Anton Paar |
| ERALYTICS |
| Grabner Instruments |
| Koehler Instrument Company |
| Cannon Instrument Company |
| NORMALAB |
| Stanhope-Seta |
| PAC |
| Labtron |
| Others |
Supply Flow & Price Mechanics
Long-term calibration service contracts lock in both platinum-iridium thermocouple supply access and predictable aftermarket revenue streams for flash point tester OEMs serving OSHA-audited Gulf Coast refineries and ISO 17025-accredited European laboratories.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions generate lifetime value multiples exceeding original equipment margins. Pricing stratifies across ISO 17025-certified automated systems, ASTM-standard manual apparatus, and economy-tier portable units, with certification grade commanding substantial premiums. Cost compression in the portable segment intensifies as Raman spectroscopy substitutes erode field-testing pricing power. Pharmaceutical laboratories demonstrate lowest price sensitivity due to ICH Q3C compliance mandates, while Indian and Brazilian fuel terminals prioritize capital efficiency.
Supply Chain Analysis
Germany and Japan anchor platinum-iridium thermocouple metallurgy and precision sensor fabrication for automated ignition detection systems. Chinese manufacturers dominate thermoelectric cooling module assembly and microprocessor controller production. Supply chain vulnerability concentrates in single-source German sensor suppliers exposed to commodity price volatility. Distribution runs through direct OEM channels for refinery deployments and specialized safety equipment distributors serving smaller laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable Raman spectroscopy and optical vapor analyzers threaten benchtop flash point tester incumbents in logistics and preliminary hazard classification applications, forcing defensive positioning around regulatory compliance depth and calibration service lock-in.
For Market Incumbents: Shield installed base revenue by embedding cloud-connected diagnostic platforms that shift customer relationships toward recurring calibration subscriptions resistant to substitution. Deepen backward integration into ASTM-standard reference materials to capture third-party metrology laboratory revenue streams. Prioritize ISO 17025 accreditation support services that cement laboratory dependency beyond hardware replacement cycles. For New Entrants and Emerging Players: ISO 17025 fast-track certification programs for refurbished automated systems unlock penetrable demand at budget-constrained university and government research institutions. Target Brazilian biofuel terminals and Indian refinery laboratories where ANVISA and BIS compliance deadlines accelerate instrument procurement ahead of domestic supplier maturation. Lead with field-deployable service capabilities that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Calibration service integrators with ISO/IEC 17043 proficiency and multi-vendor maintenance contracts present asymmetric exposure to hardware margin compression trends. Long-term viability rests on recurring revenue durability rather than equipment replacement cyclicality. Monitor ECHA guidance evolution and OSHA audit intensity as inflection signals for compliance-driven upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Platform | Shifts revenue from hardware sales to recurring predictive maintenance contracts at ExxonMobil and Shell facilities. |
| Backward Integration into Reference Materials | Captures third-party metrology revenue streams unbundling from original equipment manufacturers in Texas and Rotterdam. |
| ISO 17025 Accreditation Fast-Track | Accelerates laboratory procurement decisions at Merck KGaA and Roche facilities facing ICH Q3C compliance deadlines. |
| Portable Field-Deployable Unit Launch | Competes directly with benchtop systems in Brazilian sugarcane cooperatives and Indian refinery remote locations. |
| Electric Vehicle Electrolyte Testing Protocol | Opens specialized application segment at CATL and LG Energy Solution lithium-ion cell manufacturing facilities. |
Methodological Framework
The analysis maps closed-cup automated systems, portable open-cup units, Abel apparatus, and manual Pensky-Martens configurations, each validated through laboratory managers at Sinopec and PetroChina, calibration service directors at Rotterdam terminals, and procurement leads at Marathon Petroleum and Valero. Secondary validation draws from ASTM International protocol documentation, EPA Risk Management Plan enforcement records, ECHA REACH guidance publications, and customs trade data for instrument import flows. Bottom-up instrument shipment tallies triangulate against top-down petrochemical capacity expansion estimates.
Consistency checks validate volume and value outputs against external benchmarks including refinery laboratory capital expenditure disclosures and pharmaceutical quality control equipment procurement patterns. The analytical framework models product type, application segment, end-user category, and technology tier dimensions across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles and regulatory compliance deadline clustering. Industry-specific forecast inputs include OSHA audit scheduling intensity and ECHA substance identification guidance evolution.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and OSHA enforcement posture; material deviation in regulatory stringency would warrant model refresh. Recalibration cycles align with material shifts in UN Globally Harmonized System classification threshold revisions and regional laboratory accreditation mandate updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Testing Services Market
Test and Measurement
LCR Meter Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
RFID Tester Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market