
 NIR Moisture Analyzers Sales Market | 2026-2036
NIR Moisture Analyzers Sales Market Size, Share, and Industry Trends Forecast 2026-2036
NIR Moisture Analyzers Sales Market Insights
Silicon photodiode arrays is shifting the cost-performance curve for NIR moisture analyzers, enabling faster spectral acquisition at lower hardware expense. Mettler-Toledo International leverages its Swiss manufacturing base to sustain premium positioning in pharmaceutical-grade systems. Kett Electric Laboratory anchors the agricultural testing segment with specialized portable units for grain elevators. BÜCHI Labortechnik differentiates through modular optical configurations that extend instrument versatility across laboratory and production environments.
NIR moisture analyzers employ near-infrared spectroscopy, typically operating between 780 and 2500 nanometers, to detect water molecule absorption bands without sample destruction; the technique measures O-H bond vibrational overtones to quantify moisture content in solids, slurries, and films within seconds. Inline analyzers dominate capital deployment in chemical manufacturing where continuous process monitoring eliminates batch testing delays. Portable analyzers lead growth in agriculture as elevator operators and grain traders demand field-deployable verification tools. Desktop units retain stable margins in pharmaceutical quality control laboratories where method validation and documentation requirements favor fixed installations.
FDA enforcement of 21 CFR Part 11 electronic records standards shapes analyzer software architecture and data integrity features for US pharmaceutical buyers. EU MDR and REACH compliance requirements in Europe drive demand for analyzers with validated cleaning protocols and material safety documentation. Stakeholders must weigh fiber optic probe durability against handheld unit flexibility when specifying equipment for multi-site deployment models.
Market Dynamics
Silicon photodiode arrays are compressing hardware costs while accelerating spectral acquisition speeds, forcing incumbent vendors to defend premium positioning through software differentiation and validated method libraries.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in pharmaceutical quality control drive replacement cycles for legacy benchtop units lacking audit trail capabilities.
- German precision engineering clusters:Pharmaceutical and chemical manufacturing concentration around Ludwigshafen and Leverkusen sustains demand for pharmaceutical-grade inline systems.
- Silicon photodiode arrays:Solid-state detector technology eliminates moving parts in scanning monochromators, reducing maintenance intervals and enabling ruggedized portable designs.
Market Restraints
- Indium gallium arsenide detector costs:InGaAs array prices remain elevated for high-resolution agricultural analyzers, constraining margin expansion in portable segments.
- Optical fiber supply concentration:Specialized NIR-grade fiber production clusters in Japan and Germany create vulnerability to export control disruptions.
- Method transfer complexity:Laboratory-validated calibrations require extensive redevelopment for inline installations, extending sales cycles.
Strategic Opportunities
- India FSSAI modernization:Food safety infrastructure investments create openings for affordable portable analyzers at grain procurement centers and spice processing hubs.
- Battery electrode manufacturing:Lithium-ion cathode and anode production lines require moisture control below 50 ppm, opening specialty inline analyzer demand.
- EU Green Deal carbon accounting:Process analytical technology deployments qualify for sustainability-linked financing, reducing customer capex barriers.
Industry Challenges
- Chemometric expertise scarcity:Multivariate calibration development requires specialized spectroscopy and statistics knowledge that outpaces university training pipelines.
- Legacy DCS integration:Inline analyzers must interface with decades-old distributed control systems through proprietary communication protocols, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NIR Moisture Analyzers Sales Market |
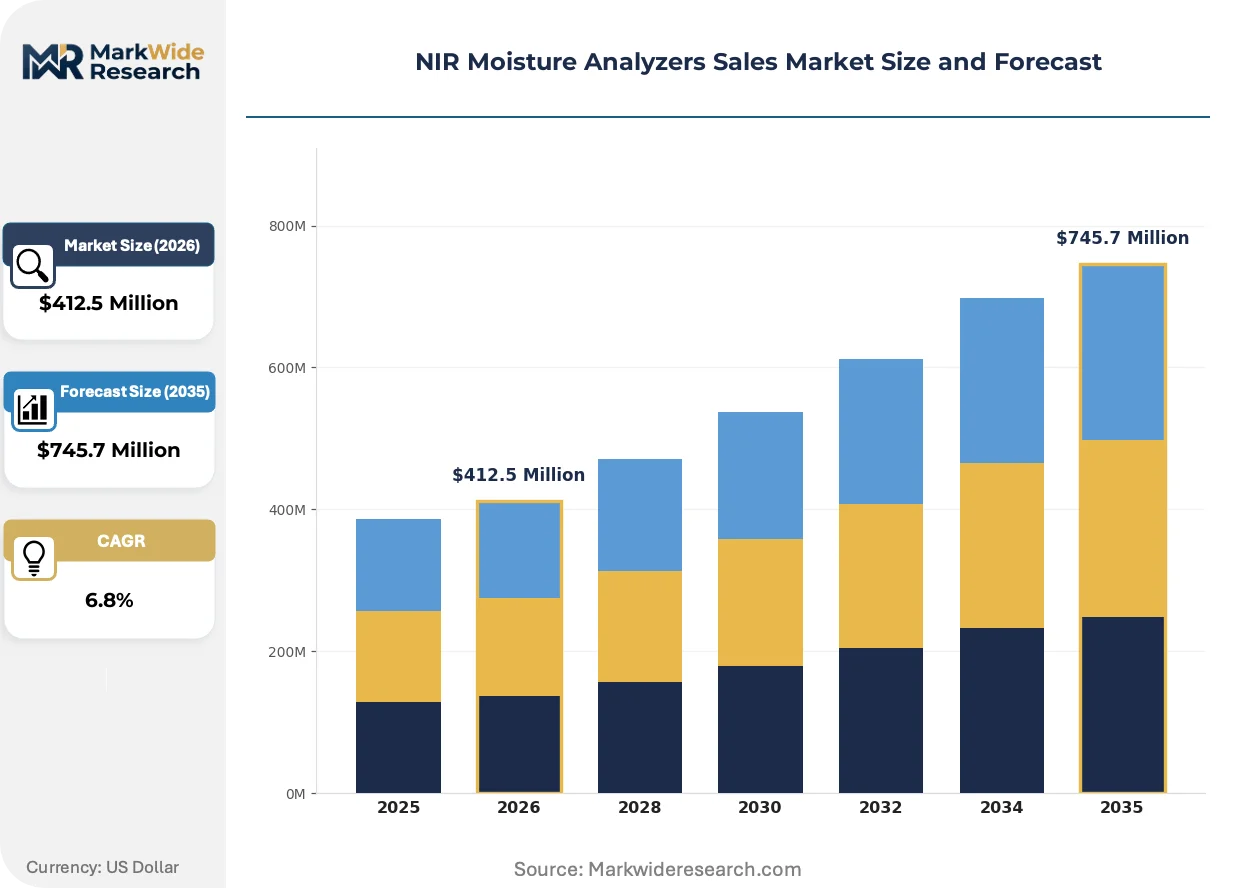
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
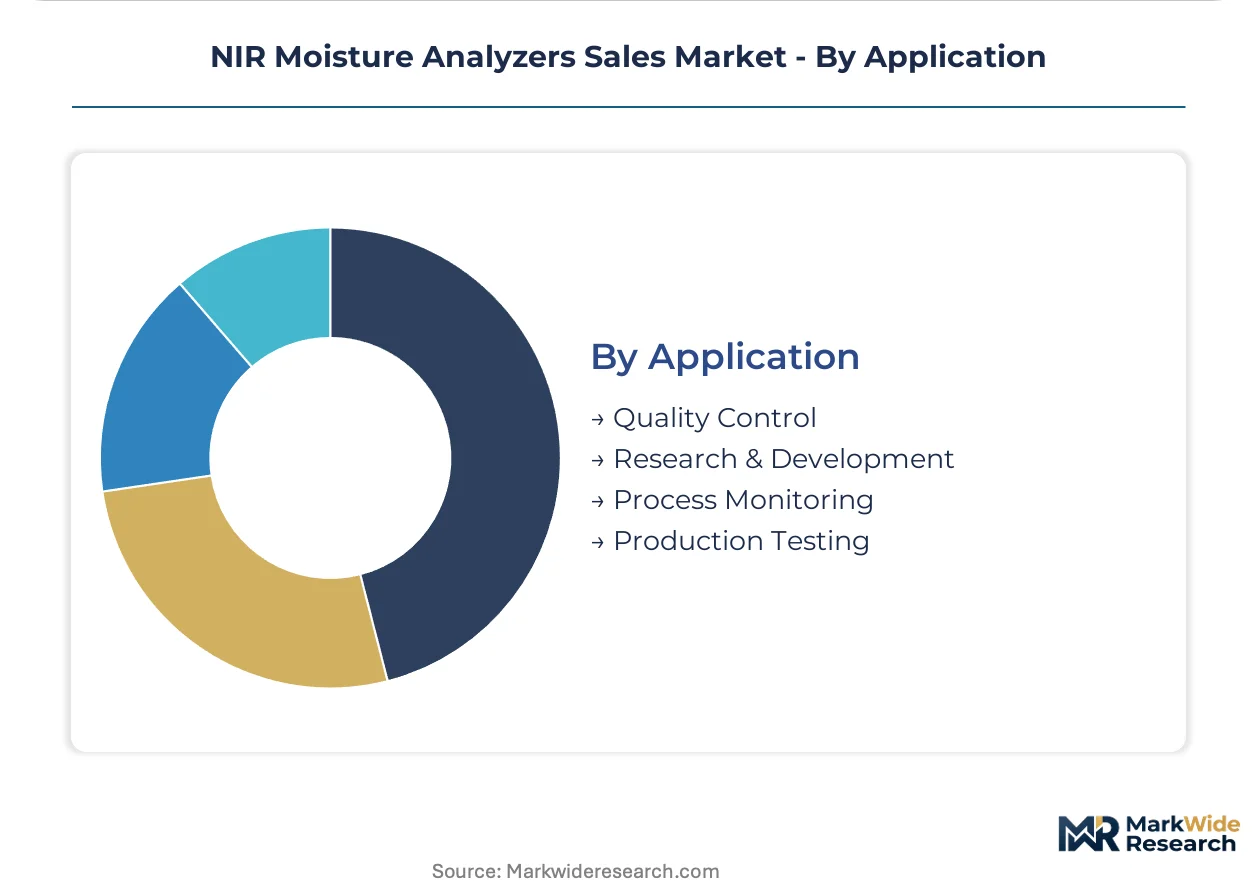
| Segmentation | Product Type: Desktop Analyzers, Portable Analyzers, Inline Analyzers, benchtop Analyzers End User: Agriculture, Food Processing, Pharmaceuticals, Chemical Manufacturing Technology: Fiber Optic, Handheld, Nondestructive, Automated Systems Application: Quality Control, Research & Development, Process Monitoring, Production Testing |
| Companies Covered | FINNA SENSORS, Kett Electric Laboratory, Mettler-Toledo International, Process Sensors Corporation, Sensortech Systems, AMETEK, MoistTech Corp., BÜCHI Labortechnik, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NIR Moisture Analyzers Sales Market Trends and Innovations
Real-time process control architectures are displacing batch sampling workflows across chemical and food manufacturing, with analyzer vendors repositioning as data platform providers rather than hardware suppliers.
MEMS-based Fabry-Perot tunable filters are converging with compact InGaAs detector packages to enable palm-sized NIR spectrometers. Agricultural cooperatives and grain elevator operators are piloting these devices for at-receipt moisture verification. The convergence is compressing the price-performance gap between laboratory-grade and field-deployable units.
EU MDR Annex I general safety and performance requirements now mandate process validation documentation for pharmaceutical manufacturing equipment. Analyzer vendors must supply IQ/OQ/PQ protocol packages and material compliance certificates. German and Swiss pharmaceutical exporters are demanding these documentation bundles upfront, filtering out smaller equipment suppliers lacking regulatory affairs capacity.
Service contract unbundling is fragmenting traditional analyzer procurement. Chemical manufacturers now separate hardware acquisition from chemometric support and annual calibration services. This pattern is most pronounced in US Gulf Coast petrochemical complexes, where specialized third-party laboratories compete with original equipment manufacturers for method development and model maintenance contracts.
NIR Moisture Analyzers Sales Market Segmentation
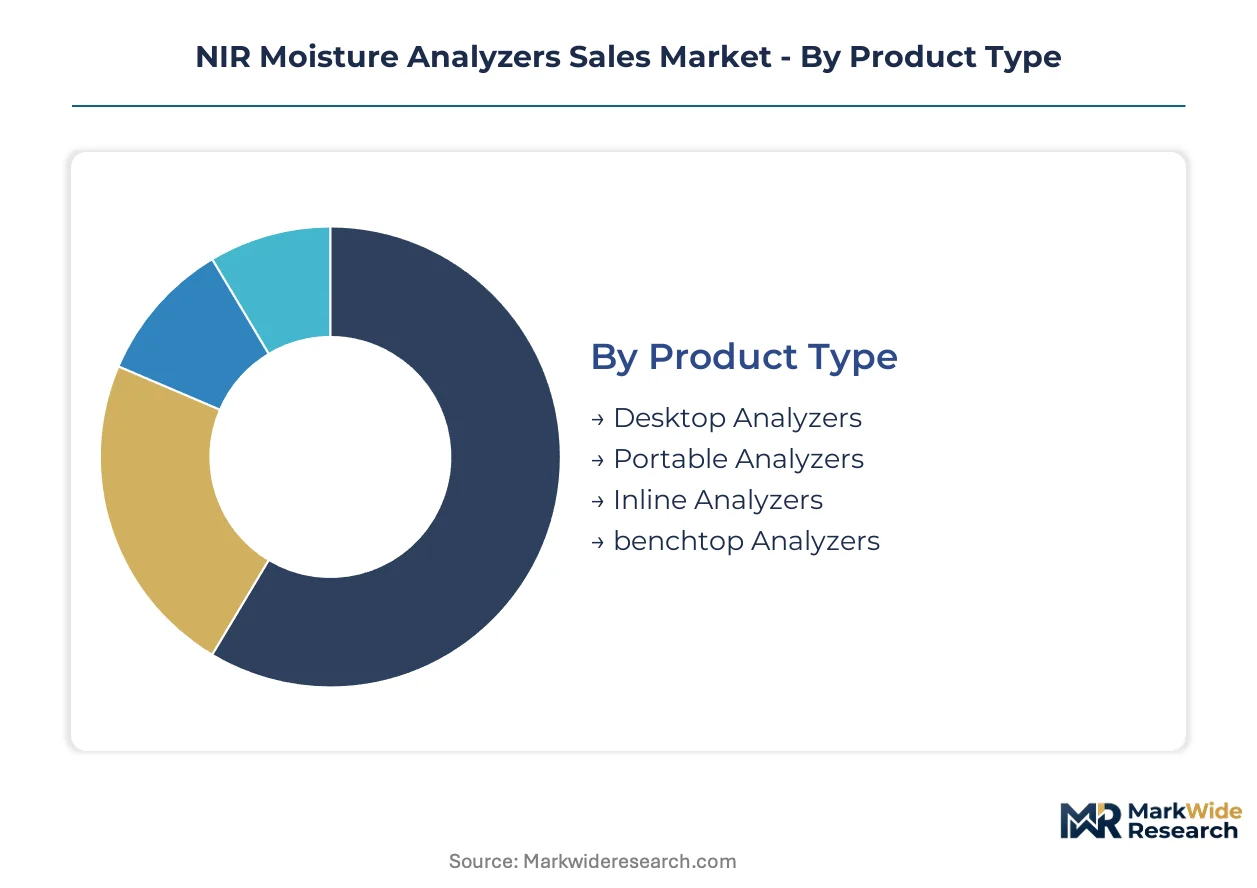
Analyzer procurement cycles diverge sharply across deployment contexts. Pharmaceutical laboratories prioritize validation documentation and fixed installations, while agricultural operators demand field portability and rapid calibration transfer.
Product Type:
Upgrade trajectories from legacy benchtop units to real-time monitoring systems are compressing replacement windows in regulated industries.
- Desktop Analyzers:Fixed-installation systems with enclosed sample chambers and integrated computing modules dominate pharmaceutical quality control laboratories. FDA 21 CFR Part 11 compliance requirements in US drug manufacturing sustain replacement demand for units lacking audit trail capabilities.
- Inline Analyzers:Process-integrated spectrometers with fiber optic probes enable continuous moisture monitoring without sampling delays. Chemical manufacturing clusters around Ludwigshafen and Leverkusen in Germany drive premium procurement for pharmaceutical-grade inline systems with validated cleaning protocols.
- Portable Analyzers:Battery-powered handheld units with silicon photodiode arrays serve grain elevators and field agricultural testing.
- Benchtop Analyzers:Entry-level laboratory units with basic scanning monochromators retain stable demand in educational and small-scale food processing settings.
Volume placements concentrate in Inline Analyzers; the faster expansion belongs to Portable Analyzers.
End User:
Regulatory enforcement intensity shapes capital allocation priorities across customer categories.
- Pharmaceuticals:GMP-validated systems with IQ/OQ/PQ documentation packages and material compliance certificates command premium positioning. Swiss and German pharmaceutical exporters demand these documentation bundles upfront, filtering out smaller equipment suppliers.
- Food Processing:Inline deployments for Hazard Analysis and Critical Control Points modernization are displacing legacy batch sampling in US and EU facilities. The FDA's enforcement of electronic records standards compels manufacturers to upgrade from benchtop units to real-time monitoring architectures.
- Agriculture:Grain elevator operators and cooperatives pilot MEMS-based palm-sized spectrometers for at-receipt moisture verification.
- Chemical Manufacturing:Continuous process monitoring eliminates batch testing delays in petrochemical and specialty chemical production.
Revenue concentration sits with Pharmaceuticals; Agriculture is climbing the fastest.
Technology:
Detector platform selection determines maintenance intervals, spectral resolution, and deployment flexibility.
- Fiber Optic:Probe-based light delivery systems enable remote sampling in hazardous or confined process environments. Specialized NIR-grade fiber production concentration in Japan and Germany creates supply vulnerability that procurement officers must weigh against measurement precision requirements.
- Nondestructive:Reflectance and transmittance measurement modes preserve sample integrity for pharmaceutical release testing and high-value agricultural commodities. O-H bond vibrational overtone detection between 780 and 2500 nanometers quantifies moisture without sample destruction.
- Handheld:Compact form factors with simplified interfaces serve field operators lacking specialized spectroscopy training.
- Automated Systems:Robotic sample handling and self-diagnostic calibration routines reduce chemometric expertise requirements in high-throughput laboratories.
Installed base dominance belongs to Fiber Optic; Nondestructive platforms are gaining share fastest.
Application:
Workflow integration depth determines software architecture requirements and service contract structures.
- Process Monitoring:Real-time data streams into distributed control systems enable closed-loop moisture control in continuous manufacturing. Legacy DCS integration challenges through proprietary communication protocols complicate deployment in decades-old chemical facilities.
- Quality Control:Validated analytical methods with documented uncertainty budgets support regulatory submission requirements in pharmaceutical and food safety contexts. EU MDR Annex I general safety and performance requirements now mandate process validation documentation for manufacturing equipment.
- Research & Development:Method development and calibration transfer activities require modular optical configurations that extend instrument versatility across experimental conditions.
- Production Testing:High-throughput screening at receiving docks and finished goods release points demands ruggedized designs with minimal warm-up periods.
Capital deployment concentrates in Process Monitoring; Quality Control shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision engineering clusters in Germany and pharmaceutical export corridors in Switzerland concentrate premium analyzer procurement. Food safety modernization across India and battery manufacturing expansion in China are redistributing demand toward mid-tier portable systems.
United States
FDA enforcement of 21 CFR Part 11 electronic records standards drives replacement cycles for legacy benchtop units in pharmaceutical quality control laboratories. The Hazard Analysis and Critical Control Points modernization compels food processors to upgrade from batch sampling to real-time monitoring architectures. Gulf Coast petrochemical complexes around Houston and Baton Rouge sustain demand for inline process analyzers with third-party service contract unbundling.
Germany
Pharmaceutical and chemical manufacturing concentration around Ludwigshafen and Leverkusen sustains premium procurement for validated inline systems. EU MDR Annex I general safety and performance requirements mandate process validation documentation that filters out smaller equipment suppliers. Precision engineering clusters in Baden-Württemberg and North Rhine-Westphalia anchor demand for pharmaceutical-grade analyzers with IQ/OQ/PQ protocol packages.
India
FSSAI modernization of food safety infrastructure creates openings for affordable portable analyzers at grain procurement centers and spice processing hubs. Agricultural cooperatives pilot MEMS-based palm-sized spectrometers for at-receipt moisture verification in Maharashtra and Gujarat. The PLI scheme for food processing equipment accelerates capital deployment in Uttar Pradesh and Madhya Pradesh grain belts.
China
Lithium-ion cathode and anode production lines require moisture control below 50 ppm, opening specialty inline analyzer demand in Fujian and Jiangsu battery manufacturing zones. Dual carbon goals under the 14th Five-Year Plan qualify process analytical technology deployments for sustainability-linked financing. Yangtze River Delta chemical clusters around Shanghai and Ningbo prioritize continuous process monitoring to eliminate batch testing delays.
Switzerland
Swissmedic pharmaceutical export requirements sustain demand for GMP-validated systems with material compliance certificates. Swiss manufacturing bases defend premium positioning through software differentiation and validated method libraries. Basel and Zurich pharmaceutical corridors demand documentation bundles upfront, compressing replacement windows for legacy installations.
NIR Moisture Analyzers Sales Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent vendors defend premium positioning through software differentiation and validated method libraries. The vendor base organizes around three strategic archetypes: precision engineering specialists with Swiss and German manufacturing heritage, agricultural testing specialists with portable unit expertise, and modular optical platform providers serving laboratory-to-production workflows. Technology licensing agreements and chemometric service unbundling represent the two dominant competitive moves reshaping procurement patterns.
Within the precision engineering tier, Mettler-Toledo International and BÜCHI Labortechnik exemplify Swiss-based manufacturers sustaining premium positioning through pharmaceutical-grade system validation. Kett Electric Laboratory occupies a distinct position among specialists in agricultural testing equipment. These three entities anchor the competitive structure without exhaustive market coverage, as the analysis identifies FINNA SENSORS, Process Sensors Corporation, Sensortech Systems, AMETEK, MoistTech Corp., and Sartorius as additional market participants.
| Leading Market Players |
|---|
| FINNA SENSORS |
| Kett Electric Laboratory |
| Mettler-Toledo International |
| Process Sensors Corporation |
| Sensortech Systems |
| AMETEK |
| MoistTech Corp. |
| BÜCHI Labortechnik |
| Sartorius |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-accounting requirements now gate qualified supply access for NIR moisture analyzers, with sustainability-linked financing eligibility restricting premium-tier procurement to vendors demonstrating validated manufacturing footprints and material compliance documentation. This environmental mandate compresses pricing power for smaller equipment suppliers lacking regulatory affairs capacity while concentrating margin capture among Swiss and German precision engineering clusters with established IQ/OQ/PQ protocol capabilities.
Pricing Analysis
Volume placements concentrate in mid-tier inline analyzers where silicon photodiode array cost compression intensifies competitive pressure, while premium margins persist in pharmaceutical-grade systems validated for FDA 21 CFR Part 11 compliance. Price differentiation hinges on certification tier and after-sales service bundling, with GMP-validated documentation packages commanding substantial premiums over standard laboratory configurations. Pricing pressure stems from agricultural cooperatives piloting MEMS-based palm-sized spectrometers at grain elevators, eroding entry-level benchtop demand. Food processing buyers exhibit highest price sensitivity due to FSSAI modernization budgets, whereas Swiss pharmaceutical exporters demonstrate lowest sensitivity given Swissmedic export documentation requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for food processing equipment and China's dual carbon goals are reshaping sourcing patterns for analyzer manufacturers seeking qualified supplier status in these growth markets. Component supply concentrates in Japan and Germany for specialized NIR-grade optical fibers, with silicon photodiode arrays drawing from Taiwanese semiconductor foundries and InGaAs detectors resting on Japanese detector manufacturing. Single-source vulnerability in NIR-grade fiber production creates exposure to export control disruptions. Distribution runs through authorized distributor networks in regulated pharmaceutical markets, while agricultural segments favor direct procurement from specialized testing equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with EU MDR Annex I documentation requirements forcing weaker players lacking validated method libraries and IQ/OQ/PQ protocol capacity toward exit or acquisition.
For Market Incumbents: Acquire chemometric service capabilities to defend against unbundling trends in US Gulf Coast petrochemical complexes, where third-party laboratories now compete for method development contracts. Deepen backward integration into silicon photodiode array sourcing to capture cost compression benefits currently flowing to component suppliers. Fortify pharmaceutical-grade positioning through software differentiation and validated method libraries that emerging MEMS-based entrants cannot replicate. For New Entrants and Emerging Players: MEMS-based Fabry-Perot tunable filter convergence with compact InGaAs packages offers a technology-first wedge into agricultural moisture verification at Indian grain procurement centers and spice processing hubs. Target FSSAI modernization investments in Maharashtra and Gujarat for initial footprint, leveraging simplified interfaces that field operators lacking spectroscopy training can deploy. Pursue white-label partnerships with established distributors rather than direct channel builds. For Investors and Strategic Acquirers: Service contract unbundling announcements from major chemical manufacturers are the leading indicator that aftermarket revenue streams are separating from hardware valuations, compressing traditional equipment supplier multiples. Frame long-term viability around platform providers with recurring chemometric revenue rather than pure hardware vendors. Target acquisition profiles centered on modular optical platform specialists with laboratory-to-production workflow coverage. Watch for FDA enforcement actions on legacy benchtop audit trail deficiencies as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Bundling | IQ/OQ/PQ protocol packages filter out smaller competitors in German pharmaceutical corridors. |
| Chemometric Service Unbundling | Third-party laboratories capture method development contracts from original equipment manufacturers in US petrochemical markets. |
| MEMS Filter Integration | Palm-sized spectrometer convergence compresses price-performance gap for agricultural field deployment. |
| Backward Integration into Detectors | In-house silicon photodiode array sourcing captures cost compression and accelerates spectral acquisition speeds. |
| Sustainability-Linked Financing Access | EU Green Deal qualification reduces customer capex barriers for process analytical technology deployments. |
Research Methodology
Independent corroboration across plant engineers at chemical manufacturing facilities, procurement leads at pharmaceutical quality control laboratories, and aftermarket service heads at precision engineering distributors underwrites the qualitative findings in this study. Primary interviews with regulatory affairs specialists and GPO contracts managers combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EU MDR Annex I technical documentation, and SEC filings from listed analytical instrument manufacturers. Bottom-up unit deployment estimates triangulate against top-down market sizing derived from trade data in NIR-grade optical components.
Comparable-period anchoring to historical replacement cycles in pharmaceutical quality control laboratories and food processing HACCP modernization waves structured the forecast window across the projection horizon. Segmentation modeling incorporated product type, end-use industry, detector technology platform, and regional regulatory cluster dimensions. CAGRs were derived from installed base evolution and upgrade trajectory analysis, with specific inputs including silicon photodiode array cost curves and FSSAI infrastructure investment disclosures.
Several conditions sit outside the modeled scope, including potential export control expansions on NIR-grade optical fibers and unforeseen disruptions in InGaAs detector supply chains. Forecasts reflect assumptions regarding continued FDA enforcement of electronic records standards and sustained EU MDR documentation requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Brightness Meter Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
LAN Tester Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Europe Electronic Test and Measurement Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Micro Ohmmeter Market