
 Voltage Calibrator Market | 2026-2036
Voltage Calibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Calibrator Market Outlook
Precision-class instrumentation is rotating toward higher-accuracy tiers as utilities and laboratories face tighter traceability mandates. Fluke Corporation leverages its distributed service network to sustain aftermarket calibration contracts across power generation sites. Keysight Technologies anchors its position through R&D intensity in automated calibration software that reduces operator intervention. Yokogawa Electric Corporation differentiates via manufacturing scale in bench systems serving Japanese semiconductor fabs.
A voltage calibrator generates precisely known electrical potential to verify and adjust the accuracy of voltmeters, multimeters, and data acquisition systems, typically achieving stability within parts-per-million over defined temperature ranges. Portable calibrators capture expanding share as field technicians replace bench-bound workflows with on-site verification at substations and wind farms. Digital calibration technology leads value generation where facilities integrate software-driven architectures that log audit trails automatically for IEC 17025 compliance.
NIST-traceable standards in the United States, IEC 17025 accreditation frameworks, and Japan's JIS calibration protocols collectively shape product specifications and market access requirements for cross-border equipment sales. Regulatory pressure on measurement uncertainty budgets forces end users to retire non-compliant analog units faster than natural replacement cycles would dictate. Stakeholders must monitor evolving cybersecurity requirements for networked calibration systems as facilities connect more devices to centralized asset management platforms.
Market Dynamics
Digital calibration protocols are compressing replacement cycles as IEC 17025 mandates force facilities to abandon analog traceability chains. Power utilities and semiconductor fabs drive the fastest equipment turnover, with networked systems now required for centralized asset management platforms.
Growth Catalysts
- Traceability Mandates:IEC 17025 accreditation requirements in Europe and Japan compel laboratories to upgrade aging analog units, creating sustained replacement demand across metrology infrastructure.
- Grid Modernization:US power utilities under FERC reliability standards expand procurement of portable field calibrators for substation verification workflows.
- Semiconductor Fabrication:Japanese fabs deploy precision bench systems to maintain voltage reference stability for advanced node production, anchoring demand for parts-per-million instrumentation.
Market Restraints
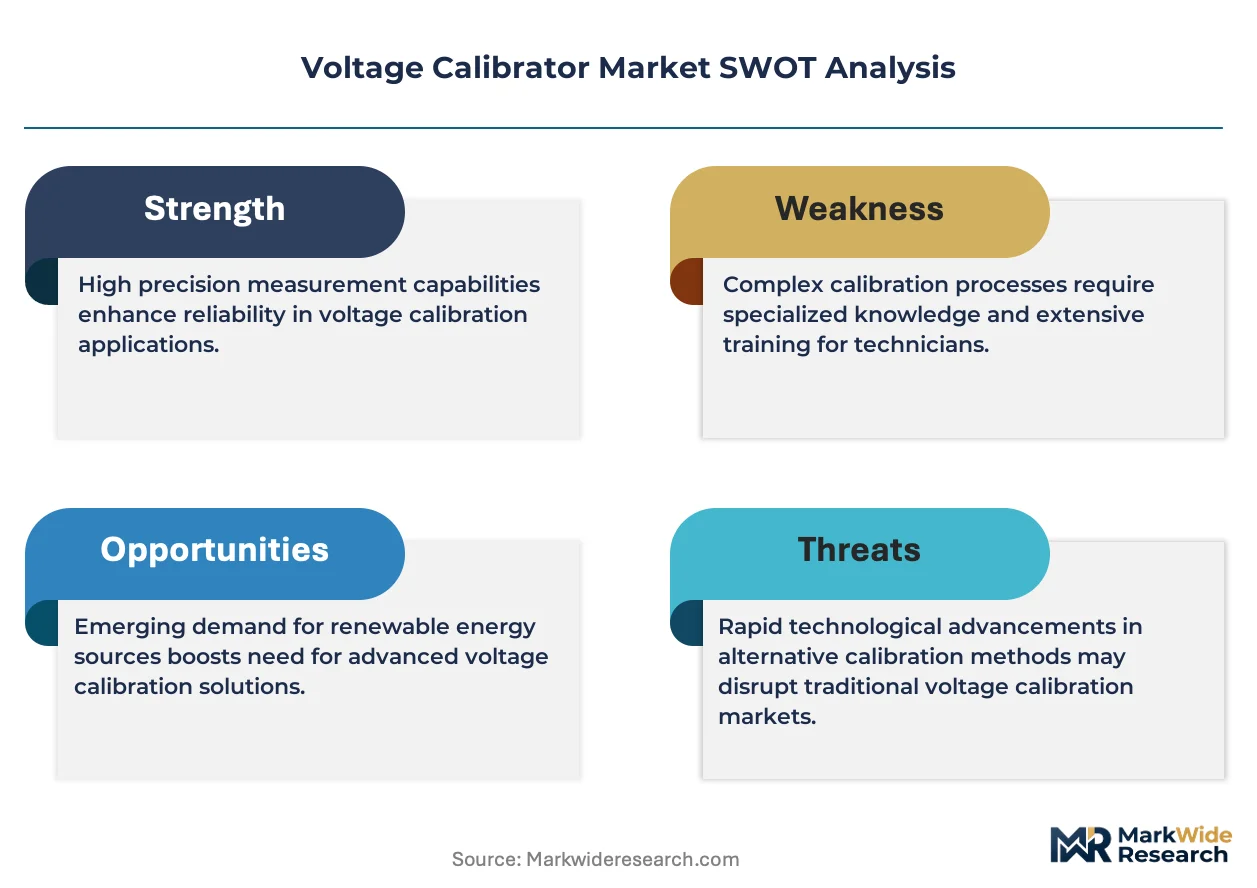
- Precision Component Costs:Voltage references using zener diode arrays and thermal stabilization subsystems face input cost volatility from specialized semiconductor foundry capacity constraints.
- Calibration Service Concentration:Third-party accreditation bodies cluster in Germany, the United States, and Japan, creating geographic bottlenecks for facilities seeking local traceability certification.
- Analog Obsolescence Friction:Legacy equipment with decades-long service life resists premature retirement despite non-compliance with digital audit trail requirements.
Strategic Opportunities
- Wind Farm Deployment:Offshore installations in the North Sea and Baltic regions require ruggedized portable calibrators for turbine transformer verification in harsh marine environments.
- Automated Software Integration:Convergence of calibration management platforms with enterprise asset management systems enables remote diagnostic capabilities and predictive maintenance scheduling.
- India Laboratory Infrastructure:BIS laboratory recognition programs and expanding pharmaceutical testing capacity create underpenetrated demand for entry-tier bench systems.
Industry Challenges
- Metrology Talent Scarcity:Specialized technicians capable of maintaining uncertainty budgets and interpreting NIST-traceable certificates command premium compensation, constraining facility expansion.
- Multi-Standard Certification Complexity:Equipment vendors must simultaneously satisfy IEC 17025, JIS, and BIS requirements, extending product development timelines and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Calibrator Market |
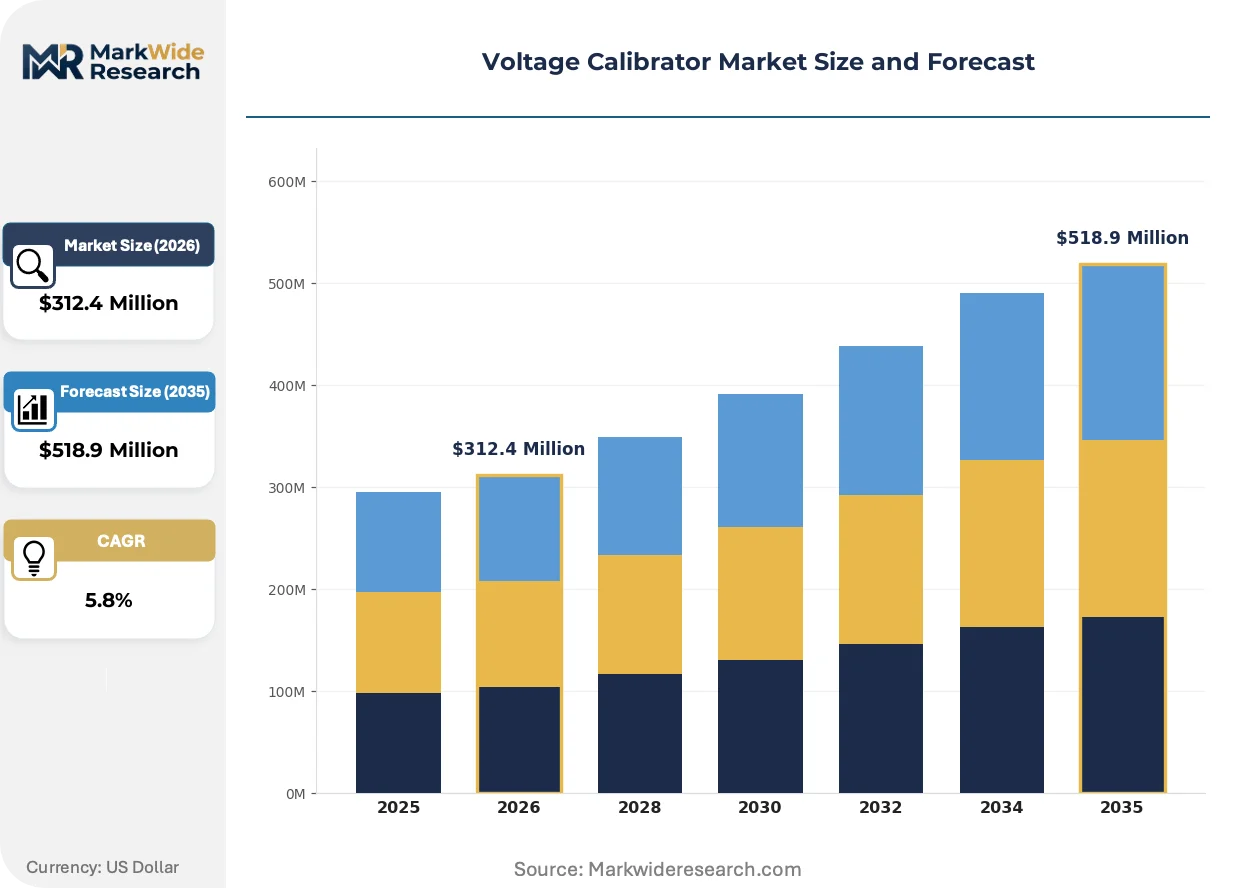
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Calibrators, Bench Calibrators, Multimeter Calibrators, Fixed Calibrators Technology: Analog Calibration, Digital Calibration, Automated Calibration, Software-Driven Calibration End User: Manufacturing, Automotive, Aerospace, Research Laboratories Installation: On-Site Installation, Factory Installation, Remote Setup, Independent Setup |
| Companies Covered | Fluke Corporation, Keysight Technologies, Yokogawa Electric Corporation, AMETEK, Inc., Tektronix, Inc., Omega Engineering, Inc., Rohde & Schwarz, Emerson Electric Co., Beamex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Calibrator Market Strategic Shifts
Calibration technology is separating into distinct performance tiers as end-use requirements diverge between field portability and laboratory precision. Software-defined architectures now dominate new product development, with automated compliance logging becoming a baseline specification rather than a premium feature.
Multi-function calibrator platforms are bifurcating the product landscape. These systems combine voltage, current, and resistance generation in single enclosures, serving maintenance teams at process plants and renewable energy sites. Industrial automation facilities in Germany and the United States adopt these consolidated units aggressively, compressing demand for discrete single-function instruments while expanding total addressable spend per installation.
REACH substance restrictions and RoHS compliance deadlines in Europe are forcing component redesigns for thermal management materials and solder alloys. Manufacturers must reformulate internal assemblies to eliminate restricted substances without degrading temperature coefficient performance. Laboratory-grade bench systems face the tightest compliance timelines, with EU-based vendors accelerating supplier qualification processes for replacement materials.
Field service teams now specify battery-operated calibrators with wireless data logging as standard equipment, displacing tethered bench workflows at remote infrastructure sites. Distributor technical support and rapid replacement programs are replacing traditional capital purchase cycles for utilities managing dispersed generation assets. This pattern concentrates in the United States and Australia, where geographic dispersion of wind and solar installations rewards mobility over laboratory proximity.
Voltage Calibrator Market Segmentation
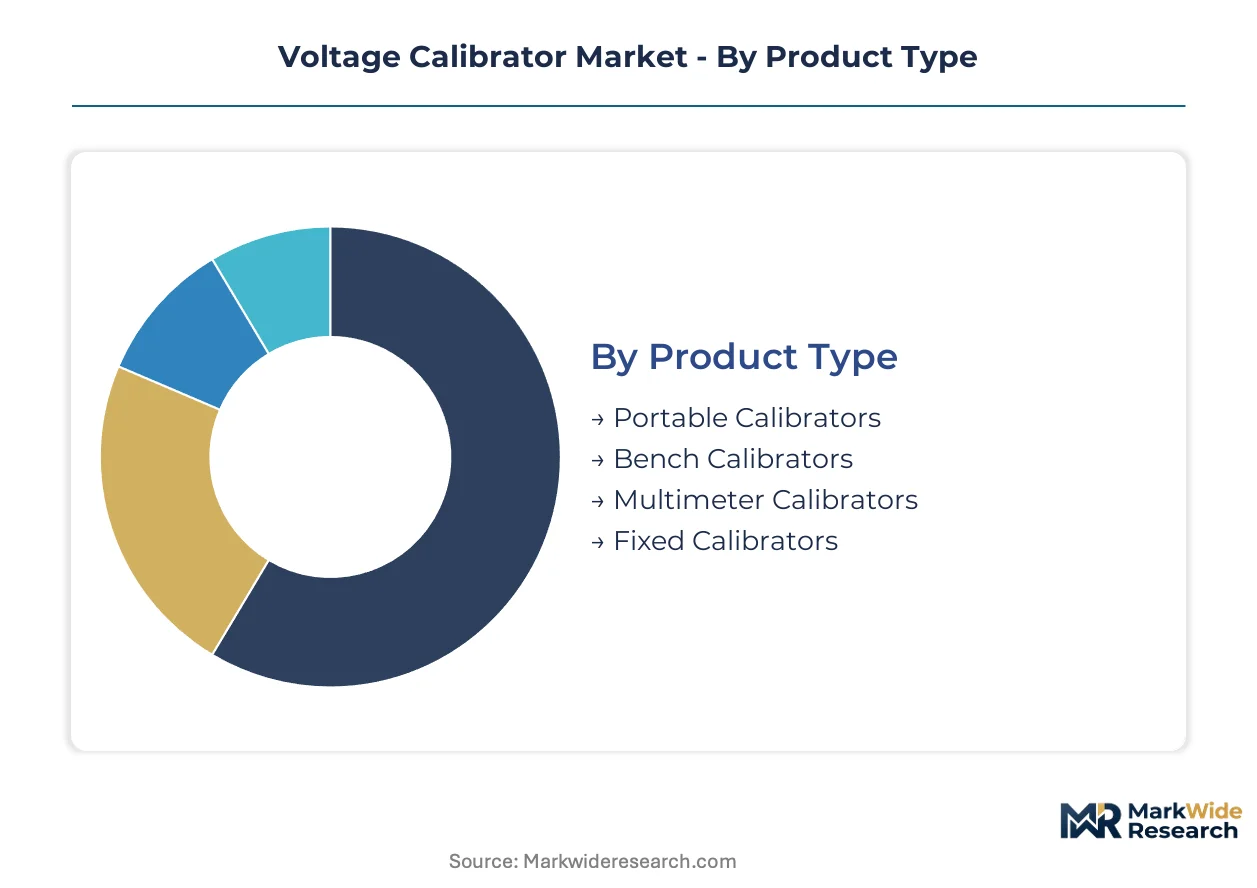
Voltage calibrator procurement patterns diverge sharply across product architectures and deployment contexts. Calibration technology selection directly determines compliance pathways for IEC 17025 accreditation, while end-user industry dictates precision requirements and replacement cycles.
Product Type:
Domestic demand concentrates in bench systems for laboratory infrastructure, whereas portable units drive export volumes to dispersed energy infrastructure markets.
- Portable Calibrators:Battery-operated units with wireless data logging enable turbine transformer verification at offshore wind installations in the North Sea. Field technicians at US power utilities under FERC reliability standards now specify these as standard equipment for substation workflows, displacing tethered bench configurations.
- Bench Calibrators:Precision systems achieving parts-per-million stability serve semiconductor fabrication facilities in Japan where voltage reference integrity anchors advanced node production. Japanese fabs deploy these for metrology infrastructure requiring JIS calibration protocol compliance.
- Multimeter Calibrators:Consolidated platforms combining voltage, current, and resistance generation serve maintenance teams at German process plants.
- Fixed Calibrators:Permanently installed units support continuous verification chains in automated production lines.
Bench calibrators hold the largest share; momentum sits with portable calibrators.
Technology:
Cost tier separation between legacy analog systems and premium digital architectures reshapes replacement timing across facility budgets.
- Digital Calibration:Software-defined architectures with automated audit trail logging satisfy IEC 17025 mandates without operator transcription. European laboratories facing REACH compliance deadlines accelerate procurement of these systems to replace analog traceability chains.
- Software-Driven Calibration:Platforms integrating with enterprise asset management systems enable remote diagnostics and predictive maintenance scheduling. US power utilities connect these to centralized platforms for dispersed generation asset management.
- Analog Calibration:Legacy equipment with decades-long service life resists premature retirement despite non-compliance with digital documentation requirements.
- Automated Calibration:Reduced operator intervention protocols address metrology talent scarcity in high-cost labor markets.
Digital calibration dominates installed base; software-driven calibration is climbing the fastest.
End User:
Application-specific precision requirements create divergent procurement patterns across manufacturing intensity and regulatory exposure.
- Research Laboratories:Facilities pursuing IEC 17025 accreditation in Germany and Japan drive demand for highest-accuracy tiers. These installations require NIST-traceable or JIS-compliant certificates with documented uncertainty budgets.
- Manufacturing:Industrial automation facilities deploy multi-function platforms for process verification, with German and US sites consolidating spend per installation.
- Aerospace:Stringent traceability requirements for flight-critical systems sustain premium pricing for certified calibration intervals.
- Automotive:EV battery testing expansion creates demand for voltage reference stability in validation laboratories.
Research laboratories command premium pricing; manufacturing delivers volume scale.
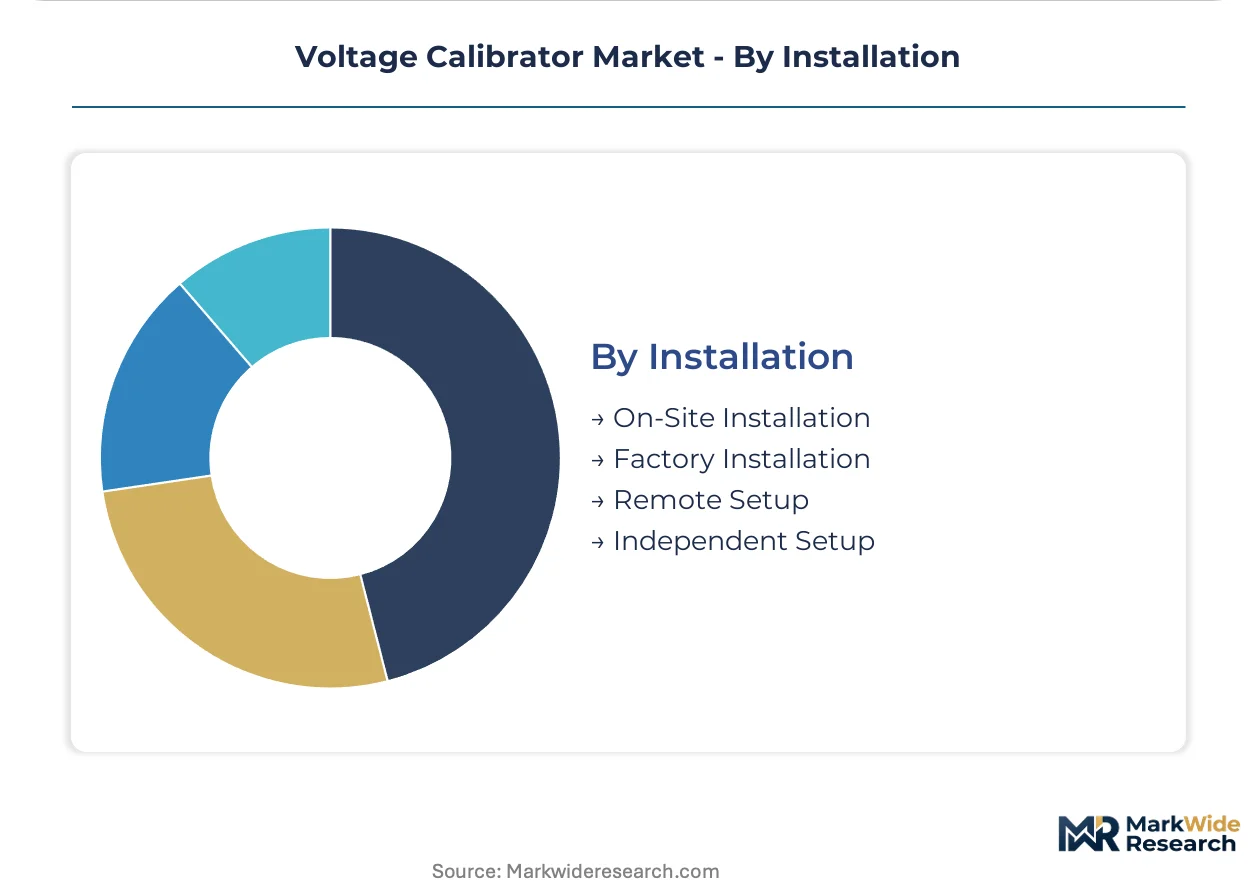
Installation:
Customer type separation between capital-purchase facilities and service-contract operators determines deployment logistics and support structures.
- On-Site Installation:Field deployment at remote wind and solar installations in Australia and the western United States rewards mobility over laboratory proximity. Distributor technical support programs replace traditional purchase cycles for geographically dispersed assets.
- Factory Installation:Original equipment integration at semiconductor fabrication facilities in Japan ensures matched performance specifications.
- Remote Setup:Networked configuration enables centralized asset management platform integration.
- Independent Setup:Self-contained deployment suits facilities with internal metrology capabilities.
Factory installation anchors precision applications; on-site installation gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for precision voltage references clusters in specialized semiconductor foundries across Germany, Japan, and the United States. Calibration equipment manufacturers concentrate final assembly near these supply nodes to minimize thermal coefficient degradation during logistics.
United States
FERC reliability standards compel power utilities to deploy portable field calibrators for substation verification workflows. NIST-traceable certificate requirements shape procurement specifications for metrology laboratories in Maryland and Colorado. Field service teams across Texas and California wind farms specify battery-operated wireless units as standard equipment.
Germany
Industrial automation density in Bavaria and Baden-Württemberg sustains demand for multi-function bench systems combining voltage, current, and resistance generation. REACH substance restrictions and RoHS compliance deadlines force component redesigns for thermal management materials. IEC 17025 accreditation requirements accelerate replacement of analog traceability chains in Berlin and Hamburg laboratory clusters.
Japan
Semiconductor fabrication facilities in the Kanto and Kansai regions deploy precision bench systems for voltage reference stability at advanced production nodes. JIS calibration protocols mandate documented uncertainty budgets for metrology infrastructure. METI industrial standards enforcement tightens measurement traceability requirements for Tokyo and Osaka research laboratories.
China
GB standards alignment with IEC frameworks expands market access for imported calibration equipment in Shanghai and Beijing laboratory clusters. MIIT industrial upgrading programs accelerate domestic precision instrument development. Yangtze River Delta manufacturing bases integrate automated calibration protocols for export-oriented electronics production.
India
BIS laboratory recognition programs and expanding pharmaceutical testing capacity create demand for entry-tier bench systems in Maharashtra and Gujarat. CEA grid modernization initiatives drive procurement of portable verification equipment for substation infrastructure. Karnataka and Telangana technology corridors invest in metrology infrastructure for semiconductor assembly and testing operations.
Voltage Calibrator Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the voltage calibrator market. Premium-tier vendors concentrate in Germany, Japan, and the United States where precision component ecosystems sustain parts-per-million stability specifications. Mid-tier competitors compete on consolidated multi-function platforms that compress installation footprints. Capacity expansion and strategic partnerships dominate competitive moves as vendors seek to anchor aftermarket calibration service contracts.
Among diversified instrumentation conglomerates, Fluke Corporation and Keysight Technologies occupy positions exemplifying technology-intensive competitive strategies. Yokogawa Electric Corporation anchors the manufacturing-scale archetype serving precision-dependent East Asian industrial markets. These three entities represent distinct strategic postures: distributed service network leverage, automated software integration, and regional supply chain proximity respectively.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Yokogawa Electric Corporation |
| AMETEK, Inc. |
| Tektronix, Inc. |
| Omega Engineering, Inc. |
| Rohde & Schwarz |
| Emerson Electric Co. |
| Beamex |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in both precision component supply access and price visibility for power utilities and semiconductor fabs across Germany, Japan, and the United States. These multi-year agreements bundle equipment procurement with mandatory IEC 17025 accreditation maintenance, insulating vendors from spot-market volatility in zener diode arrays while committing buyers to scheduled upgrade cycles.
Pricing Analysis
IEC 17025 accreditation dictates the pricing tier structure across the voltage calibrator landscape. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade bench systems with parts-per-million stability from field-portable units and entry-tier multimeter calibrators. Certification grade and after-sales service bundling drive price differentiation, with NIST-traceable documentation commanding substantial premiums. Pricing pressure stems from REACH compliance deadlines forcing component redesigns without performance degradation. Research laboratories exhibit lowest price sensitivity due to regulatory mandates, while Indian pharmaceutical testing facilities represent the most price-conscious segment.
Supply Chain Analysis
Specialized semiconductor foundry capacity in Germany, Japan, and the United States serves as the critical chokepoint for precision voltage reference production. Component sourcing draws from thermal stabilization subsystem manufacturers in Bavaria, zener diode array fabricators in Kansai, and precision resistor networks in Colorado. Single-source vulnerability concentrates around legacy analog component suppliers facing obsolescence. Distribution runs through authorized distributor technical support programs rather than direct OEM channels, particularly for geographically dispersed wind farm and substation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technicians capable of maintaining uncertainty budgets and interpreting traceability certificates remain scarce across all major markets, constraining facility expansion and equipment utilization rates. This capability gap amplifies competitive advantage for vendors with embedded training and remote diagnostic platforms.
For Market Incumbents: Secure aftermarket calibration service contracts through distributed technical support networks before emerging software-defined calibration platforms displace hardware-centric revenue streams. Invest in automated compliance logging capabilities to defend against new entrants offering subscription-based calibration management. Prioritize certification investment in BIS-recognized programs for Indian laboratory infrastructure expansion.
For New Entrants and Emerging Players: Lead with ruggedized portable calibrators targeting offshore wind installations in the North Sea and Baltic regions, where marine environment specifications create specification gaps incumbent bench-system vendors underserve. Target India's pharmaceutical testing corridor with entry-tier bench systems priced below IEC 17025-accredited tiers. Establish go-to-market partnerships with regional distributors offering rapid replacement programs rather than capital sales cycles.
For Investors and Strategic Acquirers: Precision calibration software specialists with automated audit trail platforms represent the most attractive acquisition archetype for long-term viability across the 5-10 year window. These assets capture recurring revenue from IEC 17025 compliance mandates while hardware margins compress. Watch for inflection signals in cybersecurity requirements for networked calibration systems as facilities accelerate centralized asset management platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Contract Expansion | Locks in recurring revenue from FERC-mandated utility verification workflows. |
| Automated Software Integration | Reduces operator intervention for METI-regulated Japanese semiconductor fabs. |
| Backward Integration into Precision Components | Insulates margins from zener diode foundry capacity constraints in Germany. |
| Geographic Expansion into India | Captures BIS laboratory recognition program procurement in Maharashtra. |
| RoHS Compliance Component Redesign | Maintains EU market access under REACH thermal material restrictions. |
Study Parameters
Initial hypotheses were tested against primary input from metrology laboratory directors, power utility maintenance managers, semiconductor fab equipment engineers, and calibration service technicians, then refined through secondary validation. Primary discussions captured procurement decision criteria for IEC 17025 accreditation requirements, replacement cycle timing, and software integration priorities. Secondary sources included NIST calibration certificate databases, IEC standard revision documentation, FERC reliability standard filings, and trade data for precision instrument imports. Bottom-up equipment unit economics were triangulated against top-down market sizing from metrology infrastructure investment disclosures.
Variance decomposition across product type, technology tier, end-user industry, and installation model shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included portable versus bench system architectures, digital versus analog calibration protocols, and on-site versus factory installation patterns. CAGRs were derived from replacement cycle compression rates under tightening traceability mandates and grid modernization capital deployment schedules. Forecast inputs incorporated REACH compliance deadline impacts on component costs and Indian BIS laboratory recognition program expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained IEC 17025 enforcement intensity or accelerated analog obsolescence timelines would require recalibration. Forecasts reflect documented assumptions regarding semiconductor foundry capacity allocation and metrology technician labor market tightness. Practitioners should keep alternative scenarios live as cybersecurity requirements for networked calibration systems and offshore wind deployment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Volte Testing Market
Test and Measurement
RFID Tester Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Surface Vision and Inspection Equipment Market