
 Temperature Transmitter Market | 2026-2036
Temperature Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Transmitter Market Analysis
Germany's industrial automation corridor is narrowing the gap between legacy analog systems and digital-native architectures. Emerson Electric Co. leverages its Rosemount portfolio to sustain leadership in process control installations across chemical complexes. Siemens AG anchors its position through tight integration with TIA Portal ecosystems, while Endress+Hauser Group Services AG differentiates through Heartbeat Technology diagnostics that reduce unplanned downtime.
A temperature transmitter converts thermal sensor input into a standardized electrical signal for remote monitoring and control, typically outputting 4-20 mA or digital protocols across ranges from -200°C to 1800°C depending on sensing element selection. Smart transmitters incorporating HART or Foundation Fieldbus protocols now dominate replacement cycles as facilities prioritize predictive maintenance and loop diagnostics. Wireless segments are capturing attention in remote monitoring applications where cabling costs prove prohibitive, though RTD-based wired systems still occupy the bulk of revenue in food processing and aerospace where signal integrity remains paramount.
EU F-Gas Regulation mandates tighter leak detection and refrigerant tracking, directly expanding transmitter deployment in commercial HVAC and cold storage chains. FDA 21 CFR Part 11 and EU GMP Annex 15 both impose validation requirements on pharmaceutical temperature records, creating specification premiums for calibrated digital units with audit trails. Stakeholders must weigh the capital cost of smart transmitter retrofits against the operational risk of non-compliance in regulated environments.
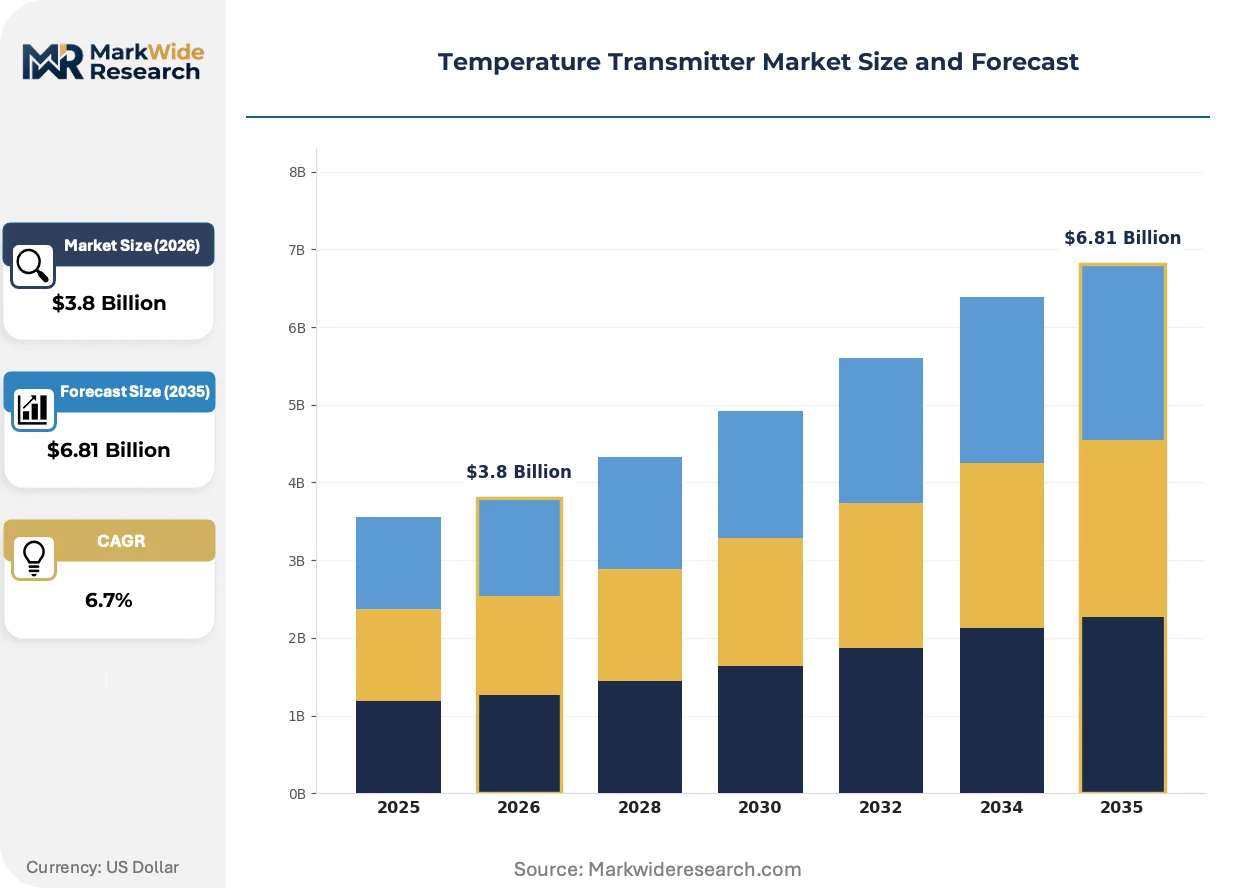
Market Dynamics
Smart transmitter retrofits are compressing replacement cycles across process industries as facilities confront simultaneous pressure from predictive maintenance mandates and refrigerant-tracking regulations.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phase-down policies are forcing HVAC operators toward precise thermal monitoring, expanding transmitter deployment in commercial cold chains and rooftop units.
- Pharmaceutical validation requirements:FDA 21 CFR Part 11 and EU GMP Annex 15 impose audit-trail mandates on temperature records, creating specification premiums for calibrated digital units with embedded diagnostics.
- Wireless protocol maturation:ISA100 and WirelessHART deployments are penetrating remote monitoring applications where cabling costs previously blocked transmitter installation.
Market Restraints
- Platinum price volatility:RTD sensing elements depend on platinum wire, exposing manufacturers to commodity swings that compress margin buffers on standard product lines.
- Foundry concentration in East Asia:MEMS temperature sensor die fabrication clusters in Taiwan and South Korea, creating single-source vulnerability for transmitter OEMs.
- Legacy 4-20 mA persistence:Installed base inertia slows digital protocol adoption as maintenance teams resist retraining on HART or Foundation Fieldbus diagnostics.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO temperature-mapping requirements for vaccine distribution are opening specification windows for validated smart transmitters in warehousing and last-mile transport.
- Electrification of heat:Industrial heat-pump installations for process steam are creating transmitter demand for refrigerant loop monitoring and compressor thermal protection.
- Cloud-native SCADA convergence:Edge-to-cloud architectures are enabling transmitter-integrated analytics that bypass traditional DCS layers, opening SaaS revenue models for hardware vendors.
Industry Challenges
- Fieldbus certification timelines:Foundation Fieldbus and Profibus PA device approval cycles stretch 12-18 months, delaying product launches and freezing engineering roadmaps.
- Silicon-to-steel integration complexity:Combining MEMS sensing with industrial-grade housings requires thermal modeling expertise that sits at the intersection of semiconductor and process-automation engineering cultures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Transmitter Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Wireless, Smart End User: Industrial, Healthcare, Pharmaceuticals, HVAC Technology: RTD, Thermocouple, Infrared, Bimetallic Application: Process Control, Environmental Monitoring, Food Processing, Aerospace |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., Endress+Hauser Group Services AG, ABB Group, Siemens AG, Yokogawa Electric Corporation, OMEGA Engineering Inc., Krohne Ltd., WIKA Alexander Wiegand SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Transmitter Market Emerging Trajectories
Sensor fusion and edge computing are redefining what a temperature transmitter delivers, shifting value capture from signal conversion toward embedded diagnostics and predictive algorithms.
Multi-sensor fusion is hybridizing temperature transmitters with pressure and flow sensing in single housings. Chemical processors in the US Gulf Coast are piloting these compact loops to reduce wiring density in hazardous areas. The convergence is compressing instrument count per measurement point while raising firmware complexity.
REACH substance restrictions are phasing out certain potting compounds and sealing elastomers used in transmitter construction. European process OEMs are reformulating housings with fluoropolymer alternatives that maintain IP ratings across thermal cycling. Food-contact applications face the tightest substitution timelines as EFSA reviews migrate into procurement specifications.
Buyer consolidation among EPC firms is compressing vendor qualification lists. Top-tier engineering contractors in the Middle East are mandating pre-approved transmitter brands for lump-sum turnkey projects, forcing smaller OEMs toward distributor partnerships or private-label arrangements. This channel consolidation is most visible in hydrogen and carbon-capture project pipelines where risk-averse procurement dominates.
Temperature Transmitter Market Segmentation
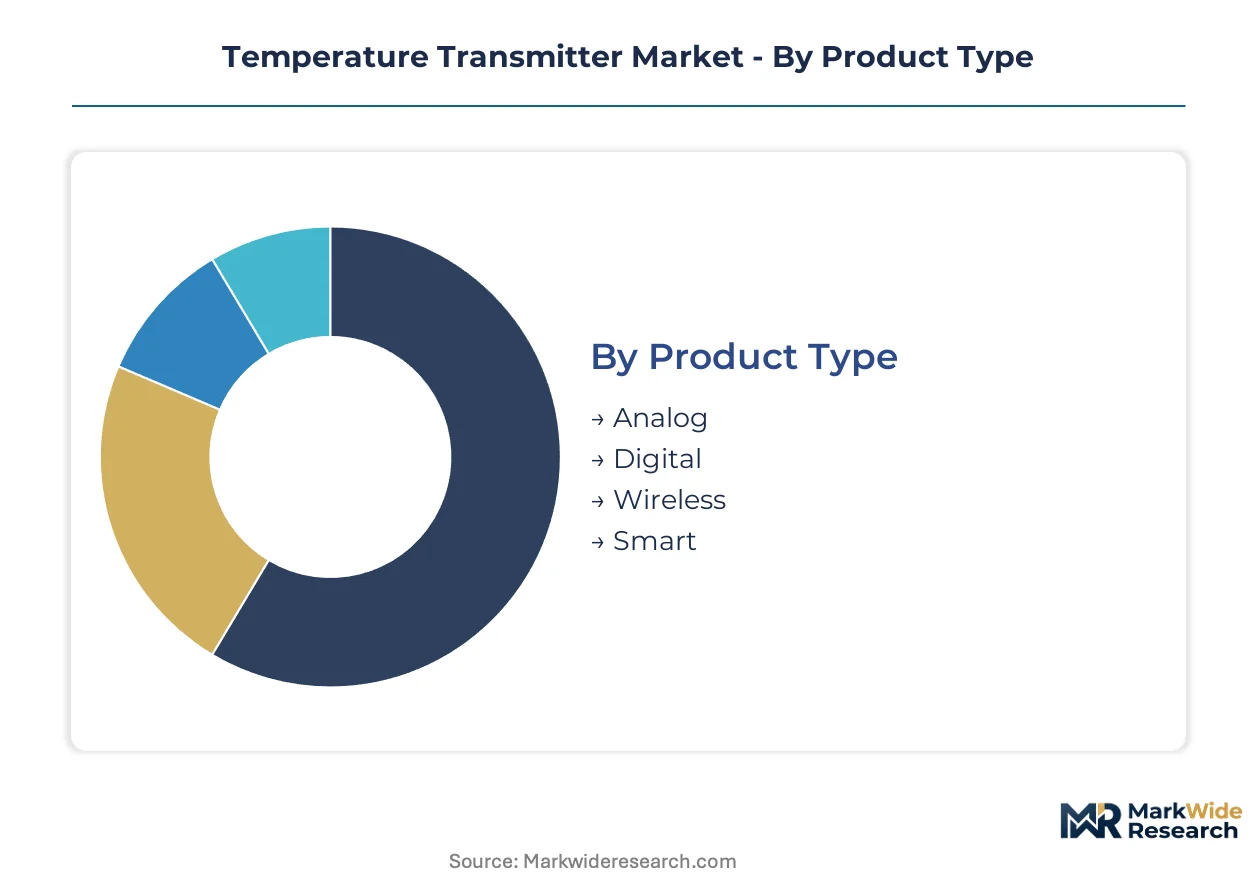
Segmentation in temperature transmitters maps directly to capital allocation patterns and compliance requirements. Product architecture choices determine protocol compatibility and maintenance economics, while end-user concentration shapes specification premiums and channel access.
Product Type:
Cost tier differentiation separates legacy replacement demand from greenfield digital specification.
- Smart:Embedded HART or Foundation Fieldbus protocols enable predictive diagnostics and loop verification without process interruption. Pharmaceutical manufacturers in Germany and HVAC operators facing EU F-Gas mandates are specifying these units for audit-trail compliance and refrigerant leak detection.
- Wireless:ISA100 and WirelessHART implementations eliminate cabling runs in remote tank farms and distributed solar thermal arrays. Deployment is concentrating in Middle Eastern petrochemical sites where trenching costs exceed transmitter hardware multiples.
- Analog:4-20 mA output dominates brownfield maintenance budgets where control system replacement timelines stretch across decades.
- Digital:Native digital protocols serve as bridge architectures during hybrid analog-digital transition phases in process plants.
Smart transmitters hold installed capacity. Wireless is rotating up the share rankings.
End User:
Application context determines calibration rigor and documentation requirements.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU GMP Annex 15 impose validation requirements on temperature records, creating specification premiums for calibrated digital units with embedded diagnostics and electronic signatures.
- HVAC:EU F-Gas Regulation mandates tighter leak detection and refrigerant tracking, expanding transmitter deployment in commercial rooftop units and cold storage chains across France, Germany, and Italy.
- Industrial:Chemical complexes and refineries drive volume through standardized 4-20 mA replacement cycles.
- Healthcare:Hospital sterilization and blood bank monitoring require ISO 17025 traceable calibration certificates.
Pharmaceuticals anchors specification premiums. HVAC is climbing the fastest on regulatory compulsion.
Technology:
Sensing element selection trades accuracy, range, and material cost against application constraints.
- RTD:Platinum wire elements deliver stability within ±0.1°C across -200°C to 850°C ranges. Food processing and aerospace applications in the US and Germany specify these where signal integrity overrides commodity price exposure.
- Thermocouple:Noble metal and base metal junctions span extremes to 1800°C in steel melt shops and gas turbine exhaust monitoring.
- Infrared:Non-contact measurement serves moving targets and hazardous media in glass manufacturing.
- Bimetallic:Mechanical actuation persists in safety-critical overtemperature protection where electrical isolation matters.
RTD holds installed capacity. Thermocouple is rotating up the share rankings in high-temperature process intensification.
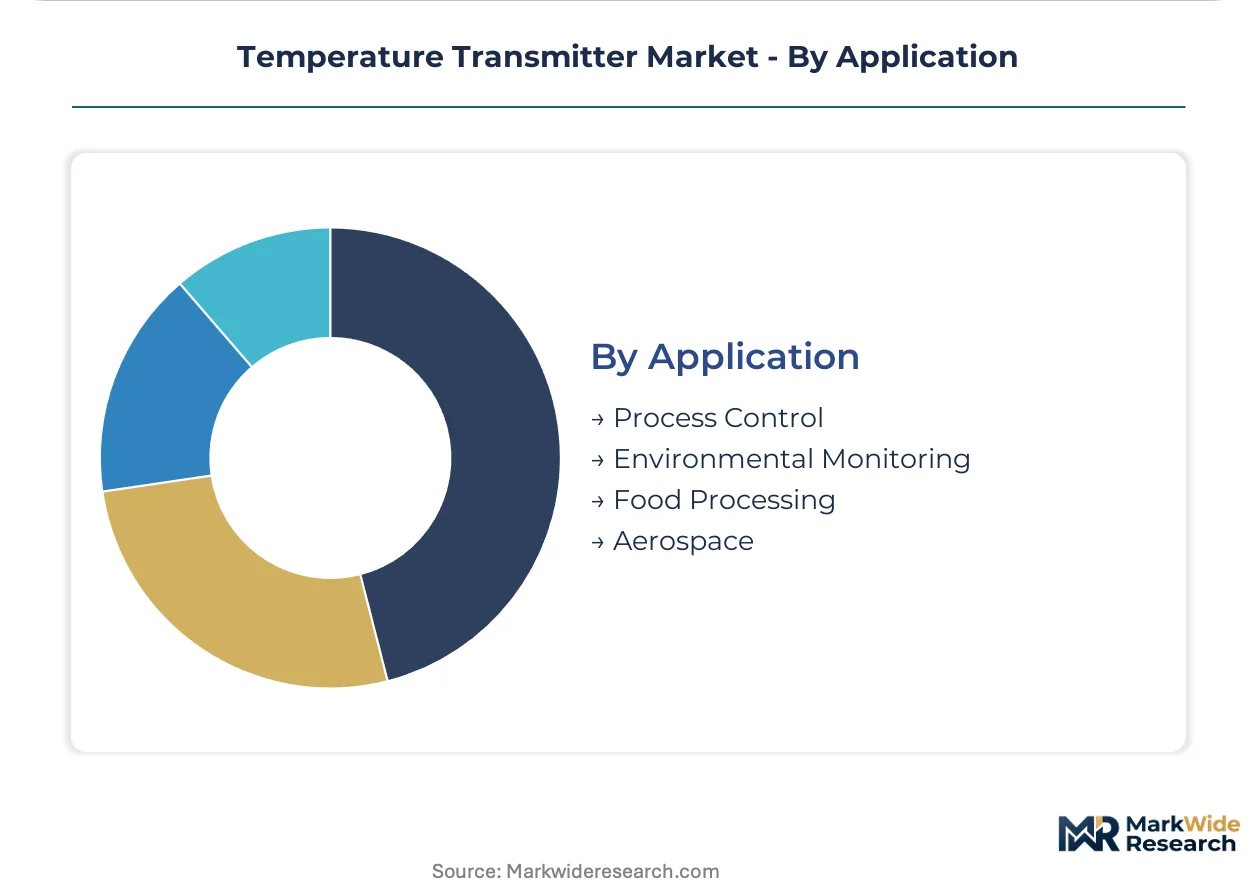
Application:
Deployment setting dictates housing ruggedness, response time, and certification requirements.
- Process Control:Chemical reactors and distillation columns demand SIL-rated transmitters with redundant sensing paths. US Gulf Coast and Ludwigshafen clusters specify these for hazardous area compliance.
- Food Processing:Hygienic tri-clamp connections and IP69K washdown ratings dominate dairy and meat processing lines in Denmark and the Netherlands.
- Environmental Monitoring:Stack emissions and wastewater compliance drives demand for corrosion-resistant housings.
- Aerospace:MIL-STD-810 qualification and radiation tolerance filter supplier pools to defense-aerospace tier ones.
Process Control holds installed capacity. Food Processing is gaining share fastest on hygiene regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation enforcement in Germany is compressing HVAC replacement cycles and accelerating digital transmitter specification across chemical automation corridors.
United States
FDA 21 CFR Part 11 validation requirements drive pharmaceutical specification premiums for calibrated smart transmitters with electronic signatures. EPA refrigerant tracking mandates expand deployment in commercial cold chains. Houston and Louisiana Gulf Coast chemical clusters specify SIL-rated units for hazardous area compliance in process control installations.
Germany
EU F-Gas Regulation phase-down policies force HVAC operators toward precise thermal monitoring in rooftop units and cold storage. REACH substance restrictions are reformulating transmitter housings with fluoropolymer alternatives. Ludwigshafen and Munich industrial automation clusters narrow the gap between legacy analog and digital-native architectures.
China
NMPA pharmaceutical cold chain regulations and dual carbon goals accelerate smart transmitter adoption in vaccine distribution networks. GB standards for industrial automation drive specification upgrades in process plants. Yangtze River Delta manufacturing hubs concentrate MEMS temperature sensor die fabrication capacity.
India
CDSCO temperature-mapping requirements for vaccine distribution open specification windows for validated smart transmitters in warehousing and last-mile transport. PLI scheme incentives support domestic automation component manufacturing. Maharashtra and Gujarat pharmaceutical clusters drive demand for audit-trail-compliant digital units.
Japan
METI industrial efficiency standards and PMDA pharmaceutical validation requirements shape transmitter specification in precision manufacturing. JIS certification maintains barrier to entry for imported units. Kansai and Chubu industrial corridors prioritize predictive maintenance integration in chemical and automotive process control.
Temperature Transmitter Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with process automation portfolios, specialized measurement technology firms with diagnostic differentiation, and regional fabrication houses serving maintenance replacement demand. Competitive moves center on strategic partnerships for protocol certification acceleration and portfolio diversification into multi-sensor fusion architectures.
Within the diversified industrial tier, Emerson Electric Co. and Siemens AG occupy positions anchored by tight integration with distributed control system ecosystems. Endress+Hauser Group Services AG exemplifies the specialized diagnostic archetype through Heartbeat Technology positioning. Honeywell International Inc. and ABB Group represent scale-driven conglomerates with broad automation portfolios spanning multiple transmitter technologies. Yokogawa Electric Corporation and Krohne Ltd. sit within the precision-oriented specialist segment.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| Endress+Hauser Group Services AG |
| ABB Group |
| Siemens AG |
| Yokogawa Electric Corporation |
| OMEGA Engineering Inc. |
| Krohne Ltd. |
| WIKA Alexander Wiegand SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta MEMS foundries concentrate temperature sensor die fabrication, granting Chinese contract manufacturers outsized leverage over transmitter OEMs facing platinum price volatility and REACH compliance costs. This geographic clustering compresses margin buffers for European and North American brands while amplifying pricing power for integrated suppliers with captive semiconductor capacity.
Pricing Analysis
German industrial automation corridors command 15-25% premiums over Southeast Asian spot markets for SIL-rated smart transmitters with embedded HART diagnostics. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in analog replacement tiers is intensifying as maintenance budgets stagnate and brownfield facilities defer digital retrofits. Pharmaceutical manufacturers prove least price-sensitive due to FDA 21 CFR Part 11 validation requirements, while HVAC contractors in price-competitive markets prioritize per-unit transactional economics.
Supply Chain Analysis
Foundry capacity at Taiwan Semiconductor Manufacturing and South Korean MEMS specialists anchors global supply for precision sensing elements. Platinum wire for RTD elements draws from South African and Russian mining operations, while fluoropolymer housing materials rest on Japanese and German chemical suppliers. Single-source vulnerability concentrates in Taiwan wafer fabrication, where geopolitical friction threatens transmitter OEM delivery schedules. Distribution runs through authorized industrial distributors and EPC pre-approval lists rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless protocol maturation and EU F-Gas regulatory compulsion are disrupting legacy analog architectures, compressing replacement cycles and opening specification windows for diagnostic-enabled units.
For Market Incumbents: Harden fieldbus certification pipelines to compress 12-18 month Foundation Fieldbus approval timelines that freeze engineering roadmaps. Deepen backward integration into MEMS temperature sensor die production to offset Taiwan foundry concentration risk. Prioritize TIA Portal and DeltaV ecosystem lock-in against emerging cloud-native SCADA challengers.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with ISA100 wireless deployments bypassing trenching cost barriers that block wired transmitter installation. India's CDSCO-mandated vaccine cold chain offers specification windows for validated smart transmitters in warehousing applications. Partner with regional EPCs for lump-sum turnkey project pre-approval rather than competing for direct OEM specification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized measurement firms with diagnostic differentiation over diversified industrial conglomerates facing portfolio complexity drag. Long-term viability hinges on edge-to-cloud analytics integration and multi-sensor fusion R&D pipelines. Watch WirelessHART and ISA100 penetration rates in Middle Eastern petrochemical installations as inflection indicators for protocol standardization winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Development | Chemical processors in the US Gulf Coast pilot compact temperature-pressure-flow loops to reduce hazardous area wiring density. |
| Cloud-Native SCADA Integration | Edge-to-cloud architectures enable transmitter-integrated analytics that bypass traditional DCS layers for SaaS revenue capture. |
| REACH Compliant Housing Reformulation | European OEMs substitute fluoropolymer alternatives for phased-out potting compounds to maintain IP ratings across thermal cycling. |
| Wireless Protocol Certification Acceleration | Shortened ISA100 and WirelessHART approval cycles unlock Middle Eastern petrochemical sites where trenching costs dominate. |
| Pharmaceutical Validation Service Bundling | FDA 21 CFR Part 11 and EU GMP Annex 15 audit-trail mandates create recurring revenue from calibration certificate subscriptions. |
Methodological Framework
A spread of perspectives from plant engineers at Ludwigshafen chemical complexes, procurement leads at German HVAC contractors, and regulatory affairs specialists at pharmaceutical OEMs converged on the working assumptions. Primary fieldwork combined structured interviews with maintenance directors and EPC specification engineers alongside secondary validation through SEC 10-K automation segment disclosures, EU F-Gas Regulation implementation reports, and customs trade data for platinum wire imports. Bottom-up transmitter shipment estimates triangulated against top-down process automation capital expenditure forecasts.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by smart/wireless/analog/digital architecture, RTD/thermocouple/infrared sensing technology, and pharmaceutical/HVAC/industrial end-use concentration. CAGRs derived from replacement cycle compression rates and regulatory mandate phase-in schedules. Industry-specific inputs included EU F-Gas refrigerant phase-down timelines and CDSCO cold chain mapping requirements.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or platinum commodity prices would shift the trajectory. Forecasts reflect documented assumptions about wireless protocol adoption curves and fieldbus certification timeline stability. Quarterly review of EPC pre-approval list changes and MEMS foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
MEMS Microphones Market