
 Consumer Special Purpose Logic IC Market | 2026-2036
Consumer Special Purpose Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Special Purpose Logic IC Market Outlook
Automotive-grade qualification tiers are redrawing competitive boundaries in consumer-adjacent logic IC supply. Texas Instruments sustains broad analog-digital integration across power management and signal conditioning portfolios. Infineon Technologies anchors its position through mixed-signal expertise tied to automotive and industrial crossover segments. STMicroelectronics differentiates via deep manufacturing scale in European and Asian production nodes.
Consumer special purpose logic ICs are application-specific integrated circuits engineered with fixed or limited reprogrammable gate arrays, operating at voltage thresholds typically between 0.5V and 5V, designed to execute dedicated control, signal processing, or interface functions within electronic systems. Their primary purpose is to replace general-purpose processors in cost-sensitive, high-volume consumer devices where deterministic performance and power efficiency outweigh flexibility requirements. ASIC designs capture the dominant share of unit economics in smartphone and wearable applications where mask costs amortize across million-unit runs. FPGA architectures serve prototyping and low-volume consumer electronics ramps where design iteration cycles compress development timelines. Mixed-signal integration is expanding fastest as audio, haptic, and sensor fusion subsystems demand unified analog front-end and digital processing on single die.
FDA device classification rules influence logic IC specifications in connected health wearables that straddle consumer and medical boundaries. EU REACH and RoHS frameworks restrict substance use in packaging and substrate materials, directly affecting foundry qualification costs and supplier selection. China's GB standards and MIIT semiconductor guidelines shape local procurement mandates for domestic consumer electronics brands. Stakeholders must monitor how automotive qualification spillover and regional substance regulations reshape design win criteria across consumer logic IC portfolios.
Market Dynamics
Automotive-grade qualification spillover is compressing design win cycles in consumer logic ICs, forcing foundries to migrate AEC-Q100 testing protocols into smartphone and wearable supply chains. This cross-tier quality migration is redrawing supplier eligibility criteria and raising capital barriers for mid-tier competitors.
Growth Catalysts
- EU REACH substance restrictions:Halogen-free substrate mandates are accelerating foundry retooling toward green packaging chemistries, creating first-mover advantages for compliant suppliers in European consumer electronics supply chains.
- Camera subsystem integration:Smartphone OEMs are expanding custom ASIC deployment for computational photography pipelines, pulling dedicated image signal processing logic into dedicated die.
- China domestic fabless scaling:MIIT semiconductor guidelines are channeling state procurement toward local design houses, concentrating demand for consumer-grade logic ICs in Shenzhen and Shanghai design clusters.
Market Restraints
- Mask cost escalation:Leading-edge ASIC NRE expenses at advanced nodes are structurally excluding sub-million-unit consumer programs from custom silicon economics.
- Wafer supply concentration:Taiwan-based foundry dominance in mixed-signal BCD processes creates geographic chokepoints for power-integrated logic IC supply.
- FPGA substitution threat:Low-cost programmable logic families from Lattice and Microchip are capturing mid-volume consumer ramps that previously justified ASIC development.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Production-linked incentives for mobile phone assembly are creating captive demand for local logic IC packaging and test capacity.
- Sensor fusion convergence:Unified audio-haptic-proximity subsystems are opening white space for mixed-signal ASICs that consolidate multiple discrete functions.
- Direct-to-OEM distribution:Bypassing traditional distribution channels through foundry-direct design support is compressing qualification timelines for tier-one consumer brands.
Industry Challenges
- Mixed-signal design talent scarcity:Analog-digital co-verification expertise is concentrated among senior designers at a handful of IDMs and design services firms.
- Dual qualification burden:Simultaneous consumer and automotive certification timelines are stretching validation resources without guaranteed volume returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Special Purpose Logic IC Market |
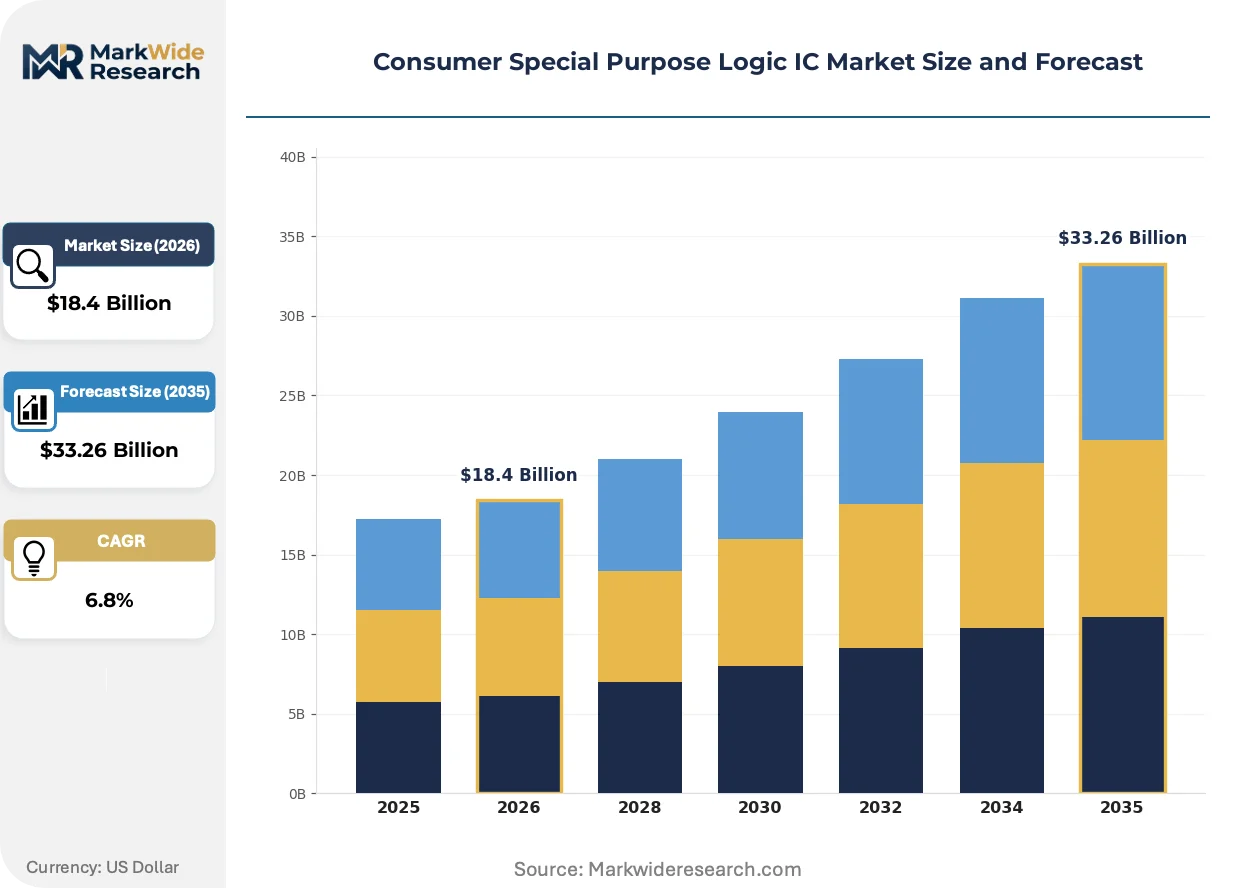
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, CPLD, ASIC, MCU Technology: Analog, Digital, Mixed-Signal, Power Management Application: Consumer Electronics, Automotive Systems, Industrial Control, Telecommunications End User: OEMs, ODMs, Distributors, Aftermarket Providers |
| Companies Covered | NXP Semiconductors, Texas Instruments, Infineon Technologies, STMicroelectronics, Renesas Electronics, Qualcomm, Broadcom, Analog Devices, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Special Purpose Logic IC Market Strategic Shifts
Chiplets and advanced packaging architectures are fragmenting the monolithic logic IC model, enabling function-specific dies to be recombined for rapid consumer product iterations. This disaggregation is compressing time-to-market while complicating thermal and signal integrity management.
Gate-all-around transistor architectures are displacing FinFET structures in sub-3nm consumer logic designs. Smartphone SoC vendors are adopting these geometries for AI acceleration blocks first, with peripheral control logic following in subsequent tapeouts. The transition is displacing established physical design toolchains and favoring EDA vendors with early process design kit access.
EU RoHS recast directives are tightening cadmium and lead exemptions in IC packaging materials. Foundries serving European consumer brands are accelerating electroplating chemistry transitions to tin-bismum alloys. The regulatory pressure is most acute in power discrete and logic IC packages for kitchen appliance and personal care device segments.
Consolidated subsystem procurement is replacing discrete component sourcing for camera and display modules. Tier-one smartphone OEMs are specifying complete imaging pipelines rather than individual sensor and ISP chips. This pattern is most visible in Chinese flagship programs where vertical integration between module houses and logic IC suppliers is tightening.
Consumer Special Purpose Logic IC Market Segmentation
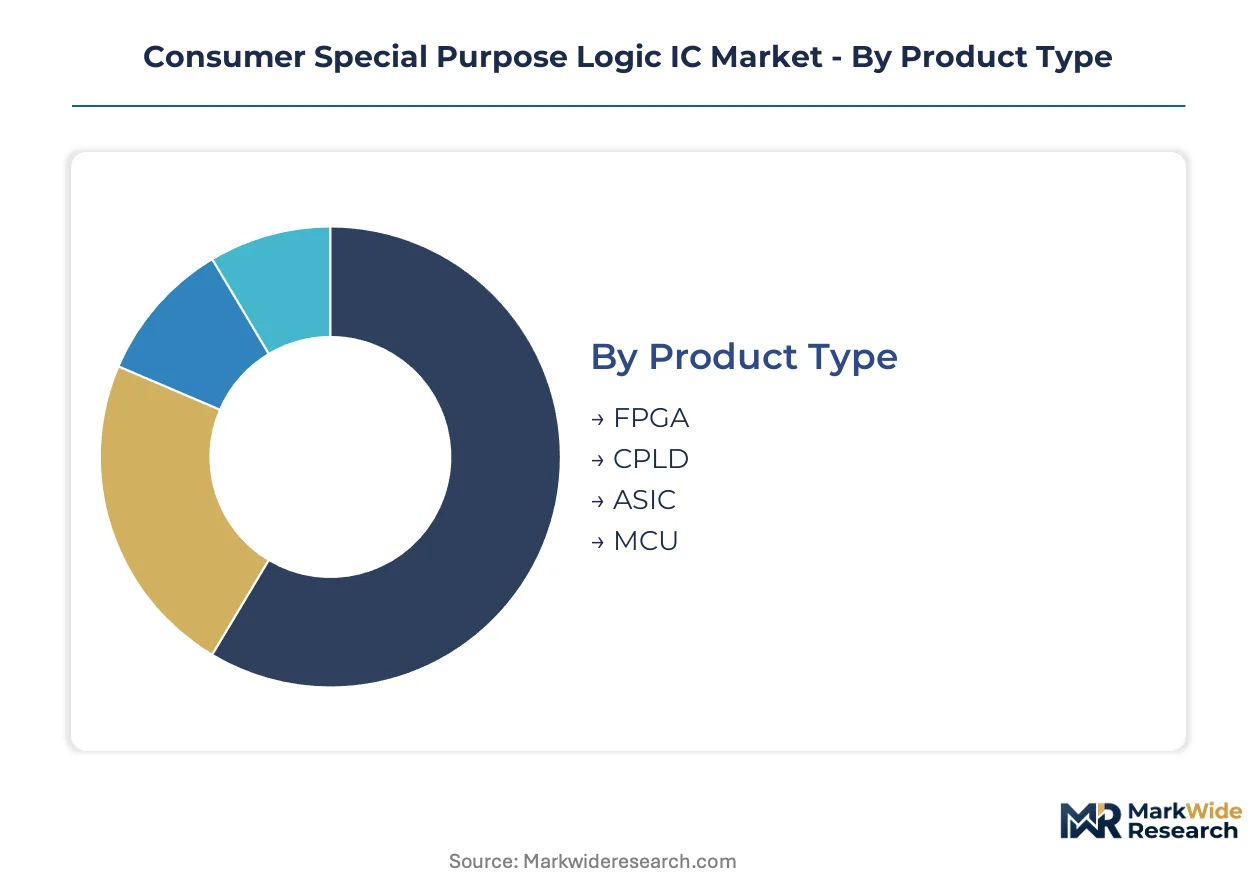
Segmentation in consumer special purpose logic ICs reveals how regulatory, cost, and application pressures fragment procurement patterns. Understanding these divides helps suppliers align qualification investments with actual design win economics.
Product Type:
EU RoHS substance restrictions and FDA device classification rules create divergent qualification burdens across programmable and fixed-logic architectures, reshaping which product types penetrate medical-adjacent wearables versus pure consumer devices.
- ASIC:Fixed-function designs with mask-defined logic gates deliver deterministic performance at lowest unit cost for million-unit smartphone and wearable programs. Shenzhen-based OEMs are concentrating custom silicon procurement for camera pipeline acceleration, though NRE amortization requirements exclude sub-million unit ramps from economic viability.
- FPGA:Field-programmable gate arrays enable rapid design iteration through reconfigurable logic blocks, serving prototyping phases and low-volume consumer electronics ramps where specification volatility exceeds ASIC payback thresholds. Lattice and Microchip programmable families are capturing mid-volume segments that previously justified custom silicon development.
- CPLD:Complex programmable logic devices offer simpler interconnect matrices than FPGAs for glue logic and power sequencing functions in cost-constrained peripherals.
- MCU:Microcontroller units integrate processor cores with embedded logic for control-dominated subsystems in appliances and personal care devices.
ASIC handles the majority of throughput; FPGA is the fastest mover on share.
Technology:
Cost tier stratification separates commodity digital logic from premium mixed-signal integration, with automotive-grade qualification spillover compressing supplier eligibility at the high end.
- Mixed-Signal:Unified analog front-end and digital processing on single die addresses audio, haptic, and sensor fusion subsystems where deterministic latency matters. Infineon and STMicroelectronics manufacturing scale supports this segment's fastest expansion as smartphone OEMs consolidate discrete functions.
- Power Management:Integrated voltage regulation and power sequencing logic operates at thresholds between 0.5V and 5V, with Taiwan-based foundry concentration in BCD processes creating geographic chokepoints for supply security.
- Digital:Pure logic implementations without analog integration serve cost-minimized control functions in high-volume consumer peripherals.
- Analog:Continuous-signal processing blocks remain essential for interface and conditioning stages in legacy appliance designs.
Mixed-Signal commands the steepest expansion trajectory; Power Management anchors volume throughput.
Application:
Customer type concentration varies sharply, with tier-one OEMs driving consolidation in flagship smartphone programs while industrial buyers fragment procurement across qualified supplier bases.
- Consumer Electronics:Smartphones, wearables, and personal care devices generate dominant demand volumes, with computational photography pipelines pulling dedicated image signal processing into custom die. Chinese domestic fabless design houses in Shenzhen and Shanghai clusters are scaling ASIC programs for local brands under MIIT semiconductor guidelines.
- Automotive Systems:Infotainment and body electronics modules adopt consumer-originated logic ICs with modified qualification protocols, creating AEC-Q100 spillover requirements that compress design win cycles.
- Industrial Control:Factory automation and instrumentation applications demand extended temperature ranges and longevity commitments absent from consumer specifications.
- Telecommunications:Infrastructure edge equipment and customer premise devices consume logic ICs with reliability tiers between consumer and full industrial grade.
Consumer Electronics handles the majority of throughput; Automotive Systems is gaining share fastest.
End User:
Supply concentration in Taiwan and China shapes which procurement channels secure allocation during capacity constraints, with direct-to-OEM distribution bypassing traditional intermediaries.
- OEMs:Original equipment manufacturers in smartphone and wearable segments specify complete imaging pipelines rather than discrete components, tightening vertical integration between module houses and logic IC suppliers. Consolidated subsystem procurement is replacing discrete component sourcing for camera and display modules.
- ODMs:Original design manufacturers in Taiwan and China provide turnkey hardware development for brands lacking internal silicon expertise.
- Distributors:Channel partners maintain inventory buffers and design support for mid-tier customers excluded from foundry-direct programs.
- Aftermarket Providers:Repair and refurbishment specialists source legacy logic ICs for extended product life cycles in emerging markets.
OEMs handle the majority of throughput; ODMs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for mixed-signal BCD processes concentrates in Taiwan, creating geographic chokepoints that ripple through consumer logic IC supply chains worldwide. Shenzhen and Shanghai design clusters absorb dominant procurement volumes as domestic fabless houses scale under state semiconductor guidelines. Regulatory divergence across major economies is fragmenting qualification requirements and reshaping supplier eligibility.
China
Smartphone OEMs in Shenzhen and Shanghai are consolidating custom ASIC procurement for computational photography pipelines. MIIT semiconductor guidelines channel state procurement toward domestic fabless design houses, accelerating local program scaling. The Yangtze River Delta and Pearl River Delta clusters concentrate mask-defined logic development for million-unit wearable and flagship mobile programs.
United States
FDA device classification rules influence logic IC specifications in connected health wearables straddling consumer and medical boundaries. FCC emissions standards shape RF-integrated logic designs for wireless audio and proximity sensing subsystems. Texas and California design centers anchor mixed-signal integration expertise for tier-one consumer electronics brands.
Germany
EU REACH substance restrictions and RoHS recast directives are accelerating foundry retooling toward halogen-free substrate chemistries. ECHA compliance mandates raise qualification costs for packaging materials in kitchen appliance and personal care device segments. Bavaria and Baden-Württemberg host automotive-grade qualification spillover into consumer-adjacent infotainment modules.
South Korea
Seoul Capital Area smartphone OEMs are specifying complete imaging pipelines rather than discrete ISP chips, tightening vertical integration between module houses and logic suppliers. MFDS medical device regulations create compliance overlap for health-monitoring wearables. Busan-Ulsan packaging clusters are expanding electroplating capacity for lead-free tin-bismuth alloys.
Japan
METI semiconductor strategy documents prioritize domestic logic IC supply security for consumer electronics brands. JIS standards govern reliability specifications in precision appliance and imaging equipment applications. Kanto and Kansai manufacturing nodes maintain specialty capacity for sensor fusion ASICs in audio-haptic subsystems.
Consumer Special Purpose Logic IC Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with IDMs commanding mixed-signal integration depth while fabless design houses capture ASIC customization economics. The vendor base stratifies across three tiers: diversified analog-digital integrators with captive fabs, programmable logic specialists serving prototyping ramps, and regional fabless houses targeting cost-optimized consumer programs. Dominant competitive moves include foundry-direct design support bypassing traditional distribution, and AEC-Q100 qualification protocol migration into smartphone supply chains.
Among diversified IDMs with European manufacturing scale, Texas Instruments, Infineon Technologies, and STMicroelectronics occupy positions exemplifying analog-digital integration leadership. These entities represent the archetype of broad portfolio suppliers sustaining manufacturing depth across power management and signal conditioning segments. Their positioning reflects how automotive-grade qualification spillover is compressing design win cycles and raising capital barriers for mid-tier competitors in consumer-adjacent logic IC supply.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Texas Instruments |
| Infineon Technologies |
| STMicroelectronics |
| Renesas Electronics |
| Qualcomm |
| Broadcom |
| Analog Devices |
| Microchip Technology |
| Others |
Value Chain & Pricing Dynamics
AEC-Q100 automotive-grade qualification spillover gates both supply eligibility and price tier formation in consumer special purpose logic IC procurement, compressing design win cycles while stratifying quotations between certified and uncertified supplier tiers.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across halogen-free substrate mandates, separating premium-compliant foundry outputs from legacy packaging chemistries. Three-tier pricing structure across automotive-qualified, consumer-grade, and economy unqualified levels reflects certification investment amortization and mask NRE recovery timelines. Cost compression in mid-volume FPGA-substitutable segments is intensifying because Lattice and Microchip programmable families undercut ASIC economics below million-unit thresholds. Smartphone OEMs exhibit lowest price sensitivity for camera pipeline ASICs, while personal care device makers drive aggressive commoditization of generic control logic.
Supply Chain Analysis
Taiwan Strait maritime lanes and foundry concentration in Hsinchu and Tainan Science Parks underwrite global mixed-signal BCD process availability, creating single-source vulnerability for power-integrated logic IC supply. Raw material dependencies center on 300mm silicon wafers, high-purity copper interconnect metals, and halogen-free epoxy mold compounds from Japanese specialty chemical suppliers. Tariff exposure runs through US-China semiconductor equipment restrictions affecting advanced node access. Distribution runs through foundry-direct design support programs that bypass traditional channel inventory for tier-one consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate-all-around transistor architecture disruption at sub-3nm geometries is accelerating competitive repositioning, with AI acceleration block adoption in smartphone SoCs creating qualification bottlenecks that favor EDA vendors with early process design kit access.
For Market Incumbents: Compound mixed-signal integration depth through captive BCD process capacity additions in European and Asian nodes, defending against fabless design house erosion in Shenzhen clusters. Accelerate AEC-Q100 protocol migration into smartphone supply chains to capture automotive-adjacent premium pricing. Prioritize halogen-free substrate chemistry transitions ahead of EU RoHS recast enforcement timelines to secure first-mover qualification advantages. For New Entrants and Emerging Players: Anchor in India PLI scheme electronics manufacturing incentives, targeting captive packaging and test capacity for mobile phone assembly ecosystems. Exploit sensor fusion convergence white space in unified audio-haptic-proximity subsystems where analog-digital co-design expertise concentrates among senior designers. Pursue direct-to-OEM distribution models that compress qualification timelines through foundry-direct design support partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabless houses in Shanghai and Shenzhen design clusters holding MIIT-aligned procurement relationships. Five-to-ten year viability hinges on backward integration into mixed-signal BCD process capacity or acquisition by diversified IDMs seeking geographic diversification. Monitor AEC-Q100 qualification spillover penetration rates into tier-one smartphone OEM specification documents as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Packaging Transition | EU REACH compliance secures European consumer electronics procurement eligibility for compliant foundries. |
| Foundry-Direct Design Support | Bypassing distributors compresses qualification timelines for Shenzhen and Seoul smartphone OEMs. |
| Sensor Fusion ASIC Consolidation | Unified audio-haptic-proximity dies displace discrete functions in wearable and flagship mobile programs. |
| India PLI Scheme Capacity Buildout | Local packaging and test infrastructure captures mobile phone assembly ecosystem demand. |
| AEC-Q100 Protocol Migration | Automotive-grade qualification spillover raises capital barriers excluding mid-tier competitors. |
Study Parameters
Cross-validation between primary interviews with foundry process engineers, smartphone OEM silicon procurement managers, fabless design house technical directors, and EDA tool platform specialists anchors the qualitative findings. Secondary sources include MIIT semiconductor guideline publications, EU ECHA substance restriction databases, Taiwan Stock Exchange foundry capex disclosures, and SEC 10-K filings from diversified IDMs. Bottom-up unit economics modeling triangulates against top-down regional demand aggregation.
Sensitivity analysis across wafer supply concentration scenarios, mask cost escalation trajectories, and FPGA substitution elasticity informs the analytical framework over the projection horizon. Segmentation dimensions span product type, technology node, application vertical, and end-user procurement channel. CAGRs derive from installed base replacement cycles, content-per-device expansion in computational photography pipelines, and regional production cluster growth patterns. Foundry utilization rates and BCD process capacity expansion announcements constitute primary forecast inputs.
Material uncertainties — Taiwan Strait logistics disruptions, EU RoHS exemption timeline revisions, and China MIIT procurement guideline updates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding smartphone unit volume trajectories and wearable sensor fusion adoption curves. Practitioners should keep alternative scenarios live as gate-all-around transistor yield ramp schedules and automotive-grade qualification protocol harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
3D Integrated Circuit Market