
 Flow Meter Market | 2026-2036
Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Meter Market Analysis
Industrial water utilities are unwinding decades of reliance on mechanical meter fleets. Emerson Electric Co. leverages its Coriolis and magnetic flow platforms to anchor large municipal desalination contracts across the Middle East and North America. Siemens AG competes through integrated digital twin offerings that pair ultrasonic sensors with cloud analytics for real-time leak detection.
A flow meter measures the volume or mass rate of fluid moving through a pipe or conduit, typically achieving accuracies between 0.1% and 2.0% of reading depending on technology and installation conditions. Electromagnetic and ultrasonic variants dominate new capital expenditure because they contain no moving parts and tolerate corrosive media. Coriolis meters command premium positioning in custody-transfer oil and gas applications where mass-flow direct measurement eliminates density compensation errors. Positive displacement technology retains defensive share in residential water billing where mechanical simplicity sustains lowest lifecycle cost.
The EPA mandates flow monitoring for municipal combined sewer overflow compliance, while the EU F-Gas Regulation and MDR framework shape product material specifications and calibration traceability requirements for equipment sold into European process industries. China's GB standards and SAMR metrology certification create parallel compliance tracks for vendors accessing industrial zones. Stakeholders must weigh regional certification burden against the margin premium available in smart, digitally enabled meter architectures.
Market Dynamics
Mechanical meter obsolescence is accelerating replacement cycles across municipal water utilities and process industries, with electromagnetic and ultrasonic technologies capturing capital budgets previously allocated to positive displacement and turbine architectures.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The United States mandates higher measurement accuracy for municipal water systems, forcing utilities to upgrade aging mechanical fleets with electromagnetic units that deliver 0.1% reading precision.
- EU Green Deal Industrial Emissions Standards:Tightening discharge monitoring requirements under the EU F-Gas Regulation and MDR framework compel chemical processors to install corrosion-resistant ultrasonic meters with digital calibration traceability.
- Desalination Infrastructure Expansion:Middle Eastern utilities are procuring large-diameter magnetic flow meters for reverse osmosis feedwater monitoring, replacing differential pressure devices that foul in saline environments.
Market Restraints
- Neodymium and Rare Earth Price Volatility:Electromagnetic meter production depends on stable magnet supply, with Chinese export quotas creating input cost uncertainty for European and North American manufacturers.
- Calibration Infrastructure Concentration:SAMR-certified laboratories in China and NIST-traceable facilities in the United States dominate high-accuracy calibration services, limiting vendor flexibility in emerging markets.
- Positive Displacement Resilience:Mechanical meters retain defensive share in residential billing applications where lifecycle cost simplicity outweighs smart functionality premiums.
Strategic Opportunities
- India Smart City Mission:AMR and AMI deployment targets in Bangalore, Chennai, and Pune create demand for battery-powered ultrasonic water meters with LoRaWAN connectivity.
- Hydrogen Economy Metering:Coriolis mass flow technology adapted for high-pressure hydrogen dispensing addresses emerging requirements at German and Japanese refueling stations.
- Cloud-Analytics Convergence:Pairing ultrasonic sensors with edge computing platforms enables predictive maintenance contracts that monetize data rather than hardware alone.
Industry Challenges
- Metrology Certification Timeline:EU MDR conformity assessment and OIML R49 testing protocols extend product launch cycles by 12-18 months for new meter architectures.
- Legacy SCADA Integration Complexity:Digital twin offerings from automation vendors require custom protocol gateways to communicate with decades-old municipal control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Meter Market |
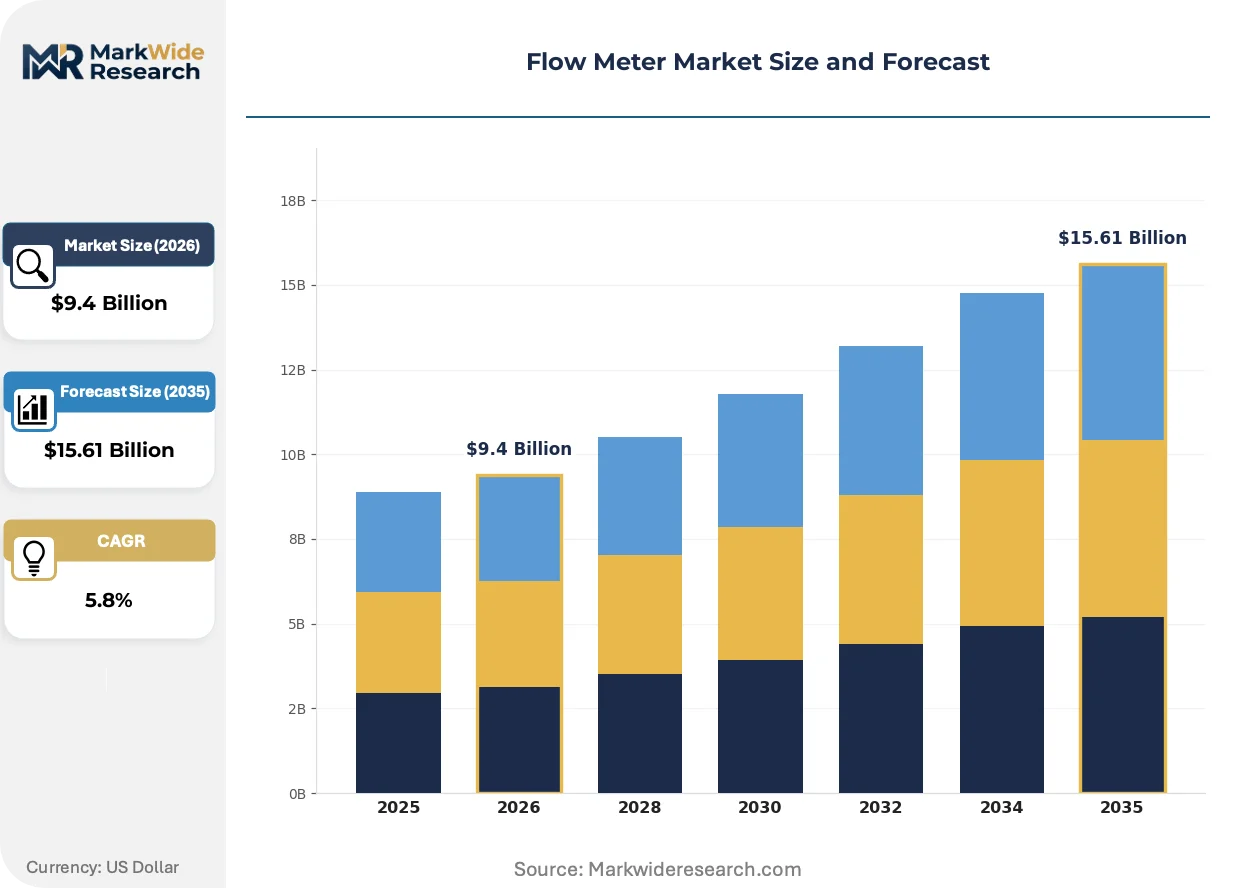
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Coriolis, Positive Displacement Technology: Analog, Digital, Smart, Mechanical End User: Water & Wastewater, Oil & Gas, Chemical, Power Generation Application: Flow Measurement, Rate Control, Tank Level Monitoring, Quality Assurance |
| Companies Covered | Emerson Electric Co., Siemens AG, ABB Ltd., Endress+Hauser, Badger Meter, Inc., Honeywell International Inc., Yokogawa Electric Corporation, KROHNE Messtechnik GmbH, Azbil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Meter Market Emerging Trajectories
Sensor miniaturization and edge computing are collapsing the cost barrier between basic mechanical meters and intelligent flow measurement systems, enabling data-driven business models that were previously confined to oil and gas custody transfer.
Clamp-on ultrasonic technology is displacing wetted-element designs in chemical and food processing applications. Pharmaceutical manufacturers in Germany and Switzerland are adopting non-invasive transit-time meters for sterile piping where contamination risk prohibits insertion devices. This shift is compressing maintenance windows and eliminating process shutdowns for sensor replacement.
The EU F-Gas Regulation and associated MDR material restrictions are reshaping meter construction specifications. Manufacturers must substitute restricted elastomers and coatings with compliant alternatives, increasing R&D expenditure but creating certification moats against non-compliant imports. Process industries in the Netherlands and Belgium are prioritizing vendors with established EU notified body relationships.
Asset-as-a-service contracting is restructuring how municipalities acquire flow measurement infrastructure. Danish and Swedish water utilities are leasing meter fleets with bundled calibration and replacement guarantees, transferring capital expenditure to operational budgets. Equipment vendors in Scandinavia are building captive financing arms to capture recurring revenue streams.
Flow Meter Market Segmentation
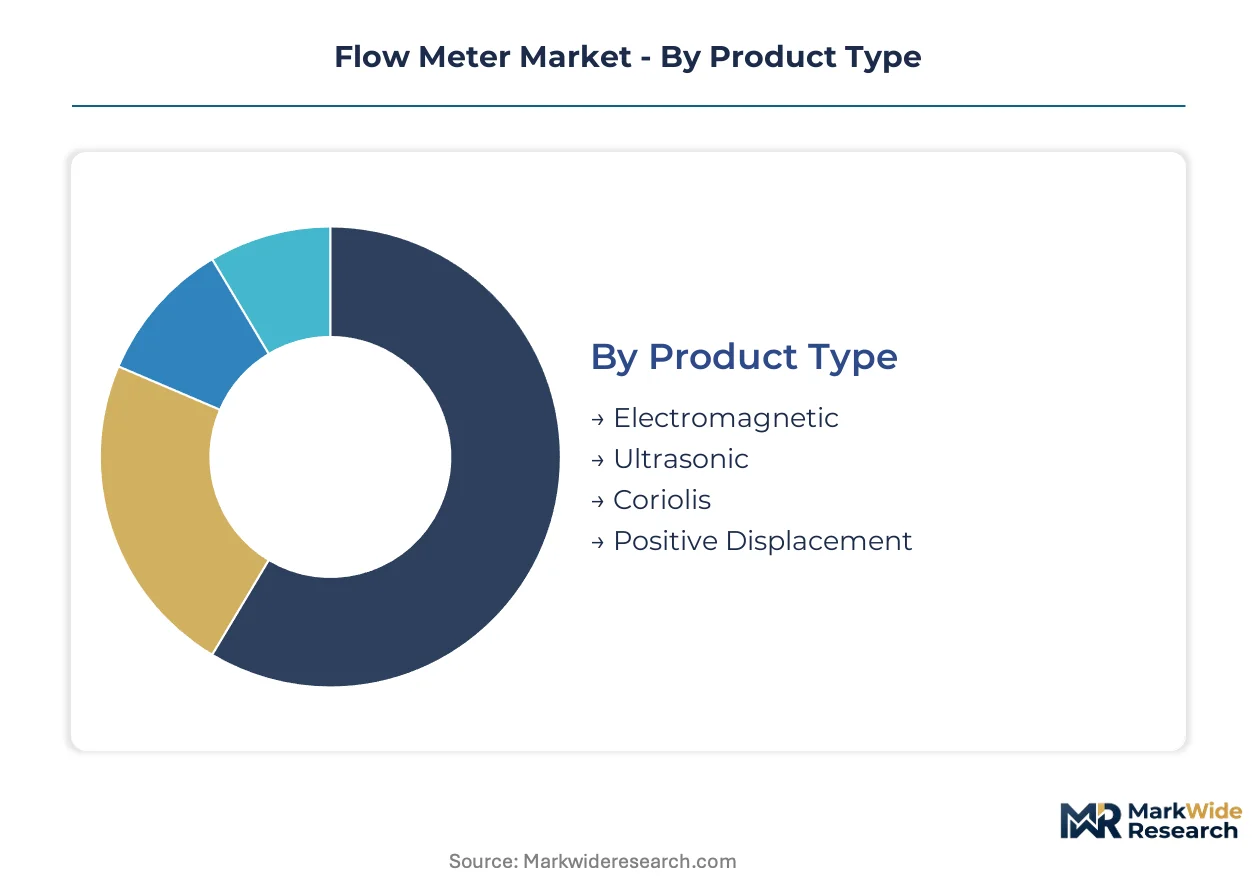
Flow meter segmentation reveals how substitution pressure from solid-state technologies is collapsing the addressable market for mechanical architectures. Technology choices now determine compliance eligibility across regulatory jurisdictions, while end-use concentration in water utilities shapes volume distribution.
Product Type:
Electromagnetic and ultrasonic variants exert mounting substitution pressure on legacy mechanical designs, with corrosion tolerance and zero-moving-part reliability driving displacement across municipal and industrial procurement cycles.
- Electromagnetic:These meters induce a magnetic field across the pipe diameter, measuring voltage proportional to fluid velocity. Water utilities in Germany and the United States are specifying electromagnetic units for EPA Lead and Copper Rule compliance, where 0.1% reading precision satisfies tightening accuracy mandates. Neodymium magnet supply concentration in China creates input cost volatility for European and North American manufacturers.
- Ultrasonic:Transit-time and Doppler variants calculate flow velocity from acoustic signal propagation differences. Clamp-on configurations are displacing wetted-element designs in pharmaceutical and food processing applications where sterile piping prohibits insertion devices. Desalination plants across the Middle East procure large-diameter ultrasonic meters for reverse osmosis feedwater monitoring.
- Coriolis:Direct mass-flow measurement eliminates density compensation errors in custody-transfer applications.
- Positive Displacement:Mechanical simplicity sustains defensive share in residential water billing where lifecycle cost outweighs smart functionality premiums.
Positive Displacement retains volume leadership in residential billing; Ultrasonic holds the steepest expansion curve across industrial retrofit cycles.
Technology:
Cost tier stratification separates premium smart architectures from legacy analog installations, with digital mid-tier offerings capturing replacement demand from municipalities seeking AMI readiness without full smart meter expenditure.
- Smart:Integrated edge computing, LoRaWAN connectivity, and cloud analytics enable predictive maintenance contracting. Danish and Swedish water utilities lease smart meter fleets with bundled calibration guarantees, transferring capital expenditure to operational budgets. Battery-powered ultrasonic smart meters serve India Smart City Mission deployment targets in Bangalore and Chennai.
- Digital:Microprocessor-based signal processing delivers improved accuracy over analog predecessors without full connectivity stacks. Municipal utilities in cost-constrained jurisdictions specify digital electromagnetic meters as a compliance-compliant intermediate step toward AMI architecture.
- Analog:Basic 4-20mA output signals persist in legacy SCADA integrations where protocol gateway costs prohibit smart meter upgrades.
- Mechanical:Turbine and paddlewheel architectures face accelerating obsolescence as electromagnetic and ultrasonic price convergence erodes their historical cost advantage.
Mechanical installations still dominate installed base counts; Smart architectures are climbing the fastest as service contracting restructures procurement economics.
End User:
Application maturity varies sharply across end-use verticals, with water and wastewater utilities driving standardized high-volume procurement while oil and gas custody transfer demands specialized certification and material specifications.
- Water & Wastewater:Municipal utilities account for the largest procurement volumes, with EPA combined sewer overflow mandates and EU Urban Wastewater Treatment Directive revisions forcing measurement infrastructure upgrades. Electromagnetic meters dominate new capital expenditure for their tolerance of raw sewage and corrosive media.
- Oil & Gas:Custody-transfer applications require OIML R49 certification and NIST-traceable calibration chains. Coriolis mass flow technology commands premium positioning where direct mass measurement eliminates compositional uncertainty in multiphase streams.
- Chemical:Process manufacturers prioritize corrosion-resistant ultrasonic meters with digital calibration traceability under EU F-Gas Regulation and MDR framework requirements.
- Power Generation:Cooling water and feedwater monitoring applications specify electromagnetic meters for their reliability in continuous-duty thermal cycles.
Water & Wastewater commands absolute volume; Chemical processing is gaining share fastest as EU emissions standards tighten discharge monitoring obligations.
Application:
Functional requirements determine sensor specification, with rate control and quality assurance applications demanding higher accuracy tiers than basic volumetric measurement.
- Flow Measurement:The foundational application spans all end-use verticals, with technology selection driven by fluid properties, pipe diameter, and accuracy requirements. Electromagnetic and ultrasonic variants are displacing differential pressure devices that foul in saline or particulate-laden streams.
- Rate Control:Closed-loop process control applications require fast response times and high repeatability. Coriolis meters serve precision chemical dosing and blending operations where mass-flow direct measurement eliminates density compensation errors.
- Tank Level Monitoring:Ultrasonic level-to-flow conversion supports inventory management in water storage and chemical tank farms.
- Quality Assurance:In-line analytical integration pairs flow measurement with conductivity, turbidity, or chemical composition sensing for real-time process validation.
Flow Measurement anchors absolute demand; Quality Assurance is expanding most quickly as pharmaceutical and food manufacturers adopt process analytical technology frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Arabian Pipeline corridor and North Sea offshore infrastructure anchor regional demand concentration for precision flow measurement systems across municipal desalination and process industry clusters.
United States
Municipal utilities in Texas and California are replacing aging mechanical meter fleets with electromagnetic units to satisfy EPA Lead and Copper Rule accuracy mandates. The EPA combined sewer overflow compliance framework forces measurement infrastructure upgrades across Great Lakes industrial corridors. Chicago and Cleveland water authorities specify 0.1% precision electromagnetic meters for raw sewage monitoring applications.
Germany
Chemical processors in the Rhine-Ruhr industrial basin prioritize corrosion-resistant ultrasonic meters with digital calibration traceability under EU F-Gas Regulation requirements. The EU MDR framework shapes product material specifications for equipment sold into European process industries. BASF and Bayer facility retrofits in Ludwigshafen and Leverkusen are driving replacement cycles for legacy differential pressure devices.
China
Industrial zone operators in Jiangsu and Zhejiang provinces require SAMR-certified calibration chains for custody-transfer applications in petrochemical complexes. GB standards and SAMR metrology certification create parallel compliance tracks for vendors accessing coastal manufacturing belts. Shanghai and Ningbo port authorities are procuring large-diameter magnetic flow meters for reverse osmosis feedwater monitoring at desalination plants.
India
AMR and AMI deployment targets under the Smart City Mission create demand for battery-powered ultrasonic water meters with LoRaWAN connectivity in Bangalore, Chennai, and Pune. The Bureau of Indian Standards (BIS) certification requirements shape product specifications for municipal procurement tenders. Maharashtra and Karnataka state water boards are accelerating electromagnetic meter adoption for non-revenue water reduction programs.
Saudi Arabia
Utilities along the Gulf coast are procuring large-diameter magnetic flow meters for reverse osmosis feedwater monitoring at Jubail and Yanbu industrial cities. The Saudi Standards, Metrology and Quality Organization (SASO) mandates calibration traceability for custody-transfer applications in oil and gas processing. NEOM development authority specifications prioritize smart meter architectures with cloud analytics integration for water distribution networks.
Flow Meter Market Vendor Landscape
Concentration sits with diversified industrial automation conglomerates that leverage integrated digital twin offerings and captive calibration infrastructure to anchor municipal and process industry contracts. The vendor base spans three strategic tiers: full-stack automation platforms with cloud-analytics convergence capabilities, specialized flow measurement pure-plays with established metrology certification relationships, and regional fabricators serving cost-constrained procurement segments. Dominant competitive moves include backward integration into neodymium magnet supply chains and geographic expansion through notified body relationships in EU member states.
Among diversified automation platforms, Emerson Electric Co. and Siemens AG exemplify the full-stack archetype that pairs sensor hardware with predictive maintenance contracting models. Yokogawa Electric Corporation occupies a position within the specialized tier, representing vendors with concentrated expertise in process industry applications. These three companies anchor the competitive structure by demonstrating how service-based revenue streams are restructuring municipal procurement economics away from capital expenditure toward operational leasing frameworks.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| ABB Ltd. |
| Endress+Hauser |
| Badger Meter, Inc. |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| KROHNE Messtechnik GmbH |
| Azbil Corporation |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet production scale in China anchors cost floors for electromagnetic meter manufacturing, concentrating upstream supply power while forcing European and North American assemblers to absorb input volatility or pursue captive magnet sourcing. This scale asymmetry shapes procurement economics across municipal utility tenders and industrial retrofit cycles.
Pricing Analysis
Volume-discount tiering structures separate OEM-direct municipal contracts from distributor-mediated industrial orders, with electromagnetic meters commanding premium positioning against ultrasonic alternatives due to neodymium input exposure. Certification grade under EU MDR and OIML R49 protocols creates price stratification between notified body-endowed vendors and regional fabricators. Cost compression in standard-tier electromagnetic units is intensifying because Chinese export quotas on rare earth elements constrain magnet supply elasticity. Municipal water utilities exhibit highest price sensitivity, while oil and gas custody-transfer buyers prioritize traceability premiums over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate neodymium procurement among European meter manufacturers, contrasting with just-in-time magnet sourcing at North American assembly plants. Magnet fabrication concentrates in China, with secondary winding and sensor assembly distributed across Germany, the United States, and Japan. Copper coil windings, fluoropolymer linings, and calibration reference standards constitute critical component dependencies. Single-source vulnerability in SAMR-certified calibration chains creates supply risk for vendors accessing Chinese industrial zones. Distribution runs through automation distributor networks for industrial accounts and direct municipal procurement channels for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility procurement consolidation across Scandinavian water authorities and Middle Eastern desalination consortia is shifting buyer power toward volume aggregators, compressing vendor margins and favoring service-contracting incumbents.
For Market Incumbents: Consolidate backward integration into neodymium magnet supply chains to insulate cost structures from Chinese export quota volatility. Deepen notified body relationships across EU member states to accelerate MDR conformity assessment timelines and defend positioning against emerging ultrasonic pure-plays. For New Entrants and Emerging Players: Predictive maintenance service gaps in legacy SCADA-integrated municipal systems present white-space opportunities for edge-computing native entrants. Target India Smart City Mission deployments in Bangalore and Chennai with battery-powered ultrasonic architectures bundled with LoRaWAN connectivity. Pursue asset-as-a-service contracting models to bypass capital expenditure barriers among cost-constrained European water utilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized flow measurement pure-plays with established metrology certification relationships over diversified automation conglomerates. Long-term viability across the projection horizon hinges on cloud-analytics convergence capabilities and recurring revenue share. Watch hydrogen economy metering adoption at German refueling stations as inflection indicator for Coriolis mass flow technology expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium sourcing insulates Emerson and Siemens from Chinese quota volatility. |
| Notified Body Relationship Expansion | Accelerated EU MDR certification timelines compress product launch cycles for Endress+Hauser. |
| Asset-as-a-Service Contracting | Danish and Swedish utilities transfer capital expenditure to operational budgets through leasing. |
| Edge Computing Platform Integration | Predictive maintenance monetization shifts revenue from hardware sales to recurring data services. |
| Hydrogen Dispensing Meter Development | Coriolis adaptation for high-pressure hydrogen addresses German and Japanese refueling requirements. |
Methodological Framework
Operator-level perspectives from municipal water utility procurement directors, chemical plant maintenance engineers, OEM instrumentation specialists, and aftermarket calibration service providers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K instrument division disclosures, EU notified body certification registers, and SAMR metrology laboratory accreditation records. Bottom-up unit shipment estimates triangulated against top-down capital expenditure tracking across desalination and process industry project databases.
Sensitivity analysis tested forecast robustness across neodymium price volatility scenarios and regulatory timeline compression assumptions. Segmentation modeling spanned product type, technology tier, end-use vertical, and application function across the analysis window. CAGRs derived from installed base replacement cycle analysis and greenfield infrastructure procurement patterns, with hydrogen economy metering and smart city connectivity serving as industry-specific demand inputs.
Material uncertainties — rare earth export policy shifts, EU MDR enforcement variance, and municipal budget cycle delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology substitution rates and certification timeline baselines. Revision becomes warranted when neodymium price volatility or regulatory compliance burden crosses thresholds that alter electromagnetic meter cost competitiveness against ultrasonic alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Metrology Software Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Calibration Services Market
Test and Measurement
LCR Meter Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Force Gauge Market