
 Cable Carrier Market | 2026-2036
Cable Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Carrier Market Outlook
Asset-light leasing models for automated production lines are reshaping how mid-sized manufacturers procure cable carrier systems. LS Cable & System leverages its integrated polymer-to-assembly infrastructure to control cost curves in energy chain production. Prysmian Group anchors European demand through specialized high-flexibility drag chains for robotics-intensive environments. Zhongtian Technology dominates domestic Chinese supply with scale advantages in plastic injection-molded carrier components.
A cable carrier is an articulated conduit system, typically constructed from segmented polymer or metal links with internal separation shelves, engineered to guide and protect moving cables, hoses, and pneumatic lines across reciprocating or rotary machine axes. Standard operating parameters span bending radii from 30 millimeters to over 500 millimeters, travel speeds exceeding 10 meters per second, and fill ratios capped at 80 percent to prevent abrasion-induced failure. Plastic material formulations currently occupy the largest volume share due to corrosion resistance and weight advantages in multi-axis robotics, while metal segments retain premium positioning in heavy-load forging and steel mill applications where thermal tolerance exceeds 150 degrees Celsius. Ceiling-mounted installations are expanding fastest in cleanroom electronics manufacturing where floor space constraints dictate overhead cable routing architecture.
The European Union's REACH regulation and Machinery Directive constrain halogenated flame retardants in polymer carriers, while China's SAMR enforces GB standards for dynamic flex testing in industrial automation equipment. Japan's METI circular economy guidelines are accelerating demand for recyclable thermoplastic elastomer formulations in replacement cycles. Stakeholders must monitor evolving regional material certifications and machine-builder procurement consolidation to align product development with specification tightening across major manufacturing jurisdictions.
Market Dynamics
Automation-intensive automotive assembly lines in Germany and Japan are expanding purchases of energy chain systems, while REACH compliance in the European Union and China's GB standards for industrial equipment are elevating material specifications across supplier portfolios.
Growth Catalysts
- REACH Regulation:The European Union's chemical safety framework constrains halogenated flame retardants in polymer carriers, forcing manufacturers toward higher-margin thermoplastic elastomer formulations that command specification premiums in robotics-intensive environments.
- Cleanroom Electronics Manufacturing:Ceiling-mounted installations are expanding fastest in this sector where floor space constraints dictate overhead cable routing architecture, creating demand for lightweight plastic carriers with integrated separation shelves.
- Yangtze River Delta Manufacturing Corridor:Demand concentrates in this Chinese industrial cluster where multi-axis robotics deployment in precision electronics and automotive component fabrication requires corrosion-resistant energy chain systems.
Market Restraints
- Steel and Aluminum Input Volatility:Metal segments retain premium positioning in heavy-load forging and steel mill applications where thermal tolerance exceeds 150 degrees Celsius, exposing producers to commodity price swings in ferrous and non-ferrous feedstocks.
- Regional Supply Concentration:China's domestic supply dominance through plastic injection-molded carrier component specialists creates sourcing vulnerability for multinational machine builders seeking qualified second-source validation.
- Fill Ratio Limitations:Standard operating parameters cap fill ratios at 80 percent to prevent abrasion-induced failure, constraining power density in compact machine designs and forcing larger carrier footprints than equipment OEMs prefer.
Strategic Opportunities
- Recyclable Thermoplastic Elastomers:Japan's METI circular economy guidelines are accelerating demand for recyclable formulations in replacement cycles, creating first-mover advantage for compounders with validated closed-loop material flows.
- Asset-Light Leasing Models:Mid-sized manufacturers are reshaping procurement through automated production line leasing, opening recurring revenue streams for cable carrier suppliers willing to bundle hardware with predictive maintenance services.
- High-Flexibility Drag Chains:Robotics-intensive environments in European automotive assembly require specialized motion-rated products, rewarding suppliers with validated dynamic flex testing protocols under Machinery Directive conformity assessment.
Industry Challenges
- Dynamic Flex Testing Certification:China's SAMR enforces GB standards for industrial automation equipment that require extensive validation timelines, compressing product launch windows for new carrier geometries.
- Legacy Pneumatic Integration:Retrofit installations in brownfield manufacturing facilities must accommodate legacy pneumatic line routing alongside modern cable bundles, complicating separation shelf configuration and bending radius optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Carrier Market |
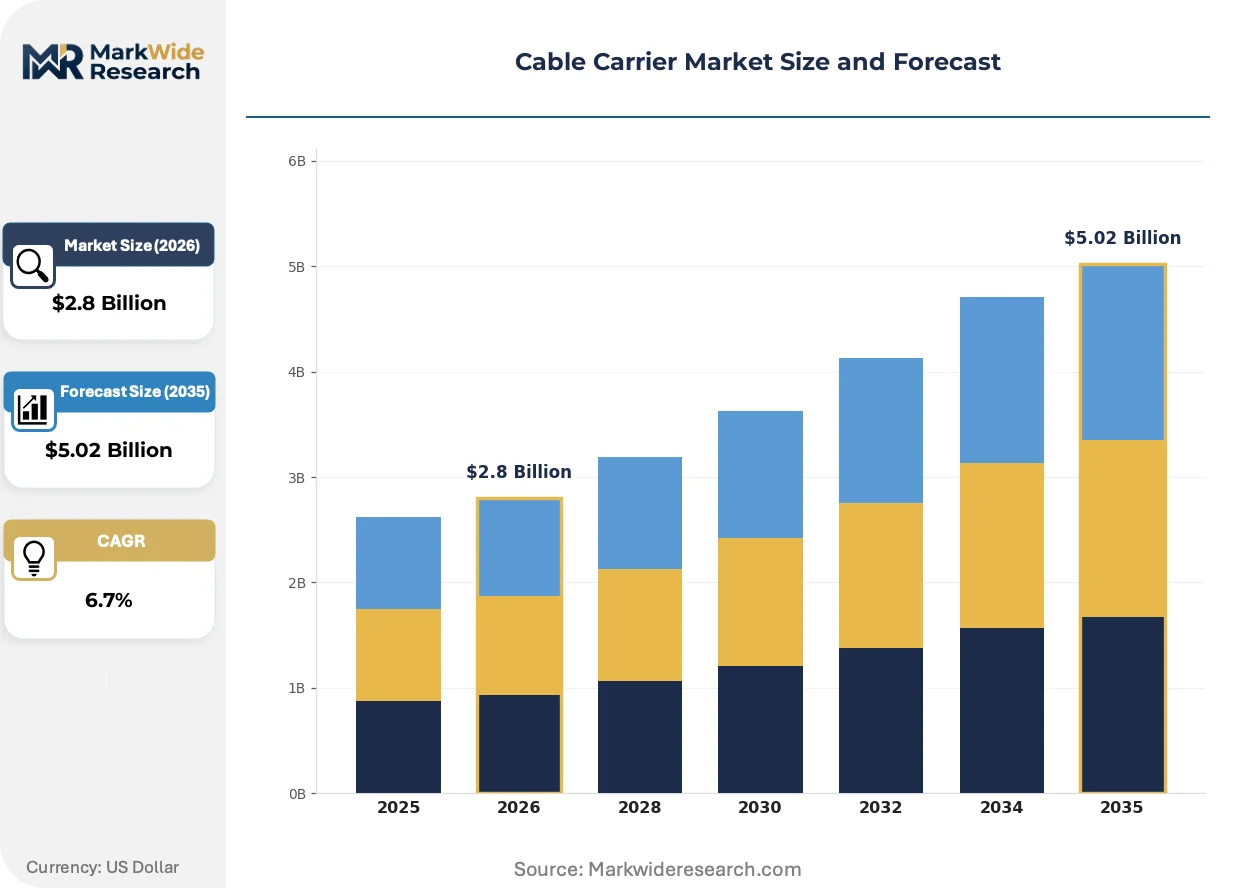
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drag Chain, Flexible Chain, Energy Chain, Lightweight Chain Installation Type: Ceiling-Mounted, Floor-Mounted, Wall-Mounted, Mobile End User: Manufacturing, Automotive, Aerospace, Telecommunications Material: Plastic, Metal, Composite, Rubber |
| Companies Covered | LS Cable & System, NKT, Prysmian Group, Zhongtian Technology, Hengtong Optoelectronics, Nexans, Southwire, CommScope, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Carrier Market Strategic Shifts
Material science advances and regulatory specification tightening are converging to reshape competitive positioning in cable carrier supply, with sustainability mandates and automation architecture evolution driving product portfolio restructuring.
Self-lubricating polymer formulations are eliminating maintenance intervals in continuous-motion applications. Automotive paint shops and semiconductor wafer handling facilities are adopting these materials to reduce downtime. The technology is migrating from niche cleanroom deployments to standard factory automation specifications, compressing the addressable market for traditional greased-metal hinge designs.
REACH compliance deadlines are accelerating substitution of brominated flame retardants with phosphorus-based and mineral alternatives. Compounders must reformulate entire product families to maintain CE marking eligibility. European robotics OEMs are responding by consolidating supplier qualification lists around partners with pre-validated halogen-free material platforms.
Machine builders are unbundling cable carrier specification from turnkey automation contracts, creating direct procurement relationships with component specialists. System integrators in Germany's automotive supply chain are disintermediating traditional distributor channels to capture engineering margin. This pattern is most visible in Bavaria and Baden-Württemberg, where mid-tier manufacturers now issue standalone RFQs for energy chain systems rather than accepting bundled subassembly pricing.
Cable Carrier Market Segmentation
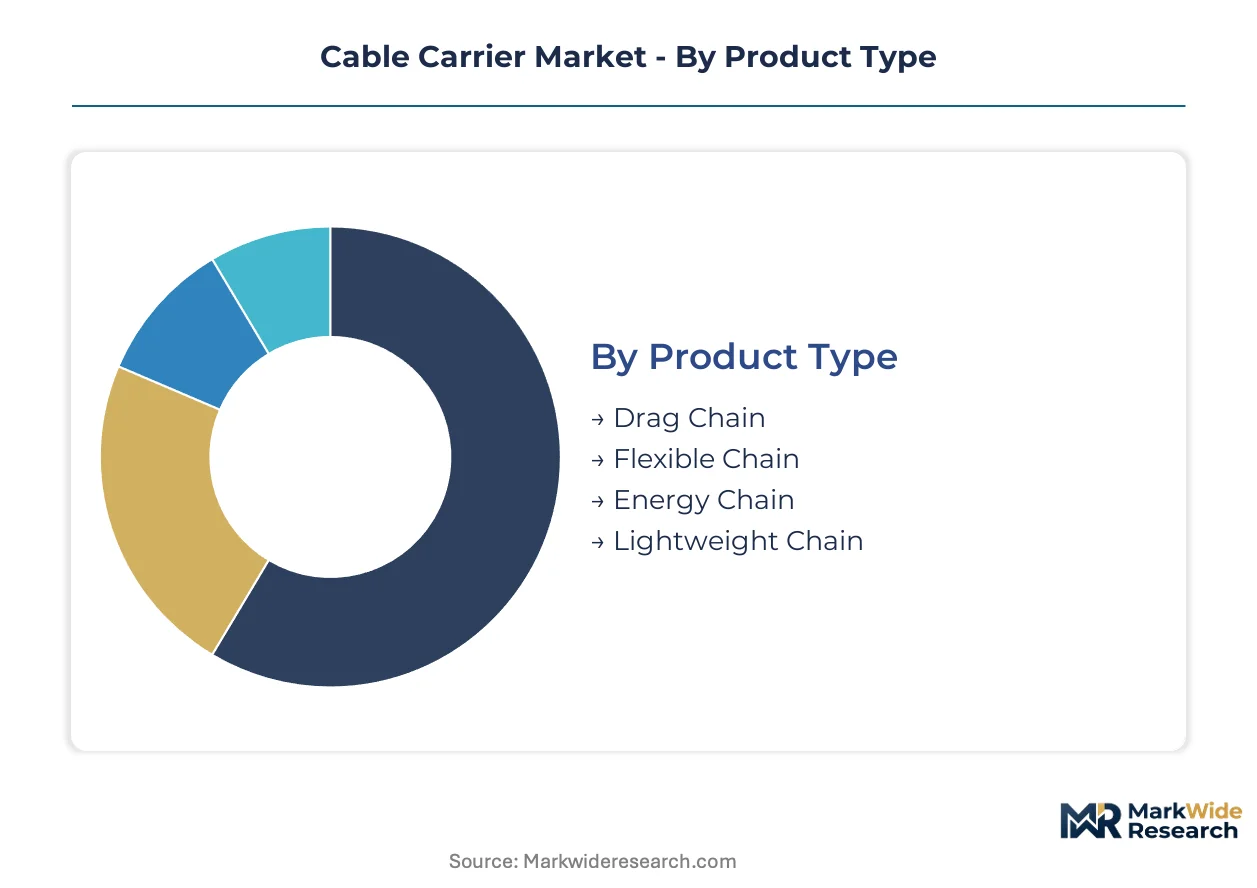
Cable carrier procurement patterns diverge sharply across application environments, installation constraints, and material performance requirements. Understanding these segment boundaries enables suppliers to align R&D investment with specification premiums and volume concentration points.
Product Type:
Cost tier differentiation separates commodity energy chains from application-engineered drag chain systems with validated dynamic flex ratings.
- Drag Chain:Articulated metal or polymer link systems engineered for reciprocating linear motion with bending radii from 30 to 500 millimeters. German automotive paint shops and Japanese semiconductor fabs specify these for continuous-duty robotics where CE marking and JIS compliance validate cycle life exceeding ten million movements.
- Energy Chain:Segmented conduit architecture with internal separation shelves for power, signal, and pneumatic line segregation. China's Yangtze River Delta manufacturing corridor concentrates demand for corrosion-resistant plastic formulations in multi-axis electronics assembly equipment.
- Flexible Chain:Reduced-pitch designs for tight bend radius applications in compact Cartesian coordinate robots.
- Lightweight Chain:Glass-reinforced polymer constructions prioritizing mass reduction in high-acceleration pick-and-place systems.
Drag chain commands the established base. The steepest expansion runs through energy chain.
Installation Type:
Application environment dictates mounting architecture, with floor space constraints and contamination exposure driving specification divergence.
- Ceiling-Mounted:Overhead routing systems with integrated suspension hardware and anti-sway stabilizers. Cleanroom electronics manufacturing in South Korea and Taiwan adopts these where floor loading restrictions and particle contamination protocols prohibit ground-level cable management.
- Floor-Mounted:Trough-style or open-channel designs for heavy-load forging and steel mill applications where thermal tolerance must exceed 150 degrees Celsius. Metal segments retain premium positioning here despite commodity price volatility in ferrous feedstocks.
- Wall-Mounted:Vertical plane routing for gantry systems and material handling conveyors in warehouse automation.
- Mobile:Portable cable carrier carts for temporary production line reconfiguration and maintenance access platforms.
Floor-mounted retains volume leadership in heavy industry. Ceiling-mounted gains share fastest in precision manufacturing.
End User:
Customer type determines performance certification requirements and replacement cycle economics, with automotive and aerospace commanding qualification premiums.
- Automotive:Paint shop automation and body-in-white welding cells specify halogen-free thermoplastic elastomers meeting REACH flame retardant constraints. German OEMs in Bavaria and Baden-Württemberg unbundle cable carrier procurement from turnkey automation contracts to capture direct engineering margin.
- Manufacturing:General factory automation spanning packaging machinery, injection molding, and material handling. This segment absorbs standardized plastic carrier volumes with shorter qualification timelines and price-sensitive tender processes.
- Aerospace:FAA and EASA certification requirements for flame resistance and outgassing properties in cabin and cargo systems.
- Telecommunications:Data center cable management and 5G infrastructure deployment with emphasis on electromagnetic interference shielding.
Manufacturing provides the volume foundation. Automotive delivers the steepest specification premium expansion.
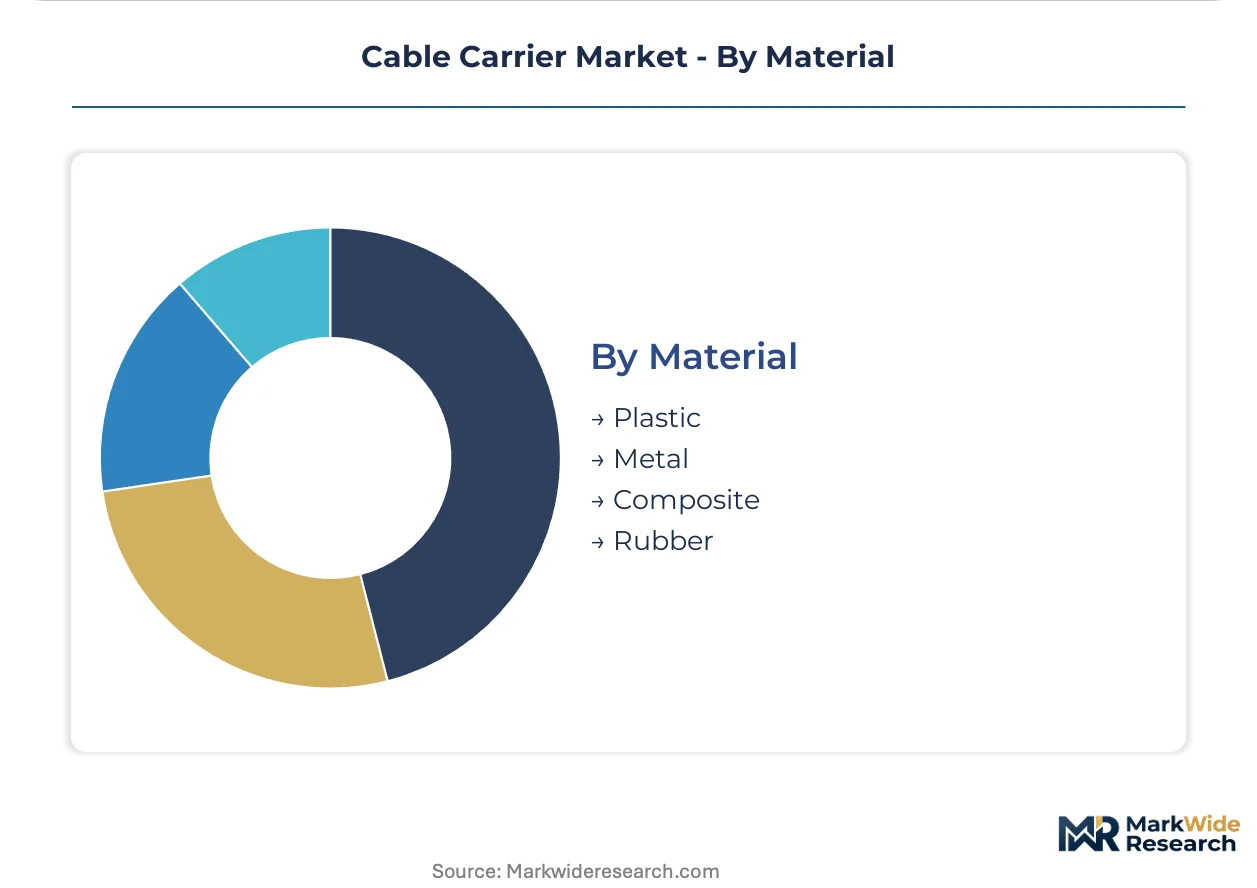
Material:
Volume concentration and margin structure split between corrosion-resistant polymers and thermally tolerant metals, with sustainability mandates accelerating formulation turnover.
- Plastic:Injection-molded nylon, polypropylene, and thermoplastic elastomer compounds dominating multi-axis robotics. REACH compliance deadlines force substitution of brominated flame retardants with phosphorus-based alternatives, compressing compounder qualification timelines.
- Metal:Steel and aluminum link constructions for heavy-load applications exceeding 150 degrees Celsius. Steel mill and forging equipment in Germany and Japan specify these despite input cost volatility.
- Composite:Hybrid polymer-metal architectures balancing weight and load capacity in aerospace and high-speed automation.
- Rubber:Molded elastomer channels for vibration-dampening and flexible hose protection in mobile hydraulic systems.
Plastic holds the installed base. Composite formulations climb fastest on aerospace and robotics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cable carrier systems reveal Germany and Japan as net technology exporters while China absorbs the largest import volumes for domestic automation buildout. Trade flows concentrate around specialized drag chain assemblies for robotics-intensive manufacturing environments.
Germany
Automotive paint shops in Bavaria and Baden-Württemberg unbundle cable carrier procurement from turnkey automation contracts to capture direct engineering margin. REACH regulation constrains halogenated flame retardants in polymer formulations, elevating specification premiums for thermoplastic elastomer alternatives. Stuttgart's robotics cluster drives demand for high-flexibility drag chains with CE-marked cycle life validation.
China
SAMR enforces GB standards for dynamic flex testing that compress product launch timelines for new carrier geometries. The Yangtze River Delta manufacturing corridor concentrates demand for corrosion-resistant plastic energy chains in multi-axis electronics assembly equipment. Shanghai and Suzhou-based machine builders source injection-molded carrier components from domestic compounders with validated halogen-free platforms.
Japan
METI circular economy guidelines accelerate replacement cycle demand for recyclable thermoplastic elastomer formulations. Semiconductor wafer handling facilities in the Chubu region adopt self-lubricating polymer carriers to eliminate maintenance intervals. Nagoya's automotive supply chain specifies JIS-compliant drag chains for continuous-duty robotics exceeding ten million movement cycles.
United States
OSHA workplace safety standards and FCC electromagnetic compatibility requirements shape procurement specifications for factory automation equipment. The Southeast manufacturing belt spanning Georgia and Tennessee expands automotive assembly capacity requiring energy chain systems for body-in-white welding cells. Detroit-area OEMs source specialized carriers for heavy-load forging applications where thermal tolerance exceeds 150 degrees Celsius.
South Korea
MFDS and national industrial safety frameworks align with ISO standards for dynamic cable management in cleanroom environments. Ceiling-mounted installations dominate Seoul Capital Area electronics manufacturing where floor loading restrictions prohibit ground-level cable routing. Busan-Ulsan shipbuilding and automotive clusters specify lightweight plastic carriers with integrated separation shelves for pneumatic line segregation.
Cable Carrier Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers: integrated polymer-to-assembly specialists, component-scale injection molders, and application-engineered system providers. Strategic archetypes include backward-integrated cable manufacturers diversifying into carrier hardware, captive automotive suppliers with validated OEM qualification protocols, and independent energy chain specialists with robotics-focused R&D programs. Dominant competitive moves encompass geographic expansion into China's Yangtze River Delta manufacturing corridor and portfolio diversification toward recyclable thermoplastic elastomer formulations compliant with Japan's circular economy mandates.
Within the integrated cable-to-carrier tier, LS Cable & System and Prysmian Group exemplify backward-integrated positioning that captures cost advantages across polymer compounding through final assembly. Zhongtian Technology occupies a scale-driven position among Chinese injection-molded component specialists serving domestic automation demand. These three anchors illustrate how supply-side configuration splits between European specification-led engineering and Asian volume manufacturing.
| Leading Market Players |
|---|
| LS Cable & System |
| NKT |
| Prysmian Group |
| Zhongtian Technology |
| Hengtong Optoelectronics |
| Nexans |
| Southwire |
| CommScope |
| Sumitomo Electric Industries |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European polymer compounding facilities is tightening supplier discipline and elevating specification premiums for REACH-compliant thermoplastic elastomer formulations. German automotive OEMs now face extended lead times for halogen-free carrier systems, forcing procurement teams toward contract-based pricing structures that lock in compounder allocation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CE marking validation and volume scale, with robotics-certified drag chains commanding substantial premiums over general factory automation specifications. Cost compression in standard-grade plastic carriers is intensifying because Chinese injection molders are expanding capacity in the Yangtze River Delta. Tier 1 automotive suppliers exhibit the lowest price sensitivity due to qualification lock-in, while mid-sized packaging machinery builders drive the most aggressive tender processes.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for multinational machine builders. Manufacturing concentrates in China, Germany, and Japan, with polymer compounding anchored in the Rhine-Ruhr industrial region and precision metalworking centered in Nagoya. Raw material dependencies include glass-reinforced nylon pellets, aluminum extrusion billets, and phosphorus-based flame retardant additives. Single-source vulnerability persists for halogen-free compound formulations validated under REACH. Distribution runs through specialized industrial distributors in Bavaria and Baden-Württemberg, with direct procurement relationships displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between cable carrier systems and predictive maintenance platforms is creating platform-economics dynamics where hardware margins collapse into service revenue streams. Machine builders unbundling component procurement from turnkey contracts are accelerating this shift.
For Market Incumbents: Harden qualification protocols against emerging Chinese compounders with pre-validated halogen-free material platforms. Defensive consolidation through captive polymer compounding in the Rhine-Ruhr region secures REACH compliance margins. Threat substitution from self-lubricating polymer formulations eliminating maintenance intervals demands accelerated R&D in continuous-motion rated products. For New Entrants and Emerging Players: Pursue white-space opportunities in asset-light leasing models for mid-sized manufacturers seeking bundled hardware-with-service procurement. The most penetrable segment spans South Korean cleanroom electronics manufacturing, where ceiling-mounted installations face limited qualified supplier competition. A direct sales model targeting Seoul Capital Area system integrators bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with closed-loop recyclable thermoplastic elastomer flows aligned to Japan's METI circular economy guidelines. Long-term viability favors backward-integrated specialists controlling polymer formulation through final assembly. The signal to watch is procurement unbundling velocity in German automotive supply chains, where direct RFQ issuance for energy chain systems indicates tipping-point adoption of platform-based supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH compliance deadlines reward compounders with validated halogen-free platforms in European robotics supply chains. |
| Predictive Maintenance Service Bundling | Asset-light leasing models open recurring revenue streams with mid-sized manufacturers in China's Yangtze River Delta. |
| Recyclable Formulation Development | METI circular economy guidelines in Japan accelerate replacement demand for closed-loop thermoplastic elastomer systems. |
| Ceiling-Mounted Product Line Expansion | Cleanroom electronics manufacturing in South Korea and Taiwan constrains floor space and mandates overhead routing architecture. |
| Dynamic Flex Testing Certification Investment | SAMR GB standards in China compress launch timelines and reward suppliers with pre-validated protocols. |
Study Parameters
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and polymer compounder technical directors anchors the qualitative findings. Secondary sources include customs trade data for energy chain system imports, SEC filings from backward-integrated cable manufacturers, SAMR GB standard documentation, and REACH compliance registries. Bottom-up segmentation modeling triangulates against top-down industry consumption estimates derived from automotive production and electronics assembly capacity data.
Calibration against historical shipment volumes and installed base replacement cycles shapes the analytical framework across the analysis window. Segmentation dimensions span product type, installation architecture, end-use industry, material formulation, and regional regulatory cluster. CAGRs derive from slope-log regression on normalized adoption curves, with specific inputs including multi-axis robotics deployment rates in precision electronics assembly and thermal tolerance requirements in heavy-load forging applications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese injection-molded component specialists or European compounders with recyclable platform launches would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Asia-Pacific Cable Joints Market
Cables
Multicore Cables Market
Cables
Aluminium Battery Cable Market
Cables
Cable Testers Market
Cables
Cable Tray Market
Cables
Instrumentation Cables Market
Cables
LED Cable Market
Cables
Cable Testing and Certification Market
Cables
Usb Data Cable Market
Cables
Global Industrial Automation Cable Market
Cables
Flat Flexible Cables Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Audio and Video Cables Market
Cables
Europe Wire and Cable Market
Cables
Network Cable Tester Market
Cables
Active Optical Cable Market