
 DSL Tester Market | 2026-2036
DSL Tester Market Size, Share, and Industry Trends Forecast 2026-2036
DSL Tester Market Analysis
The DSL tester market is decoupling into premium calibration-grade instruments and commodity installation tools. EXFO Inc. leverages its optical test heritage to dominate high-accuracy VDSL2 verification systems. Keysight Technologies Inc. anchors its position through R&D intensity in vector signal analysis for G.fast vectoring compliance. Viavi Solutions Inc. competes aggressively on handheld form factors tailored for field technician productivity.
A DSL tester is an electronic instrument that measures line impedance, insertion loss, noise margin, and sync rates across copper twisted-pair infrastructure, typically operating from 25 kHz to 212 MHz for G.fast compatibility and generating bit-loading profiles to qualify subscriber loops for service activation. Handheld testers occupy the highest volume tier due to technician mobility requirements, while modular testers capture margin pools in central office and lab environments where swap-out flexibility reduces capital redundancy. G.fast technology segments are expanding fastest as operators leverage existing copper for gigabit delivery, whereas ADSL applications have matured into replacement-cycle purchasing with compressed margins.
The Federal Communications Commission's broadband mapping mandates shape US operator investment in line-quality verification tools, while ETSI and ITU-T standards govern European G.fast interoperability testing and Asian markets follow region-specific spectrum allocation rules from national telecom regulators. Stakeholders must monitor spectrum refarming decisions that could obsolete current tester frequency ranges before equipment depreciation cycles conclude.
Market Dynamics
The DSL tester market is bifurcating under pressure from copper-to-fiber migration timelines and G.fast certification mandates, forcing manufacturers to recalibrate R&D spending toward vectoring compliance while maintaining legacy VDSL2 support for rural deployment cycles.
Growth Catalysts
- BharatNet rural broadband mandates:India's phased village connectivity targets sustain procurement of handheld field instruments for copper-loop verification across 250,000 gram panchayats.
- ETSI TS 101 376-5-1 standardization:European G.fast interoperability testing requirements elevate instrument complexity and replacement frequency in operator labs.
- Copper-loop life extension:Telecommunication operators in Indonesia and Vietnam leverage existing twisted-pair infrastructure for gigabit service trials, preserving tester demand.
Market Restraints
- Semiconductor input volatility:FPGA and high-speed ADC supply constraints from Taiwan-based foundries compress gross margins on modular tester platforms.
- Fiber substitution acceleration:GPON and XGS-PON deployment in urban China and South Korea reduces addressable copper-verification volumes.
- ITU-T G.9701 certification friction:Extended validation timelines for G.fast vectoring compliance delay product launches and freeze procurement budgets.
Strategic Opportunities
- African underpenetration:Nigeria and Kenya's national broadband plans retain copper as a transitional medium, opening field-tester demand.
- 5G fronthaul convergence:Integration of DSL loop qualification with CPRI fiber testing creates bundled instrument opportunities.
- Cloud-based test orchestration:Remote firmware updates and centralized result databases enable subscription revenue models for instrument vendors.
Industry Challenges
- RF engineering talent scarcity:Vector signal analysis expertise for 212 MHz G.fast characterization remains concentrated in Germany and Japan.
- Legacy system integration:New testers must interface with OSS/BSS platforms deployed during ADSL-era buildouts without disrupting service activation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DSL Tester Market |
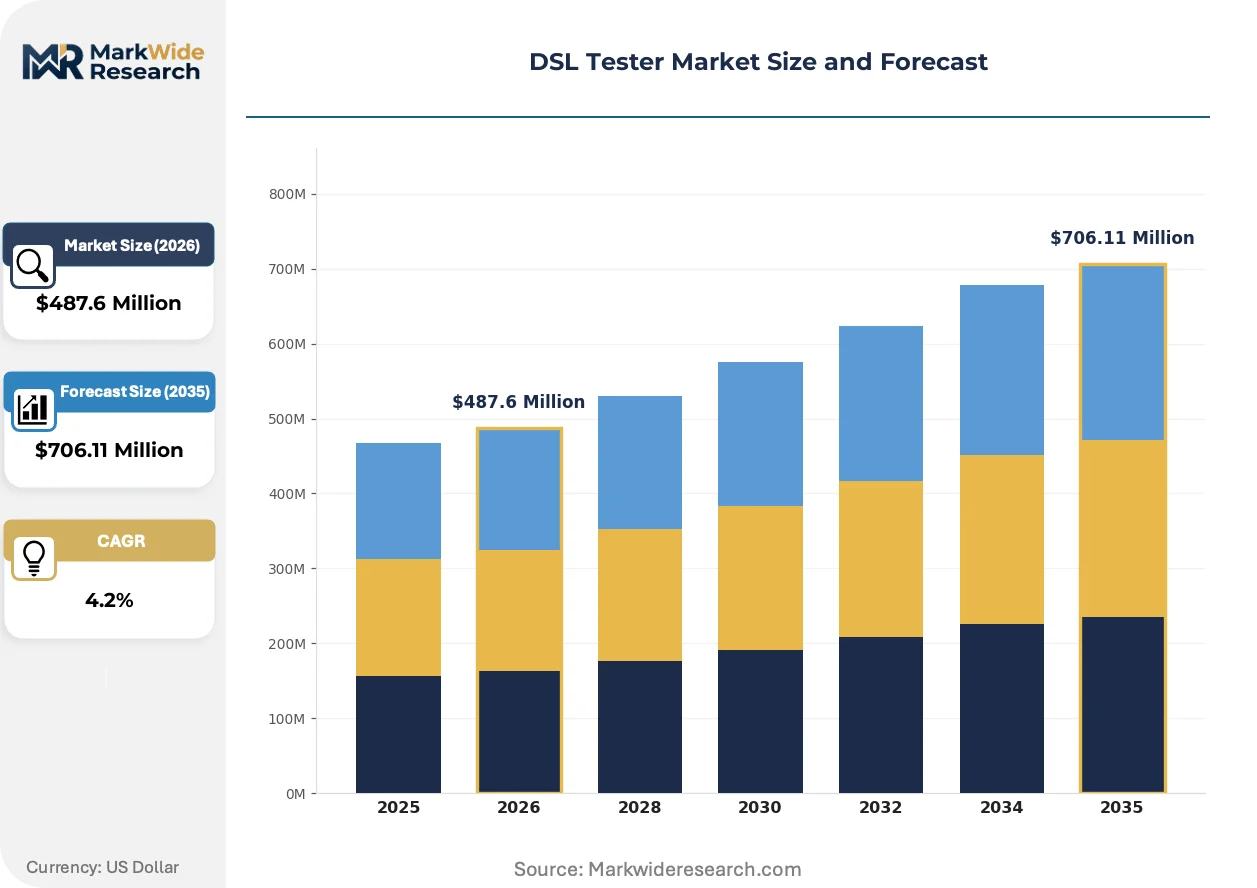
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Testers, Desktop Testers, Portable Testers, Modular Testers Technology: ADSL, VDSL, SDSL, G.fast, SHDSL Application: Network Installation, Fault Detection, Performance Monitoring, Maintenance, Quality Assurance End User: Telecommunication Operators, Network Maintenance Providers, Internet Service Providers, Equipment Manufacturers |
| Companies Covered | EXFO Inc., Keysight Technologies Inc., Viavi Solutions Inc., Rohde & Schwarz, Anritsu Corporation, Spirent Communications, Emerson Electric, ARGUS, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DSL Tester Market Emerging Trajectories
Software-defined measurement architectures are displacing fixed-function hardware, enabling field instruments to absorb new test protocols through firmware rather than physical replacement. This shift compresses capital cycles and elevates recurring revenue from calibration and feature licensing.
Multi-gigabit copper validation is decentralizing test execution from central offices to distribution points. Field technicians in Deutsche Telekom and Orange networks now perform G.fast loop qualification at street cabinets using battery-powered handheld units. This migration reduces truck rolls but demands ruggedized instruments with extended temperature tolerances.
The FCC's broadband data collection mandates are reshaping US operator investment in line-quality documentation tools. Carriers must submit geocoded serviceability metrics, requiring testers with GPS integration and automated reporting formats. Rural electric cooperatives entering broadband provision represent the fastest-adopting buyer segment.
Certification-driven procurement is tightening vendor qualification windows. Telecommunication operators now require pre-approval of test equipment against internal performance benchmarks before volume purchase authorization. This behavior concentrates demand among incumbent suppliers with established calibration traceability and compresses opportunities for new market entrants.
DSL Tester Market Segmentation
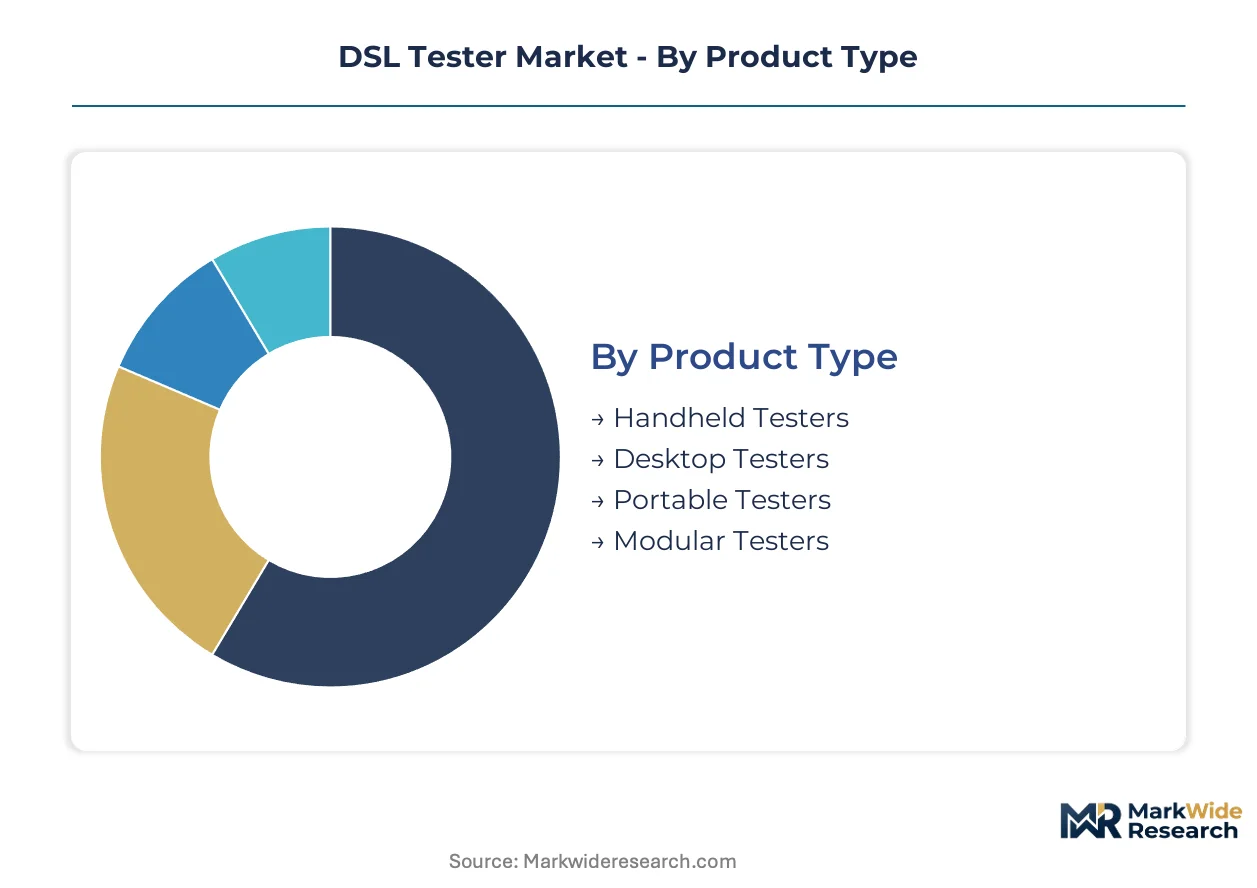
DSL tester segmentation reflects the tension between field mobility requirements and lab-grade precision. Procurement patterns diverge sharply across product architectures, legacy versus next-generation technologies, and the operational priorities of distinct buyer types.
Product Type:
Customization spans ruggedized handheld units for pole-climbing technicians to rack-mount modular systems with hot-swappable measurement cards.
- Handheld Testers:Battery-powered instruments with touchscreen interfaces dominate field technician fleets. Demand concentrates in India's BharatNet deployment, where gram panchayat connectivity targets require lightweight verification tools for rural copper loops.
- Modular Testers:Chassis-based platforms accept interchangeable test heads for ADSL through G.fast characterization. European operator labs under ETSI certification mandates drive replacement cycles as vectoring complexity escalates.
- Desktop Testers:Fixed-location instruments for central office environments with AC power dependency and higher measurement accuracy.
- Portable Testers:Intermediate form factors bridging handheld mobility and desktop performance for regional service centers.
Leading the category by volume: Handheld Testers. Growing fastest: Modular Testers.
Technology:
Technology tiers trace the copper infrastructure lifecycle from mature ADSL deployments to gigabit-capable G.fast vectoring.
- G.fast:212 MHz spectrum utilization enables gigabit speeds over existing twisted-pair infrastructure. Deutsche Telekom and Orange networks are deploying loop qualification at street cabinets, requiring handheld units with extended temperature tolerances.
- VDSL:30 MHz and 17 MHz profile support remains the workhorse for fiber-to-the-cabinet architectures. Indonesian and Vietnamese operators leverage VDSL2 for suburban gigabit trials, sustaining instrument demand amid fiber substitution in urban cores.
- ADSL:Legacy 2.2 MHz systems persist in replacement-cycle purchasing with compressed margins.
- SHDSL:Symmetric high-bit-rate digital subscriber line serves enterprise leased-line applications.
- SDSL:Single-pair symmetric deployment for small business connectivity.
Volume leadership: VDSL. Steepest expansion trajectory: G.fast.
Application:
Application segmentation maps to distinct operational phases in copper network lifecycle management.
- Network Installation:Loop qualification and service activation workflows require pre-deployment verification against bit-loading profiles.
- Fault Detection:Impulse noise and bridge tap identification for troubleshooting subscriber complaints.
- Performance Monitoring:Continuous sync rate and margin tracking for SLA compliance.
- Maintenance:Preventive line conditioning and pair remediation scheduling.
- Quality Assurance:Certification testing against ETSI and ITU-T benchmarks before network handover.
Highest procurement frequency: Network Installation. Fastest-growing requirement: Quality Assurance.
End User:
Buyer types exhibit divergent technical specifications and procurement authority structures.
- Telecommunication Operators:Incumbent carriers with centralized test equipment standardization and volume purchasing leverage. FCC broadband mapping mandates in the US are reshaping investment in GPS-integrated documentation tools.
- Internet Service Providers:Competitive carriers and rural electric cooperatives entering broadband provision represent the fastest-adopting buyer segment for automated reporting formats.
- Network Maintenance Providers:Contract field services with fleet standardization constraints and technician productivity metrics.
- Equipment Manufacturers:DSLAM and CPE vendors requiring pre-shipment line card verification.
Category volume leader: Telecommunication Operators. Fastest-expanding segment: Internet Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's telecom equipment corridors anchor India's DSL tester procurement, with BharatNet rural broadband mandates sustaining field instrument demand across 250,000 gram panchayats. The city's integration with domestic manufacturing zones and TRAI spectrum allocation frameworks positions it as the dominant demand center for handheld verification tools.
United States
Rural electric cooperatives entering broadband provision represent the fastest-adopting buyer segment for GPS-integrated documentation tools. FCC broadband mapping mandates reshape operator investment in automated reporting formats. Dallas-Fort Worth telecom corridors concentrate procurement for central office modular systems.
Germany
Deutsche Telekom networks deploy G.fast loop qualification at street cabinets using battery-powered handheld units. ETSI TS 101 376-5-1 standardization elevates instrument complexity in operator labs. Munich engineering clusters anchor vector signal analysis expertise for 212 MHz characterization.
China
GPON and XGS-PON deployment in urban cores reduces addressable copper-verification volumes, sustaining demand in suburban transition zones. MIIT spectrum allocation rules govern regional interoperability testing. Shenzhen manufacturing basins supply FPGA components for modular tester platforms.
Indonesia
Operators leverage existing twisted-pair infrastructure for gigabit service trials, preserving field-tester demand amid fiber substitution in Jakarta. National telecom regulators enforce region-specific spectrum allocation frameworks. Surabaya distribution corridors concentrate technician fleet standardization programs.
DSL Tester Market Vendor Landscape
Premium-margin players sit above commodity-margin players across calibration-grade precision and field-installation tool tiers. The vendor base stratifies between optical test heritage specialists and vector signal analysis incumbents. Three archetypes dominate: certification-lab instrument providers, ruggedized handheld manufacturers, and modular platform integrators. Competitive moves concentrate on strategic partnerships for 5G fronthaul convergence and portfolio diversification into cloud-based test orchestration.
Within the certification-lab tier, EXFO Inc. and Keysight Technologies Inc. exemplify premium-margin positioning through established calibration traceability. Viavi Solutions Inc. occupies a position among handheld specialists emphasizing technician productivity form factors. These three entities collectively represent the incumbent supplier concentration that certification-driven procurement behavior favors.
| Leading Market Players |
|---|
| EXFO Inc. |
| Keysight Technologies Inc. |
| Viavi Solutions Inc. |
| Rohde & Schwarz |
| Anritsu Corporation |
| Spirent Communications |
| Emerson Electric |
| ARGUS |
| 3M |
| Others |
Supply Flow & Price Mechanics
RF engineering talent scarcity in Munich and Bengaluru clusters shapes labor-cost differentials across calibration-grade versus field-installation tiers. Pricing spreads widen where vector signal analysis expertise concentrates, compressing margins on commodity handheld units sourced from lower-skill assembly regions.
Pricing Analysis
Certification-grade accuracy serves as the dominant value-based pricing anchor, with ETSI TS 101 376-5-1 compliance commanding substantial premiums over installation-only instruments. Three-tier pricing structure across premium, standard, and economy levels separates lab-grade modular systems from ruggedized handheld units and basic loop qualification tools. Price differentiation hinges on calibration traceability and vectoring protocol support, with rural electric cooperatives exhibiting highest price sensitivity and European incumbent operators least sensitive due to regulatory compliance mandates. Cost compression in handheld tiers is intensifying because FPGA supply constraints from Taiwan-based foundries squeeze component availability.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dallas-Fort Worth, and Munich anchor hub-and-spoke fulfillment patterns for modular tester platforms and field instrument fleets. Manufacturing concentrates in China for PCB assembly and FPGA integration, Germany for precision RF front-ends, and India for technician-grade handheld final assembly. Raw material dependencies span high-speed ADCs from Japanese suppliers, ruggedized touchscreen displays from South Korean producers, and lithium battery cells from Chinese manufacturers. Single-source vulnerability in Taiwan-based semiconductor foundries presents structural risk. Distribution runs through operator-direct procurement for lab systems and tiered distributor networks for field technician fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-driven procurement behavior is forcing consolidation as smaller vendors lack calibration traceability infrastructure for ETSI and ITU-T pre-approval requirements.
For Market Incumbents: To counter FPGA supply bottlenecks from Taiwan-based foundries, secure long-term component offtake agreements and diversify sourcing to Japanese ADC suppliers. Deepen backward integration into RF front-end manufacturing through Munich engineering cluster partnerships to defend margin position against modular platform competitors. For New Entrants and Emerging Players: Rural electric cooperatives entering US broadband provision represent an underserved buyer archetype with limited vendor relationships and urgent GPS-integrated documentation needs. Penetrate this segment through cloud-based test orchestration subscriptions bundled with ruggedized handheld units, bypassing centralized procurement gates that favor established calibration-grade suppliers. For Investors and Strategic Acquirers: The window for entry favors specialists with vector signal analysis IP and existing ETSI certification relationships. Acquisition targets should demonstrate firmware-upgradeable architectures and established technician fleet deployments. Watch G.fast vectoring compliance validation timelines as the critical inflection signal—extended ITU-T G.9701 approval delays freeze procurement budgets and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Test Orchestration | Enables subscription revenue models for Viavi and EXFO through remote firmware deployment. |
| G.fast Vectoring Compliance Investment | Keysight and Rohde & Schwarz anchor premium positioning through 212 MHz characterization expertise. |
| 5G Fronthaul Convergence | Creates bundled instrument opportunities combining DSL loop qualification with CPRI fiber testing. |
| Rural Electric Cooperative Channel Development | Opens fastest-adopting buyer segment for GPS-integrated documentation tools under FCC mandates. |
| Semiconductor Supply Diversification | Mitigates Taiwan foundry concentration risk through Japanese ADC and South Korean display sourcing. |
Methodological Framework
Regulatory filings from the FCC, ETSI standards documentation, and ITU-T recommendation archives formed the secondary backbone for compliance requirement mapping. Primary interviews with field technician fleet managers, central office test engineers, and telecommunications procurement officers validated instrument specification trends. SEC 10-K disclosures from EXFO, Keysight, and Viavi provided revenue segmentation proxies. Bottom-up modeling of BharatNet deployment schedules and top-down triangulation against European operator capex patterns anchored volume estimates.
Historical trendline analysis traced replacement cycles from ADSL-era buildouts through VDSL2 maturation and G.fast vectoring adoption curves. Segmentation dimensions modeled include product architecture, technology tier, application phase, and end-user procurement authority structure. CAGRs derived from equipment depreciation cycles and certification mandate timelines. Forecast inputs incorporated FPGA supply lead times and rural broadband subsidy program allocations.
Revisions become necessary when spectrum refarming decisions or semiconductor trade restrictions materialize outside baseline assumptions. Forecasts reflect documented expectations regarding G.fast deployment velocity and copper-loop life extension economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Color Meter Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Curve Tracer Market