
 Windows and Doors Market | 2026-2036
Windows and Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Windows and Doors Market Analysis
Skilled glazing technician availability is bifurcating the market into regions with certified installer networks and areas facing labor shortages that delay project timelines. Andersen Windows & Doors leverages its certified contractor program to control channel quality across North American markets. JELD-WEN anchors its competitive position through backward integration into vinyl extrusion and fiberglass pultrusion operations. Pella Corporation differentiates via its proprietary impervia fiberglass line and design-focused retail showrooms.
Windows and doors are engineered building envelope components fabricated from vinyl extrusions, thermally broken aluminum profiles, laminated wood cores, or pultruded fiberglass, assembled with insulated glazing units to control heat transfer, air infiltration, and structural loads. Primary industrial purpose centers on maintaining thermal boundaries in conditioned spaces while permitting controlled daylighting and emergency egress. The material dimension shows fiberglass capturing premium specification share for coastal and cold-climate applications, while vinyl sustains volume leadership in residential replacement due to cost-position and minimal maintenance requirements. Installation type dynamics reveal replacement and remodeling outpacing new construction in mature housing markets, with DIY channels expanding through pre-hung door and insert window formats.
EPA Energy Star certification and NFRC performance labeling govern product eligibility for federal tax credits and utility rebate programs in the United States. The EU Green Deal and national building renovation passports in France and Germany mandate step-change improvements in U-factor and solar heat gain coefficients for replacement installations. Stakeholders must monitor evolving code cycles in California's Title 24 and Florida's HVHZ wind-borne debris requirements, as these jurisdictions typically prefigure standards that propagate through ASHRAE and ICC model code adoptions.
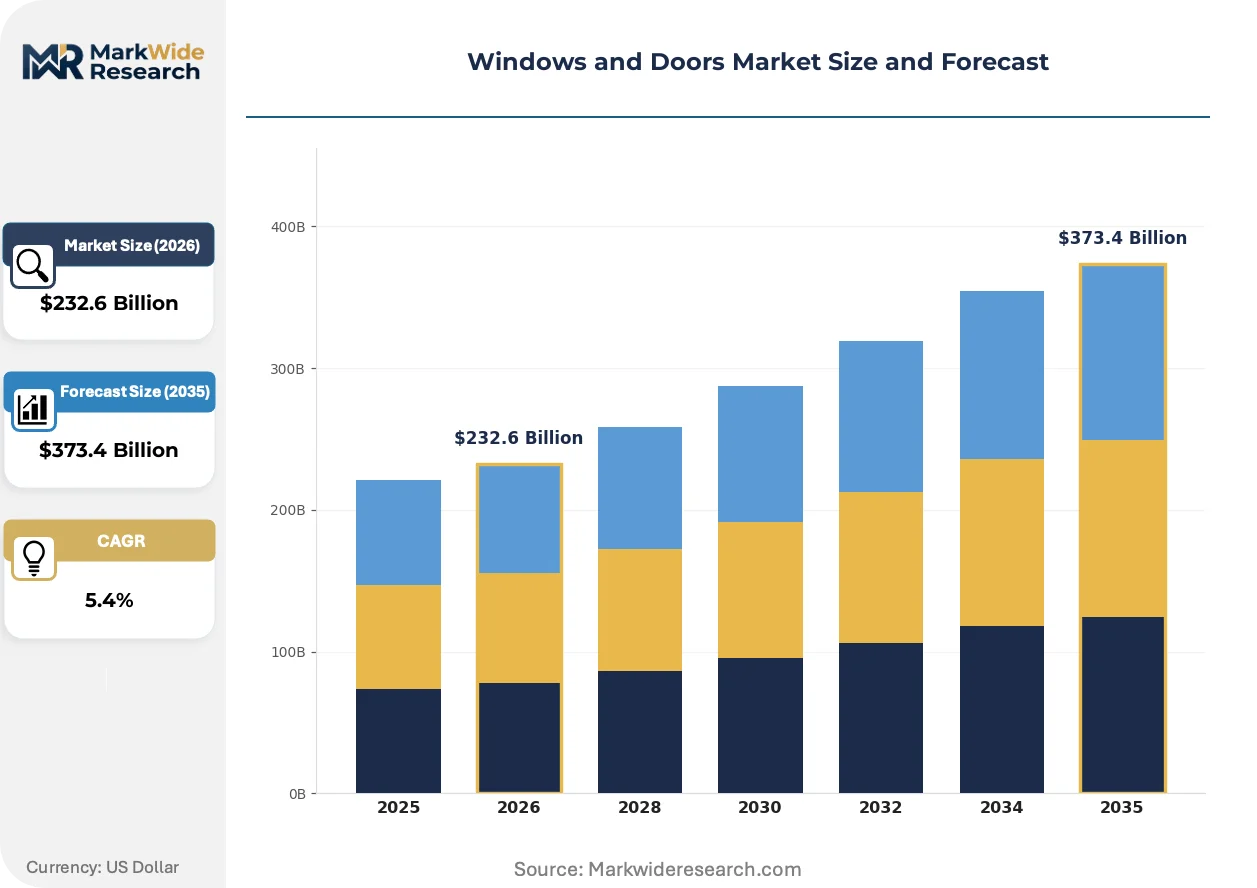
Market Dynamics
Residential retrofit demand is compressing product development cycles as manufacturers race to meet escalating thermal performance thresholds mandated by building code cycles in the United States, Germany, and Japan.
Growth Catalysts
- EPA Energy Star certification:Federal tax credit eligibility in the United States channels homeowner replacement spending toward certified products. Utility rebate programs amplify this pull in deregulated energy markets.
- Hurricane-resistant building codes:Florida's HVHZ wind-borne debris requirements and Gulf Coast state adoptions force replacement cycles for non-compliant installations. Coastal counties represent concentrated demand pockets.
- Thermally broken aluminum:Cold-climate specifications in Minnesota, Wisconsin, and Canadian provinces favor this material for commercial curtain wall retrofits. Performance gains over standard aluminum justify cost premiums.
Market Restraints
- Skilled glazing technician scarcity:Certified installer networks concentrate in metropolitan corridors while rural and secondary markets face project delays. Labor bottlenecks cap regional expansion velocity.
- Resin and aluminum price volatility:Vinyl extrusion feedstocks and aluminum billet costs fluctuate with petrochemical and energy markets. Manufacturers absorb margin compression or pass through via indexed pricing.
- Stringent NFRC testing protocols:Performance labeling requirements extend product qualification timelines. Smaller fabricators lack capital for in-house thermal testing infrastructure.
Strategic Opportunities
- Building renovation passports:France and Germany mandate step-change U-factor improvements for replacement installations. Compliance documentation services create adjacent revenue streams for distributors.
- Pre-hung door formats:DIY channel expansion reduces installer dependency for residential replacement. Big-box retail partnerships capture homeowner self-installation preferences.
- Fiberglass-vinyl hybrid systems:Pultruded fiberglass exterior skins bonded to vinyl interior frames merge coastal durability with cost efficiency. Product development targets Florida and Carolinas specification markets.
Industry Challenges
- California Title 24 compliance complexity:Prescriptive U-factor and SHGC requirements demand continuous product requalification. Engineering resources strain to maintain certified SKU portfolios across code cycles.
- Integrated glazing unit supply coordination:Insulated glass lead times vary with float glass and low-e coating capacity. Assembly plants buffer inventory or risk production stoppages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windows and Doors Market |
| Market Size in 2026 | $232.6 Billion |
| Market Size in 2035 | $373.4 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Windows, Casement Windows, Double-Hung Windows, Bi-Fold Doors Material: Vinyl, Wood, Aluminum, Fiberglass Installation Type: New Construction, Replacement, Remodeling, DIY End User: Residential, Commercial, Institutional, Industrial |
| Companies Covered | Marvin Windows & Doors, MI Windows and Doors, Andersen Windows & Doors, Therma-Tru, Ply Gem, JELD-WEN, Masonite International Corporation, PGT Innovations, Pella Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windows and Doors Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine product specifications across residential and commercial building envelopes. Installation methodologies and channel structures are adapting in parallel.
Triple-pane insulated glazing units with suspended film technology are displacing dual-pane systems in cold-climate residential specifications. Homeowners in Minnesota, Wisconsin, and Canadian provinces specify these for center-of-glass U-factors below 0.20. The technology is displacing conventional low-e dual-pane volume in utility rebate-eligible replacement segments.
The EU Green Deal's building renovation targets are cascading into national implementation through France's RE2020 environmental regulations and Germany's Gebäudeenergiegesetz. These frameworks mandate 55% primary energy reduction for major renovations. Window replacement becomes compulsory pathway for compliance in multifamily housing stock built before 1990.
Certified contractor programs are consolidating installation quality control as a competitive differentiator. Homeowners in the United States increasingly filter vendor selection through verified installer networks rather than product brand alone. This pattern concentrates in coastal markets where warranty coverage and wind-load engineering documentation carry litigation exposure.
Windows and Doors Market Segmentation
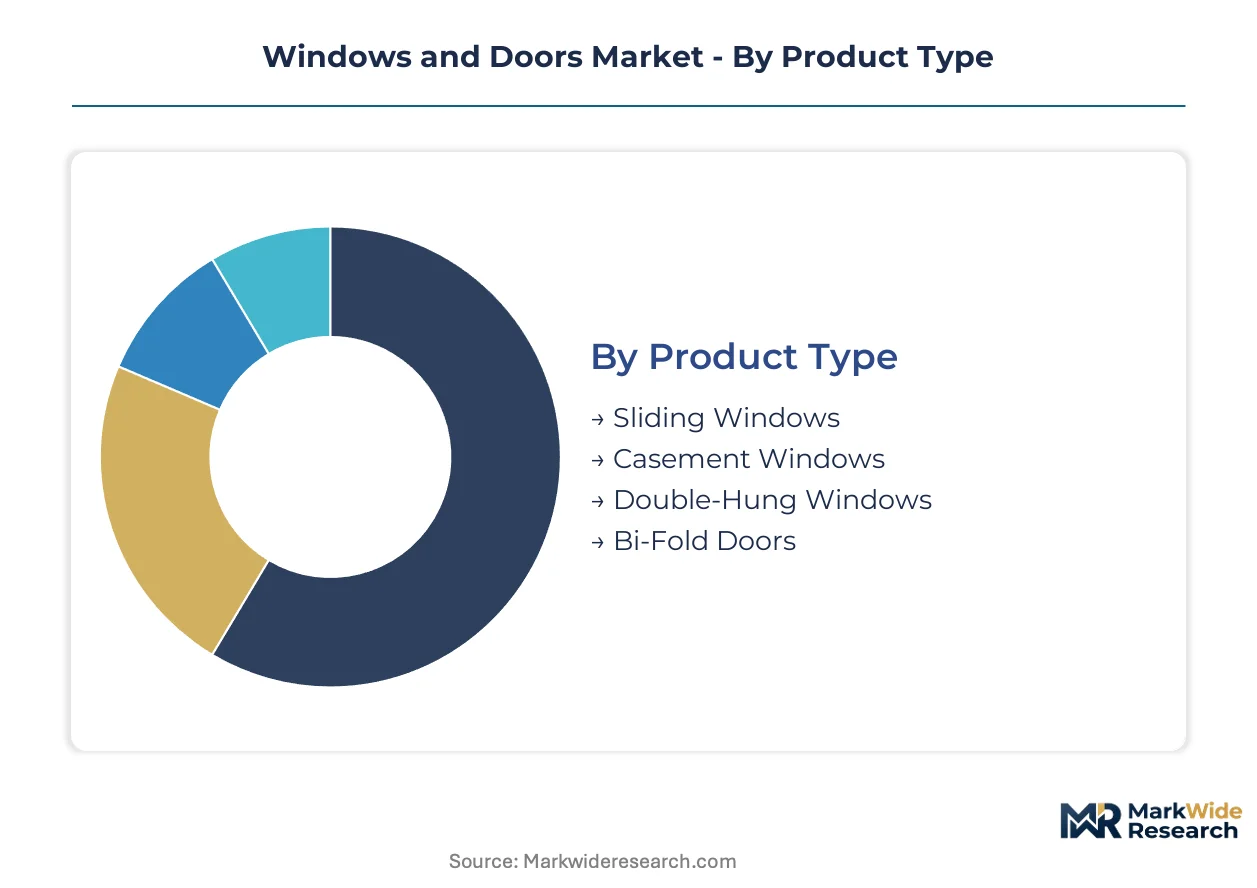
Product differentiation in the Windows and Doors Market follows thermal performance mandates, coastal durability requirements, and channel accessibility. Manufacturers configure SKU portfolios around code-driven specifications rather than aesthetic preference alone.
Product Type:
Geographic demand spreads unevenly across these formats, with coastal and cold-climate regions driving specification divergence.
- Sliding Windows:Horizontal sash operation suits contemporary residential architecture and multifamily construction where exterior projection is constrained. Florida and Gulf Coast counties specify impact-rated sliding systems for HVHZ compliance, with laminated glass and reinforced frames commanding specification premiums.
- Casement Windows:Hinged sash design with compression seal technology delivers superior air infiltration resistance for cold-climate residential retrofits. Minnesota and Wisconsin homeowners specify these for center-of-glass U-factors meeting utility rebate thresholds, with crank-operated hardware dominating professional installation channels.
- Double-Hung Windows:Vertical sliding sashes dominate residential replacement volume in mature housing markets.
- Bi-Fold Doors:Multi-panel folding systems concentrate in premium residential remodeling and commercial hospitality applications.
Double-hung windows hold the largest share; momentum sits with casement formats as thermal codes tighten.
Material:
Cost tier stratification separates premium specification markets from volume replacement channels.
- Vinyl:Extruded PVC profiles with multi-chamber construction dominate residential replacement volume due to thermal performance and minimal maintenance requirements. The material captures standard-tier pricing in big-box retail and contractor supply channels across the United States.
- Fiberglass:Pultruded composite profiles with thermal expansion coefficients matching glass deliver coastal durability and cold-climate performance. Florida and Carolinas specifications favor fiberglass for impact resistance and dimensional stability under humidity cycling.
- Wood:Laminated cores with aluminum or vinyl cladding sustain premium residential remodeling demand.
- Aluminum:Thermally broken profiles concentrate in commercial curtain wall and multifamily new construction.
Vinyl maintains volume leadership; fiberglass is gaining share fastest in coastal and cold-climate specification markets.
Installation Type:
Channel structure determines margin capture and installer dependency for each format.
- Replacement:Retrofit installation into existing rough openings dominates revenue concentration in aging housing stock markets. Professional crews complete full-frame or insert replacements, with lead-safe work practices mandated by EPA RRP rules for pre-1978 dwellings.
- Remodeling:Structural modification projects involving wall reconfiguration drive full-frame window and door specifications. Custom sizing and integrated flashing systems require certified installer networks, particularly in coastal counties with wind-borne debris engineering documentation.
- New Construction:Production homebuilding and commercial ground-up development channel volume through national distributors.
- DIY:Pre-hung door and insert window formats reduce skilled labor dependency for homeowner self-installation.
Replacement commands the revenue base; remodeling shows the steepest expansion trajectory as housing stock ages.
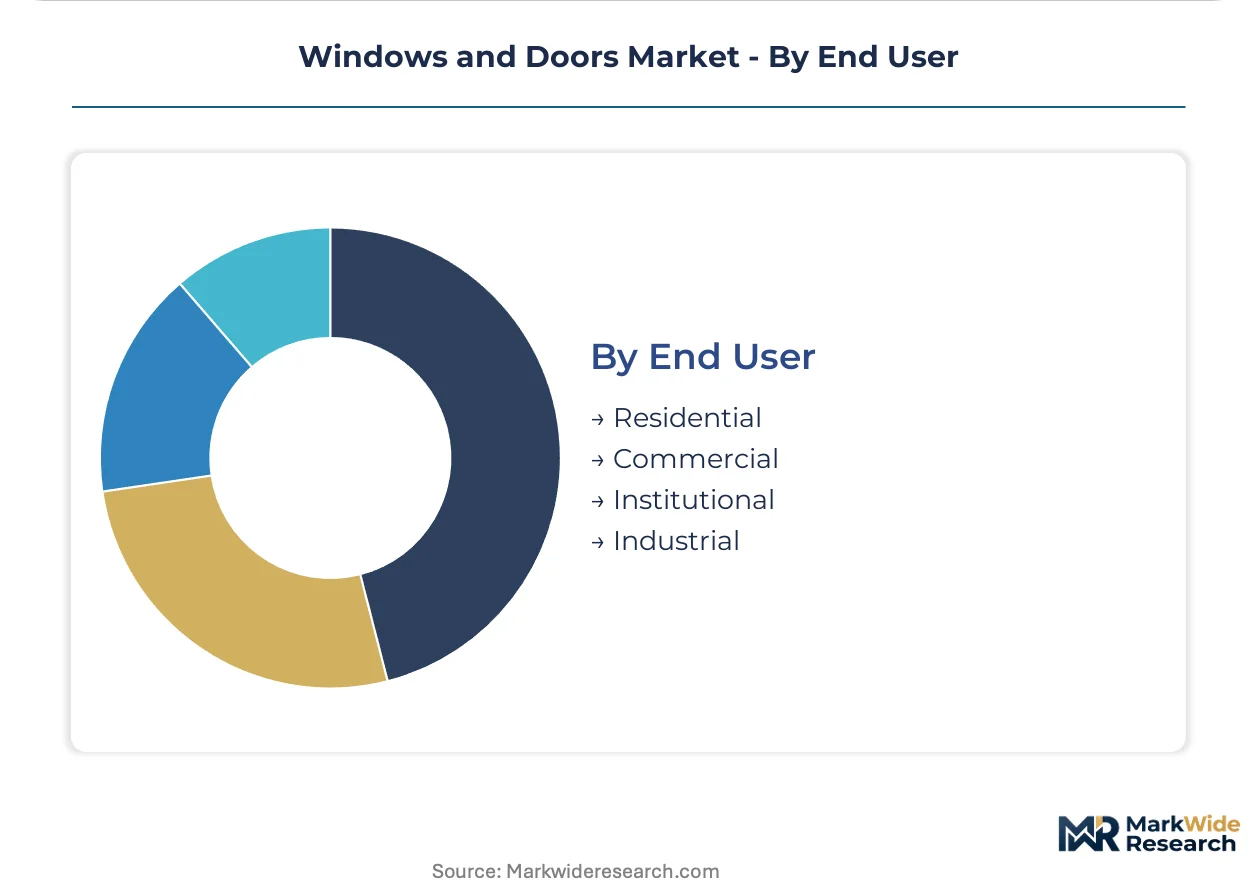
End User:
Customer type dictates specification complexity, thermal performance thresholds, and channel access requirements.
- Residential:Single-family and multifamily dwellings drive the majority of unit volume, with homeowner decision-making filtered through Energy Star certification eligibility and utility rebate programs. Tax credit documentation requirements channel spending toward NFRC-labeled products.
- Commercial:Office, retail, and hospitality buildings specify thermally broken aluminum systems and integrated curtain wall assemblies. ASHRAE 90.1 compliance and building energy benchmarking mandates drive retrofit investment in major metropolitan markets.
- Institutional:Schools, healthcare facilities, and government buildings procure through competitive bidding with prevailing wage requirements.
- Industrial:Manufacturing and warehouse facilities prioritize operational durability and security over thermal performance.
Residential absorbs the greatest unit volume; commercial retrofits climb fastest as energy benchmarking expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Star certification anchors demand concentration in the United States, where federal tax credits and utility rebate programs channel homeowner replacement spending. Germany's Gebäudeenergiegesetz and Japan's Top Runner program extend similar efficiency mandates across their respective construction markets.
United States
Aging housing stock and hurricane-resistant building codes drive replacement cycles across Florida and Gulf Coast states. Florida's HVHZ wind-borne debris requirements force non-compliant installation upgrades. Coastal counties from Miami-Dade to Houston represent concentrated demand pockets for impact-rated systems.
Germany
Building renovation passports mandate step-change U-factor improvements for replacement installations under the EU Green Deal framework. The Gebäudeenergiegesetz requires 55% primary energy reduction for major renovations. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate certified fabricator capacity for multifamily retrofits.
Japan
Top Runner energy efficiency standards and METI building renovation targets accelerate thermal performance upgrades in residential stock. Cold-climate specifications in Hokkaido and northern Honshu favor high-performance glazing systems. Manufacturing concentration in the Chubu region around Nagoya supplies domestic and export markets.
Canada
Cold-climate building codes in Ontario, Quebec, and Prairie provinces drive demand for triple-pane and suspended-film glazing technologies. Provincial energy rebate programs in British Columbia and Alberta channel spending toward NFRC-equivalent labeled products. Toronto and Vancouver metropolitan corridors concentrate certified installer networks.
France
RE2020 environmental regulations cascade EU Green Deal targets into mandatory performance thresholds for window replacement. Stepwise renovation requirements for pre-1990 multifamily housing stock create compliance-driven demand. The Île-de-France region anchors specification activity for energy benchmarking mandates.
Windows and Doors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the windows and doors sector. The market structure consolidates around integrated manufacturers with captive extrusion capacity and regional specialists with certified installation networks. Three archetypes dominate: vertically integrated material producers controlling vinyl and fiberglass supply chains, brand-centric manufacturers leveraging retail showroom presence, and coastal specialists engineering impact-rated systems for hurricane zones. Competitive moves concentrate on certified contractor program expansion and backward integration into glazing unit assembly.
Among North American fabricators, Andersen Windows & Doors, JELD-WEN, and Pella Corporation occupy positions spanning multiple archetypes. Andersen exemplifies the certified contractor network model for quality-controlled channel management. JELD-WEN represents backward integration strategy through captive vinyl extrusion and fiberglass pultrusion operations. Pella sits within the design-focused premium tier with proprietary material lines and retail showroom differentiation.
| Leading Market Players |
|---|
| Marvin Windows & Doors |
| MI Windows and Doors |
| Andersen Windows & Doors |
| Therma-Tru |
| Ply Gem |
| JELD-WEN |
| Masonite International Corporation |
| PGT Innovations |
| Pella Corporation |
| Others |
Supply Flow & Price Mechanics
Fiberglass substitution for vinyl in coastal impact-rated specifications simultaneously relocates manufacturing gravity toward pultrusion-capable plants in Florida and the Carolinas while compressing margin structures for standard-grade vinyl extruders serving big-box retail channels. This material transition reconfigures both upstream resin sourcing patterns and downstream pricing power across certified and uncertified product tiers.
Pricing Analysis
Geographic price spreads between coastal impact-rated systems and inland standard replacements have widened as Florida's HVHZ certification requirements concentrate premium specification power among certified fabricators. Three-tier pricing structure across premium, standard, and economy levels segments by NFRC performance grade and installation complexity rather than brand alone. Pricing pressure stems from resin and aluminum billet volatility indexed to petrochemical and energy markets. DIY channel buyers exhibit highest price sensitivity, while commercial retrofit specifiers prioritize warranty coverage and engineering documentation over unit cost.
Supply Chain Analysis
China and Germany anchor float glass and low-e coating capacity feeding insulated glazing unit assembly plants in the United States and Canada. Vinyl extrusion feedstocks draw from Gulf Coast petrochemical corridors, while fiberglass pultrusion relies on epoxy and polyester resin shipments from South Korea and Japan. Single-source vulnerability concentrates in low-e coating equipment where European and Japanese suppliers dominate. Distribution runs through national building material distributors, big-box retail partnerships, and certified contractor networks with divergent margin capture profiles.
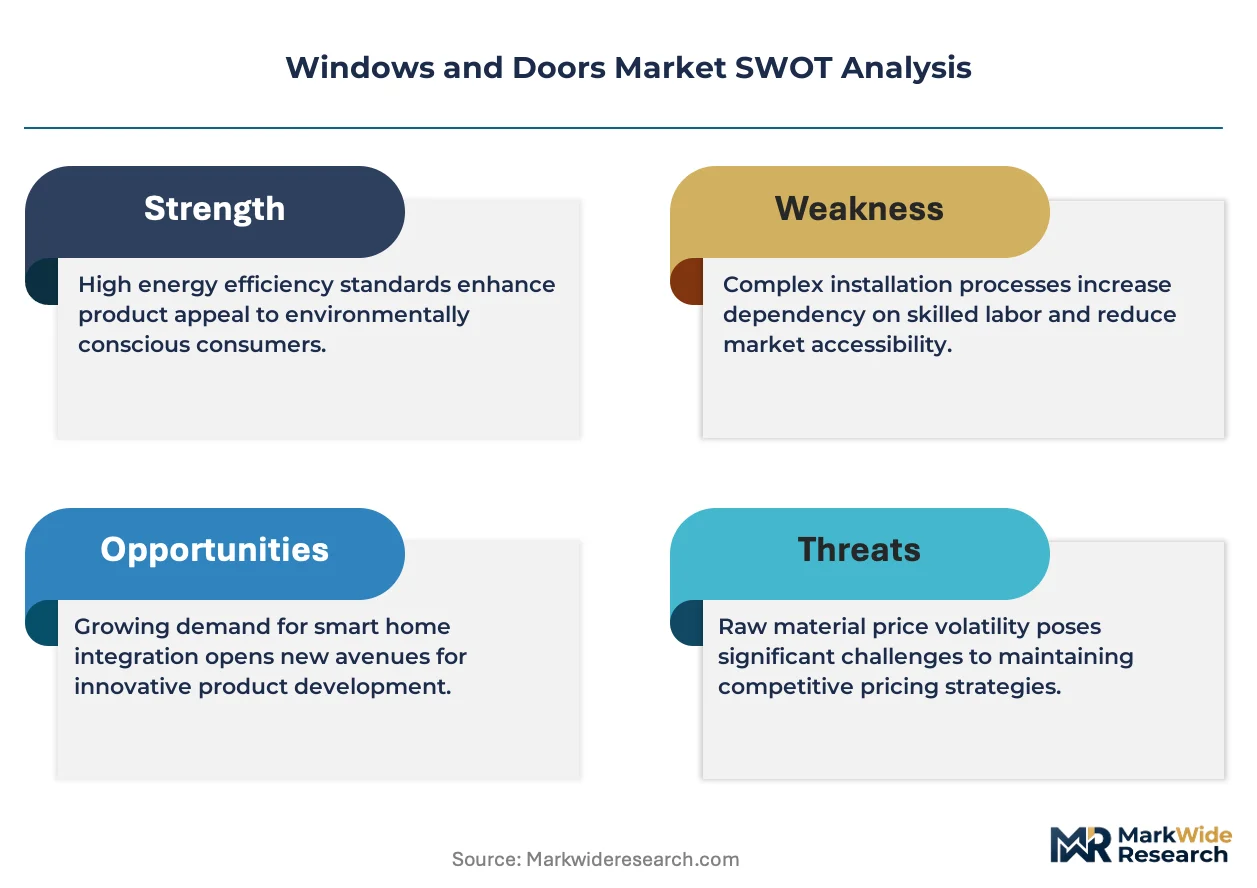
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified glazing technician shortages constrain regional expansion velocity and concentrate quality-controlled installation capacity in metropolitan corridors, creating defendable competitive positions for incumbents with captive contractor networks.
For Market Incumbents: Fortify backward integration into glazing unit assembly to buffer against float glass lead time volatility and low-e coating capacity constraints. Expand certified contractor programs in coastal counties where wind-load engineering documentation and warranty coverage carry litigation exposure, insulating against price competition from uncertified installers. For New Entrants and Emerging Players: EPA Energy Star certification fast-tracks federal tax credit eligibility and utility rebate program access, opening residential replacement channels without incumbent brand recognition. Target secondary metropolitan markets and rural counties facing skilled installer shortages where project delays create service-level differentiation opportunities. Pursue pre-hung door format partnerships with big-box retailers to reduce installer dependency. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators lacking captive extrusion capacity and certified installer networks. Long-term viability hinges on regulatory compliance infrastructure and coastal specification capabilities rather than volume scale alone. Watch Florida HVHZ code adoptions and ASHRAE 90.1 cycle updates as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glazing Unit Assembly | Insulates margin compression from float glass and low-e coating supply volatility. |
| Certified Contractor Program Expansion | Captures coastal specification markets where wind-load documentation carries litigation exposure. |
| Fiberglass-Vinyl Hybrid Product Development | Merges Florida HVHZ impact resistance with cost efficiency for Carolinas specification markets. |
| Building Renovation Passport Compliance Services | Creates adjacent revenue streams in France and Germany under EU Green Deal mandates. |
| Pre-Hung Door Format Big-Box Partnerships | Reduces installer dependency while capturing DIY channel expansion in residential replacement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports to establish baseline market sizing. Primary interviews engaged product development directors at integrated manufacturers, procurement leads at national distributors, certified glazing contractors in coastal and cold-climate markets, and regulatory affairs specialists tracking ASHRAE and ICC code cycles. Secondary sources included EPA Energy Star certification databases, NFRC performance labeling registries, EU Green Deal implementation documents, and SEC 10-K disclosures from publicly traded fabricators. Bottom-up unit volume estimates triangulated against top-down construction spending allocations.
Segmentation dimensions modeled include product type, material composition, installation category, and end-user sector across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, code adoption timelines, and efficiency standard escalation patterns. Industry-specific forecast inputs incorporated housing stock age distributions, utility rebate program budgets, and regional wind-load engineering requirements.
The analysis sits within stated boundaries; outcomes outside sustained residential retrofit spending levels, stable resin and aluminum pricing, or continued federal tax credit authorization would require recalibration. Forecasts reflect assumptions regarding skilled installer network expansion, low-e coating capacity additions, and model code propagation patterns. Recalibration cycles align with material shifts in building code adoption timelines and energy efficiency standard stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Modular Commercial Building System Market