
 Steel Utility Poles Market | 2026-2036
Steel Utility Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Utility Poles Market Outlook
The EU Green Deal is rebalancing procurement criteria across European transmission networks, favoring galvanized steel poles with lower embodied carbon footprints. Nucor Corporation leverages electric arc furnace production to sustain lower-carbon output for utility buyers. Valmont Industries, Inc. anchors North American supply through its vertically integrated coating and galvanizing operations. Meyer Utility Structures specializes in engineered tubular poles for high-voltage corridors, competing on design flexibility rather than commodity volume.
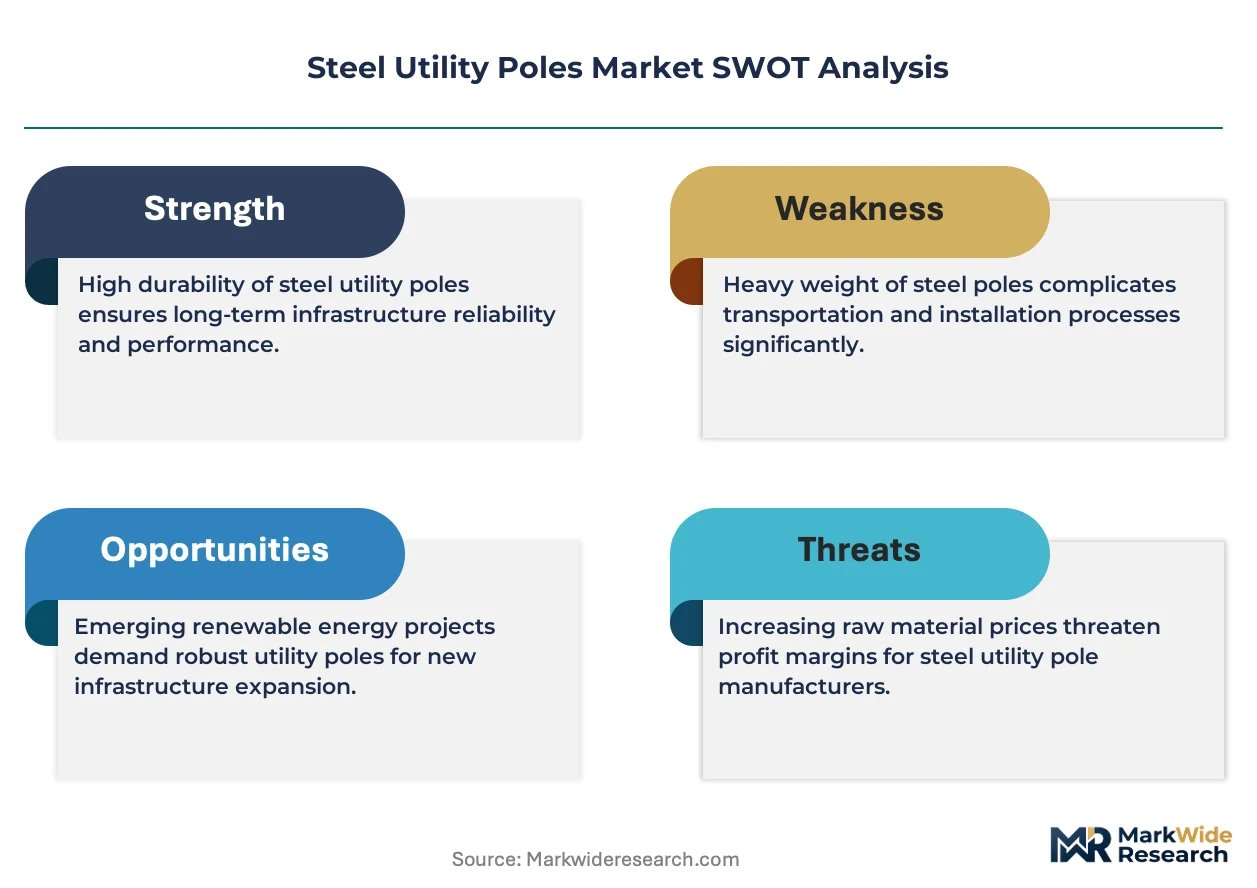
Steel utility poles are hollow or tapered structural columns fabricated from high-strength low-alloy steel, typically hot-dip galvanized to ASTM A123 specifications for corrosion resistance in outdoor electrical infrastructure. They carry conductors, transformers, and communication cables across distribution and transmission networks spanning 69 kV to 500 kV ratings. Single arm configurations dominate urban distribution grids where right-of-way constraints limit lateral space, while multi arm designs capture margin pools in dense telecommunications co-location deployments. Galvanized coating types lead volume due to decades of field-proven durability, though composite-coated poles are gaining traction in coastal corrosion zones where maintenance access is costly.
ASTM International governs material and dimensional standards for steel poles in the United States, while the EU's Construction Products Regulation mandates CE marking and EN 40 compliance for street lighting and overhead line structures. India's Bureau of Indian Standards enforces IS 2713 for tubular steel poles used in power distribution, with recent amendments tightening galvanization thickness requirements. Stakeholders must monitor how evolving national building codes and utility carbon accounting rules reshape supplier qualification criteria and coating technology roadmaps.
Market Dynamics
Grid decarbonization mandates are forcing electric utilities to requalify steel pole suppliers against embodied carbon thresholds, compressing procurement timelines and favoring producers with electric arc furnace capacity over integrated steel mills.
Growth Catalysts
- Rural electrification in India:The country's Bureau of Indian Standards has tightened galvanization specifications under IS 2713 amendments, accelerating replacement cycles for aging wooden infrastructure.
- Railway electrification corridors:Dedicated freight corridors and high-speed rail projects across Maharashtra and Gujarat are specifying engineered tubular poles for 25 kV traction networks.
- EU Green Deal infrastructure targets:Member state transmission operators must now account for scope 3 emissions in procurement, redirecting volume toward lower-carbon steel sources.
Market Restraints
- Zinc price volatility:Hot-dip galvanization depends on zinc ingot supplies concentrated in Chinese smelters, exposing pole fabricators to input cost swings that contract structures cannot fully pass through.
- Coastal corrosion limitations:ASTM A123 coatings degrade faster in marine environments than composite alternatives, restricting galvanized pole deployment within 50 kilometers of saltwater without premium duplex systems.
- Wooden pole residual stock:US rural electric cooperatives retain decades of chemically treated timber inventory, delaying steel conversion despite documented lifecycle cost advantages.
Strategic Opportunities
- Telecommunications co-location:5G small cell densification creates demand for multi-arm pole configurations that bundle power distribution with fiber and antenna mounting.
- European circular economy mandates:The EU's Construction Products Regulation is tightening end-of-life recyclability requirements, advantaging steel over concrete for new transmission corridors.
- Hybrid coating systems:Duplex coatings combining galvanization with powder or polyurethane topcoats are penetrating offshore wind connection routes where maintenance access requires 50-year service life guarantees.
Industry Challenges
- Welding certification bottlenecks:AWS D1.1 structural welding qualifications for high-strength low-alloy steels require specialized operator training that fabricators struggle to staff at scale.
- Utility qualification timelines:Investor-owned utilities in Texas and California impose 18-24 month vendor approval processes that freeze out new entrants regardless of technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Utility Poles Market |
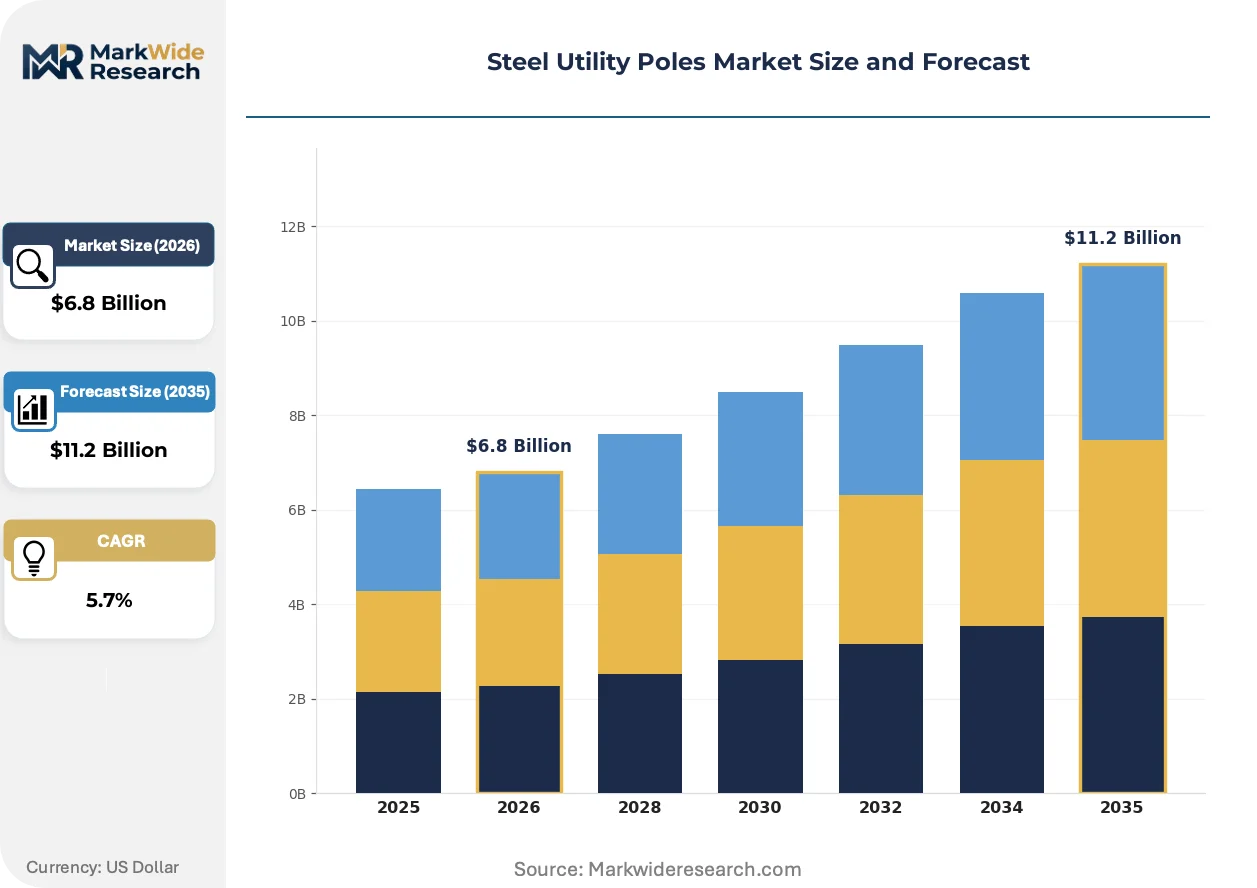
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Arm, Double Arm, Multi Arm, Guyed Poles End User: Electric Utilities, Telecommunications, Railways, Street Lighting Installation Type: Overhead, Underground, Hybrid, Remote Areas Coating Type: Galvanized, Painted, Composite, Uncoated |
| Companies Covered | Valmont Industries, Inc., Meyer Utility Structures, RS Technologies, Inc., Nippon Steel Corporation, Nucor Corporation, KEC International Limited, Skipper Limited, DAJI Towers, McWane Poles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Utility Poles Market Strategic Shifts
Material science advances and digital design tools are compressing development cycles for engineered pole systems, while regulatory carbon accounting is rewiring supplier qualification protocols across transmission networks.
Advanced high-strength steel grades with yield strengths exceeding 65 ksi are integrating into transmission pole designs, enabling thinner wall sections that reduce transport weight and foundation loads. US utilities operating 345 kV corridors are specifying these materials for new buildouts, displacing traditional 50 ksi specifications. The technology is integrating load-optimized geometries that reduce steel tonnage per mile of line without compromising structural margins.
The EU Green Deal's embodied carbon disclosure requirements are mandating Environmental Product Declarations for all structural steel entering transmission projects, effective across member state procurement frameworks. This regulatory architecture is disqualifying integrated blast furnace producers from tender participation in German and French grid modernization programs. Transmission system operators in Scandinavia are responding by sourcing exclusively from electric arc furnace suppliers with verified renewable energy inputs.
Buyers are consolidating pole procurement through framework agreements that bundle engineering, fabrication, and installation services into single-source contracts. This model is displacing traditional component bidding where utilities separately sourced steel, galvanizing, and erection services. The shift is most visible in India's state electricity boards, which are migrating from item-rate contracts to turnkey delivery structures for rural electrification packages.
Steel Utility Poles Market Segmentation
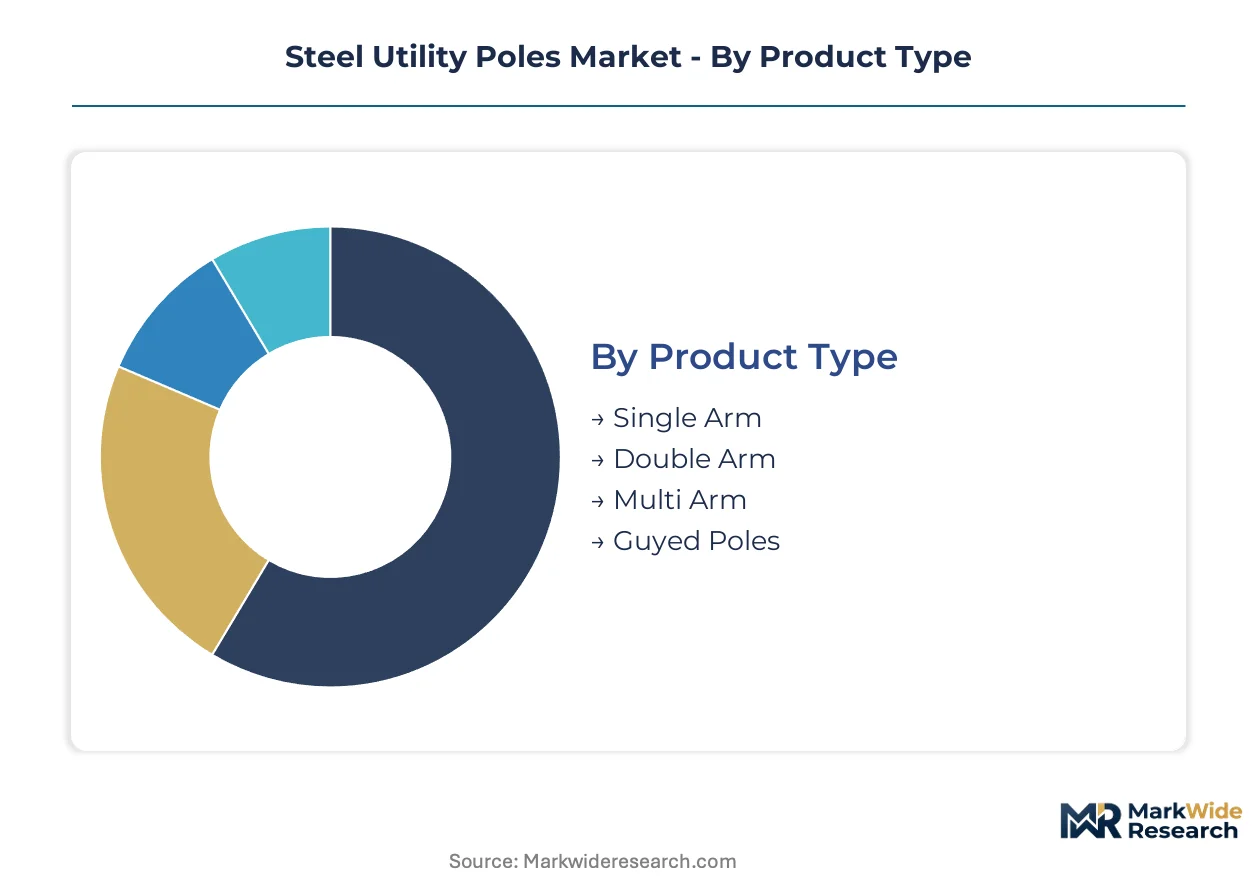
Steel utility poles serve divergent infrastructure requirements across voltage ratings, environmental exposure, and co-location demands. Specification choices cascade through foundation design, transport logistics, and lifecycle maintenance obligations. Procurement teams segment orders by structural configuration, end-use application, installation constraints, and corrosion protection systems.
Product Type:
Arm configuration determines load-bearing geometry and right-of-way footprint, with urban density and voltage rating driving selection.
- Single Arm:Cantilevered crossarm mounting suits congested urban distribution corridors where lateral space is constrained. Municipal utilities in Mumbai and Delhi specify these for 11 kV and 33 kV networks threading through established residential fabric.
- Multi Arm:Stacked crossarm arrangements bundle power distribution with telecommunications and street lighting infrastructure. 5G densification programs across German cities are accelerating orders for multi-arm configurations that reduce street clutter.
- Double Arm:Symmetrical arm pairs balance conductor tension for transmission lines traversing uneven terrain. Deployment concentrates in India's Western Ghats railway electrification corridors.
- Guyed Poles:Tension wire stabilization enables taller, lighter structures for long-span river crossings and agricultural flatlands. Demand clusters in Brazil's Pantanal floodplains where foundation costs dominate economics.
Mature deployment sits with Single Arm configurations. Newer deployment is concentrated in Multi Arm systems bundling multiple infrastructure layers.
End User:
Customer archetypes impose distinct qualification protocols, with electric utilities demanding decades-long service warranties and railways specifying fatigue-resistant designs.
- Electric Utilities:Investor-owned and state-run power companies order poles across 69 kV to 500 kV ratings with ASTM A123 or IS 2713 compliance. India's state electricity boards are consolidating procurement through turnkey rural electrification frameworks.
- Railways:Traction networks require engineered tubular poles rated for 25 kV overhead catenary systems with vibration damping. Dedicated freight corridors across Maharashtra and Gujarat are driving specification tightening.
- Telecommunications:5G small cell and fiber backhaul deployments favor multi-arm poles with integrated antenna mounting platforms. Tower companies are specifying these for urban co-location in compliance with FCC structural standards.
- Street Lighting:Municipal authorities combine illumination with traffic signaling and CCTV mounting. European cities are prioritizing CE-marked poles with end-of-life recyclability credentials under EU circular economy mandates.
Electric utilities anchor procurement volume. Telecommunications represents the steepest expansion trajectory as infrastructure sharing accelerates.
Installation Type:
Site accessibility and soil conditions dictate foundation methodology, with remote terrain imposing helicopter transport premiums.
- Overhead:Standard embedded foundation designs dominate accessible terrain with conventional auger drilling. This method captures the majority of grid modernization programs in Texas and California.
- Hybrid:Combination overhead-underground transitions serve coastal hurricane zones and wildfire-prone California corridors where buried sections mitigate risk.
- Underground:Direct-buried or duct bank configurations eliminate visual impact in historic districts and airport approach zones. Premium pricing reflects confined-space installation requirements.
- Remote Areas:Helicopter-sling transport and rock-anchor foundations serve mountainous transmission corridors. Scandinavian operators are specifying lightweight high-strength steel grades for these deployments.
Overhead installation retains cost leadership. Remote area deployment is gaining share fastest as renewable energy sites penetrate inaccessible terrain.
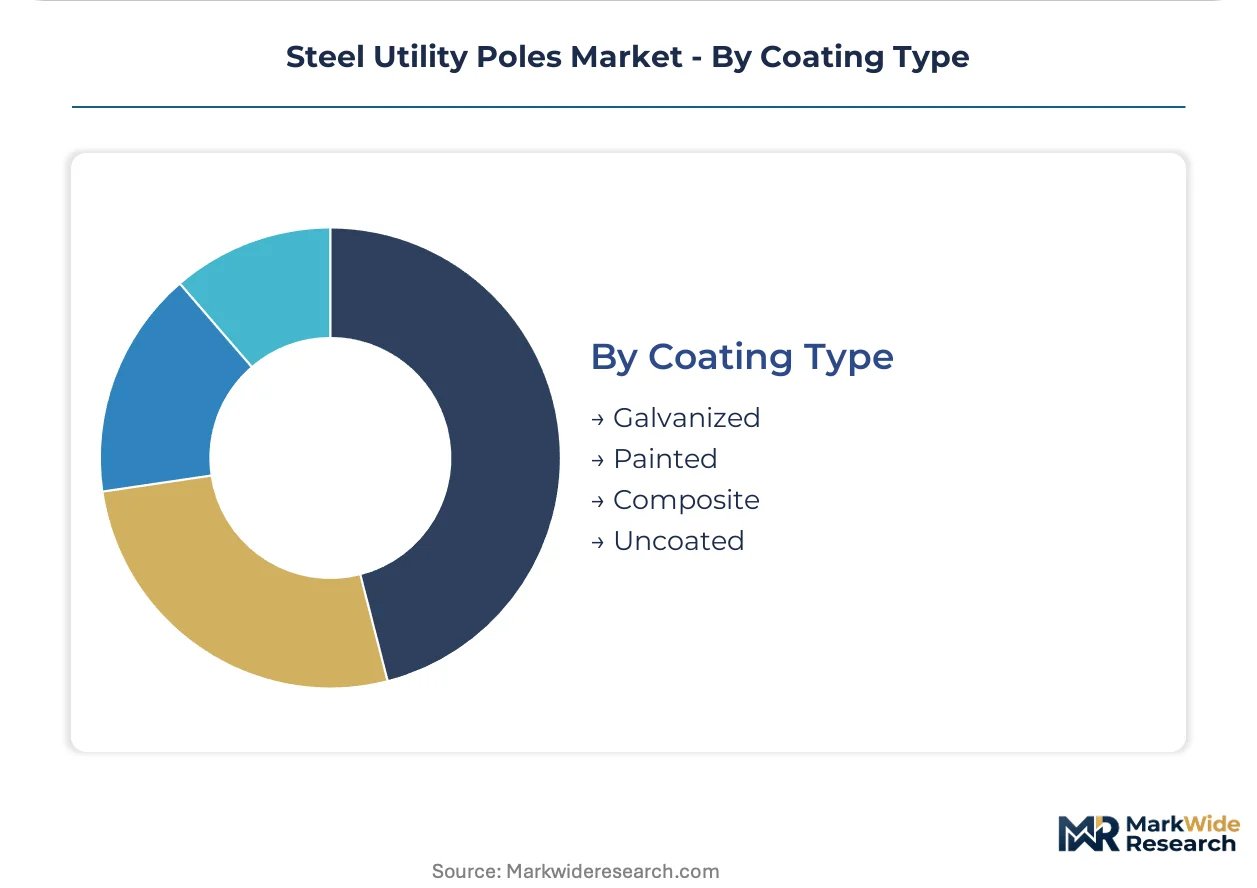
Coating Type:
Corrosion protection selection balances initial cost against maintenance access economics, with marine exposure forcing duplex system premiums.
- Galvanized:Hot-dip zinc coating to ASTM A123 or EN ISO 1461 specifications delivers proven field durability across decades. This remains the default specification for inland distribution networks.
- Composite:Polymer or fiberglass overwrap systems penetrate coastal zones within 50 kilometers of saltwater where galvanization degradation accelerates. Offshore wind connection routes are specifying these for 50-year service guarantees.
- Painted:Epoxy or polyurethane topcoats over galvanization provide color coding and additional barrier protection. Aesthetic requirements in European historic centers drive this specification.
- Uncoated:Weathering steel formulations develop protective oxide patinas without coating maintenance. Limited deployment in arid interior regions with low chloride exposure.
Galvanized coating dominates installed base. Composite systems are climbing the fastest as offshore and coastal infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electrification corridors anchor steel pole procurement, with Maharashtra and Gujarat railway projects driving specification tightening for 25 kV traction networks.
India
Rural electrification and dedicated freight corridors propel demand across Maharashtra and Gujarat. The Bureau of Indian Standards enforces IS 2713 amendments tightening galvanization thickness requirements. State electricity boards in Delhi-NCR and Tamil Nadu are consolidating procurement through turnkey rural electrification frameworks.
United States
Grid modernization programs and wildfire mitigation drive replacement of aging wooden infrastructure. The Federal Energy Regulatory Commission oversees interstate transmission reliability standards affecting pole specifications. Texas utilities impose 18-24 month vendor qualification timelines that filter supplier participation.
Germany
Transmission system operators source lower-carbon steel under EU Green Deal embodied carbon disclosure mandates. The Construction Products Regulation mandates CE marking and Environmental Product Declarations for structural steel. Industrial clusters in North Rhine-Westphalia coordinate electric arc furnace procurement for grid modernization.
China
Zinc smelter concentration shapes input cost structures for galvanizing operations. The Ministry of Ecology and Environment enforces dual carbon goals affecting steel production emissions. Manufacturing corridors in Shandong and Hebei supply domestic utility and export markets.
Brazil
Agricultural electrification and Pantanal floodplain crossings favor guyed pole configurations. ANVISA regulates environmental compliance for infrastructure materials. Distribution utilities in São Paulo and Minas Gerais specify hybrid coating systems for coastal exposure zones.
Steel Utility Poles Market Competitive Environment
The competitive structure tilts toward vertically integrated manufacturers with captive galvanizing capacity. Electric arc furnace producers command premium positioning as utilities requalify suppliers against embodied carbon thresholds. Two archetypes dominate: integrated steel-to-coating operators and engineered tubular specialists competing on design flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure renewable energy inputs for low-carbon output.
Among North American fabricators, Valmont Industries, Inc. and Nucor Corporation exemplify the integrated archetype, while Meyer Utility Structures occupies a position within the engineered specialist tier. KEC International Limited and Skipper Limited represent Indian-scale operators serving domestic electrification programs. These anchors illustrate how geographic proximity to demand clusters and production technology choices determine supplier qualification success.
| Leading Market Players |
|---|
| Valmont Industries, Inc. |
| Meyer Utility Structures |
| RS Technologies, Inc. |
| Nippon Steel Corporation |
| Nucor Corporation |
| KEC International Limited |
| Skipper Limited |
| DAJI Towers |
| McWane Poles |
| Others |
Value Chain & Pricing Dynamics
Welding certification bottlenecks in North America and India compress labor supply for high-strength low-alloy fabrication, widening spreads between premium-certified and standard-tier pole suppliers. Electric utilities in Texas and California absorb these differentials through extended vendor qualification timelines that filter out uncertified competitors.
Pricing Analysis
Service-life guarantees anchor value-based pricing for engineered tubular poles in railway electrification and offshore wind connection routes. Three-tier pricing structure across premium, standard, and economy levels separates duplex-coated coastal specifications from inland galvanized standards and untreated weathering steel for arid zones. Cost compression in standard galvanized tiers intensifies because zinc ingot volatility from Chinese smelter concentration erodes fabricator margins. Rural electric cooperatives in the United States exhibit highest price sensitivity due to decades of chemically treated timber inventory, while European transmission system operators under EU Green Deal mandates show lowest sensitivity to embodied carbon premiums.
Supply Chain Analysis
Single-source vulnerability sits with zinc ingot supplies concentrated in Chinese smelters, exposing pole fabricators to input cost swings that contract structures cannot fully pass through. Manufacturing draws from China, India, and the United States for fabricated steel poles, with galvanizing operations clustered near zinc refining capacity. Raw material dependencies rest on high-strength low-alloy steel coil, zinc ingot for hot-dip coating, and welding consumables for structural assembly. Tariff exposure on Chinese steel imports threatens cost structures for North American fabricators lacking electric arc furnace capacity. Distribution runs through direct utility framework agreements in India and Germany, displacing traditional component bidding channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steel utility poles market sits in a coating technology transition phase. Duplex systems combining galvanization with polymer topcoats are displacing single-layer ASTM A123 specifications in coastal and offshore applications.
For Market Incumbents: Anchor market position through captive electric arc furnace capacity that satisfies EU Green Deal embodied carbon disclosure requirements and secures German transmission operator qualification. Deepen backward integration into zinc coating operations to buffer Chinese smelter price volatility. Defend against composite-coated pole substitution in marine zones by extending duplex system warranties beyond 50-year service life benchmarks. For New Entrants and Emerging Players: Enter via telecommunications co-location white space created by 5G small cell densification programs across German and Indian urban corridors. Target multi-arm pole configurations bundling power distribution with fiber and antenna mounting where incumbent utilities lack design flexibility. Pursue turnkey rural electrification frameworks in India's Maharashtra and Gujarat states where state electricity boards consolidate procurement away from item-rate contracts. For Investors and Strategic Acquirers: Re-rating potential sits with electric arc furnace producers given EU Green Deal scope 3 emission accounting mandates disqualifying integrated blast furnace competitors. Long-term viability favors suppliers with verified renewable energy inputs and Environmental Product Declaration certification for European transmission access. Monitor zinc price volatility as inflection indicator for margin compression across standard galvanized tier producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing Operations | Captive coating capacity buffers zinc price volatility from Chinese smelter concentration. |
| Electric Arc Furnace Capacity Expansion | Lower-carbon output satisfies EU Green Deal embodied carbon thresholds for German utilities. |
| Duplex Coating System Development | Polymer-galvanization combinations penetrate offshore wind routes requiring 50-year guarantees. |
| Turnkey Framework Agreement Pursuit | Single-source contracts displace component bidding in India's rural electrification programs. |
| Multi-Arm Configuration Engineering | 5G co-location demand bundles power, fiber, and antenna infrastructure in dense urban corridors. |
Study Parameters
Independent corroboration across utility procurement officers, structural welding certification bodies, and zinc industry analysts underwrites the qualitative findings. Primary interviews with electric utility planning directors, railway electrification engineers, and telecommunications tower procurement managers combined with secondary validation from BIS amendments, ASTM standards documentation, and EU Construction Products Regulation filings. Bottom-up pole shipment data from Indian state electricity boards and top-down transmission investment forecasts triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments expansion by voltage rating, coating technology tier, and end-use application. The analytical framework models arm configuration, installation type, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from utility capital expenditure trajectories, railway electrification mileages, and 5G densification schedules. Forecast inputs incorporate zinc price volatility bands and welding certification capacity constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute zinc supply disruption or accelerated EU carbon border adjustment implementation. Deviation in Indian rural electrification disbursement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market