
 North America Concrete Cellulose Fiber Reinforcement Market | 2026-2036
North America Concrete Cellulose Fiber Reinforcement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Cellulose Fiber Reinforcement Market Intelligence
Skilled concrete technician availability is redrawing competitive boundaries across the North American supply base. J. Rettenmaier USA LP leverages its domestic fluff pulp processing infrastructure to control raw material flows from forest to batch plant. Sika AG anchors its position through technical service teams embedded with major ready-mix producers. BASF competes by bundling cellulose fibers with its broader admixture portfolio, forcing smaller rivals to specialize or exit.
Concrete cellulose fiber reinforcement comprises processed plant-derived fibers, typically cellulose content exceeding 95 percent by mass, engineered into monofilament or fibrillated geometries for secondary concrete reinforcement. These fibers mitigate plastic shrinkage cracking and improve freeze-thaw durability in flatwork and precast elements by distributing micro-stresses throughout the cementitious matrix. Wood fibers dominate volume in residential slab applications where cost sensitivity pushes specification toward economical pulp-derived grades. Fluff pulp commands premium positioning in infrastructure segments demanding verified alkali resistance and consistent aspect ratio control. Hemp fibers represent the fastest-expanding category as Canadian cultivators scale bast fiber extraction capacity to serve biogenic-content mandates in public procurement.
Federal Highway Administration specifications, ASTM C1116 fiber-reinforced concrete standards, and state-level Buy America provisions collectively determine qualification thresholds for infrastructure bids. The EPA's Construction General Permit requirements for stormwater pollution prevention create downstream demand for pervious concrete formulations that rely on cellulose fiber stabilization. Stakeholders must monitor evolving state DOT qualification protocols for alternative reinforcement materials, as Illinois and Michigan pilot performance-based specifications that could displace prescriptive fiber dosage rates with engineered property targets.
Market Dynamics
Federal infrastructure spending and state-level biogenic-content mandates are restructuring procurement specifications across the North American concrete cellulose fiber reinforcement market. Contractors now face dual pressure to meet performance targets while documenting sustainable sourcing credentials.
Growth Catalysts
- EPA Stormwater Standards:The EPA's Construction General Permit requirements for stormwater pollution prevention are mandating pervious concrete formulations that rely on cellulose fiber stabilization for structural integrity.
- State DOT Rehabilitation Programs:Michigan, Illinois, and Ohio transportation departments are accelerating bridge deck and pavement overlays using fiber-modified concrete mixes.
- Hemp Bast Fiber Processing:Canadian cultivators in Alberta and Saskatchewan are scaling extraction capacity to meet public procurement biogenic-content thresholds.
Market Restraints
- Fluff Pulp Supply Concentration:Domestic fluff pulp processing capacity clusters in the southeastern United States, creating geographic vulnerability for Great Lakes batch plants.
- Alkali Resistance Certification Costs:ASTM C1116 qualification protocols require extended laboratory validation that smaller admixture distributors cannot fund.
- Synthetic Macro-Fiber Substitution:Polypropylene and polyolefin fibers compete on price for residential slab applications where specification engineers prioritize first-cost over lifecycle performance.
Strategic Opportunities
- Texas Infrastructure Expansion:The state's Department of Transportation is piloting performance-based specifications that could open specification pathways for alternative reinforcement materials.
- Carbon Accounting Integration:Environmental Product Declarations aligned with CSA Group standards are creating differentiation for cellulose fiber producers with verified supply chain emissions data.
- Direct-to-Contractor Digital Platforms:Ready-mix producers are building proprietary e-procurement channels that bypass traditional distribution markups for specification-grade fiber products.
Industry Challenges
- Certified Concrete Technician Shortage:The American Concrete Institute's flatwork finisher certification programs cannot produce qualified technicians fast enough to support accelerated infrastructure timelines.
- Buy America Documentation Complexity:Federal Highway Administration compliance requires chain-of-custody verification from forest source to batch plant that many suppliers lack systems to provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Cellulose Fiber Reinforcement Market |
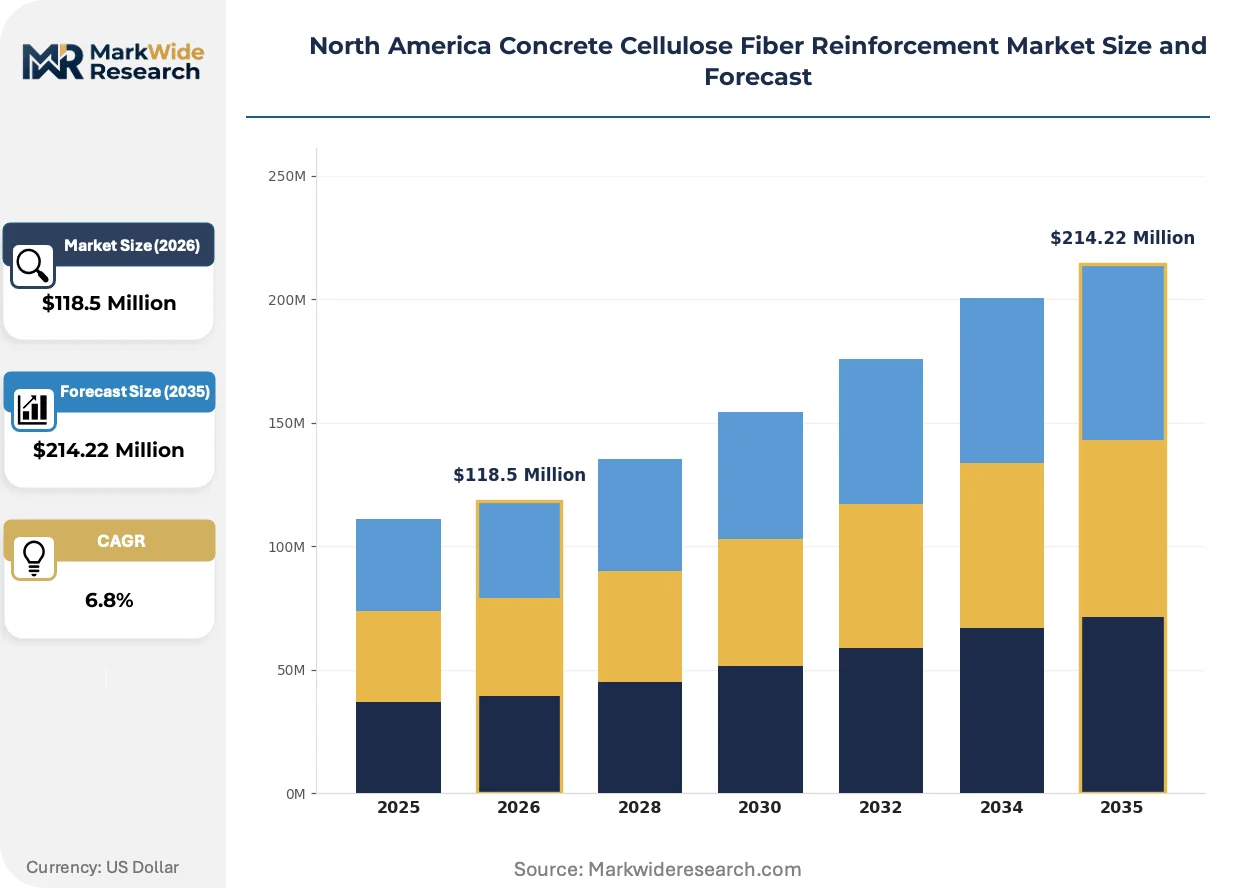
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $214.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Fluff Pulp, Cotton Fibers, Rayon, Wood Fibers, Hemp Fibers Application: Commercial Construction, Residential Projects, Infrastructure Development, Precast Concrete, Bridges End User: Construction Firms, Concrete Manufacturers, Civil Engineers, Contractors Distribution Channel: Direct Sales, Dealers & Distributors, E-commerce, Specialty Stores |
| Companies Covered | J. Rettenmaier USA LP, Fiber Technologies Inc., Concrete Protection Technologies LLC, Solomon Colors, Inc., Fiberzone India, Euclid Chemicals, Sika AG, BASF, Saint Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Cellulose Fiber Reinforcement Market Strategic Shifts & Innovations
Specification engineers are rewriting material standards to prioritize measured performance over prescriptive fiber dosages. This shift rewards suppliers capable of engineering property-specific solutions rather than commodity volume plays.
Fibrillated cellulose geometries with controlled aspect ratios are displacing monofilament wood fibers in infrastructure flatwork applications. State DOT labs in Illinois and Michigan are validating these engineered fibers for freeze-thaw durability at reduced dosage rates. The technology is displacing traditional prescriptive specifications that fixed fiber content by mass regardless of performance outcomes.
The EPA's evolving Construction General Permit framework is tightening turbidity limits for stormwater runoff from construction sites. Pervious concrete installations must now demonstrate hydraulic conductivity retention over fifteen-year service lives. Infrastructure contractors in the Great Lakes corridor are responding by specifying cellulose-stabilized mixes with documented pore structure durability.
Ready-mix procurement is consolidating around performance-guaranteed supply contracts that bundle fiber, admixture, and technical service. Large civil contractors are displacing spot-market purchasing with multi-year agreements that transfer batch optimization risk to suppliers. This pattern is most visible in Ohio and Michigan where integrated producers now embed field technicians directly with major infrastructure bidders.
North America Concrete Cellulose Fiber Reinforcement Market Segmentation
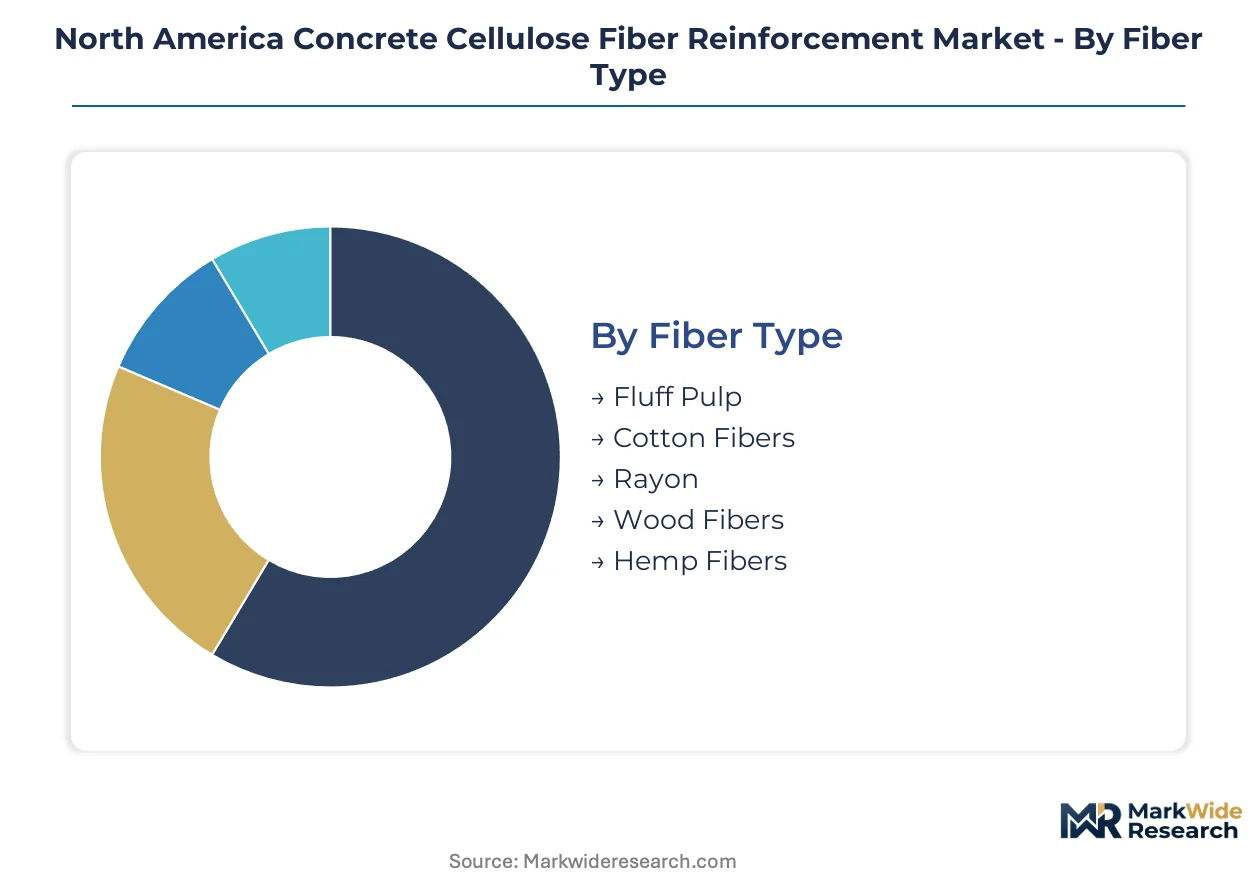
Specification engineers source cellulose fibers through distinct procurement channels tied to project scale and certification requirements. Segmentation reveals how fiber geometry, application criticality, and buyer sophistication reshape supplier positioning across the North American supply base.
Fiber Type:
Domestic pulp capacity in the southeastern United States anchors fluff pulp and wood fiber supply, while Canadian hemp cultivation serves cross-border biogenic-content mandates.
- Fluff Pulp:Highly purified cellulose derived from softwood kraft pulping delivers consistent aspect ratio control and verified alkali resistance. Demand concentrates in Michigan and Ohio infrastructure bids where state DOTs require ASTM C1116-compliant documentation for bridge deck overlays.
- Wood Fibers:Economical pulp-derived grades with fibrillated geometries mitigate plastic shrinkage in residential slab applications. Cost-sensitive flatwork contractors in Texas and Florida specify these fibers for single-family foundation pours where first-cost dominates procurement decisions.
- Hemp Fibers:Canadian bast fiber extraction capacity in Alberta and Saskatchewan scales to meet public procurement biogenic-content thresholds.
- Cotton Fibers:Textile waste streams supply short-staple cellulose for specialized precast facing mixes.
- Rayon:Regenerated cellulose filaments command niche positioning in architectural concrete demanding surface finish uniformity.
Wood fibers hold the largest share; momentum sits with hemp fibers.
Application:
Project scale determines fiber specification rigor, with federal-aid infrastructure demanding engineered property targets that residential flatwork rarely requires.
- Infrastructure Development:Highway rehabilitation and stormwater management projects specify cellulose-stabilized pervious concrete for hydraulic conductivity retention. EPA Construction General Permit turbidity limits drive specification across the Great Lakes corridor.
- Bridges:Deck overlays and substructure repairs require freeze-thaw durable fiber-modified mixes with documented fifteen-year service life validation. Illinois DOT pilot programs are validating reduced-dosage fibrillated fiber formulations.
- Commercial Construction:Warehouse and retail flatwork prioritize plastic shrinkage crack control in large pour sequences.
- Residential Projects:Slab-on-grade foundations and basement walls represent volume demand sensitive to material cost per cubic yard.
- Precast Concrete:Architectural and structural elements incorporate cellulose fibers for handling durability and surface quality.
Infrastructure Development generates the highest specification intensity; Bridges is expanding most quickly.
End User:
Technical capability gaps across the installation workforce fragment procurement authority between design engineers and field contractors.
- Civil Engineers:Specification authority for federal and state infrastructure projects demands fiber producers deliver Environmental Product Declarations and chain-of-custody documentation. FHWA Buy America compliance requirements filter supplier qualification across Michigan, Ohio, and Illinois bids.
- Concrete Manufacturers:Ready-mix producers bundle fiber with admixture portfolios under performance-guaranteed supply contracts. Integrated technical service teams embed directly with major infrastructure bidders in the Great Lakes region.
- Construction Firms:Large civil contractors displace spot-market purchasing with multi-year agreements transferring batch optimization risk.
- Contractors:Smaller residential and commercial flatwork specialists rely on distributor recommendations for commodity-grade fiber selection.
Concrete Manufacturers command procurement volume; Civil Engineers drive specification upgrade.
Distribution Channel:
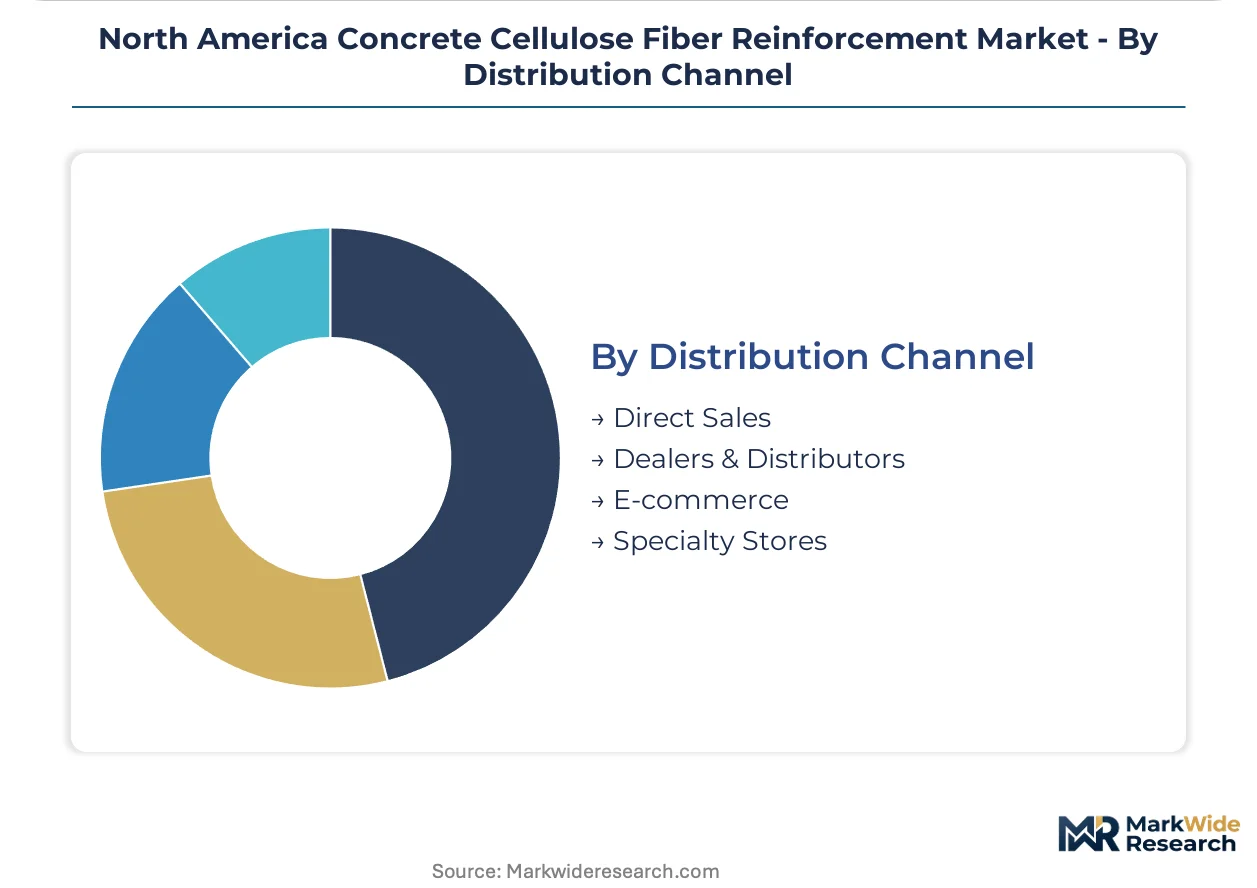
Channel selection tracks buyer scale and technical support requirements, with integrated producers bypassing traditional distribution for direct specification engagement.
- Direct Sales:Large ready-mix and precast producers procure specification-grade fibers through technical service relationships. Sika AG and BASF anchor positions by embedding field teams with batch plant operations.
- Dealers & Distributors:Regional admixture distributors serve mid-tier contractors lacking in-house materials engineering capacity. Geographic coverage gaps in the Great Lakes corridor create vulnerability for fluff pulp-dependent suppliers.
- E-commerce:Proprietary digital platforms enable ready-mix producers to bypass markup layers for standardized fiber grades.
- Specialty Stores:Limited relevance given the technical specification nature of concrete reinforcement procurement.
Direct Sales captures the premium tier; E-commerce is gaining share fastest among standardized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors United States demand through stormwater management mandates that reshape material specifications across the Great Lakes industrial corridor. Federal infrastructure spending and state-level biogenic-content requirements are restructuring procurement patterns across North American jurisdictions.
United States
Bridge deck rehabilitation and pervious concrete installations drive specification intensity across Michigan, Ohio, and Illinois. The Federal Highway Administration's Buy America provisions require chain-of-custody documentation from forest source to batch plant. Chicago and Detroit metropolitan areas concentrate demand for ASTM C1116-compliant fiber formulations in transportation infrastructure bids.
Canada
Hemp bast fiber extraction capacity scales in Alberta and Saskatchewan to meet public procurement biogenic-content thresholds. Provincial transportation departments in Ontario and Quebec pilot performance-based specifications for alternative reinforcement materials. Toronto's infrastructure procurement increasingly mandates verified sustainable sourcing credentials for concrete additives.
Mexico
Industrial construction in Nuevo León and Mexico City generates demand for plastic shrinkage crack control in large commercial flatwork pours. Federal environmental standards for construction runoff management are tightening compliance requirements for permeable pavement installations. Monterrey's precast concrete sector sources cellulose fibers through cross-border supply chains serving North American automotive manufacturing facilities.
North America Concrete Cellulose Fiber Reinforcement Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the North American concrete cellulose fiber reinforcement supply base. Three strategic archetypes dominate: forest-products conglomerates with captive pulp processing, diversified chemical admixture suppliers bundling fibers into broader portfolios, and regional specialists focused on technical service relationships with ready-mix producers. Competitive moves concentrate on embedding field technicians with batch plant operations and securing multi-year performance-guaranteed supply contracts.
Within the integrated chemical tier, Sika AG and BASF occupy positions that exemplify portfolio bundling strategies, while J. Rettenmaier USA LP represents forest-to-fiber vertical control. These three entities anchor the premium specification segment through technical service infrastructure and documented compliance with federal procurement standards.
| Leading Market Players |
|---|
| J. Rettenmaier USA LP |
| Fiber Technologies Inc. |
| Concrete Protection Technologies LLC |
| Solomon Colors, Inc. |
| Fiberzone India |
| Euclid Chemicals |
| Sika AG |
| BASF |
| Saint Gobain |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day fluff pulp inventory cycles at Great Lakes batch plants concentrate pricing power with southeastern domestic processors who control alkali-resistant grade supply. This lead-time exposure forces infrastructure contractors into premium contract structures that embed supply security premiums, while residential flatwork buyers absorb spot-market volatility through distributor markups.
Pricing Analysis
Great Lakes-to-Southeast fiber spreads of 15-25% reflect freight absorption and qualification documentation costs that Michigan DOT contractors cannot negotiate away. Three-tier pricing structure across ASTM C1116-certified, state-qualification-grade, and commodity residential tiers separates infrastructure bids from slab-on-grade volume plays. Cost compression in wood fiber segments runs through polypropylene substitution pressure from residential specifiers who prioritize first-cost over lifecycle performance. Residential contractors exhibit highest price sensitivity; civil engineers with federal-aid mandates show lowest.
Supply Chain Analysis
Strategic stockpiling of fluff pulp dominates infrastructure procurement while residential distributors run just-in-time wood fiber inventories sensitive to southeastern pulp mill output fluctuations. Supply concentrates in United States southeastern kraft pulping capacity and Canadian Alberta-Saskatchewan hemp bast processing zones. Raw material flows draw from softwood timberland leases, chemical pulping reagents, and agricultural hemp cultivation. Single-source vulnerability sits with the limited domestic fluff pulp processors qualified for ASTM C1116 documentation. Distribution runs through embedded technical service teams at major ready-mix producers who bypass traditional admixture distributors for specification-grade fiber procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synthetic macro-fiber incumbents who exploit specification engineer familiarity and lower first-cost positioning in residential segments.
For Market Incumbents: Secure captive fluff pulp supply through backward integration into southeastern kraft processing or long-term offtake agreements with Georgia-Pacific and International Paper divisions. Lock in multi-year performance-guaranteed supply contracts with Ohio and Michigan DOT contractors before Texas performance-based specifications open pathways for polypropylene competitors. Certification investment in Illinois DOT pilot programs represents the critical defensive lever against reduced-dosage fibrillated fiber displacement. For New Entrants and Emerging Players: Lead with hemp bast fiber biogenic-content credentials to capture Ontario and Quebec public procurement mandates that United States incumbents cannot satisfy without Canadian cultivation partnerships. Target Alberta-Saskatchewan extraction capacity expansion as the most penetrable supply node, bypassing southeastern fluff pulp concentration entirely. Direct-to-contractor digital platforms offer the cleanest go-to-market angle for standardized grades without embedded technical service overhead. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because biogenic-content mandates and Buy America compliance create durable moats around qualified suppliers with documented chain-of-custody systems. Acquisition targets should profile as regional admixture distributors with dormant technical service capabilities that integrated chemical suppliers can activate. The signal to watch is Illinois DOT performance-based specification adoption rates, which would validate engineered-property-over-prescriptive-dosage shifts and reward fiber producers with materials science R&D depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp Processing | Captive supply of ASTM C1116-compliant fiber secures Great Lakes infrastructure bid qualification. |
| Performance-Guaranteed Supply Contracts | Multi-year agreements with Michigan DOT contractors transfer batch optimization risk from ready-mix producers. |
| Hemp Bast Fiber Extraction Scale-Up | Alberta-Saskatchewan capacity expansion satisfies Ontario biogenic-content procurement thresholds. |
| Direct-to-Contractor Digital Platforms | Proprietary e-procurement channels bypass distributor markups for standardized residential grades. |
| EPD and Carbon Accounting Certification | CSA Group-aligned declarations differentiate suppliers in Toronto infrastructure procurement. |
Research Approach
Desk research of FHWA specification databases, state DOT qualification protocols, and EPA Construction General Permit guidance documents preceded structured interviews with ready-mix plant managers, civil engineering specification leads, admixture distributor procurement heads, and cellulose fiber technical service directors. Secondary validation drew from customs trade data, forest products industry association reports, and SEC filings of integrated chemical suppliers. Bottom-up fiber volume estimates by application and state were triangulated against top-down infrastructure spending allocations.
Variance decomposition across fiber type, application criticality, and end-user procurement authority shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include fiber geometry grade, infrastructure versus residential end-use, and civil engineer versus contractor procurement authority. CAGRs were derived from elasticity-adjusted infrastructure spending forecasts and substitution rate assumptions between cellulose and synthetic macro-fibers. Industry-specific inputs incorporated state DOT rehabilitation program announcements and hemp cultivation acreage expansion in Canadian prairie provinces.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure appropriation levels or EPA stormwater standard enforcement intensity would require recalibration. Forecasts reflect assumptions regarding specification engineer acceptance of performance-based protocols and fluff pulp processing capacity expansion timelines. Revision becomes warranted when polypropylene fiber price-performance ratios cross thresholds that trigger residential segment specification switching.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Skirting Board Market