
 Road & Highway Infrastructure Market | 2026-2036
Road & Highway Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Road & Highway Infrastructure Market Analytics
Modular construction packaging is shifting how government agencies procure road and highway infrastructure, with design-build-finance-operate bundles replacing traditional segmented contracts. China Communications Construction Company leverages its integrated engineering-procurement-construction model to dominate multi-billion dollar expressway projects across Asia and Africa. Vinci SA sustains competitive positioning through specialized tunneling expertise and geographic diversification across Europe and the Americas. Skanska AB differentiates via sustainability-certified construction methods that meet tightening environmental procurement standards.
Road and highway infrastructure encompasses the physical structures, pavement systems, traffic control technologies, and ancillary facilities that enable vehicular movement across regional and national networks, typically engineered to withstand axle loads exceeding ten tons and designed for twenty-to-fifty-year service lives. Its primary commercial purpose is reducing logistics costs and travel time for freight and passenger transport while supporting territorial economic integration. Pavements and bridges represent mature, high-volume segments where margin pools concentrate in maintenance and rehabilitation contracts rather than greenfield construction. Smart Traffic Management technology within the technology dimension is attracting disproportionate capital allocation as urban congestion and emissions regulations intensify demand for real-time flow optimization and automated tolling systems.
The Federal Highway Administration enforces structural design standards and environmental review protocols under the National Environmental Policy Act, while state departments of transportation implement Buy America provisions for steel and manufactured products used in federally aided projects. The European Union's F-Gas Regulation and CO2 performance standards for heavy vehicles indirectly shape highway infrastructure demand by accelerating fleet turnover and associated road wear patterns. Stakeholders must monitor how evolving lifecycle assessment requirements and climate resilience mandates recalibrate procurement criteria for materials selection and project delivery methods.
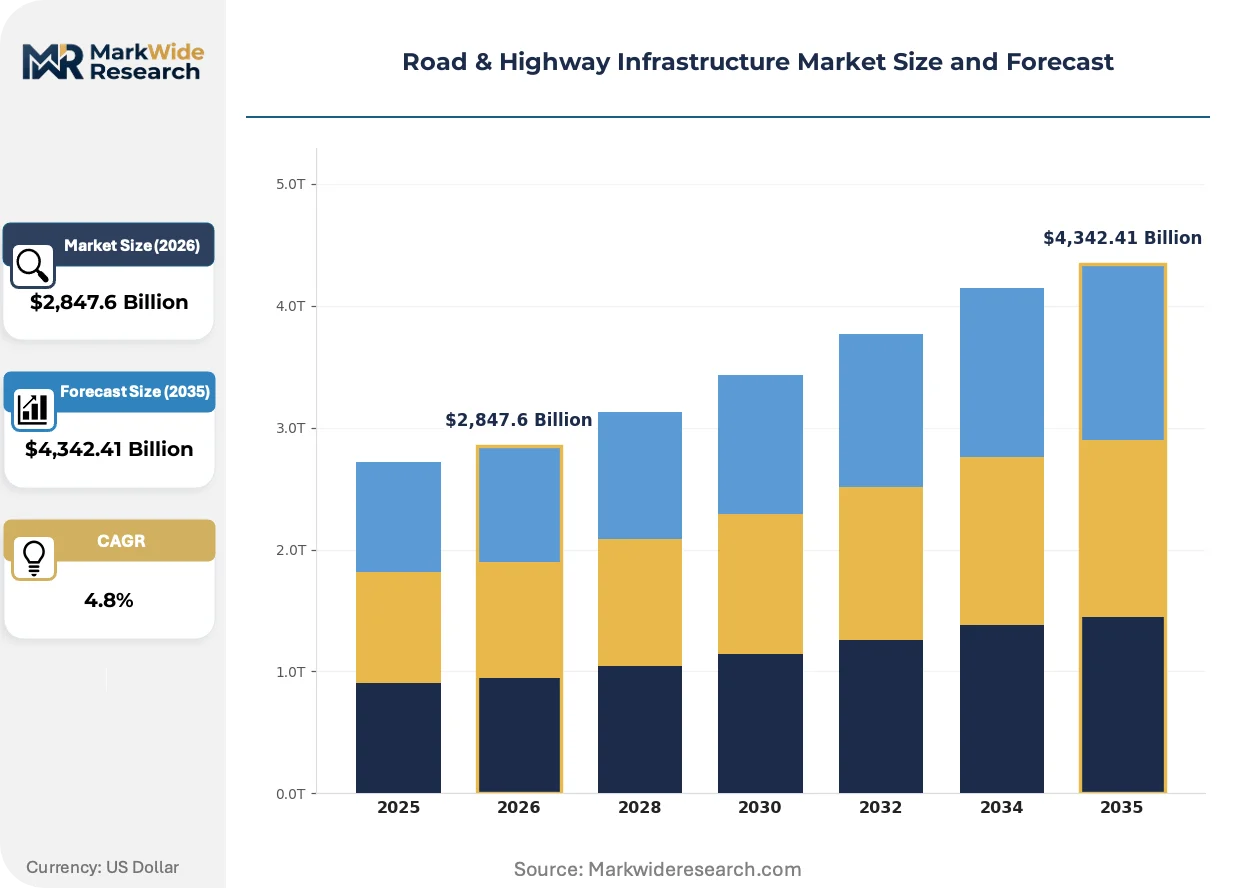
Market Dynamics
Smart Traffic Management technology is absorbing capital allocation across new road projects as urban congestion and emissions mandates intensify demand for real-time flow optimization and automated tolling systems.
Growth Catalysts
- Industrial Corridor Connectivity:Government agencies in India are expanding highway networks to link manufacturing zones. The National Highways Authority continues awarding large-scale expressway contracts to reduce logistics costs.
- Lifecycle Assessment Mandates:The EU Green Deal is recalibrating procurement criteria for materials selection in European road projects. Climate resilience requirements now shape asphalt and concrete specifications.
- Design-Build-Finance-Operate Bundles:Modular construction packaging is replacing traditional segmented contracts. Government procurement departments favor integrated delivery models that transfer operational risk to private consortia.
Market Restraints
- Steel Input Volatility:Buy America provisions under the Federal Highway Administration create cost premiums for federally aided projects. Domestic steel sourcing constraints inflate material budgets.
- Specialized Equipment Concentration:Tunnel boring machine manufacturing concentrates in Germany and Japan. Project delays cascade when equipment availability tightens.
- F-Gas Regulatory Friction:The European Union's F-Gas Regulation restricts refrigerants used in road maintenance vehicles. Fleet compliance costs compress contractor margins.
Strategic Opportunities
- African Expressway Development:Multi-billion dollar corridor projects across East and West Africa remain underpenetrated. Chinese engineering-procurement-construction models demonstrate viable entry pathways.
- Carbon-Neutral Asphalt:Warm-mix and bio-based binder technologies converge with lifecycle assessment requirements. Early certification creates differentiation in European tenders.
- Automated Tolling Convergence:GNSS-based and DSRC tolling systems integrate with urban congestion pricing schemes. Metropolitan authorities in Singapore and London pilot seamless multi-modal payment platforms.
Industry Challenges
- Geotechnical Engineering Talent Scarcity:Specialized foundation design expertise for soft-soil conditions remains concentrated in aging workforces. Emerging markets struggle to staff complex bridge projects.
- Environmental Review Timelines:National Environmental Policy Act compliance cycles extend project initiation by three to five years. Pre-construction capital sits idle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road & Highway Infrastructure Market |
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,342.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridges, Tunnels, Pavements, Signaling Systems Technology: Smart Traffic Management, Geospatial Technology, Construction Materials, Surveillance Systems Application: Urban Roads, Highways, Managed Lanes, Rural Roads End User: Government Agencies, Contractors, Consultants, Public Works Departments |
| Companies Covered | China Communications Construction Company, Vinci SA, ACS Group, Bechtel Corporation, Bouygues Construction, Skanska AB, STRABAG, China State Construction Engineering Corp., Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road & Highway Infrastructure Market Evolving Landscape
Digital twin modeling and predictive maintenance algorithms are transforming how highway authorities manage asset lifecycles. These technologies compress inspection cycles and extend pavement service intervals.
Permeable pavement systems incorporating photocatalytic concrete are absorbing nitrogen oxide emissions from vehicle exhaust. Municipal road departments in Milan and Mexico City deploy these surfaces in high-traffic zones. The technology is absorbing maintenance budget allocations previously directed toward conventional resurfacing.
The EU's Corporate Sustainability Reporting Directive now mandates disclosure of construction material embodied carbon. European departments of transportation embed these requirements into tender evaluation scoring. Steel and cement suppliers with Environmental Product Declarations capture preferential contract terms.
Public-private partnership concession terms are compressing from thirty-year to fifteen-year durations. Institutional investors in Australian and Canadian pension funds favor shorter payback periods with explicit maintenance obligations. This behavioral shift concentrates risk with contractors holding operational expertise.
Road & Highway Infrastructure Market Segmentation
Road and highway infrastructure procurement varies sharply across project types, with design specifications and lifecycle requirements dictating supplier capabilities. Segment-level analysis reveals where margin pools concentrate and which technology layers command premium pricing.
Product Type:
Structural product selection hinges on terrain constraints, traffic load specifications, and maintenance liability allocation between public owners and private operators.
- Bridges:Steel and prestressed concrete superstructures engineered for spans exceeding 50 meters. Demand clusters in India's industrial corridor expansion where the National Highways Authority awards multi-kilometer viaduct contracts across riverine and hilly terrain.
- Tunnels:Bored and cut-and-cover excavations requiring specialized ventilation and fire suppression systems. Alpine crossings in Austria and Norway drive procurement for twin-tube configurations with integrated safety monitoring.
- Pavements:Asphalt and Portland cement concrete surfaces designed for 20-year service intervals.
- Signaling Systems:Variable message displays, lane control signals, and emergency communication networks.
Pavements lead volumes today; tunnels are gaining share fastest.
Technology:
Technology deployment patterns track regulatory pressure intensity, with emissions mandates and congestion pricing schemes accelerating capital allocation toward intelligent systems.
- Smart Traffic Management:Real-time flow optimization platforms integrating AI-driven signal control with automated incident detection. Singapore's Land Transport Authority deploys these systems across expressway networks to enable dynamic congestion pricing.
- Geospatial Technology:LiDAR scanning and satellite-based deformation monitoring for asset condition assessment. European infrastructure managers embed these tools into predictive maintenance contracts under EU Green Deal lifecycle mandates.
- Construction Materials:Warm-mix asphalt, photocatalytic concrete, and carbon-capture cement formulations.
- Surveillance Systems:ANPR cameras, weigh-in-motion sensors, and automated enforcement hardware.
Construction materials lead volumes today; smart traffic management is climbing the fastest.
Application:
Application segments diverge by funding mechanism, with toll-backed managed lanes attracting private finance while rural roads remain dependent on federal aid formulas.
- Urban Roads:Dense network segments requiring coordination with underground utilities and pedestrian infrastructure. Mexico City deploys permeable photocatalytic surfaces in high-traffic zones to absorb nitrogen oxide emissions.
- Highways:Multi-lane arterials designed for speeds exceeding 100 km/h with full access control. China's expressway buildout concentrates procurement volume for asphalt paving and bridge construction.
- Managed Lanes:Tolled express lanes with dynamic pricing and dedicated access points.
- Rural Roads:Low-volume connectors linking agricultural production zones to processing facilities.
Highways lead volumes today; managed lanes are expanding most quickly.
End User:
End-user procurement authority determines contract structure complexity, with centralized agencies favoring design-build-finance-operate bundles while decentralized departments retain segmented bidding.
- Government Agencies:Federal and state departments of transportation setting technical standards and environmental compliance frameworks. The Federal Highway Administration enforces Buy America provisions for steel and manufactured products.
- Contractors:Engineering-procurement-construction firms executing design-build and public-private partnership deliveries. Vinci SA and Skanska AB compete for integrated contracts transferring operational risk to private consortia.
- Consultants:Geotechnical, structural, and environmental advisory firms conducting feasibility studies and construction supervision.
- Public Works Departments:Municipal authorities maintaining local road networks and urban street infrastructure.
Government agencies lead volumes today; contractors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern highway infrastructure industry traces its scalable origins to the United States Interstate Highway System initiated in 1956, which established engineering standards and procurement frameworks later replicated across industrializing economies worldwide.
United States
Federal highway aid formulas and state-managed toll authority bonds drive pavement rehabilitation and bridge replacement cycles. The Federal Highway Administration enforces Buy America provisions for steel and manufactured products, creating cost premiums for domestic sourcing. Texas and California concentrate procurement volume for managed lane expansions and freight corridor upgrades.
China
Provincial expressway buildout and intercity connectivity mandates absorb the majority of global asphalt and concrete volumes. The Ministry of Transport implements dual carbon goals that recalibrate material specifications toward lower-emission binders. The Yangtze River Delta and Pearl River Delta clusters anchor design-build-finance-operate contract awards for multi-kilometer viaducts.
India
National Highways Authority expressway awards and industrial corridor linkages concentrate demand for bridge superstructures and pavement systems. The Ministry of Road Transport and Highways accelerates Bharatmala program implementation with hybrid annuity and toll-operate-transfer models. Gujarat and Maharashtra host the densest contractor mobilization for Delhi-Mumbai Industrial Corridor feeder routes.
Germany
Federal trunk road maintenance backlogs and tunnel safety upgrades sustain specialized engineering demand. The EU Green Deal and F-Gas Regulation shape fleet compliance and material lifecycle assessment requirements for public tenders. Bavaria and Baden-Württemberg concentrate alpine tunneling procurement for cross-border freight corridors.
Saudi Arabia
NEOM linear city infrastructure and Red Sea coastal connectivity projects attract engineering-procurement-construction consortia. The National Infrastructure Fund and Public Investment Commission structure long-term availability payments for transport assets. The Eastern Province and Riyadh anchor cement and steel-intensive highway construction for mining and logistics zones.
Road & Highway Infrastructure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated delivery capability and specialized technical expertise. The vendor base organizes into three tiers: engineering-procurement-construction conglomerates with captive financing arms, regional contractors competing on local regulatory relationships, and niche specialists in tunneling or bridge engineering. Consolidation pressure intensifies as public procurement shifts toward design-build-finance-operate bundles that transfer operational risk. Dominant competitive moves include strategic partnerships with pension funds for concession financing and backward integration into construction materials supply.
Within the integrated delivery tier, China Communications Construction Company and China State Construction Engineering Corp. exemplify state-backed engineering-procurement-construction models that dominate multi-billion dollar expressway awards across Asia and Africa. Vinci SA and Skanska AB occupy positions among European specialists competing for sustainability-certified tenders under tightening lifecycle assessment mandates. Larsen & Toubro anchors Indian contractor capacity for industrial corridor and urban expressway projects.
| Leading Market Players |
|---|
| China Communications Construction Company |
| Vinci SA |
| ACS Group |
| Bechtel Corporation |
| Bouygues Construction |
| Skanska AB |
| STRABAG |
| China State Construction Engineering Corp. |
| Larsen & Toubro |
| Others |
Value Network & Pricing Analysis
Buy America procurement mandates under the Federal Highway Administration are forcing contractors toward domestic steel sourcing that inflates material budgets and compresses bid margins across federally aided projects.
Pricing Analysis
Project-based lump-sum contracting dominates highway infrastructure procurement, with price differentiation resting on contractor bonding capacity and past performance ratings rather than unit cost alone. Three-tier pricing structure across premium, standard, and economy levels separates design-build-finance-operate consortia from traditional segmented bidders from commodity maintenance providers. Cost compression in standard-tier paving contracts is intensifying because warm-mix asphalt adoption adds equipment conversion overhead. Government agencies exhibit highest price sensitivity on rural road segments; toll-backed managed lane operators show lowest sensitivity due to revenue certainty.
Supply Chain Analysis
Single-source vulnerability sits with tunnel boring machine manufacturing concentrated in Germany and Japan, where equipment lead times cascade into project delays when availability tightens. Geographic supply concentration draws from China for cement and steel rebar, India for bitumen and aggregates, and Germany for specialized foundation equipment. Raw material dependencies rest on petroleum-derived asphalt binders, Portland cement clinker, and high-grade structural steel. Tariff exposure on Chinese steel imports under Section 232 provisions creates input cost volatility. Distribution runs through regional materials yards co-located with major corridor projects, with just-in-time delivery contracts minimizing on-site inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible public infrastructure replacement cycles and regulatory mandates for climate-resilient materials.
For Market Incumbents: Deploy captive financing arms to capture concession equity returns as public-private partnership terms compress toward fifteen-year durations. Deepen backward integration into carbon-neutral asphalt production to preempt EU Green Deal procurement scoring advantages. Consolidate regional maintenance contractors to lock in recurring rehabilitation revenue streams as pavement service intervals extend through digital twin optimization. For New Entrants and Emerging Players: Launch via specialized tunneling equipment leasing models targeting East African expressway corridors where Chinese engineering-procurement-construction presence has proven viability but local capacity remains thin. Prioritize carbon-capture cement certification to differentiate in European tenders where Environmental Product Declarations now embed into evaluation scoring. Target hybrid annuity contract structures in India where National Highways Authority awards concentrate and foreign joint venture requirements create partnership entry pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale contractors holding operational expertise in smart traffic management integration, as metropolitan congestion pricing schemes accelerate capital allocation toward intelligent systems. Long-term viability hinges on positioning ahead of lifecycle assessment mandate expansion beyond Europe into Asia-Pacific procurement frameworks. Monitor F-Gas Regulation compliance cost trajectories as a signal for European contractor margin inflection and consolidation pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Construction Materials | Captive cement and asphalt supply secures margin control under volatile input cost regimes. |
| Smart Traffic Management Platform Acquisition | AI-driven signal control capabilities differentiate bids for urban congestion pricing mandates. |
| African Expressway Joint Venture Formation | Chinese EPC partnership structures demonstrate viable entry pathways for underpenetrated corridors. |
| Carbon-Neutral Material Certification Program | Environmental Product Declarations capture preferential tender terms under EU Green Deal scoring. |
| Predictive Maintenance Service Contract Expansion | Digital twin algorithms compress inspection cycles and extend recurring revenue from asset management. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged project finance directors at infrastructure funds, procurement officers at national highways authorities, plant managers at construction materials suppliers, and EPC contract executives at integrated delivery firms. Secondary sources drew from Federal Highway Administration project databases, EU tender portal records, Ministry of Transport filings in China and India, and customs data on steel and cement trade flows. Bottom-up project pipeline aggregation and top-down macroeconomic elasticity models were triangulated for convergence.
Rate-of-change decomposition across the analysis window separates volume growth in lane-kilometers added from value growth in technology content per kilometer. Segmentation dimensions modeled include product type, technology layer, application context, and end-user procurement authority, with additional disaggregation by contract structure complexity and financing mechanism. CAGRs were derived from elasticity-adjusted public capital expenditure forecasts and private concession investment momentum. Industry-specific inputs incorporated asphalt price indices, steel futures curves, and equipment utilization rates from foundation engineering specialists.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged environmental review timelines or sudden shifts in Buy America enforcement intensity. Forecasts reflect assumptions on public budget continuity, commodity price normalization, and regulatory mandate implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Canada Commercial Construction Market