
 Bed Headwall Systems Market | 2026-2036
Bed Headwall Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Headwall Systems Market Analytics
Integration of IoT-enabled monitoring interfaces into headwall architectures is reshaping how medical gas, power, and data converge at the patient bedside. Drägerwerk AG & Co. KGaA leverages its respiratory therapy heritage to anchor premium positions in critical care configurations. Amico Group of Companies sustains broad manufacturing scale across North American hospital networks. Stryker Corporation competes through surgical suite adjacencies that extend into patient room infrastructure.
Bed headwall systems are wall-mounted clinical service panels that consolidate medical gas outlets, electrical receptacles, nurse call interfaces, and lighting into a single patient-facing unit, typically manufactured from aluminum extrusions or antimicrobial-coated steel with sealed gasket construction to support infection control protocols. Their primary purpose is to centralize life-support utilities while enabling rapid clinician access during emergency response. Integrated headwalls command the highest value per unit due to factory-preconfigured utility bundles that reduce field installation labor. Modular headwalls represent the fastest-growing product configuration as retrofit-driven hospitals seek phased upgrade paths without full room closures. Electrical systems and medical gas systems together constitute the core technology stack where specification decisions lock in vendor relationships.
FDA 510(k) clearance requirements for devices incorporating electrical patient monitoring interfaces shape product development timelines and design documentation burdens for manufacturers serving US acute care markets. The EU Medical Device Regulation (MDR) and CE marking obligations under the EU Green Deal's embodied carbon tracking provisions are simultaneously tightening compliance scope for European shipments. Stakeholders must monitor how evolving interoperability standards between headwall-integrated communication systems and electronic health record platforms will determine specification authority shifts from facilities managers to chief medical information officers.
Market Dynamics
Hospital infrastructure modernization is compressing replacement cycles for clinical service panels as facilities prioritize integrated patient room ecosystems over standalone utility installations. The convergence of medical gas, power, and data at the bedside is forcing specification authority shifts from facilities managers to clinical informatics leadership.
Growth Catalysts
- US CMS Reimbursement Frameworks:Value-based care metrics are accelerating capital equipment procurement for acute care facilities seeking operational efficiency gains. Hospital systems prioritize integrated headwall configurations to reduce clinical workflow friction.
- Germany Hospital Digitization:Federal programs prioritizing connected clinical environments are concentrating demand for IoT-enabled monitoring interfaces within headwall architectures. Procurement timelines compress as digitization mandates harden.
- Modular Retrofit Configurations:Phased upgrade paths without full room closures are displacing traditional rip-and-replace installations. Healthcare facilities facing occupancy constraints favor modular product architectures.
Market Restraints
- Aluminum Input Volatility:Extrusion-grade aluminum price swings compress manufacturing margins for aluminum-dominant product lines. Cost pass-through mechanisms face resistance from hospital procurement committees.
- EU MDR Compliance Burden:CE marking obligations under the EU Medical Device Regulation extend design documentation timelines for manufacturers serving European acute care markets. Smaller vendors lack regulatory affairs bandwidth.
- Integrated System Substitution:Ceiling-mounted service pendants in surgical and critical care environments compete for specification in high-acuity settings. Pendant manufacturers leverage existing surgeon relationships.
Strategic Opportunities
- India Healthcare Infrastructure Expansion:Greenfield hospital construction under national health mission programs creates first-mover positioning for integrated headwall suppliers. Public-private partnership models concentrate procurement authority.
- EHR Interoperability Mandates:Evolving connectivity standards between headwall-integrated communication systems and electronic health record platforms create specification influence opportunities for clinical informatics vendors.
- Antimicrobial Coating Convergence:Integration of copper-alloy surfaces with sealed gasket construction addresses infection control protocols while differentiating premium product tiers. Coating technology licensors seek headwall manufacturing partnerships.
Industry Challenges
- FDA 510(k) Timeline Compression:Devices incorporating electrical patient monitoring interfaces face extended clearance cycles that delay product launches. Documentation requirements strain regulatory affairs staffing.
- Legacy Nurse Call Integration:Proprietary communication protocols in installed base systems complicate interoperability with next-generation headwall architectures. Field engineering costs escalate for hybrid installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Headwall Systems Market |
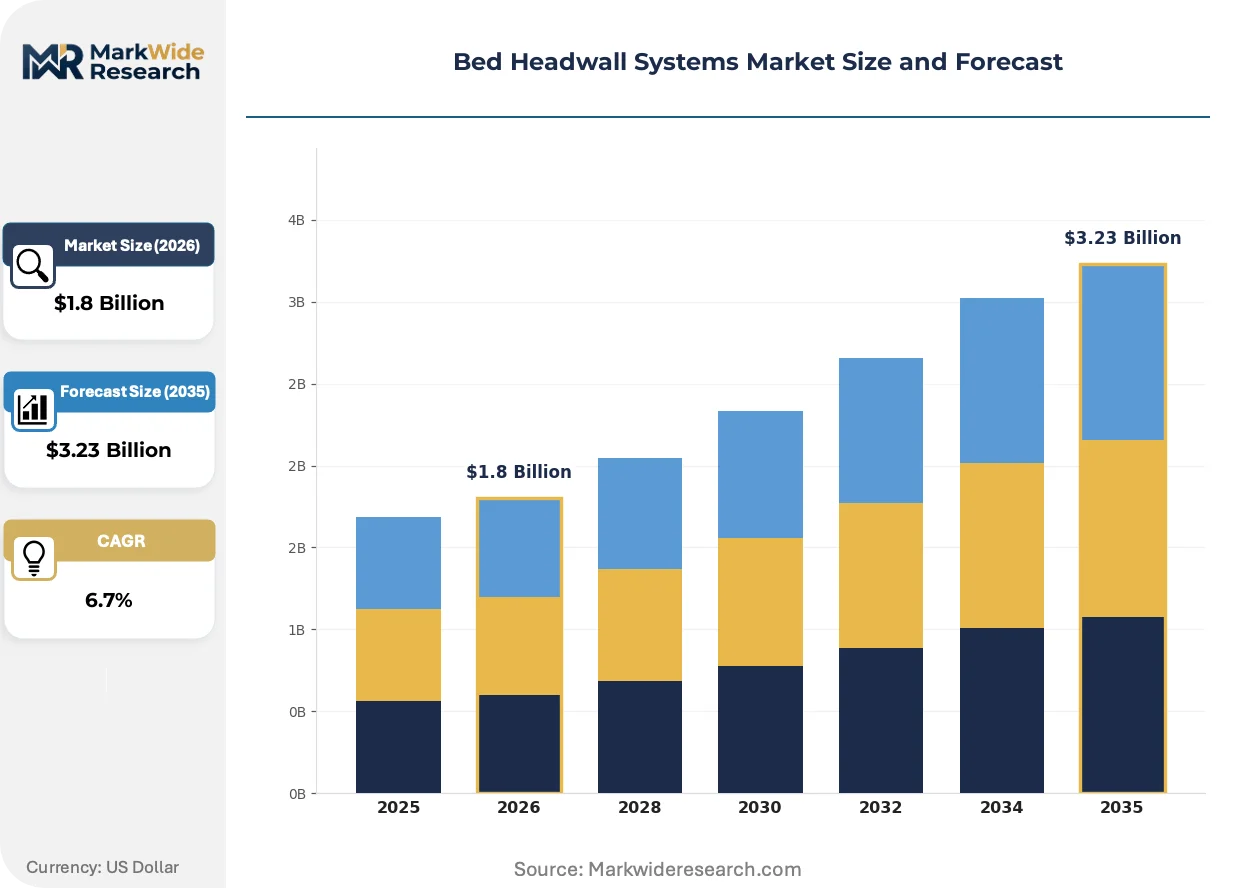
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Headwalls, Standard Headwalls, Modular Headwalls, Custom Headwalls Application: Hospitals, Clinics, Rehabilitation Centers, Long-term Care Facilities End User: Healthcare Providers, Facility Managers, Contractors, Architects Technology: Electrical Systems, Medical Gas Systems, Lighting Systems, Communication Systems |
| Companies Covered | Drägerwerk AG & Co. KGaA, Amico Group of Companies, Hill-Rom Holdings, Stryker Corporation, Schönn Medizintechnik GmbH, Static Systems, Herco Wassertechnik, BeaconMedaes, Tri-Tech Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Headwall Systems Market Evolving Landscape
Bedside clinical environments are undergoing fundamental reconfiguration as digital infrastructure displaces analog utility distribution. Three converging forces are reshaping how medical gas, power, and data converge at the point of care.
IoT-enabled sensor arrays embedded within headwall extrusions are digitizing real-time utility status monitoring and predictive maintenance workflows. Critical care facilities in Germany and the US are adopting these configurations fastest. The technology is digitizing service contract structures toward uptime-guarantee models that transfer operational risk to manufacturers.
The EU Green Deal's embodied carbon tracking provisions are tightening material provenance documentation requirements for European shipments. Manufacturers must now certify aluminum sourcing and coating chemistry through third-party verification. German hospital procurement frameworks are most aggressively embedding these criteria into specification templates.
Acute care facilities are consolidating vendor relationships through single-source contracting for integrated room ecosystems. Group purchasing organizations are displacing individual hospital negotiations. This concentration is most visible in US health system networks where standardization across facility portfolios drives volume commitments.
Bed Headwall Systems Market Segmentation
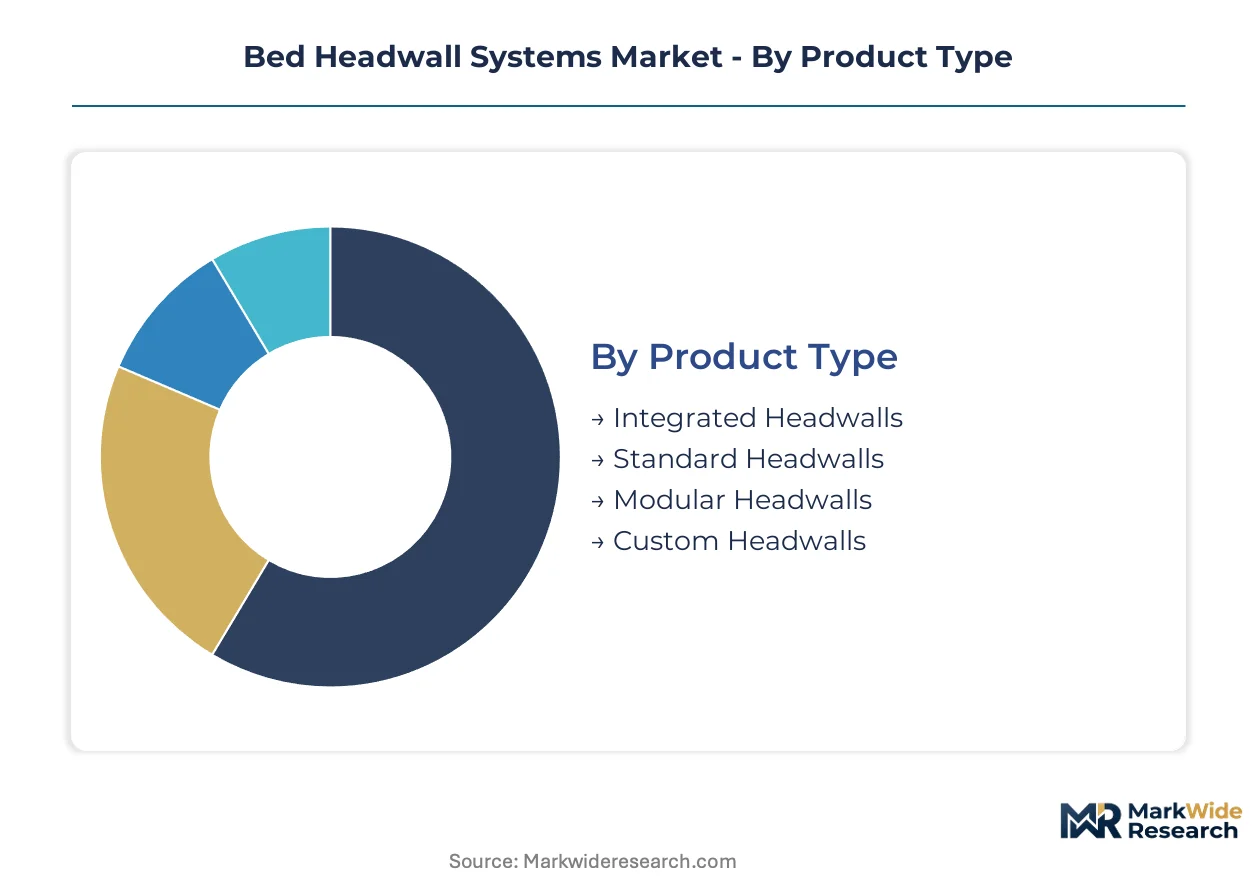
Bed headwall systems fragment across four distinct category axes, each governing different specification decision points in hospital procurement workflows. Product architecture and application setting together determine installation complexity, while end-user authority and technology stack composition shape vendor selection criteria.
Product Type:
After-sales-service intensity varies sharply across product architectures, with integrated systems demanding factory-trained technician networks and modular configurations requiring flexible field support models.
- Integrated Headwalls:Factory-preconfigured utility bundles consolidate medical gas, power, and data into sealed aluminum extrusion assemblies. Demand concentrates in US acute care facilities seeking reduced installation labor under CMS value-based procurement timelines. These configurations command premium pricing but lock hospitals into single-source service contracts.
- Modular Headwalls:Phased upgrade paths enable retrofit-driven hospitals to modernize patient rooms without full closures. German hospital digitization programs favor these configurations for their interoperability with evolving IoT monitoring standards. This architecture expands most quickly as occupancy-constrained facilities prioritize incremental deployment.
- Standard Headwalls:Fixed utility configurations serve budget-constrained clinic and long-term care environments with predictable clinical workflows.
- Custom Headwalls:Architect-specified designs address unique room geometries in flagship medical center construction projects.
By volume, standard headwalls lead due to broad clinic penetration. By growth pace, modular configurations are climbing the fastest.
Application:
Capital allocation intensity separates application tiers, with hospitals deploying comprehensive integrated systems while outpatient settings prioritize electrical and lighting fundamentals.
- Hospitals:Acute care facilities specify the full technology stack including medical gas and communication interfaces, with procurement authority shifting from facilities managers to chief medical information officers under EHR interoperability mandates. US health system networks concentrate purchasing through group purchasing organization contracts.
- Clinics:Outpatient settings emphasize electrical receptacles and nurse call connectivity over medical gas infrastructure, with faster replacement cycles driven by leasehold improvement budgets rather than capital planning cycles.
- Rehabilitation Centers:Patient mobility requirements drive demand for lower-mounted utility configurations with enhanced lighting controls.
- Long-term Care Facilities:Medicaid reimbursement constraints limit specification to basic electrical and lighting systems with minimal communication integration.
By installed base, hospitals dominate. By expansion trajectory, rehabilitation centers are gaining share fastest as post-acute care networks extend regional footprints.
End User:
Specification authority fragmentation creates complex sales cycles requiring distinct technical documentation for clinical, operational, and design stakeholders.
- Healthcare Providers:Clinical leadership drives integrated system selection based on workflow efficiency and patient safety protocols, with German hospital digitization programs embedding their preferences into federal procurement templates.
- Facility Managers:Maintenance cost projections and service contract structures dominate their evaluation criteria, particularly for aluminum-dominant product lines facing input price volatility.
- Contractors:Installation labor minimization favors factory-preconfigured systems that reduce field wiring and gas line termination complexity.
- Architects:Aesthetic integration with room design schemes and antimicrobial surface specifications influence their specification authority in greenfield construction.
By decision frequency, facility managers lead. By influence expansion, healthcare providers are extending their authority fastest as clinical informatics reshapes procurement.
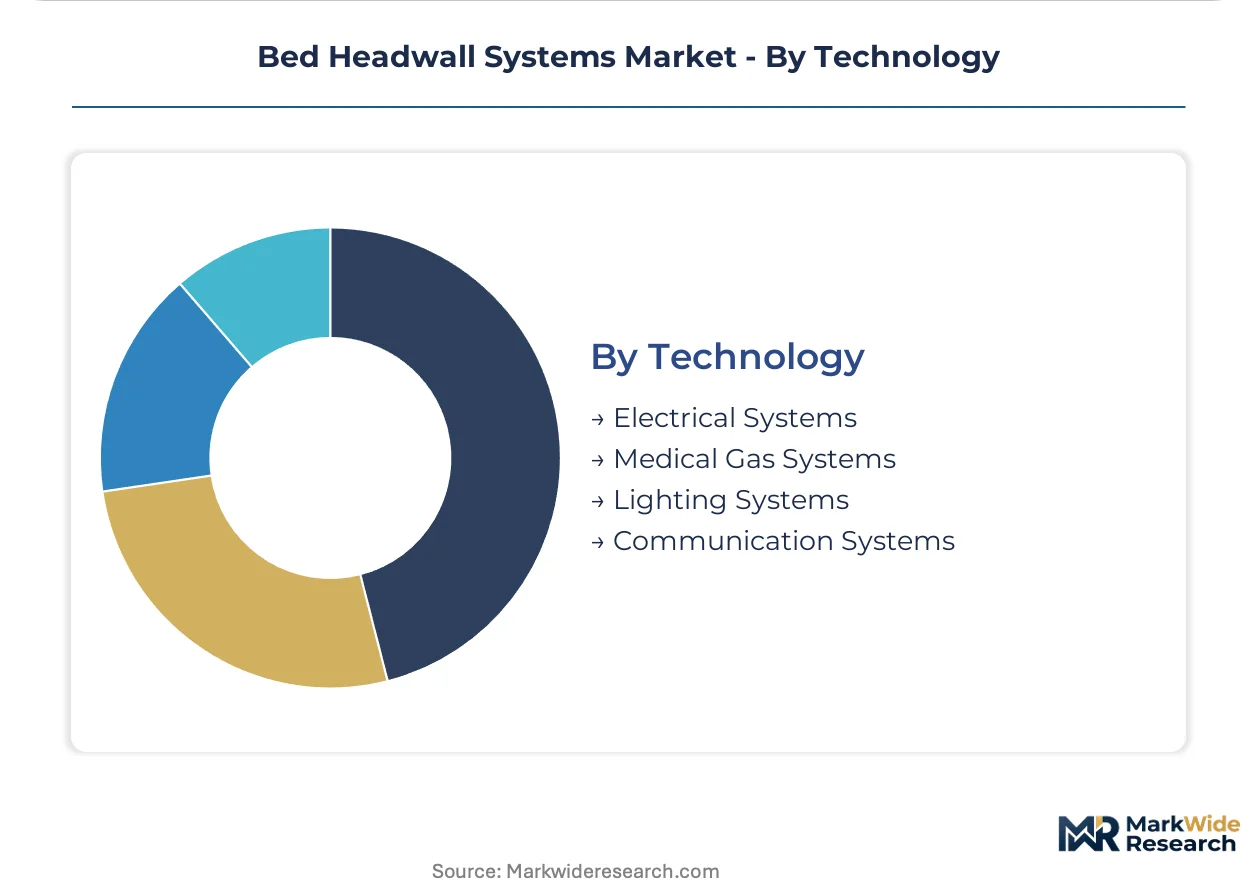
Technology:
Regulatory compliance burden concentrates in electrical and medical gas systems, where FDA 510(k) and EU MDR requirements extend design documentation timelines.
- Electrical Systems:Receptacle configurations and patient monitoring interfaces face FDA clearance requirements that strain manufacturer regulatory affairs staffing, with 510(k) timeline compression delaying product launches for devices incorporating bedside monitoring connectivity.
- Medical Gas Systems:Oxygen, vacuum, and air outlet specifications anchor critical care configurations, with German hospitals prioritizing connected gas monitoring under federal digitization mandates.
- Lighting Systems:LED integration with circadian rhythm programming addresses patient recovery protocols in premium installations.
- Communication Systems:Nurse call and EHR interoperability interfaces face legacy protocol integration challenges that escalate field engineering costs for hybrid installations.
By specification lock-in, electrical systems lead. By development priority, communication systems are advancing fastest as interoperability mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of bed headwall systems track hospital construction cycles and regulatory alignment, with surplus capacity in German and US manufacturing bases supplying digitization-driven demand across European and Asian markets. Import dependency concentrates in emerging healthcare infrastructure markets where domestic fabrication lacks medical-grade certification bandwidth.
United States
CMS value-based reimbursement frameworks compress capital equipment procurement timelines for acute care facilities seeking operational efficiency certification. FDA 510(k) clearance requirements for integrated monitoring interfaces extend design documentation burdens for manufacturers serving this market. Texas Medical Center and Cleveland Clinic anchor specification authority shifts toward clinical informatics leadership in their expansion projects.
Germany
Federal hospital digitization programs prioritize connected clinical environments with IoT-enabled monitoring interfaces embedded in headwall architectures. EU MDR and CE marking obligations under the EU Green Deal tighten material provenance documentation for aluminum sourcing and coating chemistry. Berlin-Brandenburg and North Rhine-Westphalia concentrate procurement through standardized federal templates that favor modular retrofit configurations.
India
National health mission programs drive greenfield hospital construction under public-private partnership models that concentrate procurement authority. CDSCO medical device regulations and BIS standards for electrical safety create compliance thresholds for imported systems. Maharashtra and Karnataka absorb first-mover integrated headwall deployments in their tertiary care expansion corridors.
China
Hospital infrastructure modernization accelerates procurement of integrated patient room systems under national healthcare reform timelines. NMPA medical device registration and GB standards for medical gas distribution shape product localization requirements. Yangtze River Delta and Pearl River Delta clusters dominate domestic manufacturing scale for aluminum extrusion-based clinical service panels.
Japan
Aging facility replacement cycles and infection control protocol upgrades drive specification of antimicrobial-coated steel headwall configurations. PMDA and METI coordination on medical device interoperability standards influences EHR integration requirements. Kanto and Kansai regions concentrate demand through university hospital network procurement standardization.
Bed Headwall Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: respiratory therapy heritage players, broad-scale manufacturing networks, and surgical suite adjacency extenders. Tier-one positions require factory-preconfigured utility bundles and factory-trained technician service networks. Tier-two competitors compete on modular retrofit flexibility and field installation labor reduction. Dominant competitive moves include single-source contracting for integrated room ecosystems and antimicrobial coating technology licensing partnerships.
Within the heritage medical technology tier, Drägerwerk AG & Co. KGaA and Stryker Corporation exemplify divergent strategic anchors—one leveraging respiratory therapy lineage for critical care positioning, the other extending surgical suite relationships into patient room infrastructure. Amico Group of Companies occupies a position within the North American manufacturing scale archetype, sustaining broad distribution across hospital network procurement frameworks. Schönn Medizintechnik GmbH represents the specialized German fabrication segment serving federal digitization program specifications.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Amico Group of Companies |
| Hill-Rom Holdings |
| Stryker Corporation |
| Schönn Medizintechnik GmbH |
| Static Systems |
| Herco Wassertechnik |
| BeaconMedaes |
| Tri-Tech Medical |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margins for aluminum extrusion shipments while amplifying price differentiation between integrated factory-preconfigured systems and modular field-assembled alternatives. Supply concentration in German and US manufacturing bases feeds downstream pricing power toward vendors with captive technician networks, whereas Asian procurement committees extract concessions from distributors lacking direct service capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under FDA 510(k) and EU MDR pathways separates premium integrated headwalls from standard modular configurations, while volume scale and after-sales bundling differentiate mid-tier offerings. Pricing pressure stems from aluminum input volatility that resists full pass-through to hospital procurement committees. Clinic and long-term care facilities exhibit highest price sensitivity due to Medicaid reimbursement constraints, whereas US health system networks prioritize standardization over unit cost minimization.
Supply Chain Analysis
Extended payment terms from German hospital procurement frameworks and supply-chain finance facilities anchored in North American GPO contracts shape working capital structures for extrusion-grade aluminum sourcing. Manufacturing concentrates in Germany, the United States, and China, with the Yangtze River Delta clusters dominating domestic scale for aluminum extrusion-based clinical service panels. Raw material dependencies center on extrusion-grade aluminum, antimicrobial coating chemistries, and sealed gasket polymers. Single-source vulnerability concentrates in respiratory therapy heritage players controlling critical care gas outlet specifications. Distribution runs through factory-trained technician networks for integrated systems and flexible regional distributors for modular configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital infrastructure modernization cycles position this market for recovery as deferred replacement demand from occupancy-constrained facilities releases into procurement pipelines. Federal digitization mandates in Germany and CMS value-based frameworks in the US compress decision timelines and concentrate specification authority.
For Market Incumbents: Harden factory-preconfigured utility bundles against modular retrofit substitution by embedding IoT-enabled monitoring interfaces that lock in single-source service contracts. Extend captive technician networks into India and Southeast Asia before greenfield hospital construction consolidates around regional fabrication. CE marking bandwidth under EU MDR functions as a defensive moat against smaller competitors lacking regulatory affairs scale.
For New Entrants and Emerging Players: Mid-market rehabilitation centers in North American post-acute care networks represent the most penetrable entry point given their patient mobility requirements and lower certification burden relative to acute care. India's public-private partnership hospital construction under national health mission programs offers first-mover positioning before procurement authority concentrates. A go-to-market angle through antimicrobial coating technology licensing partnerships bypasses direct manufacturing scale requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology parents where headwall systems constitute non-core patient room infrastructure divisions. Long-term viability over a multi-year horizon rests on clinical informatics integration capabilities rather than standalone utility manufacturing. The signal to watch is specification authority shifts from facilities managers to chief medical information officers, which elevates software interoperability valuation above hardware margins.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance timelines for integrated monitoring interfaces determine competitive entry sequencing in US acute care. |
| CE Marking Under EU MDR | Documentation burdens under EU Green Deal carbon tracking provisions filter smaller vendors from European procurement. |
| Hospital System Partnership | Single-source contracting for integrated room ecosystems locks in volume commitments across US health network portfolios. |
| Software Companion Development | EHR interoperability mandates elevate clinical informatics vendors to specification authority in procurement workflows. |
| Reimbursement Strategy Alignment | CMS value-based care metrics accelerate capital equipment procurement for operational efficiency certification. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with hospital procurement committees, biomedical engineers, GPO contracts managers, and clinical informatics officers; and secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS reimbursement framework documentation. Bottom-up triangulation across product architecture segments and top-down cross-check against federal digitization program budgets anchored volume and value estimates.
Forecast inputs span integrated versus modular product configurations, hospital versus clinic application settings, and technology stack composition across electrical, medical gas, lighting, and communication systems. CAGRs derive from replacement cycle compression analysis and procurement timeline elasticity under reimbursement mandate pressure. Aluminum input price volatility curves and regulatory documentation timeline assumptions feed scenario boundaries.
Macroeconomic conditions sit as an overlay; deviation in hospital construction lending rates or healthcare infrastructure fiscal transfers would shift the trajectory. Forecasts reflect documented assumptions on digitization mandate hardening and interoperability standard adoption. Regulatory timeline extensions under FDA or EU MDR pathways, or supply disruption in extrusion-grade aluminum markets, would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market