
 Wood Shingles Market | 2026-2036
Wood Shingles Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Shingles Market Outlook
Residential roofing is pivoting toward heritage aesthetics and carbon-sequestering materials, pulling wood shingles back into specification cycles after decades of synthetic dominance. CertainTeed leverages extensive distribution networks to sustain contractor loyalty across North American markets. GAF competes through integrated roofing systems that bundle underlayment with shingle packages. Malarkey Roofing Products differentiates via polymer-modified asphalt adjacent lines that position the firm at the intersection of traditional and engineered roofing.
Wood shingles are thin, tapered pieces of timber, typically cedar, pine, or red oak, split or sawn to precise thickness gradients and installed in overlapping courses to shed water. Cedar shingles, prized for natural preservatives like thujaplicin, dominate premium residential applications where dimensional stability and insect resistance justify higher material costs. Pine shingles occupy the fastest-growing volume tier among budget-conscious renovation projects, while fire-retardant treatment types command the widest margin pools due to code-mandated upgrades in wildfire-prone zones. DIY installations remain structurally constrained by skilled-labor requirements and permitting complexity, limiting mass-market penetration despite retail availability.
The National Fire Protection Association's Class A and Class B ratings, enforced by local building departments across California and Colorado, dictate treatment-type demand and effectively filter untreated products from high-risk geographies. EPA guidelines on volatile organic compound emissions from pressure-treatment chemicals further constrain formulation choices and supplier qualification. Stakeholders must monitor evolving wildfire-urban-interface ordinances and treatment-chemical registration statuses to anticipate product-line obsolescence and replacement-cycle timing.
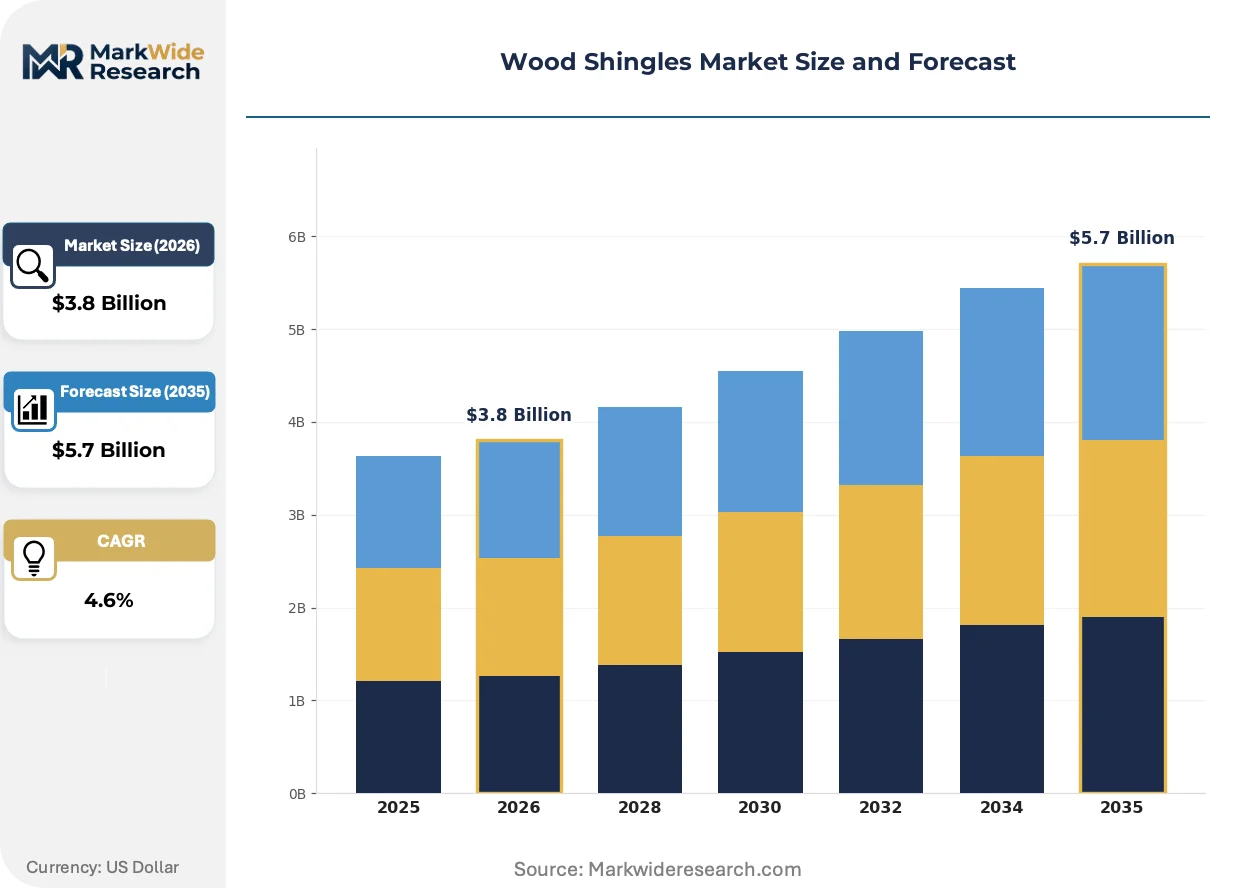
Market Dynamics
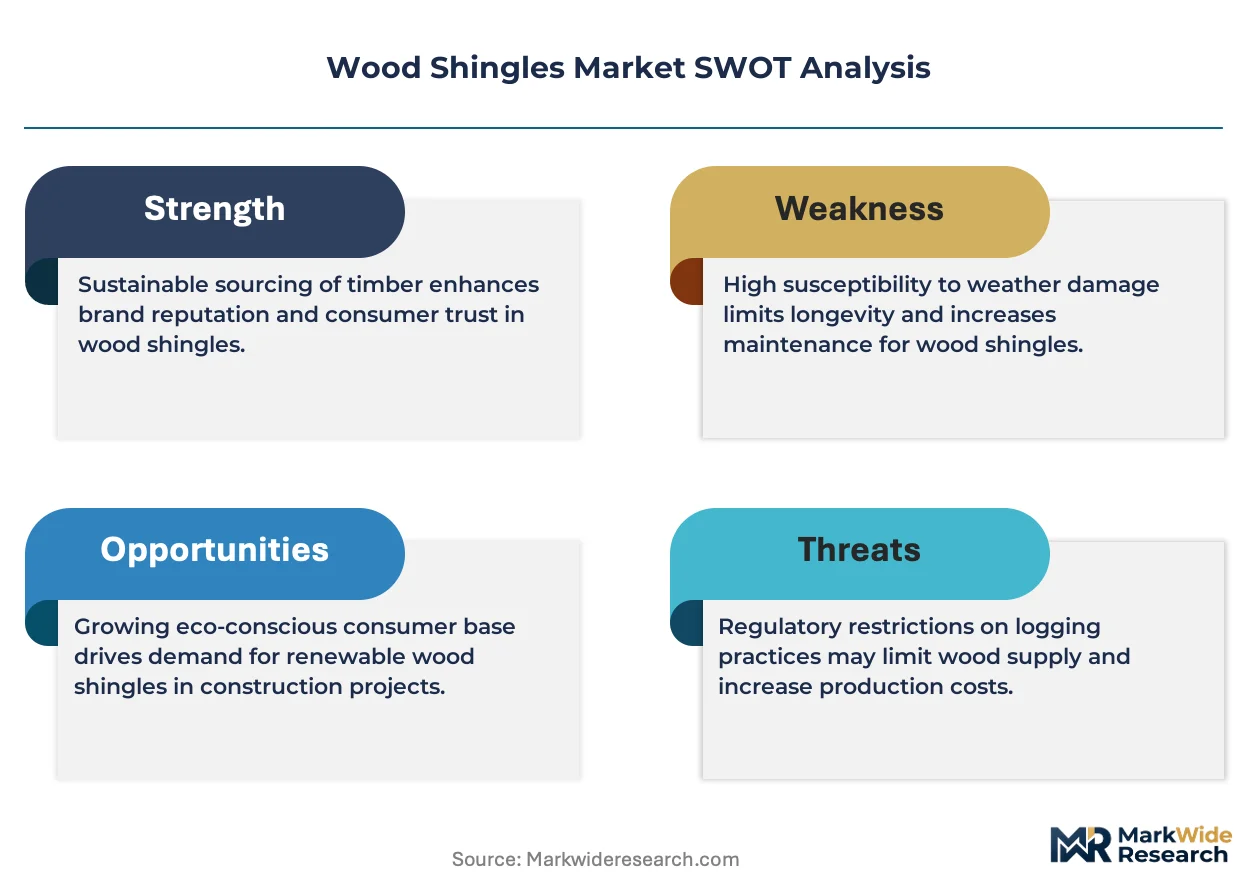
California's Title 24 wildfire-urban-interface ordinances and EPA volatile organic compound emission limits are compressing untreated wood shingle supply while accelerating fire-retardant treatment capacity investments across Pacific Northwest manufacturing clusters.
Growth Catalysts
- Heritage Preservation Mandates:Historic district commissions in Massachusetts and Oregon are specifying cedar shingles for restoration projects, creating code-protected demand pools insulated from synthetic substitution.
- Carbon Sequestration Accounting:Architects pursuing LEED v4.1 and Passive House certification are specifying biomass-based cladding to offset embodied carbon in structural systems.
- Proximity Sourcing Economics:British Columbia and Washington State mill operations benefit from captive western red cedar supply chains that compress landed costs for coastal construction markets.
Market Restraints
- Feedstock Cost Volatility:Old-growth western red cedar harvest restrictions under British Columbia's Old Growth Strategic Review are constraining premium grade supply and inflating raw material input costs.
- Substitution Pressure:Polymer-modified asphalt shingles and fiber-cement composites are capturing specification share in wildfire-prone Colorado and Arizona markets where Class A ratings are mandatory.
- Treatment Chemical Registration:EPA re-registration timelines for ammonium polyphosphate and boron-based retardants are creating formulation uncertainty and supplier qualification bottlenecks.
Strategic Opportunities
- Underpenetrated Mountain West:Montana and Idaho residential markets show cedar shingle penetration below 3% despite compatible architectural vernacular and expanding high-net-worth second-home construction.
- Prefabricated Panel Integration:Offsite construction manufacturers are specifying pre-cut shingle courses for panelized wall systems, opening industrial procurement channels beyond traditional roofing contractors.
- Incentive-Aligned Retrofit:California's Self-Generation Incentive Program and property-assessed clean energy financing are bundling fire-hardened roofing with solar and battery upgrades in wildfire mitigation packages.
Industry Challenges
- Skilled Installer Scarcity: Master shingle mechanics capable of woven valleys and custom sidewall integration are retiring faster than apprenticeship programs in Maine and Vermont can replenish.
- Permitting Timeline Compression: Local fire marshal plan review backlogs in Los Angeles and San Diego counties are extending project starts by 8-14 weeks, straining contractor cash flow and customer retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Shingles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cedar Shingles, Pine Shingles, Red Oak Shingles, Walnut Shingles Application: Residential Roofing, Commercial Roofing, Siding, Outdoor Structures Installation Type: New Construction, Renovation, Repair, DIY Installations Treatment Type: Untreated, Pressure-Treated, Fire-Retardant, Algae-Resistant |
| Companies Covered | Owens Corning, TAMKO Building Products, Malarkey Roofing Products, Decra Roofing Systems, Atlas Roofing Corporation, CertainTeed, IKO Industries, PABCO Roofing Products, GAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Shingles Market Strategic Shifts
Material science advances and procurement model fragmentation are bifurcating the wood shingle value chain between artisanal heritage craft and engineered performance systems.
Pressure-impregnated fire-retardant treatments are expanding into Class A-rated product tiers previously dominated by mineral-surfaced asphalt and metal roofing systems. Custom home builders in Marin County and Santa Barbara are specifying these treatments for primary residences at 40% premium over untreated cedar. The technology is expanding into insurance-mandated retrofit markets where carriers are conditioning renewal coverage on roof assembly fire ratings.
California's Title 24 Part 11 wildfire-urban-interface standards are mandating Class A or Class B roof assembly ratings in designated high-severity zones, effectively prohibiting untreated wood shingles from new construction and major renovations. Manufacturers are responding with proprietary treatment formulations that maintain dimensional stability while meeting extended weathering exposure tests. Colorado's adoption of similar WUI codes is extending this regulatory geography northward along the Front Range.
Builder procurement of roofing packages is consolidating under national production homebuilders who negotiate master purchasing agreements with integrated system suppliers. Regional distributors serving custom builders and renovation contractors are losing specification influence to direct manufacturer-contractor relationships. This concentration is most visible in Seattle and Portland metropolitan markets where Lennar and D.R. Horton operations are standardizing shingle-brand specifications across subdivision portfolios.
Wood Shingles Market Segmentation
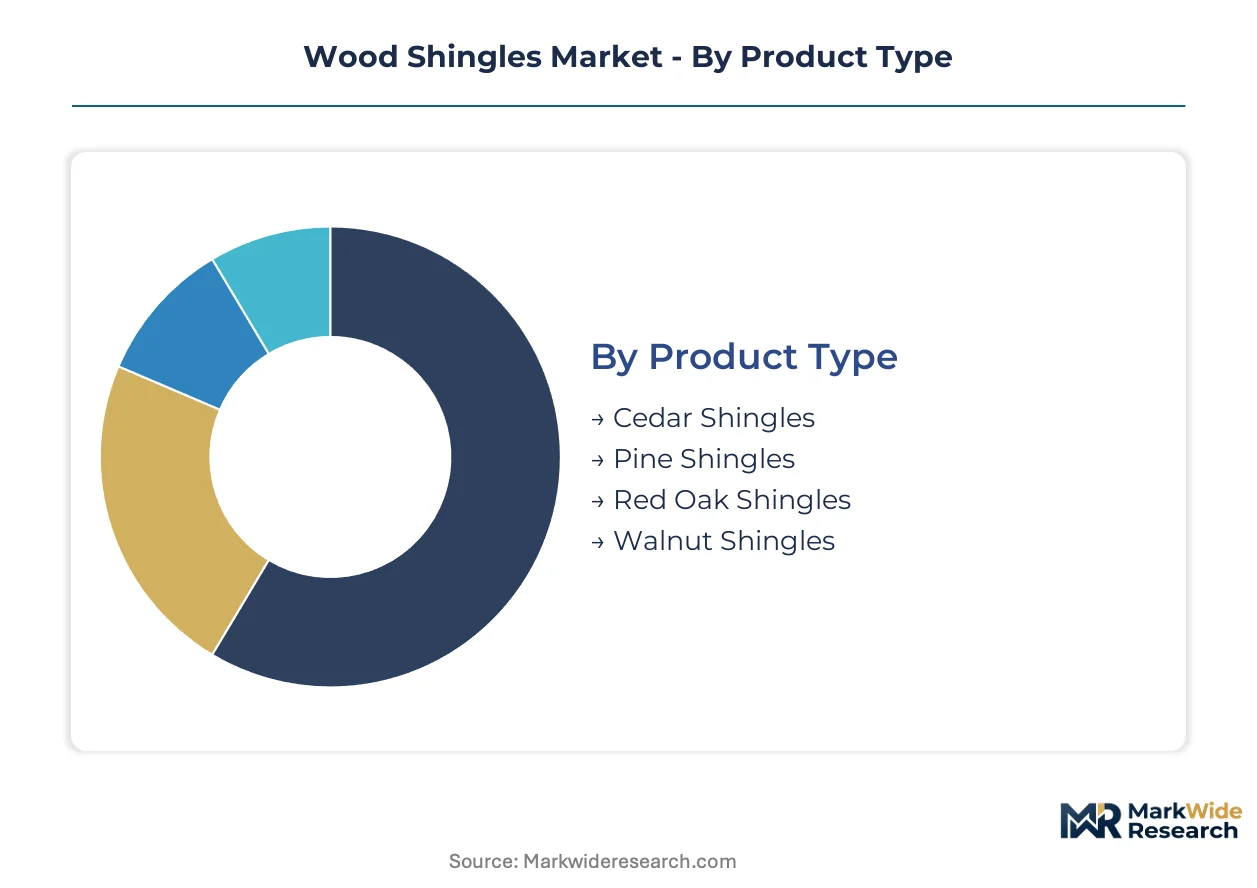
Wood shingle segmentation reveals divergent capital requirements across treatment technologies and installation channels. Product differentiation concentrates margin capture in fire-retardant and cedar grades, while application mix determines geographic exposure to regulatory risk.
Product Type:
Capital intensity peaks in cedar processing, where kiln-drying equipment and grading infrastructure demand seven-figure upfront investment. Pine and oak operations run leaner with lower barrier-to-entry sawmill configurations.
- Cedar Shingles:Western red cedar contains natural thujaplicin preservatives that deliver dimensional stability without chemical additives. Demand clusters in Pacific Northwest heritage districts and Marin County custom builds where untreated premiums justify material costs. British Columbia's Old Growth Strategic Review is constraining premium-grade feedstock and inflating input costs for coastal manufacturers.
- Pine Shingles:Eastern white pine offers the lowest unit cost among viable roofing timbers, positioning this segment for renovation-driven volume expansion. Budget-conscious contractors in Maine and Vermont specify pine for secondary structures and accessory buildings where longevity requirements moderate.
- Red Oak Shingles:Dense grain structure provides impact resistance for Midwest applications, though tannin bleeding complicates finish compatibility.
- Walnut Shingles:Dark coloration and fine texture command specialty architectural specification in high-end Chicago and Minneapolis residential markets.
Most installed capacity flows through Cedar Shingles. Expansion is steepest in Pine Shingles.
Application:
Revenue per square foot varies threefold across applications, with siding and commercial roofing requiring specialized fastening systems and moisture-management detailing that elevate contractor qualification thresholds.
- Residential Roofing:Steep-slope installation dominates volume, with woven valleys and sidewall integration demanding master mechanic skill levels. California's Title 24 wildfire-urban-interface codes are filtering untreated products from new construction in Los Angeles and San Diego counties, redirecting specification toward fire-retardant assemblies.
- Commercial Roofing:Low-slope compatibility limitations constrain wood shingle penetration to architectural accent applications on hospitality and institutional buildings. Insurance carriers are conditioning renewal coverage on Class A assembly ratings, accelerating retrofit demand in Santa Barbara and Marin County.
- Siding:Horizontal exposure courses require rain-screen detailing and drainage-plane integration that elevate material and labor costs above vinyl and fiber-cement alternatives.
- Outdoor Structures:Pergolas, gazebos, and accessory buildings tolerate lower-grade material and simplified installation protocols, opening retail and e-commerce distribution channels.
Residential Roofing absorbs the majority of production volume. Siding is gaining share fastest among specification architects pursuing LEED v4.1 biomass cladding credits.
Installation Type:
Customer acquisition economics diverge sharply between new construction master purchasing agreements and fragmented renovation bidding.
- New Construction:National production homebuilders in Seattle and Portland metropolitan markets negotiate system packages bundling underlayment, shingles, and warranty coverage, compressing distributor margins.
- Renovation:Custom builders and specialty contractors maintain specification autonomy, preserving brand loyalty and upsell opportunity for treatment upgrades.
- Repair:Storm-damage claims and insurance-mandated fire-hardening retrofits in Colorado Front Range counties are creating episodic demand spikes with compressed timeline requirements.
- DIY Installations:Permitting complexity and structural load calculations limit mass-market penetration despite retail availability at building supply chains.
New Construction channels move the highest square footage. Repair activity is expanding most quickly in wildfire-urban-interface retrofit zones.
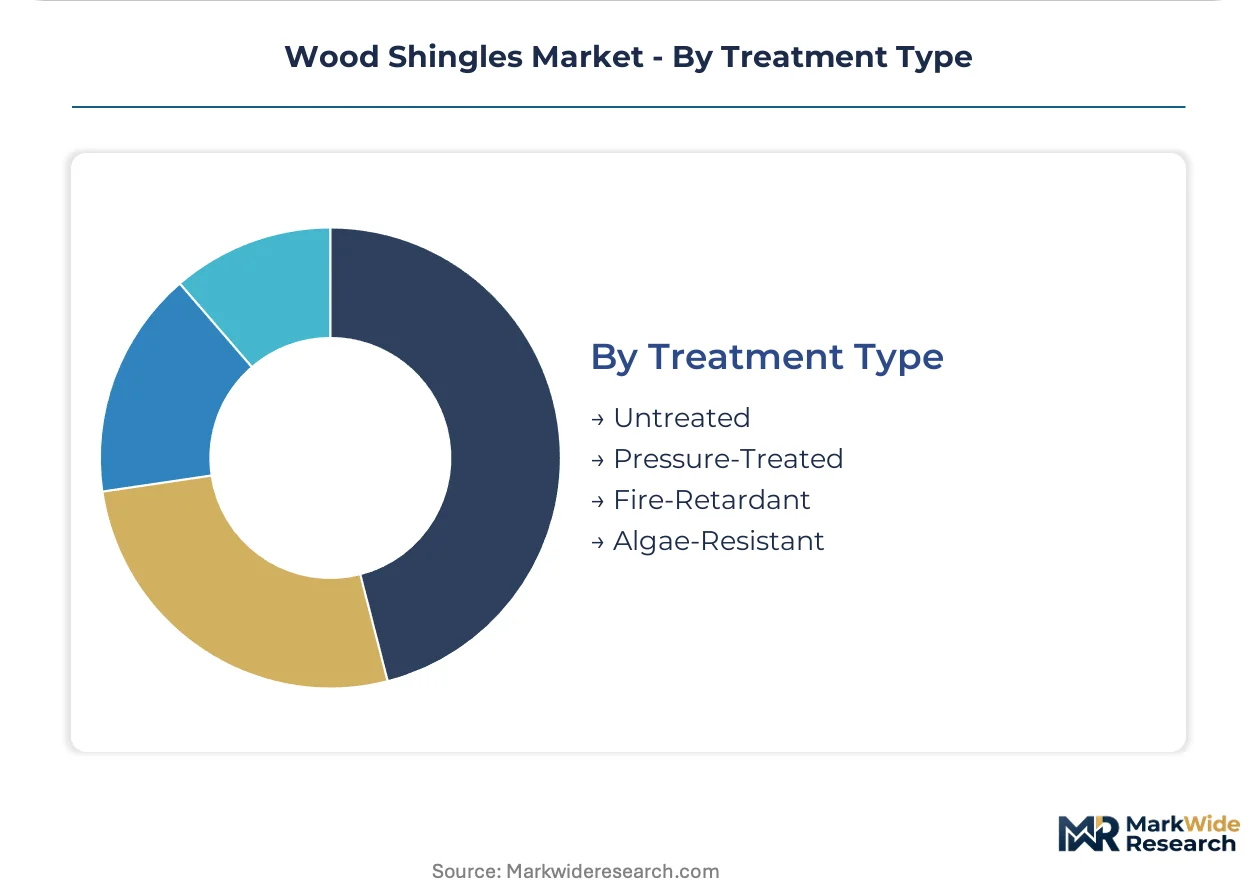
Treatment Type:
Regulatory compliance costs stratify this category, with EPA re-registration timelines for ammonium polyphosphate and boron-based retardants creating supplier qualification bottlenecks that favor scaled manufacturers.
- Fire-Retardant:Pressure-impregnated formulations achieve Class A and Class B ratings required by California Title 24 Part 11 and Colorado WUI codes. Custom home builders accept 40% material premiums for primary residence specification. Extended weathering exposure tests are filtering unstable formulations from approved product lists.
- Pressure-Treated:Copper-azole and micronized copper formulations deliver rot and insect resistance for ground-contact and high-moisture applications. EPA volatile organic compound emission limits constrain formulation choices and require emission-control equipment investments at treatment facilities.
- Untreated:Natural cedar preservatives suffice for heritage restoration projects in Massachusetts and Oregon historic districts where code-protected demand insulates from synthetic substitution.
- Algae-Resistant:Zinc and copper granule surface treatments address aesthetic degradation in humid Southeast and Great Lakes climates, extending replacement cycles.
Fire-Retardant treatments command the widest margin pools. Algae-Resistant formulations are climbing the fastest as humid-climate builders specify extended-warranty assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as fire-treatment compliance costs drive untreated shingle manufacturing toward jurisdictions with less stringent wildfire-urban-interface codes. British Columbia mill clusters capture cost advantages from captive cedar feedstock and lower environmental enforcement overhead compared to California-based competitors.
United States
California's Title 24 Part 11 mandates Class A or Class B roof assembly ratings in designated high-severity wildfire zones, effectively prohibiting untreated wood shingles from new construction in Los Angeles and San Diego counties. The EPA's volatile organic compound emission limits constrain pressure-treatment chemical formulations and require emission-control equipment investments at Pacific Northwest manufacturing facilities. Marin County and Santa Barbara custom home builders specify fire-retardant cedar shingles at material premiums exceeding standard grades.
Canada
British Columbia's Old Growth Strategic Review restricts old-growth western red cedar harvests, constraining premium-grade feedstock supply and inflating raw material input costs for coastal manufacturers. The province's timber tenure system prioritizes domestic mill access to second-growth cedar stands. Vancouver Island and Sunshine Coast mill operations maintain competitive positioning through proximity to Seattle and Portland metropolitan construction markets.
Germany
The EU Green Deal's embodied carbon accounting frameworks create specification pathways for biomass-based cladding in Passive House-certified residential projects. REACH regulations govern chemical treatments used in fire-retardant and pressure-treated product categories. Bavarian timber processors supply heritage restoration markets across Central Europe where cedar and pine shingles meet historic district preservation mandates.
Japan
METI's building energy efficiency standards incentivize carbon-sequestering materials in low-carbon housing certification programs. JIS standards specify dimensional tolerances and durability testing protocols for timber roofing products. Kyushu and Hokkaido regional markets show emerging specification interest in western red cedar shingles for high-end residential applications.
Australia
State-level bushfire construction standards in New South Wales and Victoria mandate fire-rated roofing assemblies in designated bushfire-prone areas, creating treatment-type demand segmentation. The Building Code of Australia's compliance frameworks filter untreated timber products from high-risk zones. Sydney and Melbourne metropolitan architects specify cedar shingles for heritage-compatible infill projects in protected streetscapes.
Wood Shingles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated roofing system suppliers commanding new construction channels while regional distributors retain influence in custom builder and renovation markets. The vendor base concentrates around three strategic archetypes: national production homebuilder system suppliers, heritage craft specialists serving historic preservation commissions, and treatment-technology innovators pursuing insurance-mandated retrofit demand. Competitive moves center on master purchasing agreement consolidation with national builders and proprietary fire-retardant formulation development to secure approved product list status under evolving wildfire codes.
Among North American roofing system suppliers, CertainTeed and GAF exemplify the integrated system archetype, bundling underlayment and shingle packages to sustain contractor loyalty across metropolitan markets. Malarkey Roofing Products occupies a position at the intersection of traditional and engineered roofing through polymer-modified asphalt adjacent lines. Owens Corning and TAMKO Building Products anchor the scale-driven tier, leveraging distribution network density to capture specification share in production homebuilder portfolios.
| Leading Market Players |
|---|
| Owens Corning |
| TAMKO Building Products |
| Malarkey Roofing Products |
| Decra Roofing Systems |
| Atlas Roofing Corporation |
| CertainTeed |
| IKO Industries |
| PABCO Roofing Products |
| GAF |
| Others |
Value Chain & Pricing Dynamics
Master shingle mechanics concentrated in Maine and Vermont drive labor-cost differentials that widen pricing-tier spreads between heritage craft installations and production-homebuilder standardized packages. British Columbia mill proximity to Pacific Northwest markets compresses landed costs for coastal buyers while inland contractors absorb elevated freight premiums that shift specification toward lower-grade pine alternatives.
Pricing Analysis
Distributor margin layering separates fire-retardant cedar premiums from untreated commodity grades, with regional distributors capturing wider spreads in renovation channels than national builders negotiating direct manufacturer contracts. Pricing stratifies across Class A-certified, pressure-treated, and natural cedar tiers based on EPA compliance costs and British Columbia feedstock scarcity. Cost compression in untreated segments intensifies as polymer-modified asphalt substitutes capture wildfire-zone specification. Price-sensitive production homebuilders in Seattle and Portland metropolitan markets drive volume-tier negotiation, while Marin County custom builders exhibit minimal sensitivity to material premiums.
Supply Chain Analysis
Certification gating through NFPA Class A and Class B ratings filters supplier qualification, concentrating treated-product capacity among scaled manufacturers with EPA-registered formulation portfolios. Feedstock draws from British Columbia, Washington State, and Oregon mill clusters, with western red cedar supply tethered to provincial harvest restrictions. Ammonium polyphosphate and boron-based retardant dependencies expose formulators to EPA re-registration timeline risk. Distribution runs through regional specialty distributors serving custom builders, bypassed by national production homebuilders negotiating master purchasing agreements directly with integrated system suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where British Columbia feedstock access and lower environmental enforcement overhead offset California's Title 24 compliance costs for untreated shingle manufacturing.
For Market Incumbents: Cement contractor loyalty in Pacific Northwest heritage districts through apprenticeship program sponsorship that addresses retiring master mechanic scarcity. Secure approved product list status under evolving Colorado WUI codes before polymer-modified asphalt substitutes lock out wood specification. Capacity addition in Montana and Idaho captures underpenetrated Mountain West demand before regional distributors establish exclusive relationships. For New Entrants and Emerging Players: Capture prefabricated panel integration channels serving offsite construction manufacturers seeking pre-cut shingle courses for industrial procurement. Target Idaho and Montana residential markets below 3% cedar penetration where compatible architectural vernacular meets expanding second-home construction. Pursue direct-to-builder go-to-market positioning that bypasses distributor margin layering in custom renovation segments. For Investors and Strategic Acquirers: Integrated roofing system suppliers are the most active acquirer in this space, consolidating regional treatment-technology innovators to secure proprietary fire-retardant formulation portfolios. Long-term viability hinges on wildfire-urban-interface code expansion geography and insurance-mandated retrofit cycle timing. Watch EPA re-registration outcomes for ammonium polyphosphate as inflection indicator for formulation obsolescence risk and replacement-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Fire-Retardant Formulation Development | Secures Class A rating under California Title 24 Part 11 and Colorado WUI codes. |
| Master Purchasing Agreement Consolidation | Lennar and D.R. Horton standardization in Seattle and Portland compresses distributor influence. |
| Apprenticeship Program Investment | Addresses Maine and Vermont master mechanic retirement gaps threatening installation capacity. |
| Prefabricated Panel Channel Entry | Opens industrial procurement beyond traditional roofing contractor relationships. |
| British Columbia Feedstock Integration | Captures western red cedar supply chain proximity to Pacific Northwest construction markets. |
Study Parameters
Bottom-up residential roofing and siding modeling reconciled against top-down mill capacity and treatment facility tracking forms the analytical core of this study. Primary interviews with cedar mill operations managers, fire-retardant formulation chemists, roofing contractor purchasing agents, historic preservation commission staff, and insurance risk assessors combined with secondary validation from British Columbia Ministry of Forests harvest data, EPA chemical registration databases, California Building Standards Commission code filings, and National Fire Protection Association certification records.
Historical trendline analysis of cedar feedstock pricing, treatment chemical input costs, and regional construction permit volumes established baseline trajectory parameters across the projection horizon. Segmentation modeling spanned product type, application, installation channel, and treatment technology dimensions. CAGRs derived from regression analysis against housing starts, wildfire-urban-interface code expansion geography, and insurance mandate adoption curves.
Underlying measurement precision varies by segment; fire-retardant treatment volumes carry tighter precision than untreated heritage restoration demand given regulatory reporting requirements. Forecasts reflect assumptions regarding EPA re-registration timelines, provincial harvest restriction enforcement, and insurance carrier retrofit mandate diffusion. A model refresh is warranted upon material change in Colorado or Arizona WUI code adoption timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Asphalt Modifiers Market