
 Nut Runner Market | 2026-2036
Nut Runner Market Size, Share, and Industry Trends Forecast 2026-2036
Nut Runner Market Analytics
A widening capital-intensity divergence between full-range industrial suppliers and focused precision-tool specialists is redrawing competitive boundaries in the nut runner space. Atlas Copco AB leverages its compressed-air ecosystem to sustain premium positioning across integrated assembly systems. Robert Bosch GmbH anchors its presence through deep electric-drive expertise and automotive OEM relationships. Ingersoll Rand Inc. competes on scale, extending its industrial tool portfolio into cordless and connected torque platforms.
A nut runner is a torque-controlled fastening device engineered to tighten nuts, bolts, and threaded fasteners to specified clamp loads, typically operating within tolerances of plus or minus three percent to prevent joint failure in critical assemblies. Electric variants deploy brushless DC motors with closed-loop transducer feedback, while pneumatic units rely on stall-type or shut-off clutch mechanisms calibrated to target torque values. Electric nut runners are capturing margin pools as battery platforms and Industry 4.0 data logging reshape procurement criteria. The automotive end-user segment leads absolute volume, though aerospace quality-control applications command premium pricing due to traceability mandates. Robotics technology is displacing semi-automated stations in high-volume engine plants, concentrating vendor relationships around system integrators.
ISO 5393 standards govern rotary tool performance testing, while OSHA lockout-tagout rules in the United States and Machinery Directive 2006/42/EC in Europe shape workplace safety and CE marking requirements for powered fastening equipment. Japan's METI industrial productivity guidelines and China's GB standards for pneumatic tools further fragment compliance obligations across supply chains. Stakeholders must monitor how battery-platform standardization and torque-data traceability requirements reshape supplier qualification criteria and aftermarket service models.
Market Dynamics
Brushless DC motor architectures with integrated torque transducers are compressing the performance gap between pneumatic and electric platforms, forcing recalibration of procurement criteria across automotive and aerospace assembly lines.
Growth Catalysts
- EV Battery Pack Assembly:Electric vehicle manufacturers in China require precision fastening for module-to-pack connections, driving specification upgrades at domestic OEM plants.
- OSHA Lockout-Tagout Enforcement:Heightened workplace safety inspections across United States manufacturing facilities mandate certified shut-off mechanisms on powered fastening equipment.
- Industry 4.0 Data Logging:Closed-loop feedback systems with traceable torque curves enable predictive maintenance contracts and aftermarket service revenue expansion.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing capacity clusters in China, exposing brushless motor producers to export quota volatility.
- ISO 5393 Certification Timeline:Rotary tool performance testing protocols require 12-18 month validation cycles, delaying new product commercialization.
- Stall-Type Pneumatic Substitutes:Legacy air-powered units retain cost advantage in low-tolerance applications, limiting electric platform penetration in price-sensitive segments.
Strategic Opportunities
- India Automotive Component Manufacturing:PLI scheme incentives for advanced automotive technology create qualified demand for calibrated torque equipment at Tier-1 suppliers.
- GB Standard Harmonization:China's national pneumatic tool standards are converging with ISO frameworks, reducing compliance fragmentation for multinational suppliers.
- Robotics Integration:Collaborative robot deployments in German engine plants require force-controlled fastening end-effectors, opening system integrator partnerships.
Industry Challenges
- Mechatronics Skill Gap:Servicing transducer-equipped electric units demands expertise spanning mechanical calibration and embedded firmware diagnostics.
- CE Marking Machinery Directive Complexity:European conformity assessment for powered hand tools requires third-party intervention for noise emission and electromagnetic compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut Runner Market |
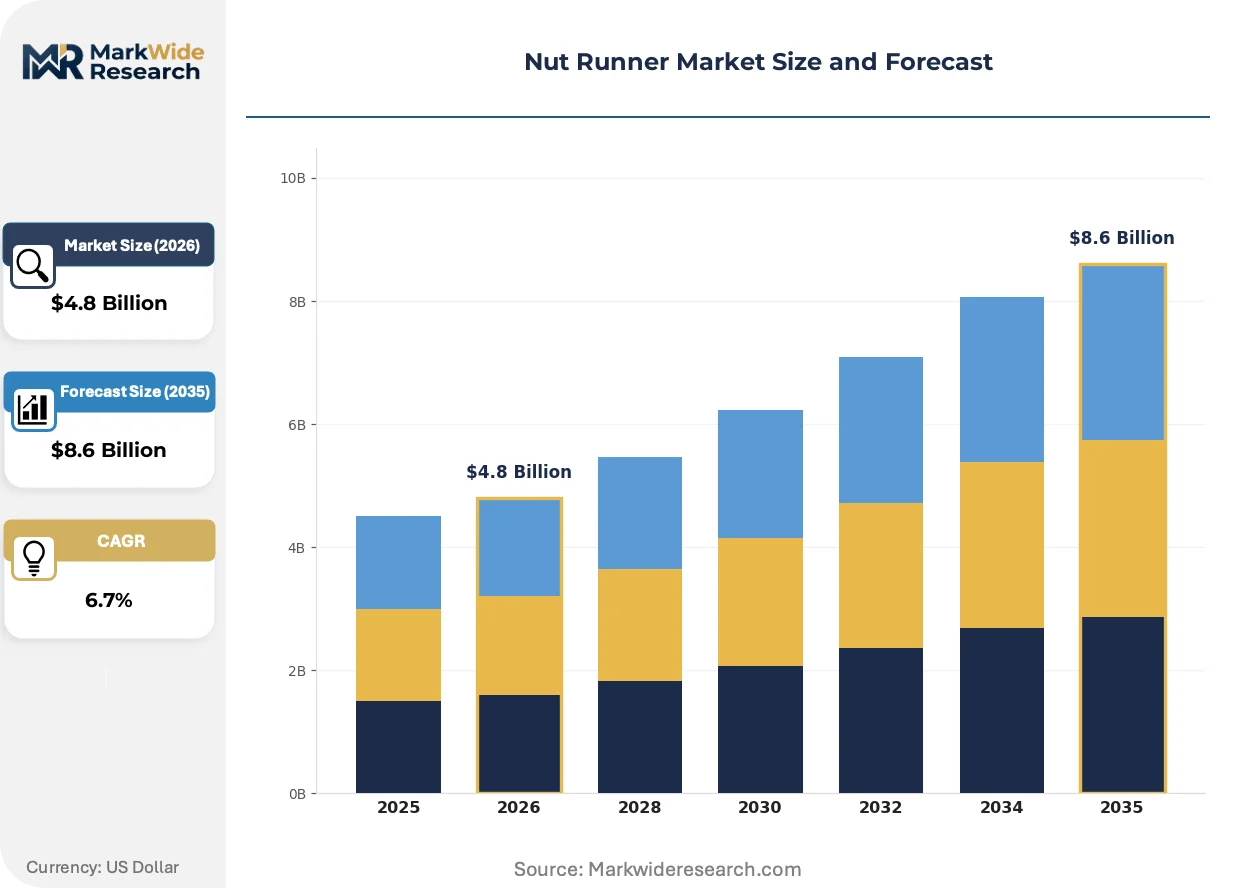
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Nut Runner, Pneumatic Nut Runner, Manual Nut Runner, Hydraulic Nut Runner End User: Aerospace, Automotive, Manufacturing, Construction Technology: Automated, Semi-Automated, Manual, Robotics Application: Assembly, Maintenance, Repair, Quality Control |
| Companies Covered | Atlas Copco AB, Stanley Engineered Fastening, Robert Bosch GmbH, Estic Corporation, Dai-Ichi Dentsu Ltd., Ingersoll Rand Inc., AIMCO, Sanyo Machine Works Ltd., Maschinenfabrik Wagner GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut Runner Market Evolving Landscape
Battery-platform standardization and torque-data monetization are redefining vendor-customer relationships. Equipment suppliers now compete on software integration depth rather than hardware specifications alone.
Cordless brushless DC nut runners with 18V-36V interchangeable battery platforms are supplanting tethered electric and pneumatic units in final assembly stations. Automotive OEMs in Germany and Japan are specifying these platforms for mixed-model lines. The shift compresses infrastructure requirements while enabling rapid station reconfiguration.
Machinery Directive 2006/42/EC amendments on human-robot collaboration are mandating force-limiting features on automated fastening systems. European system integrators must certify compliance through notified bodies. Aerospace tier suppliers face the steepest adaptation costs due to dual traceability requirements.
Outcome-based contracting is displacing capital purchase models for high-volume assembly operations. Tier-1 suppliers now pay per correctly tightened joint rather than owning equipment. This pattern concentrates in North American automotive transmission plants where uptime guarantees dominate vendor selection.
Nut Runner Market Segmentation
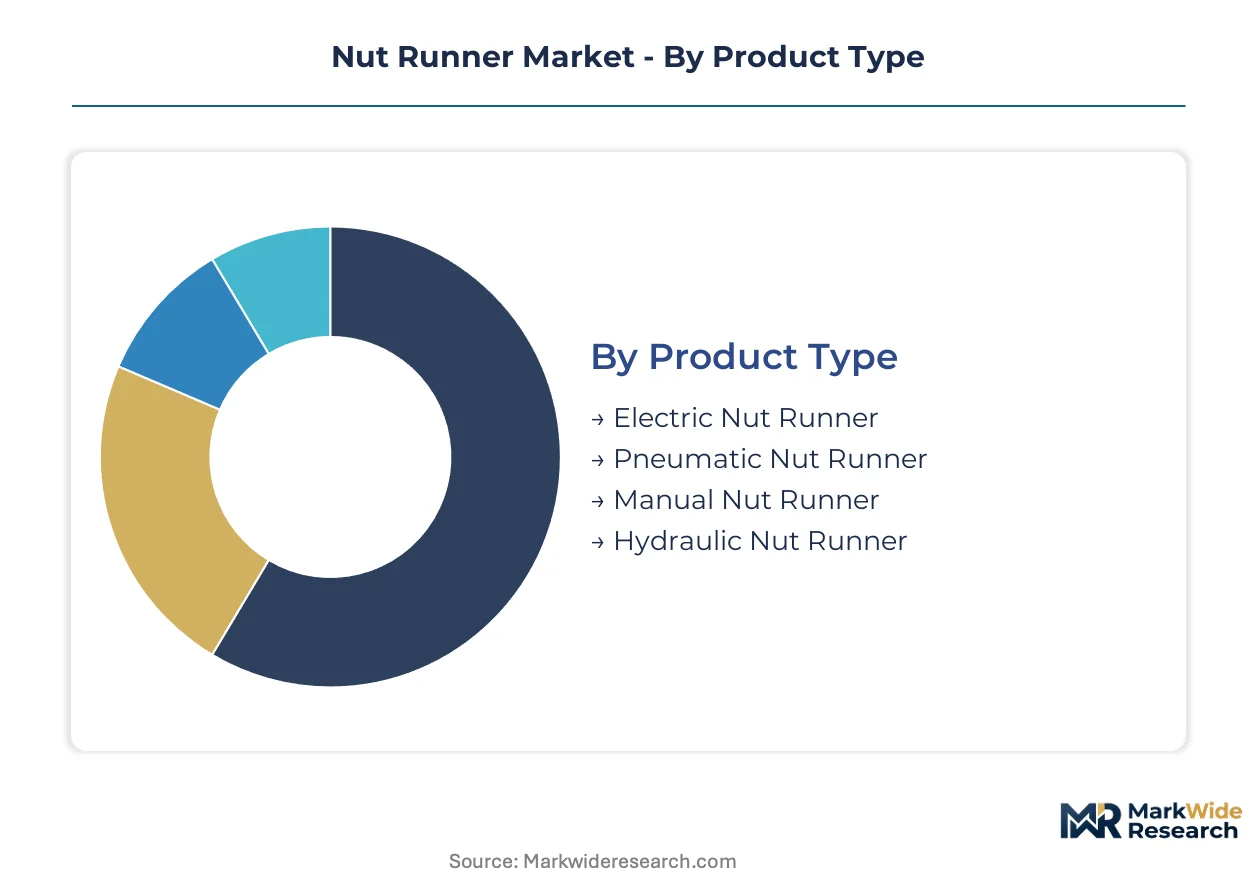
Segmentation in the nut runner market reveals how torque-tool procurement fractures across power-source preferences, automation readiness, and traceability mandates. Buyers select platforms based on joint-criticality, infrastructure constraints, and data-logging requirements rather than torque capacity alone.
Product Type:
Pneumatic units face the most acute substitution pressure as brushless DC architectures close the performance gap and battery platforms eliminate compressed-air infrastructure.
- Electric Nut Runner:Brushless DC motors with closed-loop transducer feedback deliver plus-or-minus three percent torque tolerance. Demand concentrates in German and Japanese automotive OEM plants where Industry 4.0 data logging and rapid station reconfiguration override higher capital costs.
- Pneumatic Nut Runner:Stall-type or shut-off clutch mechanisms operate without electrical infrastructure. Legacy installations in price-sensitive Chinese manufacturing and maintenance operations retain this technology where tolerance requirements stay below critical thresholds.
- Manual Nut Runner:Click-type or beam-style torque wrenches serve low-volume repair and field service applications.
- Hydraulic Nut Runner:High-torque bolting systems for wind turbine assembly and heavy construction.
Electric nut runners retain volume leadership in new installations; hydraulic variants hold the steepest expansion curve in renewable energy infrastructure.
End User:
Cost tier stratification separates aerospace traceability mandates from automotive volume procurement.
- Automotive:Mixed-model assembly lines in Germany and China drive specification for cordless platforms with interchangeable 18V-36V batteries. OEMs prioritize uptime guarantees and predictive maintenance contracts over unit purchase price.
- Aerospace:Tier-1 suppliers face dual ISO 5393 and customer-specific torque-curve documentation requirements. Premium pricing reflects mandatory traceability and third-party calibration protocols.
- Manufacturing:General industrial fastening across machinery and equipment production.
- Construction:Field bolting for structural steel and infrastructure projects.
Automotive dominates absolute unit demand; aerospace commands the widest margin spread per fastening operation.
Technology:
Customer type divides between system-integrator relationships and standalone tool procurement.
- Automated:Fixed-station nut runners with PLC integration and real-time torque monitoring. German engine plants specify these for high-volume cylinder head assembly.
- Robotics:Force-controlled end-effectors mounted on collaborative robots. European Machinery Directive 2006/42/EC amendments on human-robot collaboration mandate force-limiting features.
- Semi-Automated:Operator-guided tools with shut-off clutches and error-proofing.
- Manual:Hand-held tools without automation integration.
Semi-automated systems retain installed-base dominance; robotics integration is climbing the fastest in greenfield European assembly plants.
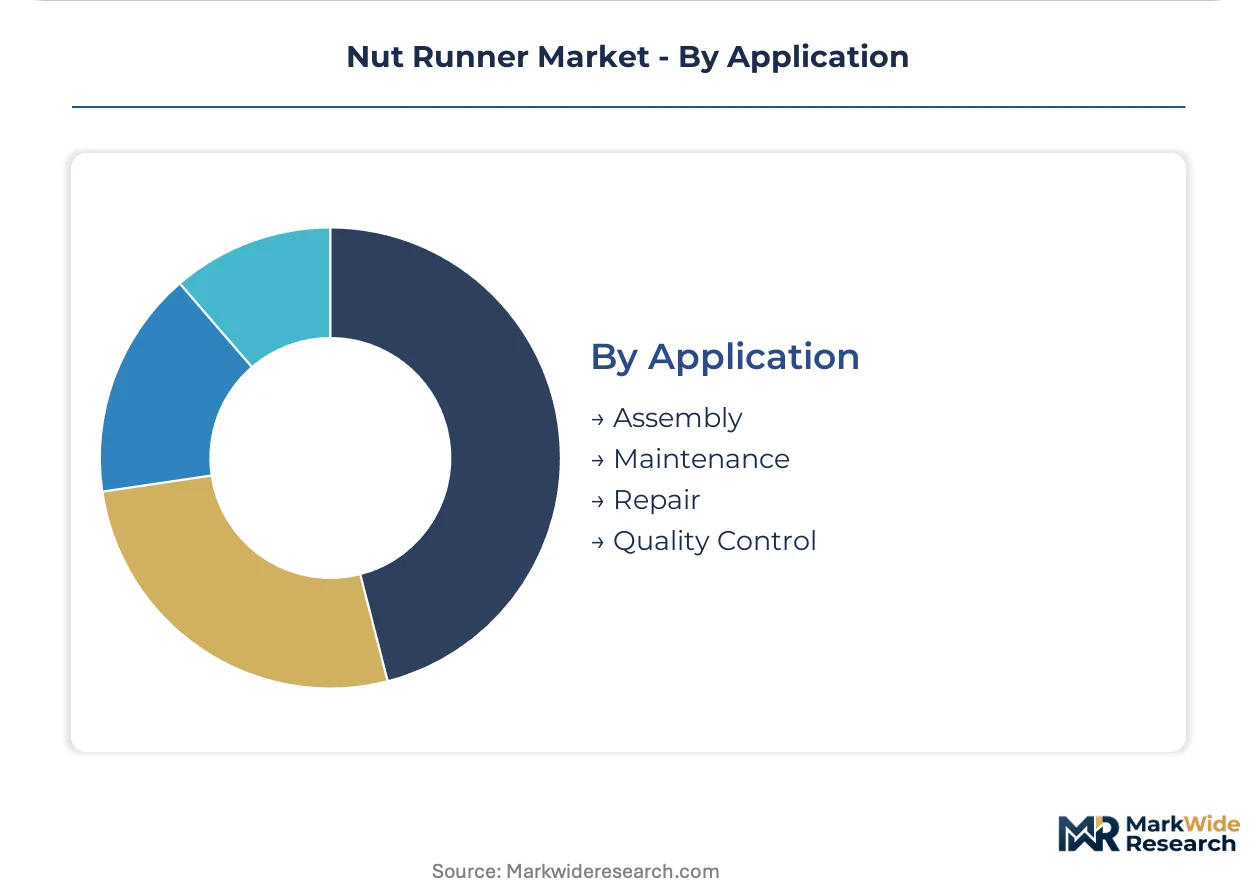
Application:
Volume concentration in assembly operations contrasts with margin concentration in quality control.
- Assembly:Original equipment manufacturing across automotive powertrain and EV battery pack construction. Chinese domestic EV producers scale module-to-pack fastening with precision torque specifications.
- Quality Control:Audit tightening and torque verification with full documentation. Aerospace final assembly lines mandate this application for regulatory compliance.
- Maintenance:Scheduled service and component replacement in operating facilities.
- Repair:Unscheduled corrective work and field service operations.
Assembly commands the largest equipment footprint; quality control applications are expanding most quickly as traceability mandates tighten across automotive and aerospace supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese automotive assembly corridors, while Chinese domestic EV producers extract procurement leverage through volume concentration. Regulatory divergence between OSHA enforcement in the United States and Machinery Directive amendments in Europe fragments vendor qualification protocols. Industrial clusters in Stuttgart, Nagoya, and Shanghai anchor regional demand formation.
United States
Automotive transmission plants in Michigan and Ohio drive specification for cordless brushless platforms with predictive maintenance contracts. OSHA lockout-tagout enforcement mandates certified shut-off mechanisms across powered fastening equipment. Detroit-area OEMs prioritize uptime guarantees over unit capital expenditure in vendor selection criteria.
Germany
Machinery Directive 2006/42/EC amendments on human-robot collaboration mandate force-limiting features on automated fastening systems. Stuttgart and Wolfsburg assembly corridors specify integrated Industry 4.0 data logging for torque curve traceability. German system integrators dominate robotics integration partnerships for greenfield engine plants.
China
Domestic EV battery pack assembly scales module-to-pack fastening with precision torque specifications at BYD and CATL supplier parks. GB standards for pneumatic tools are converging with ISO frameworks, reducing compliance fragmentation. Shanghai and Shenzhen industrial zones concentrate demand for calibrated electric nut runners.
Japan
METI industrial productivity guidelines push manufacturers toward calibrated equipment with closed-loop feedback systems. Toyota and Honda assembly lines in Nagoya and Tokyo specify rapid station reconfiguration through interchangeable battery platforms. Japanese automotive OEM relationships anchor premium positioning for precision-tool specialists.
India
PLI scheme incentives for advanced automotive technology create qualified demand for calibrated torque equipment at Tier-1 suppliers. Tamil Nadu and Maharashtra automotive corridors expand precision fastening adoption as export-oriented component manufacturing scales. Domestic OEMs upgrade from pneumatic legacy installations to electric platforms.
Nut Runner Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage compressed-air ecosystems and electric-drive expertise to sustain premium positioning. The vendor base spans three tiers: full-range industrial suppliers with integrated assembly systems, precision-tool specialists focused on torque-controlled applications, and regional fabricators competing on price-sensitive pneumatic units. Dominant competitive moves include portfolio diversification into cordless battery platforms and strategic partnerships with automotive system integrators for robotics deployment.
Within the diversified industrial tier, Atlas Copco AB and Robert Bosch GmbH exemplify archetypes that anchor competitive positioning through deep OEM relationships and technology ecosystems. Ingersoll Rand Inc. occupies a scale-driven position extending industrial tool portfolios into connected torque platforms. Japanese specialists including Estic Corporation and Dai-Ichi Dentsu Ltd. represent precision-focused fabricators concentrated in automotive assembly automation.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Stanley Engineered Fastening |
| Robert Bosch GmbH |
| Estic Corporation |
| Dai-Ichi Dentsu Ltd. |
| Ingersoll Rand Inc. |
| AIMCO |
| Sanyo Machine Works Ltd. |
| Maschinenfabrik Wagner GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Long-term predictive maintenance contracts lock in both supply access and price visibility for German automotive OEMs, compressing spot-market exposure while embedding calibration service costs into per-joint pricing structures. This contract architecture shields Tier-1 suppliers from neodymium magnet volatility while binding vendors to uptime guarantees across multi-year assembly line deployments.
Pricing Analysis
Configured-to-order pricing for transducer-equipped electric units commands a 40-60% premium over standard pneumatic catalog pricing, with ISO 5393 certification tier and battery-platform interoperability acting as the primary differentiation drivers. Cost compression in the pneumatic legacy tier intensifies as Chinese domestic EV producers scale module-to-pack fastening, while aerospace traceability mandates render Tier-1 suppliers virtually price-inelastic. The widest buyer price sensitivity gap separates maintenance operations in price-conscious Indian component manufacturing from German system integrators specifying force-controlled robotics.
Supply Chain Analysis
Rare earth magnet processing concentration in China underwrites supply vulnerability for brushless DC motor producers, with neodymium and dysprosium extraction capacity anchoring downstream electric nut runner availability. Component sourcing draws from Japanese torque transducer specialists, German precision gearing fabricators, and Taiwanese semiconductor foundries for motor control ICs. Single-source vulnerability concentrates in rare earth oxide separation, while distribution runs through authorized industrial tool distributors with factory-certified calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fastening demand fragments across EV battery assembly, aerospace traceability mandates, and collaborative robotics integration, creating defendable niches for specialists against consolidated industrial conglomerates.
For Market Incumbents: Compound defensive moats through captive calibration service networks and backward integration into torque transducer manufacturing, neutralizing emerging specialist threats in the robotics end-effector segment. Prioritize certification investment for Machinery Directive 2006/42/EC force-limiting compliance to lock out unqualified competitors from European greenfield engine plant contracts. For New Entrants and Emerging Players: Lead with cordless platform interoperability as the wedge into Indian Tier-1 supplier parks, where PLI scheme incentives fund precision equipment upgrades but incumbent service networks remain underdeveloped. Target semi-automated station retrofits as the most penetrable application layer, offering subscription-based torque-data logging to bypass capital purchase barriers. For Investors and Strategic Acquirers: Precision-tool specialists with embedded firmware capabilities and automotive OEM qualification represent the highest-conviction acquisition archetype for exposure to Industry 4.0 data monetization. Watch for inflection in Chinese GB standard harmonization with ISO 5393 frameworks as the signal that compliance fragmentation costs are shifting toward multinational suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interchangeable 18V-36V architectures enable rapid station reconfiguration at German mixed-model lines. |
| Backward Integration into Transducers | In-house torque sensor production secures supply continuity against Japanese component lead time volatility. |
| Robotics System Integrator Partnership | Force-controlled end-effector certification opens European greenfield engine plant specifications. |
| Predictive Maintenance Contract Expansion | Per-joint pricing models embed recurring revenue at North American automotive transmission plants. |
| GB Standard Harmonization Investment | Early compliance positioning captures Chinese domestic EV producer procurement as ISO convergence accelerates. |
Research Methodology
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on supplier qualification protocols across German, Japanese, and Chinese automotive corridors. Primary fieldwork engaged plant engineers, Tier-1 supplier maintenance directors, aftermarket service heads, and robotics system integrators, while secondary validation drew from SEC 10-K filings, METI industrial productivity reports, and GB standards documentation. Bottom-up equipment shipment analysis triangulates against top-down automotive production capacity modeling.
Sensitivity analysis across rare earth magnet price scenarios and EV battery pack assembly growth assumptions tests forecast robustness over the projection horizon. Segmentation dimensions include power source architecture, automation technology tier, end-user industry, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, greenfield capacity additions, and technology substitution elasticity, with torque-data monetization adoption curves and collaborative robotics deployment rates serving as industry-specific demand drivers.
Underlying assumptions cover OSHA enforcement continuity, China rare earth export quota stability, and Machinery Directive amendment implementation timelines, with deviation risk concentrated in battery-platform standardization fragmentation and mechatronics technician availability. Practitioners should keep alternative scenarios live as GB-ISO convergence velocity and human-robot collaboration regulatory interpretation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cordless Wood Planer Market
Tools
Thread Milling Machine Market
Tools
Brazing Torch Market
Tools
Cordless Multi Rotary Tools Market
Tools
Parting-Off Blades Market
Tools
Crimping Tool Market
Tools
Wood-Burning Tool Market
Tools
Vise-Grip Pliers Market
Tools
Paint Spray Guns Market
Tools
Masonry Cleaners Market
Tools
Portable Boring Machines Market
Tools
Tile Cutter Market
Tools
Pliers Market
Tools
Press Machine Market
Tools
Total Station Market
Tools
Fixed Cutter Bits Market