
 Global Formwork Market | 2026-2036
Global Formwork Market Size, Share, and Industry Trends Forecast 2026-2036
Global Formwork Market Analysis
Market Dynamics and Competitive Landscape
Chinese formwork manufacturing capacity is shifting toward higher-grade aluminum and automated modular systems to serve premium export segments. PERI GmbH leverages its integrated engineering services to dominate complex infrastructure projects across Europe and the Middle East. Doka GmbH sustains competitive positioning through captive supply of engineered timber and steel components. ULMA Construction anchors its growth in Latin America through localized production facilities and regional distribution networks.
Product Segmentation and Technical Overview
Formwork encompasses temporary molds into which concrete is poured and shaped, with modern systems specifying load-bearing capacities from 60 to 120 kN per square meter depending on material grade and panel geometry. Steel formwork retains the largest revenue share due to durability across high-rise commercial cycles, while aluminum formwork represents the fastest-expanding category as residential developers prioritize lightweight, crane-efficient panel systems for repetitive slab construction. Timber formwork occupies mature, price-sensitive segments where single-use economics prevail in emerging markets with abundant softwood supply.
Regulatory Environment and Outlook
The EU Green Deal and REACH frameworks enforce embodied carbon thresholds that favor reusable aluminum and certified timber over disposable plastic alternatives, while China's MEE dual carbon goals mandate recycled content minimums in construction materials procurement. India's BIS certification requirements for structural shuttering safety are tightening product standards across domestic and imported supply channels. Stakeholders must monitor evolving circular economy mandates that will determine material eligibility in public infrastructure tendering across major economies.
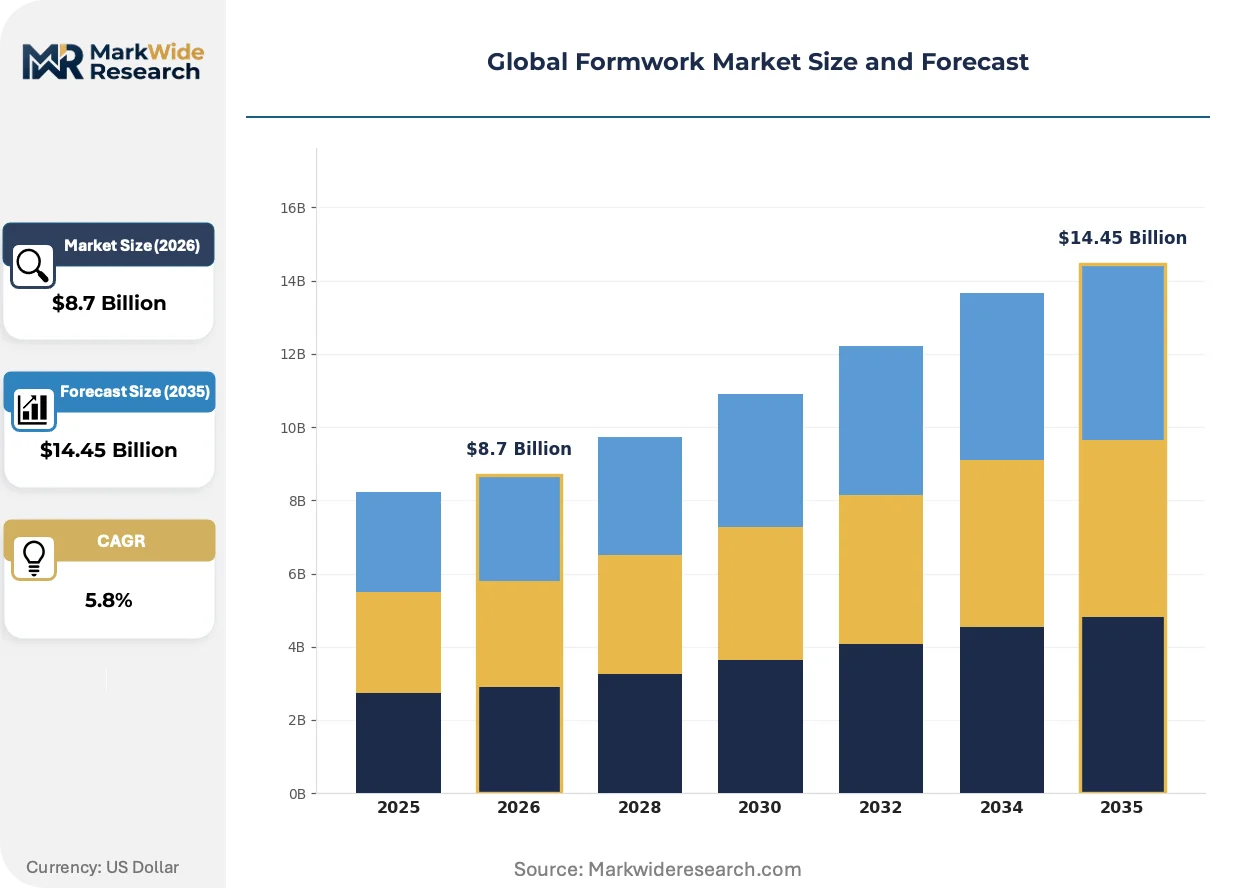
Market Dynamics
Modular aluminum systems are displacing traditional timber and steel alternatives as residential developers prioritize crane-cycle efficiency and labor cost reduction across high-rise construction.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:REACH-compliant aluminum formwork gains preference in European public infrastructure tendering over disposable plastic alternatives.
- India's urban housing programs:Mass residential construction under PMAY-Urban drives procurement of reusable panel systems for repetitive slab casting.
- Lightweight modular technology:Aluminum systems reduce crane time by 40-60% versus steel equivalents, accelerating adoption in dense urban sites.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations compress margins for system manufacturers dependent on aerospace-grade alloy feedstock.
- Chinese supply concentration:Over 60% of global aluminum extrusion capacity sits in Shandong and Guangdong provinces, creating geopolitical and logistics risk.
- Timber substitution in price-sensitive segments:Abundant softwood supply in Brazil and Southeast Asia sustains single-use economics for low-rise residential.
Strategic Opportunities
- India's infrastructure investment wave:National Highway Development and metro rail projects create demand for engineered climbing and tunnel formwork systems.
- Digital twin integration:BIM-compatible formwork design software enables just-in-time panel configuration and waste reduction.
- China's MEE dual carbon procurement mandates:Recycled-content minimums in state construction projects favor domestic aluminum system suppliers with closed-loop remelting.
Industry Challenges
- Skilled formwork engineering shortage:Complex infrastructure projects require certified designers for load-bearing calculations, with talent concentrated in Germany and Austria.
- BIS certification timeline compression:India's tightened structural shuttering safety standards extend product approval cycles for imported systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Formwork Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Formwork, Aluminum Formwork, Plastic Formwork, Timber Formwork End User: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Projects Application: Slab Formwork, Wall Formwork, Column Formwork, Beam Formwork Installation Method: Traditional, Modular, Automated, Customized |
| Companies Covered | PERI GmbH, Doka GmbH, ULMA Construction, Alsina, MEVA, RMD Kwikform, Acrow, PASCHAL, NOE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Formwork Market Emerging Trajectories
Automation and material science advances are compressing project timelines while regulatory pressure on embodied carbon forces specification changes across public and private construction.
Self-climbing formwork systems are converging with IoT sensor networks to enable real-time load monitoring and automated safety alerts during concrete pours. High-rise commercial developers in Singapore and Dubai are deploying these integrated systems to reduce manual inspection labor. The convergence is compressing insurance premiums and enabling taller continuous pours without structural risk.
REACH framework amendments on persistent organic pollutants are restricting certain timber treatments and plastic formwork coatings across European construction sites. Manufacturers must reformulate surface finishes or shift to certified aluminum alternatives to maintain market access. German and French infrastructure consortia are now specifying cradle-to-cradle material passports in major tender documents.
Rental and lease-to-own models are displacing outright purchase for mid-sized contractors seeking to preserve working capital. Equipment financing platforms in the United Kingdom and Australia now bundle formwork systems with maintenance and engineering support. This shift concentrates fleet ownership among specialized lessors with remanufacturing capabilities.
Global Formwork Market Segmentation
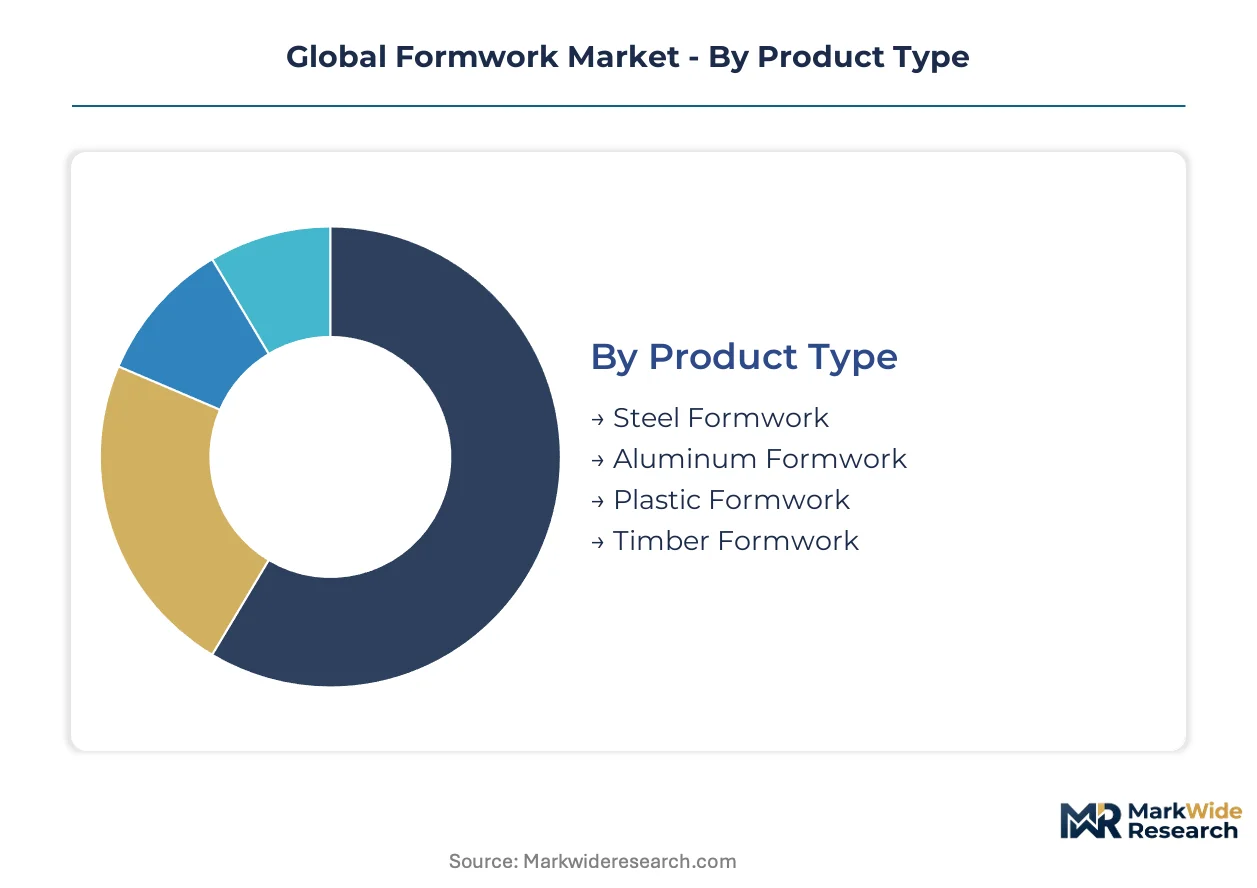
Formwork procurement decisions hinge on load-bearing requirements, crane-cycle economics, and reuse intensity across project types. Segmentation reveals where aluminum modular systems displace traditional materials and which installation methods command premium positioning.
Product Type:
Standalone systems dominate high-rise commercial cycles, while embedded lightweight alternatives penetrate residential repetitive casting.
- Steel Formwork:Engineered panels fabricated from high-tensile steel grades withstand 80-120 kN per square meter loads across high-rise commercial cores. Demand concentrates in Singapore and Dubai supertall projects where durability across 500+ reuse cycles justifies capital intensity.
- Aluminum Formwork:Aerospace-grade alloy extrusions deliver 60-80 kN capacity at one-third steel weight, enabling 40-60% crane-time reduction. Residential developers in India and Vietnam prioritize these systems for repetitive slab construction under PMAY-Urban and similar housing programs.
- Plastic Formwork:Glass-reinforced polymer panels serve low-load architectural concrete in European residential basements and landscaping walls.
- Timber Formwork:Softwood plywood systems retain cost advantage in Brazil and Indonesia where abundant plantation supply sustains single-use economics for low-rise housing.
Volume placements concentrate in Steel Formwork; the faster expansion belongs to Aluminum Formwork.
End User:
Cost-tier differentiation separates capital-intensive infrastructure from working-capital-constrained residential contractors.
- Residential Construction:High-rise apartment developers in India and China specify aluminum panel systems for standardized floor plates, with crane efficiency and labor reduction driving specification. PMAY-Urban procurement mandates favor reusable systems with 200+ cycle ratings.
- Commercial Construction:Mixed-use towers in Singapore and Dubai deploy self-climbing steel systems for continuous core pours, with integrated IoT load monitoring compressing insurance premiums and enabling taller single-stage casting.
- Infrastructure Development:National highway and metro rail authorities in India and Saudi Arabia procure engineered climbing and tunnel formwork for complex geometries.
- Industrial Projects:Power plant and refinery contractors in Germany and South Korea specify heavy-duty steel for containment structures and process vessels.
Contractor fleet ownership concentrates in Commercial Construction; Infrastructure Development shows the steepest expansion trajectory for rental-lease models.
Application:
Structural function determines panel geometry complexity and engineering support intensity.
- Slab Formwork:Flat aluminum panel systems dominate residential high-rises in India and Vietnam where standardized floor plates enable just-in-time configuration. BIM-compatible design software reduces waste through precise panel sequencing.
- Wall Formwork:Vertical steel or timber systems serve architectural concrete finishes in German and French commercial projects, with cradle-to-cradle material passports now specified in major tender documents.
- Column Formwork:Circular and rectangular adjustable systems address variable cross-sections in infrastructure projects across Saudi Arabia and UAE.
- Beam Formwork:Custom timber and steel combinations handle complex load-transfer geometries in industrial facilities.
Procurement volume clusters in Slab Formwork; Wall Formwork gains share fastest under EU Green Deal embodied carbon thresholds.
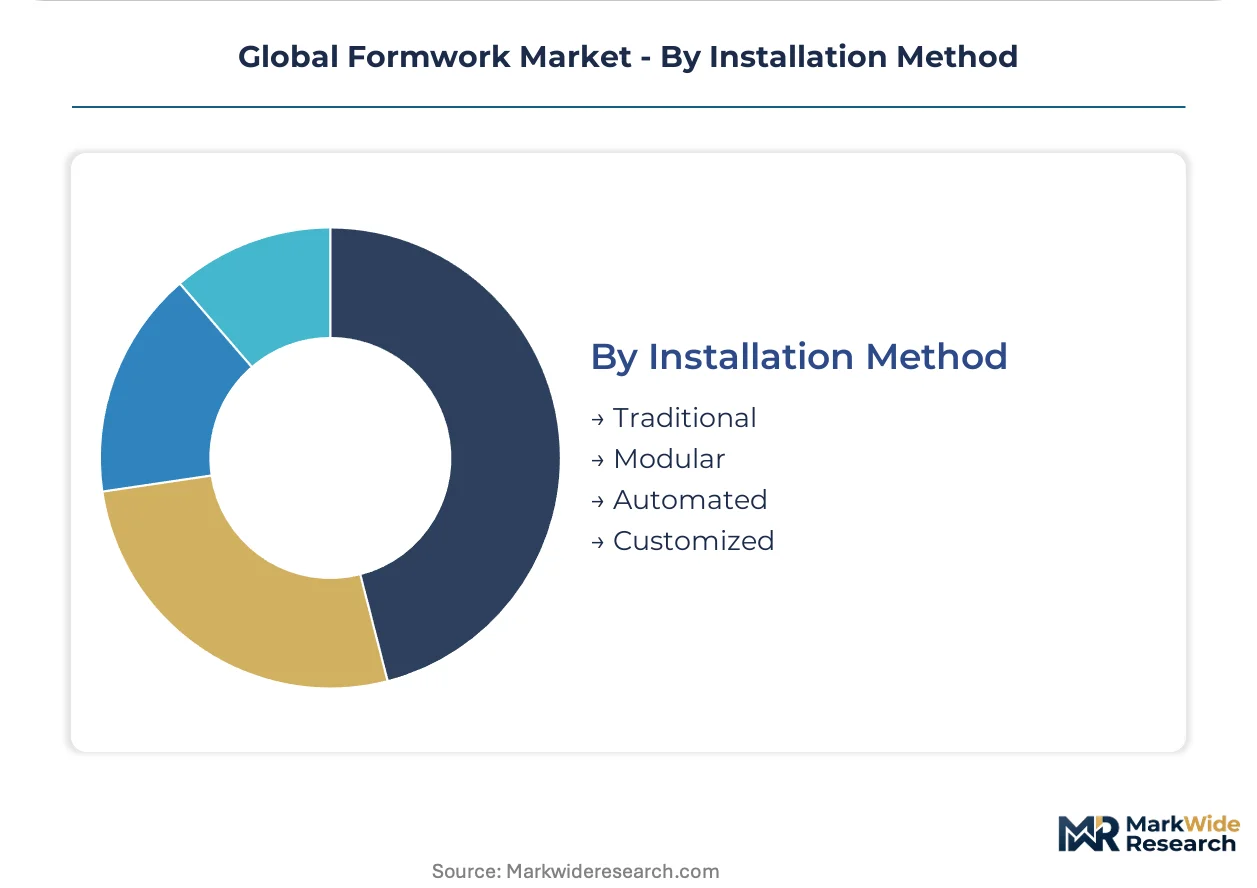
Installation Method:
Customer-type stratification separates self-performing contractors from specialized formwork subcontractors.
- Traditional:Timber-based stick-built methods persist in price-sensitive Brazilian and Indonesian residential markets with abundant local labor.
- Modular:Prefabricated aluminum and steel panel systems dominate Indian and Chinese residential high-rises, with crane efficiency and reduced skilled labor requirements driving adoption.
- Automated:Self-climbing and tunneling systems with integrated IoT sensors command premium positioning in Singapore and Dubai commercial towers, enabling real-time load monitoring.
- Customized:Engineered solutions for complex infrastructure geometries in German and Austrian alpine tunnel projects require certified designers for load-bearing calculations.
Deployment volume concentrates in Modular systems; Automated methods expand most quickly in dense urban sites with labor cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Guangdong provinces anchor global aluminum extrusion capacity for formwork manufacturing, with over sixty percent of worldwide supply originating from these coastal industrial clusters. This geographic concentration shapes procurement patterns and logistics strategies for contractors across multiple continents.
China
MEE dual carbon procurement mandates now require recycled-content minimums in state construction projects, favoring domestic suppliers with closed-loop remelting capabilities. Yangtze River Delta and Pearl River Delta industrial zones are upgrading toward aerospace-grade alloy extrusions and automated modular systems. Zhengzhou machinery clusters are expanding engineered timber-steel hybrid production for premium export segments.
Germany
REACH framework amendments on persistent organic pollutants restrict certain timber treatments and plastic formwork coatings across construction sites. Bavarian and Baden-Württemberg engineering centers concentrate certified formwork designers for complex load-bearing calculations. Munich-based infrastructure consortia now specify cradle-to-cradle material passports in major tender documents.
India
PMAY-Urban mass housing programs drive procurement of reusable aluminum panel systems with two-hundred-plus cycle ratings for repetitive slab casting. BIS certification timelines for structural shuttering safety are extending product approval cycles for imported systems. Maharashtra and Gujarat industrial corridors are localizing steel formwork fabrication to serve national highway and metro rail projects.
United Arab Emirates
Supertall commercial tower construction in Dubai and Abu Dhabi deploys self-climbing steel systems with integrated IoT load monitoring for continuous core pours. MOHAP construction material standards are tightening specifications for high-rise safety systems. Jebel Ali industrial zones are expanding rental and lease-to-own fleet operations for mid-sized contractors.
United States
OSHA fall-protection regulations and state-level green building codes are elevating specification standards for reusable formwork systems in public infrastructure. Texas and California metropolitan construction markets are adopting BIM-compatible design software for just-in-time panel configuration. Pacific Northwest timber clusters sustain softwood plywood supply for price-sensitive residential segments.
Global Formwork Market Vendor Landscape
Global majors compete with regional champions across engineering services and captive material supply, creating a tiered structure where integrated solution providers command premium positioning in complex infrastructure while localized fabricators capture residential volume. The vendor base stratifies across three archetypes: German-Austrian engineering specialists with integrated design services, Chinese scale manufacturers with aluminum extrusion advantages, and regional rental fleet operators with remanufacturing capabilities. Dominant competitive moves include backward integration into engineered timber and steel component supply, plus strategic partnerships between equipment financing platforms and maintenance service providers.
Among German-Austrian engineering specialists, PERI GmbH and Doka GmbH exemplify the integrated-service archetype, anchoring competitive positioning through captive supply chains and project engineering capabilities. ULMA Construction occupies a position within the regional-fleet tier, representing localized production and distribution strategies across Latin American markets. These three entities illustrate how geographic origin and corporate structure map to distinct strategic postures without requiring specific operational claims.
| Leading Market Players |
|---|
| PERI GmbH |
| Doka GmbH |
| ULMA Construction |
| Alsina |
| MEVA |
| RMD Kwikform |
| Acrow |
| PASCHAL |
| NOE |
| Others |
Supply Flow & Price Mechanics
Primary aluminum feedstock from LME-registered smelters flows through Shandong and Guangdong extrusion clusters before reaching three distinct pricing tiers: German-Austrian engineering specialists bundle certified design services with panel leases, Chinese scale manufacturers compete on unbundled equipment sales, and regional rental operators price by project cycle with remanufacturing support included.
Pricing Analysis
Service bundling separates premium positioning from commodity competition. German-Austrian suppliers embed engineering certification and IoT-enabled load monitoring into long-term lease rates, while Chinese manufacturers strip out after-sales support to hit lower capital expenditure thresholds for Indian and Vietnamese residential developers. Price differentiation hinges on BIS certification tier and crane-cycle efficiency guarantees. Cost compression in the unbundled equipment tier stems from aerospace-grade alloy price volatility. Price-sensitive mid-sized contractors in Brazil and Indonesia favor single-use timber economics over reusable system investments.
Supply Chain Analysis
Aluminum alloy supply rests on Chinese primary and secondary smelting capacity concentrated in Shandong, Guangdong, and Henan provinces. Engineered timber inputs draw from Bavarian and Pacific Northwest softwood clusters, while high-tensile steel plate feeds from German and South Korean rolling mills. Single-source vulnerability runs through the Yangtze River Delta extrusion corridor where over half of aerospace-grade formwork alloy is processed. Distribution runs through specialized equipment lessors with regional remanufacturing hubs serving contractor fleets across India, the UAE, and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum extrusion capacity concentration in eastern China provinces props system pricing, with any disruption to Shandong or Guangdong output immediately transmitting to global contractor procurement costs.
For Market Incumbents: Cement captive supply relationships with secondary aluminum remelters to satisfy China's MEE dual carbon recycled-content mandates. Expand certified engineering talent pools in Bavaria and Baden-Württemberg to defend against skilled formwork designer shortages threatening complex infrastructure project execution. Prioritize backward integration into engineered timber processing to offset REACH restrictions on treated softwood imports. For New Entrants and Emerging Players: EU Green Deal embodied carbon thresholds in Germany and France open a window for cradle-to-cradle certified aluminum systems with material passports specified in Munich and Paris infrastructure tenders. Target India's PMAY-Urban mass housing procurement with lightweight modular panel offerings that compress BIS approval timelines through pre-certified design templates. Pursue lease-to-own partnerships with UK and Australian equipment financing platforms to bypass capital constraints among mid-sized contractors. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional rental fleet operators with remanufacturing capabilities in Maharashtra and Gujarat industrial corridors. Long-term viability over the coming decade depends on positioning for circular economy mandates tightening across European and Chinese public infrastructure tendering. Watch for BIS certification timeline compression in India as the signal indicating regulatory barrier shifts favoring domestic fabrication over imported systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Remelting | Closed-loop secondary aluminum supply satisfies China's MEE dual carbon procurement mandates for state projects. |
| BIM-Compatible Design Software Deployment | Just-in-time panel configuration reduces waste and accelerates approval cycles under India's tightened BIS standards. |
| Regional Rental Fleet Expansion | Maharashtra and Gujarat hubs capture India's infrastructure investment wave through lease-to-own contractor financing. |
| Cradle-to-Cradle Certification Investment | Material passports specified in German and French tender documents unlock premium positioning in EU Green Deal compliance. |
| IoT Load Monitoring Integration | Real-time sensor networks in Dubai and Singapore towers compress insurance premiums and enable taller continuous pours. |
Methodological Framework
Trade statistics from national customs authorities, construction equipment registration databases, and aluminum extrusion industry associations formed the secondary backbone. Primary interviews with formwork engineering directors, equipment procurement managers at major contractors, rental fleet operators, and BIS certification specialists validated demand assumptions. SEC filings and annual reports from listed construction equipment lessors provided financial calibration. Bottom-up project pipeline analysis across India, China, and the UAE was triangulated against top-down macro construction spend forecasts.
Historical trendline analysis of formwork system shipments and lease fleet utilization established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across material type, end-use sector, structural application, and installation method complexity. CAGRs were derived from regression analysis of construction output correlations and formwork intensity coefficients. Key forecast inputs included PMAY-Urban housing unit targets, EU Green Deal embodied carbon threshold implementation timelines, and Chinese state construction procurement volumes.
The model assumes a particular technology adoption path; alternative pathways for self-climbing IoT-integrated systems would alter the outlook if labor cost pressures in dense urban sites accelerate faster than projected. Forecasts reflect assumptions about aluminum price stabilization and BIS certification process efficiency. Supply concentration risk in Shandong and Guangdong provinces, REACH framework amendment scope, and India's infrastructure execution rate constitute a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Global Screw Piles Market